
 Vegan Sauces, Dressings and Spreads Market | 2026-2036
Vegan Sauces, Dressings and Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Sauces, Dressings and Spreads Market Intelligence
Stricter allergen labeling mandates from regulators like the US FDA and Europe's EFSA is expanding the compliance burden for new market entrants. This regulatory pressure favors established players with sophisticated quality control and sourcing protocols. Primal Kitchen leverages its brand strength in the paleo and keto-aligned consumer space. Daiya Foods Inc. specializes in dairy-free formulations, particularly cheese-alternative bases for sauces, while B&G Foods Inc. operates a diversified portfolio that integrates vegan options within its broader condiment lines.
Vegan sauces, dressings, and spreads are food condiments formulated entirely from plant-based ingredients, excluding all animal products. Their stability and texture often rely on plant-derived emulsifiers, such as soy lecithin, and hydrocolloid thickeners like xanthan gum to mimic the mouthfeel of traditional dairy or egg-based counterparts. Nut-based and seed-based formulations command a premium due to perceived health benefits and higher input costs. Within product types, cooking sauces and spreads are showing significant development, moving beyond simple salad dressings to more complex culinary applications.
Global food safety is governed by frameworks like ISO 22000 and guidelines from the WHO, which influence manufacturing practices. In China, compliance with national GB standards for food additives and labeling is mandatory for market access, shaping product formulation for both domestic and foreign brands. Success for manufacturers now depends on navigating the patchwork of international clean-label standards while managing volatile plant-based ingredient supply chains.
Market Dynamics
The central dynamic shaping the market is the convergence of stringent food allergen labeling mandates with heightened consumer demand for clean-label products. This pressure forces manufacturers to innovate formulations that exclude common allergens while simultaneously meeting expectations for taste, texture, and minimal processing.
Growth Catalysts
- Food Service Expansion:The integration of dedicated plant-based menus within major restaurant chains and food service operators creates a substantial and consistent B2B demand channel for vegan sauces and dressings, particularly in North America and Western Europe.
- Regulatory Harmonization:Stricter food labeling laws, such as those enforced by the European Food Safety Authority (EFSA) concerning allergens, compel product reformulation, which in turn expands the market for compliant, transparently labeled vegan alternatives.
- Health-Driven Consumerism:A pronounced shift towards health and wellness, especially in developed markets like Germany and the United States, is boosting sales of premium products formulated with nutrient-dense ingredients like nuts, seeds, and avocados.
Market Restraints
- Ingredient Price Volatility:The market is exposed to significant price fluctuations for key inputs like cashews, almonds, and avocados, which are susceptible to climate-related supply shocks, impacting production costs and final retail prices.
- Technical Formulation Hurdles:Replicating the sensory properties of traditional dairy and egg-based condiments without using artificial additives or common allergens presents a significant technical challenge, requiring advanced and costly plant-based emulsifiers and thickeners.
- Supply Chain Concentration:A dependency on a limited number of agricultural regions for certified non-GMO soy and other key plant-based commodities creates potential bottlenecks and sourcing vulnerabilities for manufacturers.
Strategic Opportunities
- Ethnic and Culinary Sauces:There is a significant opportunity to develop complex, ready-to-use vegan cooking sauces for specific global cuisines, such as Indian curries or Mexican moles, moving beyond basic dressings and spreads.
- Clean-Label Fermentation:Applying fermentation technologies to plant-based ingredients can create novel, umami-rich flavor profiles and enhance nutritional content in spreads and sauces, appealing to health-conscious consumers seeking minimally processed foods.
- Untapped Geographic Markets:Markets in certain Asia-Pacific countries show strong potential, where rising disposable incomes and a growing interest in plant-based diets have yet to be met with a wide variety of specialized vegan condiment options.
Industry Challenges
- Navigating "Clean Label" Definitions:Manufacturers face the operational challenge of aligning product formulations with the varied and often ambiguous "clean label" standards that differ between retailers and regulatory bodies across the US and EU.
- Maintaining Ingredient Integrity:Ensuring consistent quality, traceability, and allergen-free status for a global supply chain of plant-based ingredients requires sophisticated and costly quality control and supplier verification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Sauces, Dressings and Spreads Market |
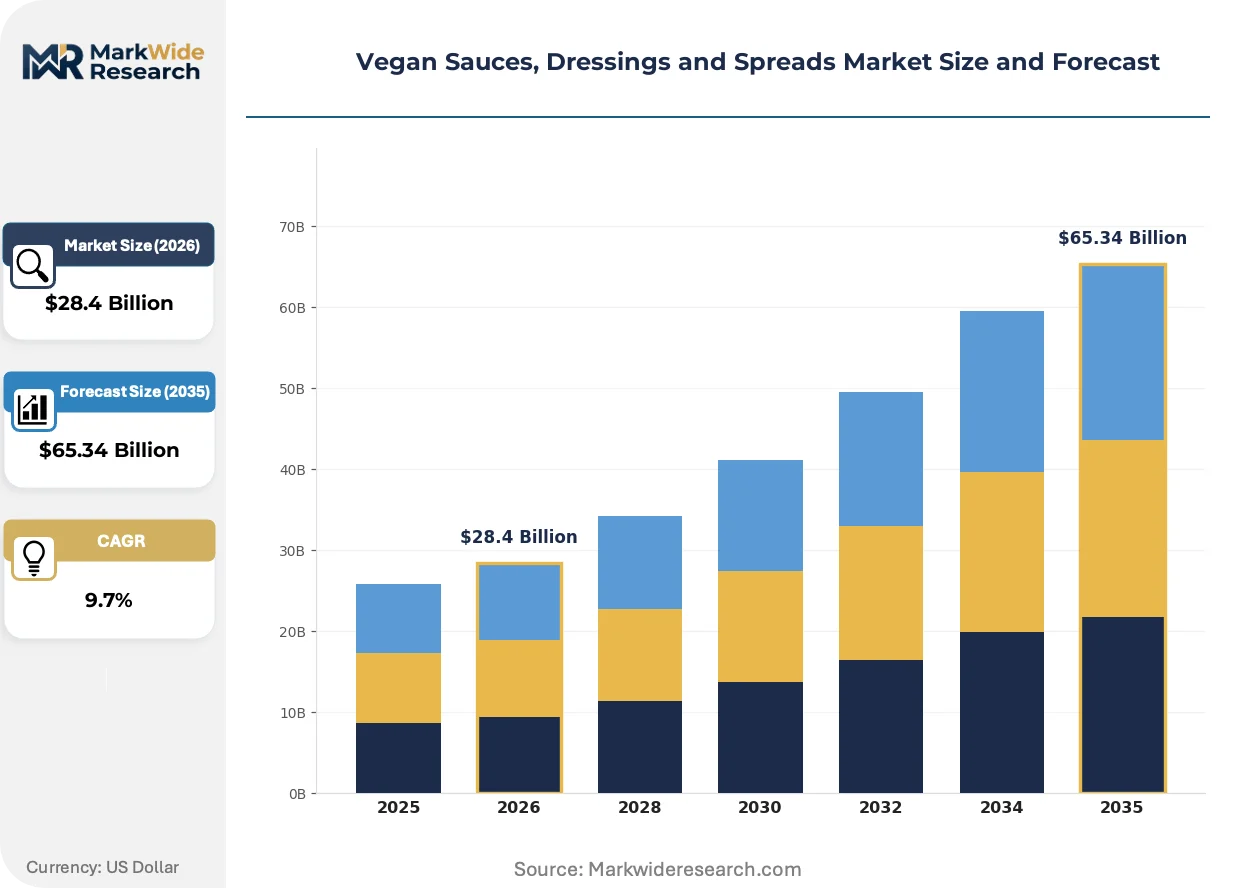
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $65.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salad Dressings, Cooking Sauces, Spreads, Dips Ingredient Base: Nut-Based, Soy-Based, Seed-Based, Vegetable-Based Flavor Profile: Spicy, Sweet, Savory, Tangy Packaging Type: Bottles, Jars, Pouches, Sachets |
| Companies Covered | Amy's Kitchen Inc., Litehouse Inc., Follow Your Heart, Primal Kitchen, Sir Kensington's, Daiya Foods Inc., B&G Foods Inc., Organicville, Meridian Foods Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Sauces, Dressings and Spreads Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards functional and nutritionally enhanced formulations that transcend simple animal-product substitution. Food science innovations are meeting consumer demands for products that are not only vegan but also cleaner, fresher, and more flavorful, altering production methods and brand positioning.
High-Pressure Processing (HPP) is a non-thermal pasteurization technique used to extend shelf life while preserving the nutritional and sensory qualities of fresh ingredients. Premium brands targeting the health-conscious consumer are increasingly adopting HPP for refrigerated dressings and spreads. This technology is absorbing the role of chemical preservatives and thermal pasteurization, enabling a distinct category of high-value, clean-label condiments with a "fresh-made" appeal.
In China, adherence to national GB standards for food additives and labeling is mandatory for market access. These stringent regulations directly influence product development, often requiring manufacturers to use a specific, pre-approved list of plant-based thickeners, stabilizers, and natural colorants. Cooking sauces and complex spreads are the product categories most impacted, as their formulations must be meticulously revised to achieve compliance before entering the Chinese market.
A notable behavioral shift is occurring as consumers increasingly purchase specialty vegan condiments via direct-to-consumer (DTC) websites and curated food subscription boxes. This movement disrupts the traditional dominance of large grocery retail channels, creating space for artisanal and niche brands to build a loyal customer base directly. The trend is particularly visible in the United States and the UK, where online platforms facilitate greater product discovery and brand storytelling.
Vegan Sauces, Dressings and Spreads Market Segmentation
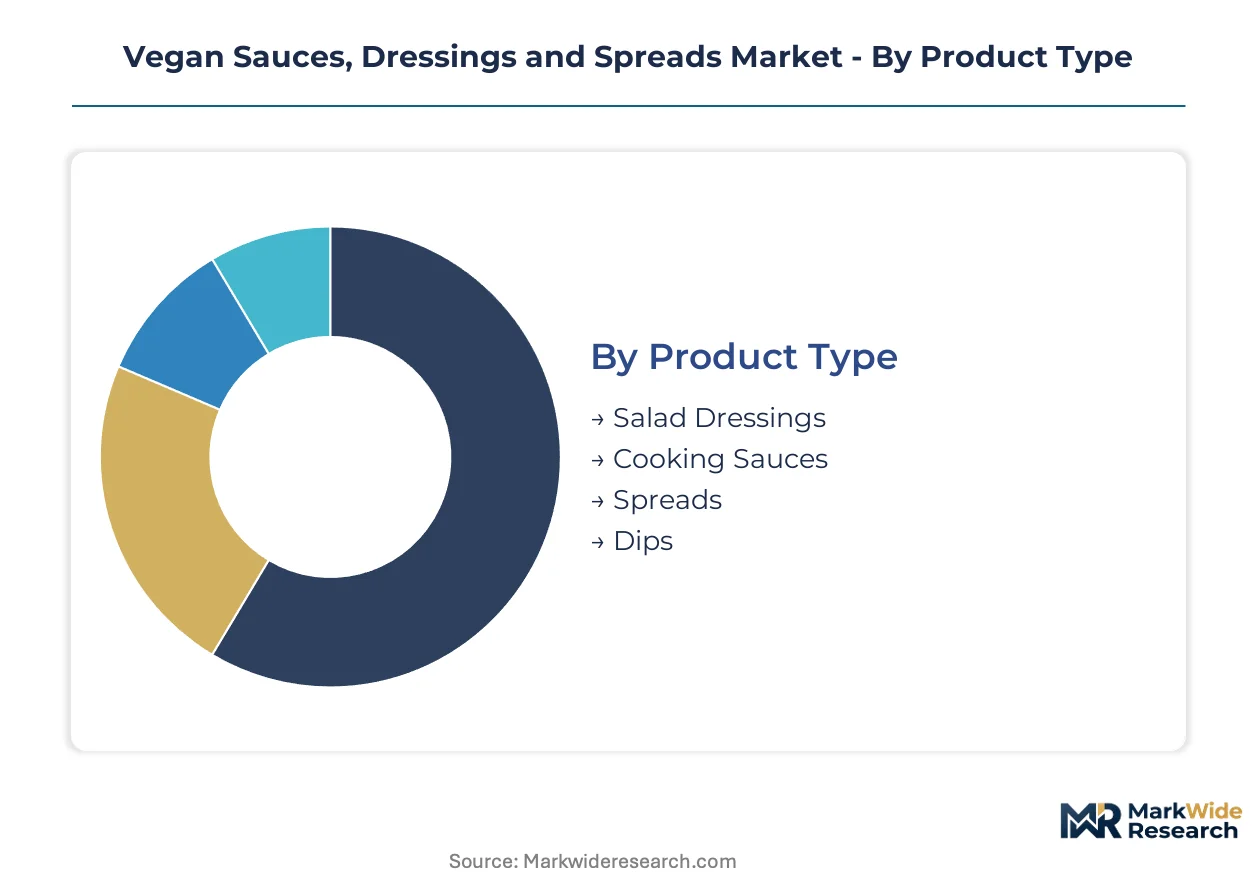
Understanding the Vegan Sauces, Dressings and Spreads Market through segmentation reveals critical insights into product development and consumer preferences. This detailed breakdown allows manufacturers to align their offerings with specific demand pockets. Pinpointing growth areas across diverse product types and ingredient bases informs targeted market strategies.
Product Type:
The product type segmentation highlights the balance between highly customized culinary solutions and more standardized everyday condiments. Manufacturers navigate consumer expectations for both bespoke flavor profiles and convenient, broadly appealing options.
- Cooking Sauces:These complex formulations are designed for specific culinary applications, often requiring a delicate balance of plant-based emulsifiers and thickeners to achieve desired textures. Demand is concentrating in the food service industry, where restaurants seek versatile vegan bases for their expanding plant-based menus.
- Spreads:Vegan spreads offer versatile applications, from sandwiches to dips, and often incorporate nut or seed bases for enhanced texture and nutritional value. Health-conscious consumers in Germany and the United States drive demand for these nutrient-dense options.
- Salad Dressings:These liquid condiments primarily enhance salads, often relying on oil and vinegar bases with plant-derived emulsifiers for stability.
- Dips:Thicker than dressings, vegan dips serve as accompaniments for snacks and meals, frequently using vegetable or legume bases for creamy consistency.
Leading the category by volume: Salad Dressings. Growing fastest: Cooking Sauces.
Ingredient Base:
This category reflects the cost structures and perceived health benefits associated with different plant-derived components. Ingredient choices directly influence both the final product's pricing tier and its appeal to specific dietary niches.
- Nut-Based:Formulations using ingredients like cashews or almonds provide rich, creamy textures and are often positioned as premium products due to higher input costs and perceived health benefits. Demand for these high-value options is strong in developed markets like the United States.
- Soy-Based:These products leverage the emulsifying and protein-rich properties of soy, offering a cost-effective and widely available base for various vegan condiments. Their stability and versatility make them a staple in many mass-market formulations.
- Seed-Based:Utilizing seeds such as sunflower or pumpkin, these bases cater to allergen-sensitive consumers while offering distinct flavor profiles.
- Vegetable-Based:Ingredients like cauliflower or sweet potato form the base for these options, providing natural colors and nutritional value, often targeting clean-label preferences.
Ingredient selection significantly impacts product texture and stability, necessitating advanced formulation expertise for dairy-free alternatives.
Flavor Profile:
Flavor profiles dictate consumer acceptance and cultural relevance, with manufacturers tailoring offerings to regional palates and culinary traditions. This segmentation highlights the diverse taste experiences sought by vegan consumers globally.
- Savory:Encompassing umami-rich and herbaceous notes, savory vegan condiments appeal to a broad consumer base, often mimicking traditional meat or cheese-based flavors. These profiles are foundational for many cooking sauces and spreads, especially in Western Europe.
- Spicy:Products with a spicy flavor profile cater to consumers seeking bolder taste experiences, often incorporating chili, pepper, or other heat-inducing ingredients. Emerging markets in Asia-Pacific show a rising interest in these dynamic options.
- Sweet:Sweet vegan sauces and spreads often incorporate fruit purees or natural sweeteners, primarily used in dessert applications or as breakfast accompaniments.
- Tangy:Characterized by acidic notes from ingredients like vinegar or citrus, tangy condiments provide brightness and cut through richness, popular in salad dressings.
Regional culinary traditions heavily influence the prevalence of specific flavor profiles, driving localized product development efforts.
Packaging Type:
Packaging choices reflect convenience, shelf-life requirements, and brand positioning. The format directly impacts consumer interaction, distribution logistics, and the product's environmental footprint.
- Bottles:Glass or plastic bottles are common for liquid products like dressings and larger volume sauces, offering good visual appeal and resealability for multi-use applications. This format dominates the retail grocery channel for established brands.
- Pouches:Flexible pouches offer convenience, reduced material usage, and often extended shelf life for single-serve or squeeze applications, appealing to on-the-go consumers. This type is gaining traction for innovative and fresh-made refrigerated products.
- Jars:Typically glass, jars are favored for spreads and thicker sauces, providing a premium feel and excellent product visibility.
- Sachets:Small, single-serving sachets are designed for portion control and convenience, widely used in food service and for sampling new products.
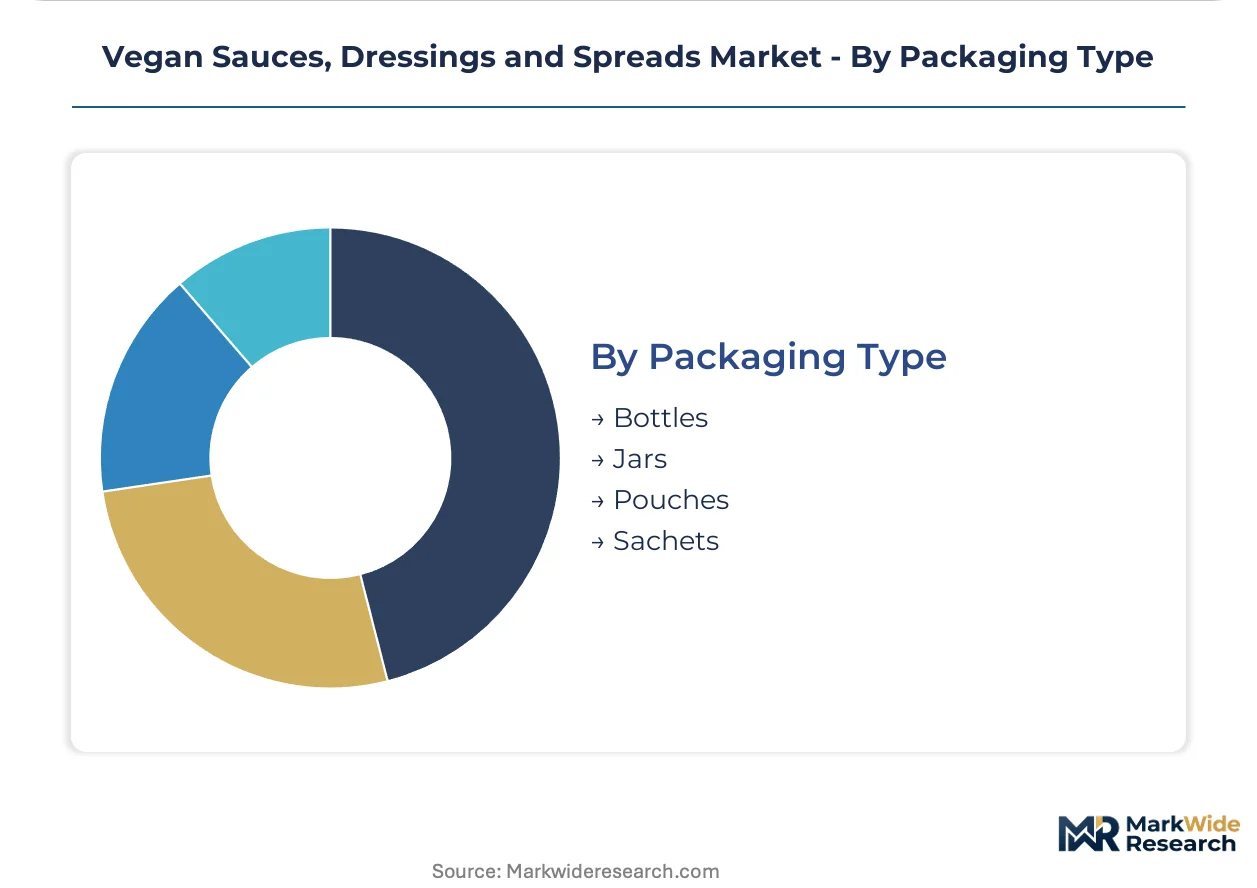
Packaging innovation focuses on sustainability and consumer convenience, with flexible formats experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' Food Valley innovation cluster, acting as a de facto special economic zone for agri-food technologies, drives significant concentration in vegan food development. This strategic focus fosters collaboration between research institutions and industry players. Such regional initiatives accelerate product innovation and market entry for specialized vegan condiments.
United States
Health-driven consumerism and the rapid expansion of plant-based menus in food service drive demand across the United States. The Food and Drug Administration (FDA) mandates stringent allergen labeling, compelling manufacturers to reformulate products for clarity. California's robust food tech hubs, particularly around San Francisco, lead in developing novel plant-based ingredient solutions.
Germany
German consumers exhibit high health consciousness and a strong preference for clean-label products, boosting sales of premium vegan spreads. The European Food Safety Authority (EFSA) enforces strict food safety and allergen regulations, influencing product development for market access. Berlin's vibrant plant-based startup ecosystem fosters innovation in unique flavor profiles and ingredient bases.
China
Rising disposable incomes and a growing interest in diverse culinary experiences fuel demand for vegan cooking sauces in China. Compliance with national GB standards for food additives and labeling is mandatory, shaping product formulation for both domestic and foreign brands. Shanghai's advanced food processing zones are becoming crucial for scaling compliant vegan food production.
United Kingdom
A pronounced shift towards plant-based diets and the growth of direct-to-consumer channels characterize the UK market. The Food Standards Agency (FSA) provides guidelines for food labeling and safety, influencing manufacturers' transparency efforts. London's dynamic specialty food scene fosters the development and distribution of artisanal vegan condiments.
Vegan Sauces, Dressings and Spreads Market Key Industry Players
North American producers anchor one tier of the vegan sauces, dressings, and spreads market; European specialists hold another. The market structure exhibits a blend of established food conglomerates diversifying their portfolios and agile niche players focusing on specific dietary trends. Strategic partnerships between ingredient suppliers and finished product manufacturers are common, alongside portfolio diversification to capture broader consumer segments.
Specialists in plant-based innovation, like Daiya Foods Inc., anchor one segment of the market, focusing on dairy-free formulations. Primal Kitchen exemplifies a brand leveraging strong alignment with specific dietary niches such as paleo and keto. B&G Foods Inc. maintains a diversified portfolio, integrating vegan options within its broader condiment lines to cater to evolving consumer preferences.
| Leading Market Players |
|---|
| Amy's Kitchen Inc. |
| Litehouse Inc. |
| Follow Your Heart |
| Primal Kitchen |
| Sir Kensington's |
| Daiya Foods Inc. |
| B&G Foods Inc. |
| Organicville |
| Meridian Foods Limited |
| Others |
Cost & Logistics Intelligence
Demand for clean-label products across the EU and US forces manufacturers to source certified plant-based ingredients. This pressure drives up input costs, directly influencing final product pricing and requiring robust supply chain verification.
Pricing Analysis
Premium pricing applies to short lead-time orders for specialized vegan emulsifiers and thickeners, reflecting rapid formulation needs. The market primarily operates on a contract-based long-term offtake model for key plant-based commodities. Price differentiation stems from ingredient certification levels, such as non-GMO or organic, and customization for food service clients. Pricing softness reflects intense competition in the mass-market salad dressing segment, making budget-conscious buyers highly price sensitive, unlike health-conscious consumers of premium nut-based spreads.
Supply Chain Analysis
National GB standards in China, mandating specific food additives and labeling, reshape sourcing for market access. The supply chain for vegan sauces and dressings concentrates in agricultural regions like the US for soy and Southeast Asia for cashews, alongside specialized ingredient manufacturers in Europe. Key dependencies include plant-based emulsifiers, hydrocolloid thickeners, and certified non-GMO soy. Commodity price volatility for inputs like cashews and avocados presents a significant structural risk; distribution runs through a dual model of large grocery retail channels and the expanding food service industry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan sauces, dressings, and spreads market is increasingly becoming a vertical-integration race. Manufacturers are pursuing upstream control over key plant-based ingredient sourcing to manage quality and cost volatility.
For Market Incumbents: To counter the margin pressure from volatile ingredient prices, established players should deepen backward integration into plant-based commodity processing. Portfolio diversification through the acquisition of niche brands focusing on specific dietary trends, like paleo or keto, also strengthens market presence. Investing in advanced HPP technology extends shelf life and preserves sensory qualities, differentiating premium refrigerated products. Strategic partnerships with food service operators secure consistent B2B demand channels. For New Entrants and Emerging Players: Direct-to-consumer (DTC) websites offer a primary route for niche brands to build loyal customer bases and gather direct feedback. Artisanal brands can target the underpenetrated market for complex, ready-to-use vegan cooking sauces in Asian-Pacific countries. Focusing on clean-label fermentation technologies provides novel, umami-rich flavor profiles for premium spreads. A strong brand storytelling approach highlighting ingredient provenance and functional benefits serves as a compelling go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with established clean-label supply chains. Long-term viability over the next decade hinges on intellectual property in plant-based formulation science and efficient ingredient sourcing. Acquisition targets should include companies with strong regional distribution networks and proprietary fermentation capabilities. A key signal to watch is the sustained growth of dedicated plant-based menus within major food service chains, indicating scalable B2B demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nut Processing | Secures consistent supply of premium nut-based ingredients, mitigating price volatility for high-value spreads. |
| Investment in HPP Technology | Extends shelf life for fresh-made refrigerated dressings, appealing to health-conscious consumers in the US. |
| Targeted Acquisition of Fermentation Startups | Integrates novel flavor profiles and enhanced nutritional content, differentiating products from traditional offerings. |
| Expansion of Food Service Partnerships | Establishes stable B2B demand channels, supporting growth of cooking sauces in Western Europe. |
| Compliance with China's GB Standards | Unlocks market access for complex cooking sauces, capitalizing on rising disposable incomes in Shanghai. |
Research Approach
WHO guidelines, ISO 22000 standards, and national GB standards in China formed the secondary backbone for this analysis, complemented by regulatory frameworks from the US FDA and Europe's EFSA. Industry insights were gathered through primary interviews with food scientists, procurement leads at major food service chains, and brand managers at vegan condiment companies. This approach integrated bottom-up market sizing with top-down validation, ensuring data robustness.
A bottom-up analytical lens projected market values across the analysis window, validated by top-down industry trends. Segmentation dimensions modeled included product type, ingredient base, flavor profile, and packaging type, alongside regional market dynamics. Compound annual growth rates were derived from historical data and projected consumer adoption patterns. Key forecast inputs included plant-based ingredient price trends and food service expansion rates.
Inputs from public financial reports and regulatory databases were available through the study window; gaps in real-time supply chain cost data introduce uncertainty bands. Forecasts reflect assumptions on consumer behavior and regulatory shifts, with volatile ingredient pricing posing a key risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Soups and Sauces Market