
 Cayenne Pepper Market | 2026-2036
Cayenne Pepper Market Size, Share, and Industry Trends Forecast 2026-2036
Cayenne Pepper Market Outlook
Agricultural labor availability across major Capsicum annuum growing belts is reorganizing harvest logistics and mechanization timelines. McCormick & Company leverages its vertically integrated procurement network to secure consistent high-Scoville cultivars from contracted farms in multiple hemispheres. Everest Food Products anchors its position through deep backward integration into Indian spice-growing cooperatives, while Kerry Group competes via specialized extraction capabilities serving pharmaceutical and nutraceutical formulators.
Cayenne pepper comprises dried, ground fruit of Capsicum annuum cultivars typically measuring 30,000 to 50,000 Scoville Heat Units, with capsaicinoid content extracted via solvent or supercritical CO2 methods for industrial applications. Powder dominates food industry procurement due to its blending versatility in sauces, seasonings, and processed meats, though oil and extract segments command premium pricing from pharmaceutical buyers seeking standardized capsaicin concentrations for topical analgesic formulations. Organic grade supply trails conventional volumes but captures disproportionate margin pools as European and North American clean-label commitments harden sourcing specifications.
The FDA's Food Safety Modernization Act preventive controls and the EPA's pesticide tolerance schedules govern US-bound shipments, while India's FSSAI enforces mandatory spice testing for domestic and export lots. The EU's REACH framework and EFSA novel food assessments constrain extract introductions, pushing suppliers toward pre-certified compliance dossiers. Stakeholders must monitor evolving residue limits and organic equivalence agreements to avoid border detention and maintain contract renewals with institutional buyers.
Market Dynamics
Certified organic procurement specifications from North American and European specialty food manufacturers are restructuring cultivation priorities across traditional Capsicum annuum growing belts, forcing extractors and grinding houses to requalify supplier bases.
Growth Catalysts
- Clean-label hot sauce formulation:Specialty food manufacturers in the United States are mandating certified organic cayenne for premium sauce lines, pulling premium-grade pod volumes from India's Guntur district and Mexico's Yucatán Peninsula.
- FSSAI-mandated spice purity standards:India's tightened domestic testing requirements are elevating quality baselines for export lots, creating compliance-ready supply pools for EU and US-bound shipments.
- Supercritical CO2 extraction:Pharmaceutical and nutraceutical formulators are adopting solvent-free capsaicinoid recovery methods, opening premium pricing tiers for standardized extract grades.
Market Restraints
- Aflatoxin residue limits:The EU's tightened maximum residue thresholds are rejecting conventional shipments at elevated rates, compressing accessible export volumes for non-certified cultivators.
- Agricultural labor availability:Harvest logistics across Indian and Mexican growing belts face seasonal workforce gaps, delaying mechanization timelines and elevating per-unit labor costs.
- Synthetic capsaicin competition:Laboratory-produced capsaicin substitutes are capturing industrial flavoring applications, narrowing addressable demand for botanical extracts in non-pharmaceutical segments.
Strategic Opportunities
- Functional seasoning blends:European clean-label commitments are hardening sourcing specifications, creating first-mover advantages for suppliers with pre-certified organic equivalence dossiers.
- Topical analgesic formulations:Standardized capsaicin concentrations for pain management applications command pharmaceutical-grade premiums, expanding addressable value pools beyond food industry procurement.
- Direct-to-grinder procurement models:Eliminating intermediary aggregators in Indian spice-growing cooperatives is capturing margin previously distributed across fragmented trader networks.
Industry Challenges
- Organic certification timelines:Three-year conversion periods for conventional farmland are constraining near-term supply expansion, locking contract renewals to existing certified acreage.
- Multi-jurisdiction compliance synchronization:Reconciling FDA preventive controls, EPA pesticide tolerances, and REACH framework dossiers is extending product registration cycles for extract introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cayenne Pepper Market |
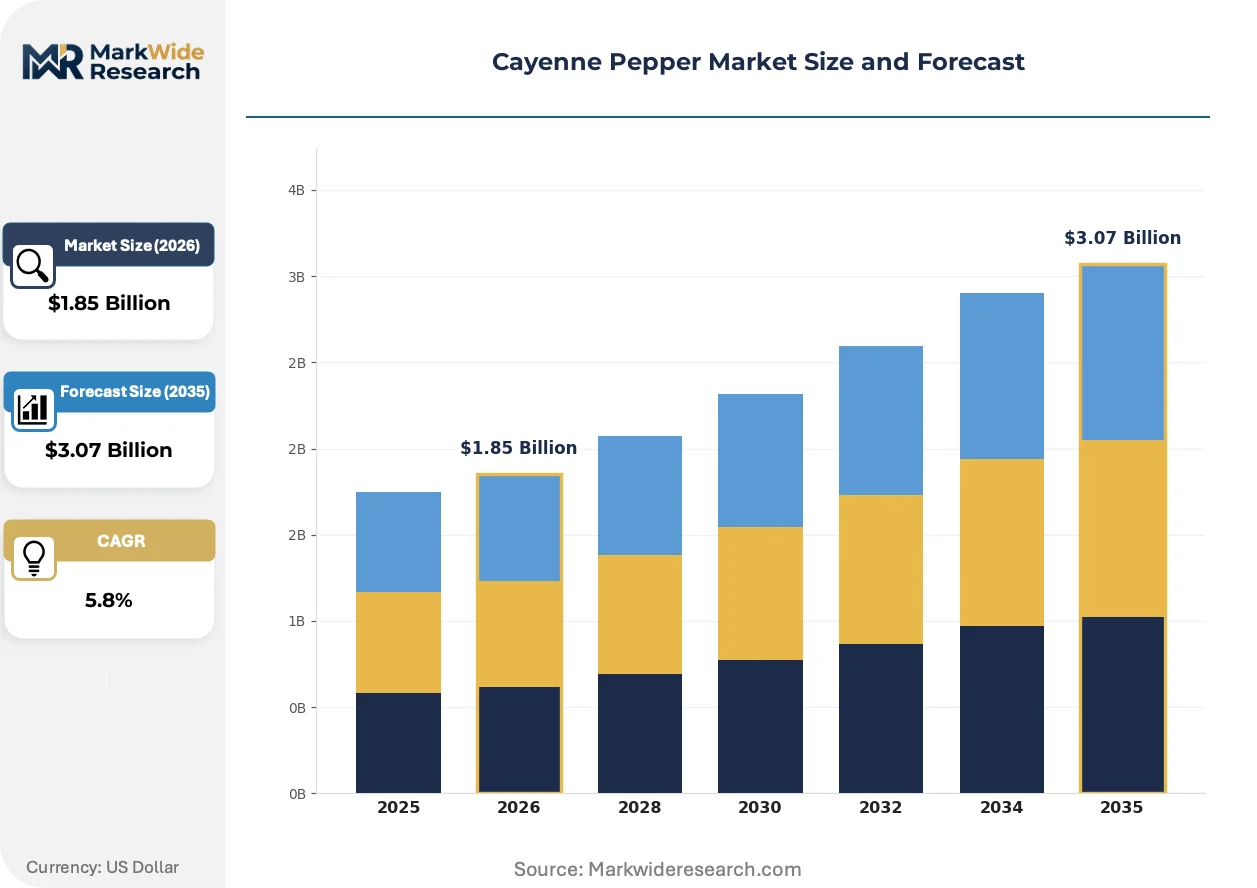
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flakes, Oil, Extract End Use: Food Industry, Pharmaceuticals, Cosmetics, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Grade: Organic, Conventional, Non-GMO, Others |
| Companies Covered | Badia Spices, Mahashian Di Hatti, McCormick & Company, Euroma Group, Shan Foods, Olam International, Everest Food Products, Kerry Group, Frontier Natural Products Co-op, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cayenne Pepper Market Strategic Shifts
Processing technology and procurement specification evolution are compressing traditional supply chain tiers while regulatory fragmentation across major import jurisdictions is elevating compliance infrastructure investments.
Supercritical CO2 extraction systems are displacing solvent-based methods in pharmaceutical-grade capsaicinoid recovery. Nutraceutical formulators in Germany and Switzerland are adopting these systems at accelerated replacement cycles. This displacement is compressing the supplier base toward capital-intensive extraction houses capable of documenting batch-level purity certifications.
REACH framework pre-registration requirements are constraining novel extract introductions into European pharmaceutical channels. Industrial consequence includes mandatory safety dossier compilation before market entry. Standardized capsaicin oil segments face extended assessment timelines, pushing suppliers toward EFSA-reviewed legacy formulations.
Buyer consolidation among North American seasoning blend manufacturers is shortening supplier qualification cycles while elevating volume minimums. Mid-tier grinding houses are losing contract access to vertically integrated procurement networks. This concentration is most visible in US-bound organic cayenne powder procurement, where three specialty food manufacturers now anchor annual contracting.
Cayenne Pepper Market Segmentation
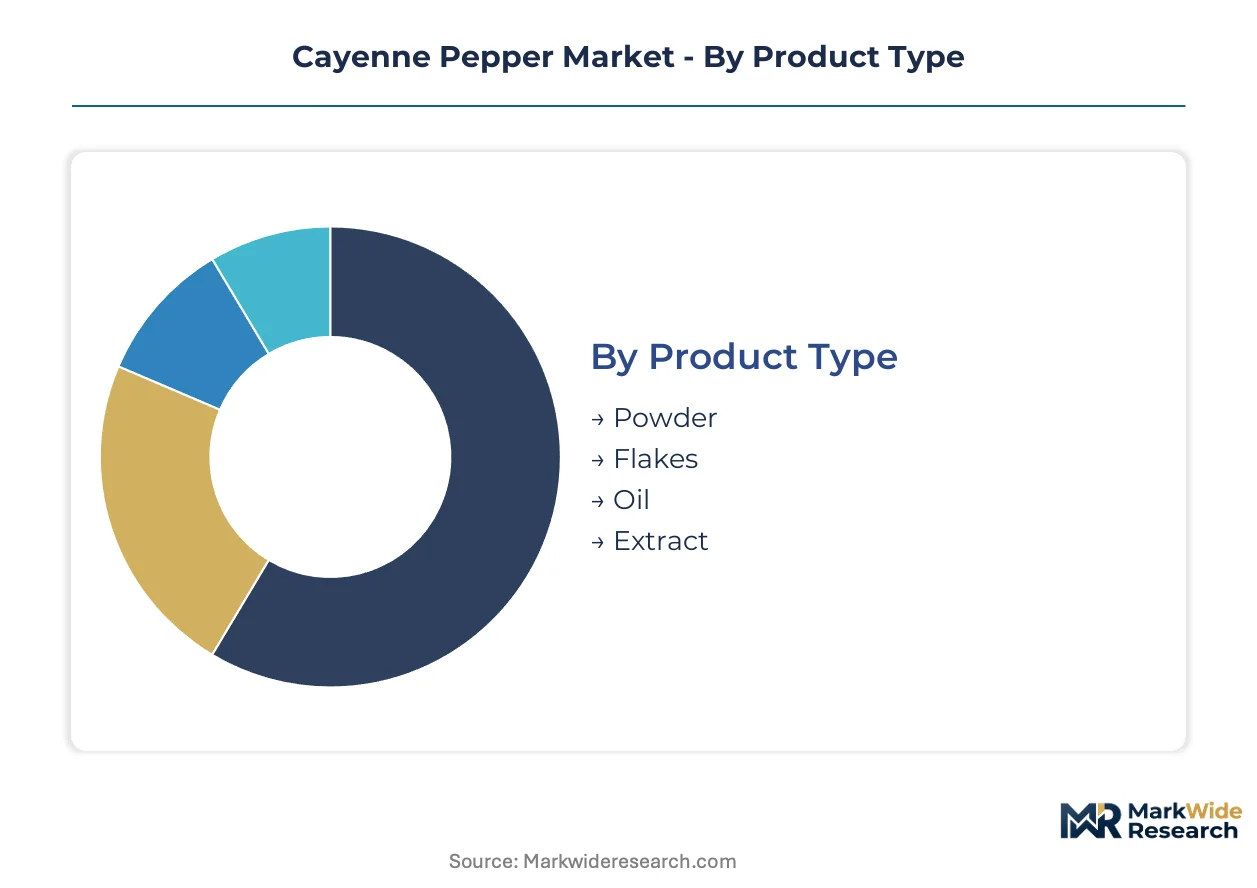
Segmentation in the cayenne pepper market reveals distinct procurement pathways and margin structures. Product form determines extraction investment and end-use access, while grade certification gates entry into premium channels.
Product Type:
Powder and extract segments flow through divergent channel architectures, with powder dominating food manufacturing procurement and extract commanding pharmaceutical direct sales.
- Powder:Finely ground dried fruit of Capsicum annuum cultivars, typically standardized to 30,000-50,000 Scoville Heat Units. Food manufacturers in the United States blend powder into hot sauces, seasoning mixes, and processed meat formulations, with clean-label commitments pulling organic-certified volumes toward premium contract tiers.
- Extract:Concentrated capsaicinoid products recovered via solvent or supercritical CO2 methods, yielding standardized potency for pharmaceutical applications. German and Swiss nutraceutical formulators specify solvent-free extraction methods, creating premium pricing tiers unavailable to solvent-based suppliers.
- Flakes:Coarsely crushed dried pods retaining visual identity for culinary applications. Specialty food manufacturers use flakes for texture differentiation in premium sauce lines.
- Oil:Oleoresin suspensions delivering heat without particulate matter. Industrial flavor houses specify oil for beverage and confectionery applications requiring clear dissolution.
Powder dominates installed base. Extract is where expansion concentrates.
End Use:
Application-specific purity requirements segment suppliers by certification depth and documentation capability.
- Food Industry:Sauce manufacturers, seasoning blenders, and processed meat processors constitute the volume anchor. McCormick & Company and Everest Food Products anchor procurement through backward integration into growing cooperatives.
- Pharmaceuticals:Topical analgesic formulators demand batch-level capsaicin standardization and REACH dossier compliance for European market access.
- Nutraceuticals:Capsaicinoid supplements targeting metabolic support and pain management. Supercritical CO2 extraction methods are climbing fastest in this segment.
- Cosmetics:Warming agents and circulation-stimulating additives in topical preparations. Formulators prioritize certified organic grades for clean beauty positioning.
Food Industry commands volume leadership. Pharmaceuticals is where margin expansion concentrates.
Distribution Channel:
Channel selection determines supplier qualification intensity and working capital requirements.
- Wholesalers:Aggregators in Indian spice-growing cooperatives and Mexican cultivation belts consolidate smallholder output for grinding houses. Direct-to-grinder procurement models are compressing traditional wholesaler margins.
- Supermarkets:Mass retail private-label seasoning programs demand volume consistency and multi-jurisdiction compliance documentation.
- Specialty Stores:Premium organic and single-origin positioning for culinary enthusiasts. European clean-label commitments harden sourcing specifications in this channel.
- Online Retail:Direct-to-consumer organic powder and specialty extract sales. Buyer consolidation among North American seasoning blend manufacturers is shortening supplier qualification cycles in adjacent digital channels.
Wholesalers retain volume throughput. Specialty Stores is where pricing power concentrates.
Grade:
Certification tier determines market access and contract renewal probability across import jurisdictions.
- Organic:Certified cultivation excluding synthetic pesticides and fertilizers, with three-year conversion timelines constraining near-term supply expansion. EU and US organic equivalence agreements govern cross-border shipment eligibility.
- Conventional:Standard agricultural practices with FSSAI-mandated purity testing for Indian export lots. The EU's tightened aflatoxin residue limits are rejecting conventional shipments at elevated rates.
- Non-GMO:Identity-preserved supply chains documenting absence of genetically modified cultivars. North American specialty food manufacturers specify Non-GMO for premium positioning.
- Others:Includes fair-trade and geographic indication grades capturing niche premium pools.
Conventional dominates planted acreage. Organic is where contract renewal security concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize certified organic grades for clean-label formulations, while European procurement emphasizes REACH dossier compliance for pharmaceutical extracts. Indian and Mexican supply clusters dominate raw material flows but serve fundamentally different end-use specifications.
United States
Specialty food manufacturers in the United States anchor organic cayenne procurement for premium hot sauce lines. The FDA's Food Safety Modernization Act preventive controls govern import inspections and facility registrations. McCormick & Company maintains vertically integrated sourcing networks across multiple hemispheres to secure consistent high-Scoville cultivars.
India
Indian extractors and grinding houses supply premium-grade pods from Guntur district cultivation clusters to international buyers. The FSSAI enforces mandatory spice purity testing for domestic and export lots, elevating quality baselines for EU and US-bound shipments. Everest Food Products anchors market position through backward integration into spice-growing cooperatives.
Germany
German nutraceutical formulators drive demand for supercritical CO2 extraction methods in capsaicinoid recovery. The REACH framework and EFSA novel food assessments constrain extract introductions, pushing suppliers toward pre-certified compliance dossiers. Swiss and German buyers command premium pricing tiers unavailable to solvent-based suppliers.
Mexico
Mexico's Yucatán Peninsula supplies traditional cultivation clusters with heritage cultivars sought by international extractors. Agricultural labor availability constraints delay mechanization timelines and elevate per-unit harvest costs. Regional growers face competitive pressure from Indian supply bases on conventional grade exports.
Switzerland
Swiss pharmaceutical and nutraceutical formulators specify solvent-free extraction methods for standardized capsaicin concentrations. Swissmedic and EFSA regulatory alignment requires batch-level purity certifications for topical analgesic applications. Kerry Group competes through specialized extraction capabilities serving these precision buyers.
Cayenne Pepper Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with consolidation most visible in North American organic procurement. Three specialty food manufacturers now anchor annual contracting for US-bound powder volumes, compressing access for mid-tier grinding houses. The competitive landscape organizes around vertically integrated procurement networks, specialized extraction capabilities, and direct-to-grinder procurement models eliminating intermediary margins. Dominant competitive moves include backward integration into growing cooperatives and capacity expansion in supercritical CO2 extraction infrastructure.
Among North American seasoning blenders, McCormick & Company exemplifies the integrated procurement archetype through multi-hemisphere sourcing networks. Kerry Group occupies a position within the specialized extraction tier, serving pharmaceutical and nutraceutical formulators with documented purity certifications. Everest Food Products represents the cooperative-integrated model, anchoring supply security through upstream control over Indian spice-growing operations.
| Leading Market Players |
|---|
| Badia Spices |
| Mahashian Di Hatti |
| McCormick & Company |
| Euroma Group |
| Shan Foods |
| Olam International |
| Everest Food Products |
| Kerry Group |
| Frontier Natural Products Co-op |
| Others |
Value Chain & Pricing Dynamics
EU REACH framework dossier requirements gate both supply qualification and price differentiation simultaneously, compressing accessible supplier pools toward capital-intensive extraction houses capable of documenting batch-level purity certifications while commanding pharmaceutical-grade premiums unavailable to conventional processors.
Pricing Analysis
Long-term offtake contracts anchor procurement for North American seasoning blend manufacturers seeking volume consistency, while spot purchases persist for smaller grinding houses facing irregular demand. Price differentiation rests on organic certification tier and supercritical CO2 extraction capability, with solvent-free methods capturing premium tiers from German and Swiss nutraceutical formulators. Cost compression in conventional grade shipments is intensifying because EU aflatoxin residue limits are rejecting non-certified lots at elevated rates. Food industry buyers exhibit highest price sensitivity due to commoditized powder segments, while pharmaceutical formulators show lowest sensitivity given standardized capsaicin concentration requirements.
Supply Chain Analysis
India and Mexico anchor raw material flows from Guntur district and Yucatán Peninsula cultivation clusters, with Germany and Switzerland hosting specialized extraction infrastructure for pharmaceutical-grade processing. Raw material dependencies center on Capsicum annuum cultivar availability, agricultural labor pools, and organic certification conversion timelines. Single-source vulnerability concentrates in Indian spice-growing cooperatives where fragmented smallholder structures create consolidation bottlenecks. Distribution runs through vertically integrated procurement networks eliminating traditional wholesaler margins, with direct-to-grinder models capturing value previously distributed across intermediary aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is disrupting traditional solvent-based processing, creating first-mover advantages for suppliers investing in pharmaceutical-grade certification infrastructure.
For Market Incumbents: Compound backward integration into Indian and Mexican growing cooperatives to secure captive supply of high-Scoville cultivars before organic certification timelines constrain expansion. Expand supercritical CO2 extraction capacity in Germany or Switzerland to serve REACH-compliant pharmaceutical channels, defending against synthetic capsaicin substitution in industrial flavoring applications. For New Entrants and Emerging Players: Anchor in European clean-label specialty stores where sourcing specification hardening creates entry gaps for pre-certified organic equivalence dossiers. Target direct-to-consumer online retail for premium organic powder and single-origin flake positioning, leveraging shortened supplier qualification cycles in adjacent digital channels to bypass entrenched wholesaler networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure as pharmaceutical buyers consolidate toward documented purity certification suppliers. Acquisition targets should emphasize extraction houses with existing REACH dossiers and multi-hemisphere raw material sourcing networks. The signal to watch is EU aflatoxin enforcement intensity, which would accelerate conventional supplier displacement and premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Pharmaceutical-grade extraction methods command premium pricing tiers from German nutraceutical formulators. |
| Organic Certification Investment | Three-year farmland conversion timelines lock contract renewals to existing certified acreage pools. |
| Direct-to-Grinder Procurement Model | Eliminating Indian spice trader intermediaries captures margin previously distributed across fragmented networks. |
| REACH Dossier Pre-Registration | EFSA-reviewed legacy formulations avoid extended assessment timelines constraining novel extract introductions. |
| Multi-Hemisphere Sourcing Network | Vertically integrated procurement across India and Mexico mitigates seasonal labor availability constraints. |
Study Parameters
A standing panel of spice procurement directors, extraction facility managers, organic certification auditors, and pharmaceutical formulation scientists provided ongoing calibration throughout the research cycle. Primary interviews with these stakeholders combined with secondary validation from FSSAI export records, EU RASFF border rejection databases, FDA facility registration filings, and customs trade data. Bottom-up acreage and yield estimates triangulated against top-down consumption modeling across food manufacturing and pharmaceutical end-use segments.
Consistency checks validated volume and value outputs against external benchmarks including organic certification body acreage reports and supercritical equipment manufacturer order backlogs. The analytical framework segmented across product form, grade certification tier, end-use application, and regional regulatory cluster throughout the projection horizon. CAGRs derived from fitted growth curves incorporating agricultural input cost trajectories, labor availability projections, and evolving residue limit enforcement intensity.
Decision-makers should treat outputs as directional under sustained EU aflatoxin enforcement and stable organic equivalence agreement frameworks; material deviation in either would warrant model refresh. Specific risk factors include synthetic capsaicin substitution acceleration, three-year organic conversion timeline extensions, and multi-jurisdiction compliance synchronization failures. Recalibration cycles align with material shifts in regulatory enforcement intensity and extraction technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Frangipani Extract Market