
 Dipping Sauces Market | 2026-2036
Dipping Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Dipping Sauces Market Outlook
Foodservice distribution is reshaping how dipping sauces reach end users, with direct-to-restaurant platforms and centralized procurement hubs displacing traditional wholesale layers. McCormick & Company leverages its spice sourcing infrastructure to control raw material costs across barbecue and mustard lines. Nestlé sustains global manufacturing scale through regional production facilities that tailor viscosity and heat profiles to local preferences. Kraft Heinz anchors North American foodservice contracts with portion-controlled packet formats designed for quick-serve operators.
Dipping sauces are emulsified or suspended condiments formulated with acidulants, hydrocolloids, and flavor compounds to deliver consistent cling, stability, and taste release at serving temperatures between 4°C and 60°C; their primary commercial purpose is to extend menu versatility for protein and snack items without requiring kitchen labor. Soy sauce and barbecue sauce dominate volume due to entrenched placement in Asian and American cuisines, while gluten-free ingredient variants capture expanding margin pools as co-manufacturers invest in dedicated allergen-free production lines. Salsa competes intensely in the hotel and catering channel where fresh-refrigerated positioning commands price premiums over shelf-stable alternatives.
FDA labeling requirements for added sugars and sodium content shape formulation decisions for US-exported products, while EFSA evaluations of novel hydrocolloids determine which texturizers gain approval for European formulations. BIS certification for packaged foods affects market access for brands targeting India's organized retail sector. Stakeholders must monitor how divergent clean-label thresholds across regulators influence the economics of running single versus dual formulation platforms.
Market Dynamics
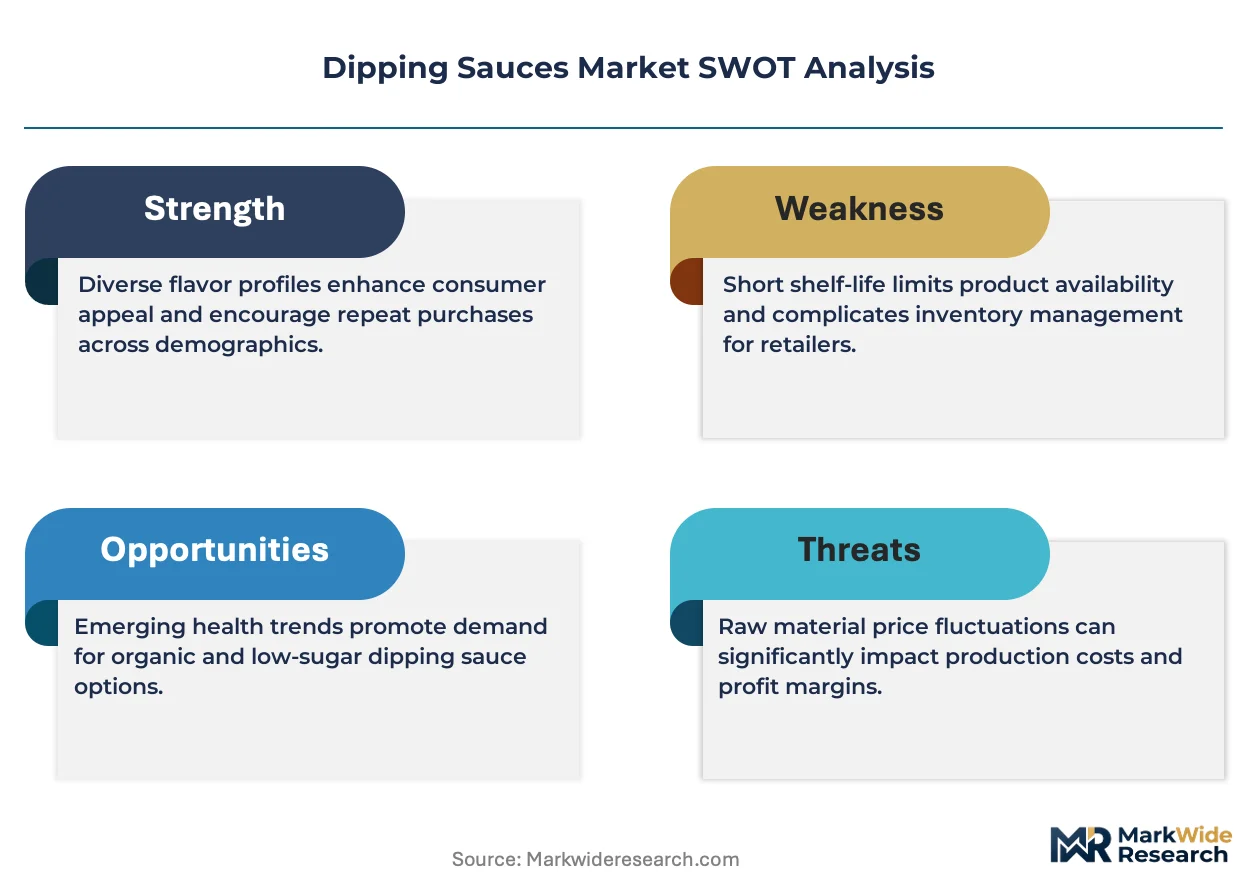
Clean-label ingredient mandates across multiple jurisdictions are forcing simultaneous reformulation of viscosity systems and preservative packages, compressing R&D timelines while expanding compliance costs for manufacturers serving cross-border foodservice accounts.
Growth Catalysts
- Street food formalization in Indonesia:Urban mall operators in Jakarta and Surabaya are standardizing sambal procurement through centralized commissary contracts, creating volume anchors for regional sauce processors.
- FDA added-sugar disclosure rules:US foodservice distributors now demand reformulated barbecue and sweet chili profiles with reduced high-fructose corn syrup, opening substitution opportunities for tapioca-based sweetener systems.
- High-pressure processing (HPP):Cold-pasteurization technology extends refrigerated salsa shelf life without thermal degradation of fresh pepper volatiles, enabling hotel and catering channel expansion.
Market Restraints
- Chili pepper input volatility:Drought cycles in India's Guntur growing belt and Mexico's Chihuahua region create 18-24 month price swings for capsaicin-intensive formulations.
- Single-source hydrocolloid concentration:EFSA-approved texturizers for clean-label European formulations draw from a narrow supplier base in fermentation-derived gellan and xanthan capacity.
- Refrigerated logistics cost structure:Cold-chain requirements for fresh-refrigerated salsa and hummus-based dips impose 3-4x distribution cost multiples versus ambient-stable alternatives.
Strategic Opportunities
- Vietnam's organized retail penetration:Modern trade expansion in Ho Chi Minh City and Hanoi creates shelf space for premium soy and fish sauce blends previously confined to traditional wet markets.
- EU Green Deal packaging mandates:Biodegradable portion-control packet requirements for foodservice operators drive innovation in seaweed-based film barriers for single-serve condiments.
- Direct-to-restaurant platform convergence:Digital procurement hubs in Southeast Asia aggregate independent operator demand, bypassing traditional wholesale markups for mid-volume sauce suppliers.
Industry Challenges
- Allergen-segregated production capacity:Gluten-free and sesame-free certification requirements demand dedicated filling lines and CIP systems, stretching capital deployment timelines for co-manufacturers.
- Dual-formulation platform complexity:Divergent clean-label thresholds between FDA disclosure rules and EFSA novel hydrocolloid approvals force parallel SKU maintenance for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dipping Sauces Market |
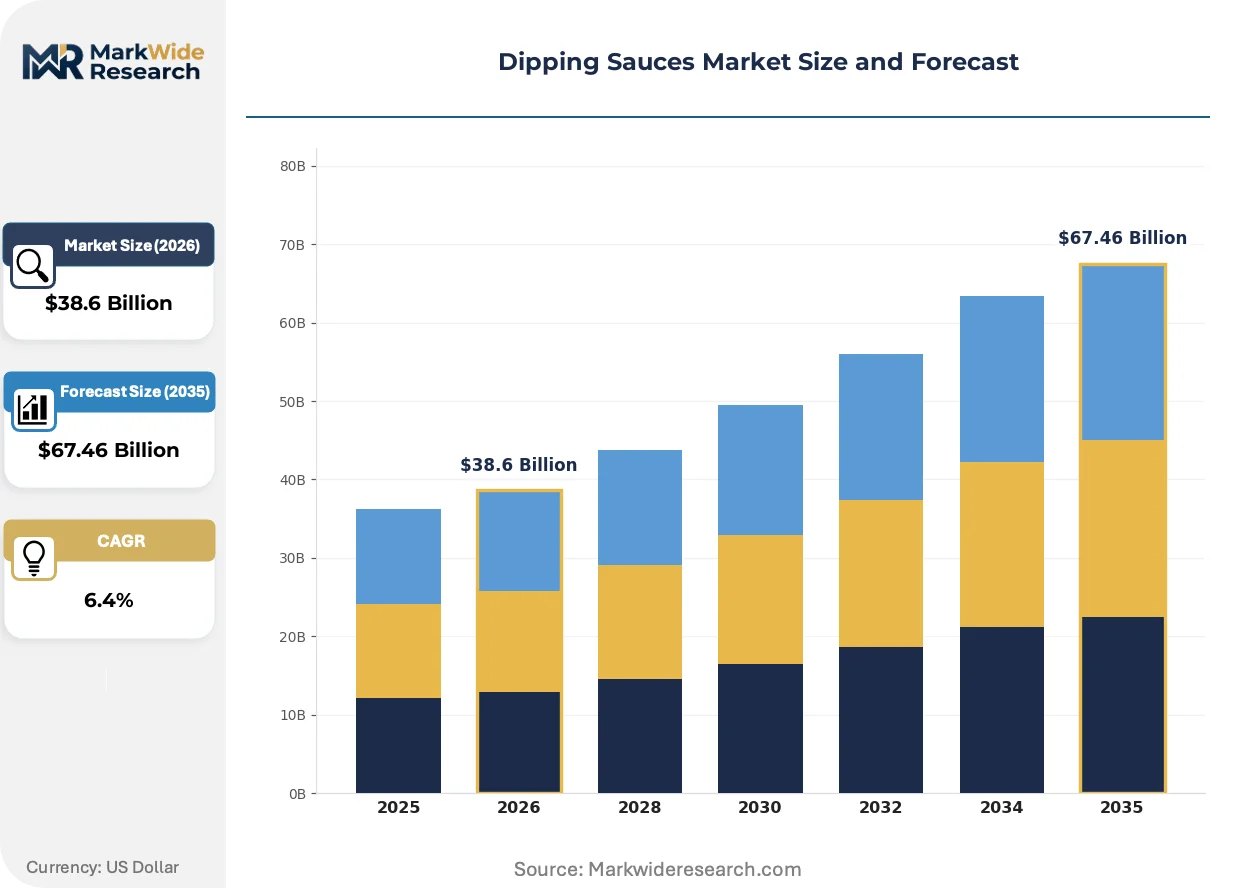
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barbecue Sauce, Mustard Sauce, Soy Sauce, Salsa Ingredient Type: Organic, Gluten-Free, Low Sugar, Spicy End User: Restaurants, Hotels, Catering Services, Food Trucks Packaging Type: Bottles, Pouches, Jars, Tubs |
| Companies Covered | McCormick & Company Incorporated, Nestlé, Kraft Heinz Company, Del Monte Foods Inc, Campbell Soup Company, Unilever Plc, General Mills Inc, Kikkoman Corporation, Conagra Brands Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dipping Sauces Market Strategic Shifts
Formulation science and distribution infrastructure are converging to redefine how dipping sauces achieve shelf stability, flavor precision, and regulatory compliance across temperature-variable supply chains.
Microencapsulation of volatile spice compounds using lipid-based wall materials protects heat-sensitive flavor molecules through retort processing and ambient distribution. Quick-service chains in Southeast Asia are piloting these systems for chili-crisp and sambal varieties that previously required refrigerated handling. The technology is rendering obsolete the traditional trade-off between thermal shelf stability and fresh flavor perception in extended-distribution sauces.
REACH restrictions on synthetic preservatives and EFSA evaluations of novel acidulants are accelerating migration to fermented rice vinegar and citrus-derived clean-label alternatives. European manufacturers reformulating barbecue and mustard lines face 12-18 month approval timelines for new texturizing systems. Hotel and catering operators sourcing fresh-refrigerated salsa are absorbing price premiums to maintain compliance with evolving additive thresholds.
Consolidated procurement through centralized commissary hubs is displacing fragmented wholesale purchasing in Indonesia's urban foodservice sector. Mall-based dining chains in Jakarta now specify viscosity and Scoville consistency across multi-location sauce deliveries, shifting supplier selection toward processors with laboratory-scale quality control. This pattern is most visible in soy-based and chili-forward categories where batch-to-batch variation previously dominated traditional supply relationships.
Dipping Sauces Market Segmentation
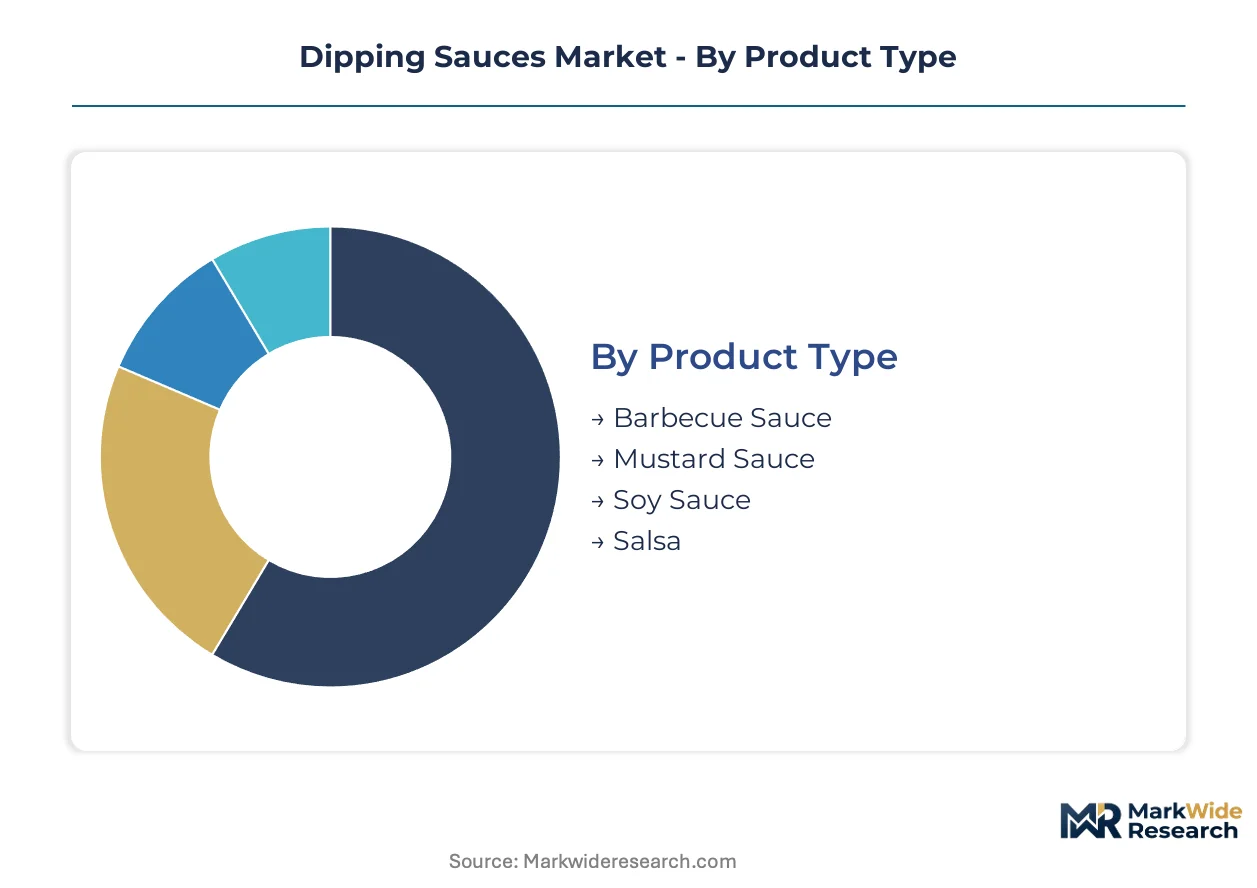
Dipping sauces segment along formulation chemistry, procurement channel, and temperature stability requirements that dictate manufacturing asset allocation. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier specialization.
Product Type:
Barbecue sauce and soy sauce turn inventory fastest through foodservice channels, while mustard and salsa exhibit slower velocity tied to seasonal menu cycles and refrigerated handling constraints.
- Barbecue Sauce:Tomato-vinegar emulsions with molasses or tapioca-based sweetener systems deliver cling viscosity at 60°C serving temperatures. Quick-service chains across the American South and Midwest specify this profile for protein coating applications, with FDA added-sugar disclosure rules forcing reformulation away from high-fructose corn syrup.
- Soy Sauce:Fermented wheat-soy hydrolysates with 15-18% sodium content by weight provide umami base notes for Asian cuisine integration. Indonesia's urban mall operators in Jakarta and Surabaya standardize procurement through centralized commissary contracts, creating volume anchors for regional processors.
- Mustard Sauce:Acidulated mustard flour suspensions with turmeric-derived color stability.
- Salsa:Fresh-refrigerated tomato-pepper blends requiring HPP cold-pasteurization for hotel and catering channel placement.
Barbecue sauce anchors the volume base while salsa gains share at the steepest rate through premium fresh-refrigerated positioning.
Ingredient Type:
Cost tiers separate commodity formulations from certified variants, with organic and gluten-free commanding 40-60% manufacturing overhead premiums for segregated production lines.
- Organic:USDA or EU organic certified inputs exclude synthetic pesticides and GMO-derived hydrocolloids. European clean-label mandates under EFSA novel ingredient evaluations restrict texturizer options, compressing approved supplier lists for organic barbecue and mustard emulsions.
- Gluten-Free:Dedicated filling lines and CIP systems prevent wheat cross-contamination, stretching capital deployment timelines for co-manufacturers. India's BIS certification for packaged foods creates compliance barriers for brands targeting organized retail penetration.
- Low Sugar:Reformulated acidulant blends replacing caloric sweeteners with stevia or monk fruit extracts.
- Spicy:Capsaicin-intensive profiles vulnerable to 18-24 month price swings from Guntur and Chihuahua drought cycles.
Gluten-free certification expands most quickly as allergen-segregated capacity becomes a procurement prerequisite for multinational foodservice contracts.
End User:
Customer type determines pack size, temperature requirements, and price elasticity, with institutional buyers negotiating multi-year contracts against spot-market food truck purchasing.
- Restaurants:Quick-serve operators specify portion-controlled packets and bulk dispensing formats designed for 4°C-60°C holding ranges. Southeast Asian chains are expanding dipping sauce menus to match localized taste profiles, driving formulation customization at regional production facilities.
- Hotels:Full-service properties demand Scoville and viscosity consistency across multi-location deliveries, shifting supplier selection toward processors with laboratory-scale quality control systems.
- Catering Services:Event-volume procurement with seasonal demand spikes and refrigerated logistics cost structure constraints.
- Food Trucks:Small-batch, high-velocity purchasing through direct-to-restaurant digital platforms bypassing traditional wholesale markups.
Restaurants dominate absolute volume while food trucks climb the fastest through platform-enabled procurement aggregation.
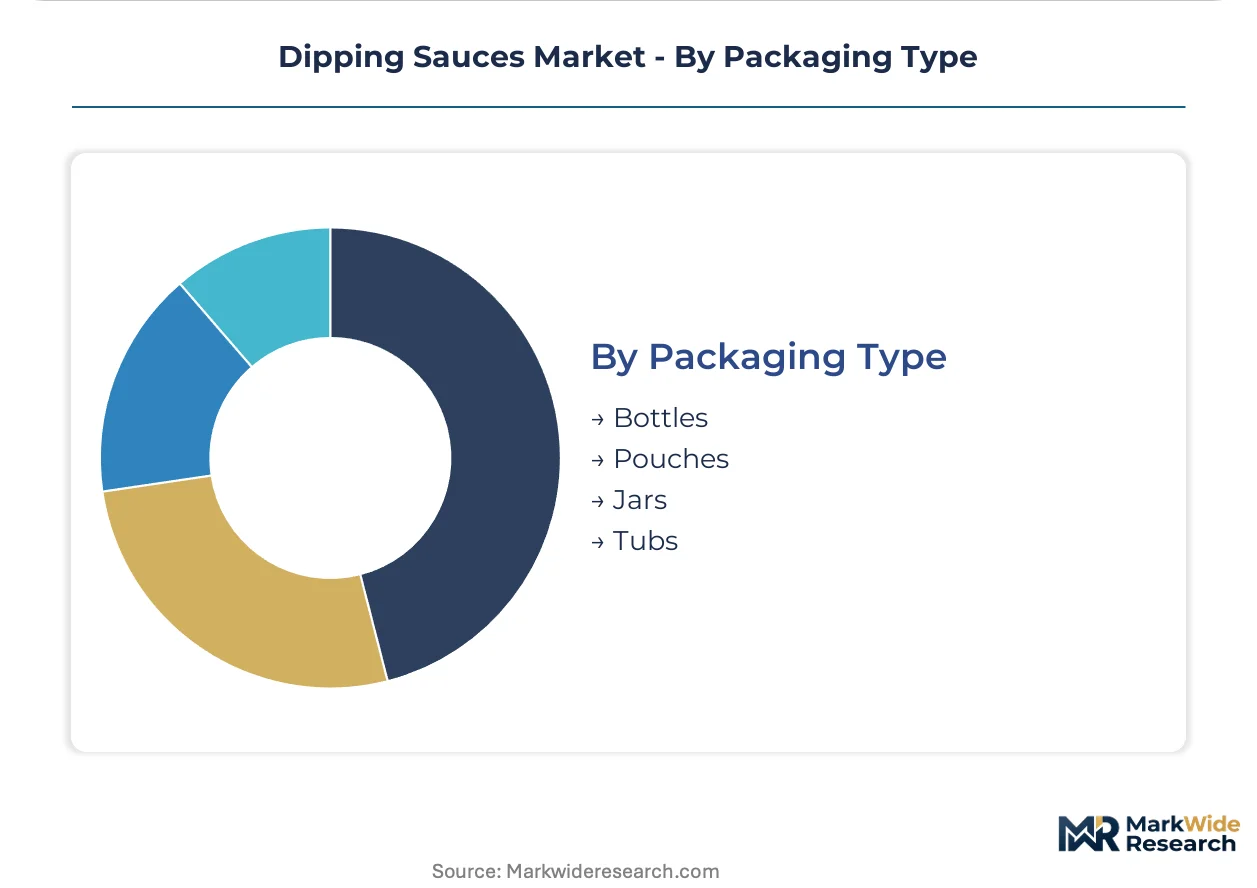
Packaging Type:
Material science and logistics economics separate ambient-stable formats from cold-chain-dependent alternatives, with sustainability mandates reshaping barrier film specifications.
- Bottles:PET or glass containers with induction-sealed closures for retail shelf stability and pour control. EU Green Deal packaging mandates are accelerating migration toward biodegradable alternatives, with seaweed-based film barriers entering pilot trials for single-serve condiment applications.
- Pouches:Flexible laminated films with spout fitments for foodservice portion efficiency and reduced shipping cube.
- Jars:Wide-mouth glass with vacuum-sealed lug closures for salsa and thick-format specialty sauces.
- Tubs:Injection-molded PP with tamper-evident lids for bulk foodservice and deli-counter applications.
Bottles maintain the installed base while pouches expand most quickly through foodservice logistics optimization and sustainability-driven material reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific condiment trade flows, handling containerized spice imports and processed sauce exports that connect Asian ingredient suppliers to North American foodservice distributors.
United States
Quick-service chains across the American South and Midwest specify barbecue sauce viscosity profiles for protein coating applications. FDA added-sugar disclosure rules force reformulation away from high-fructose corn syrup toward tapioca-based sweetener systems. McCormick & Company leverages its Maryland-based spice sourcing infrastructure to control raw material costs across regional barbecue and mustard production lines.
Indonesia
Urban mall operators in Jakarta and Surabaya standardize sambal procurement through centralized commissary contracts. BIS certification for packaged foods creates compliance barriers for brands targeting organized retail penetration beyond traditional wet markets. Street food formalization in Java's urban centers drives bulk procurement of soy-based and chili-forward varieties for mall-based dining chains.
Germany
Clean-label ingredient mandates under REACH restrictions and EFSA novel hydrocolloid evaluations compress approved supplier lists for organic barbecue emulsions. EU Green Deal packaging mandates accelerate migration toward biodegradable alternatives for single-serve condiment applications. Bavarian food processors reformulate mustard lines using fermented rice vinegar as synthetic preservative replacements face regulatory sunset.
India
Gluten-free certification requirements stretch capital deployment timelines for co-manufacturers serving multinational foodservice contracts. FSSAI labeling standards for packaged foods shape formulation decisions for domestic and export-oriented producers. Guntur's chili pepper growing belt experiences 18-24 month price swings that transmit volatility to capsaicin-intensive sauce formulations across South Asian supply chains.
Vietnam
Modern trade expansion in Ho Chi Minh City and Hanoi creates shelf space for premium soy and fish sauce blends previously confined to traditional wet markets. Direct-to-restaurant digital procurement hubs aggregate independent operator demand, bypassing traditional wholesale markups for mid-volume sauce suppliers. Da Nang's emerging logistics corridor supports temperature-controlled distribution for fermented sauce varieties requiring ambient stability management.
Dipping Sauces Market Competitive Environment
On the supply side, the industry is consolidating around diversified condiment conglomerates with captive spice sourcing and regional production footprints. Tiered competitive positioning separates global scale operators from mid-cap specialists focused on single-category dominance. Three archetypes predominate: vertically integrated spice-to-sauce processors, co-manufacturing platforms serving private-label retail, and fermentation-specialized Asian sauce houses. M&A activity concentrates on acquiring allergen-segregated production capacity, while strategic partnerships with direct-to-restaurant platforms reshape foodservice channel access.
Within the diversified conglomerate tier, McCormick & Company Incorporated and Nestlé exemplify scale-driven positioning through global manufacturing networks and regional formulation tailoring. Kraft Heinz Company occupies a position anchoring North American foodservice contracts through portion-controlled packet formats. Among fermentation-specialized operators, Kikkoman Corporation represents the traditional soy sauce archetype with entrenched placement in Asian cuisine integration. These three companies collectively illustrate how supply-side concentration in dipping sauces favors players with backward integration into raw material sourcing and multi-regional production assets.
| Leading Market Players |
|---|
| McCormick & Company Incorporated |
| Nestlé |
| Kraft Heinz Company |
| Del Monte Foods Inc |
| Campbell Soup Company |
| Unilever Plc |
| General Mills Inc |
| Kikkoman Corporation |
| Conagra Brands Inc |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European fermentation-derived hydrocolloid production is compressing margins for clean-label texturizer suppliers while simultaneously accelerating price competition in premium barbecue and mustard emulsions. This utilization imbalance forces manufacturers to absorb reformulation costs or push price increases toward foodservice distributors with limited alternative sourcing options.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified formulations with dedicated allergen-segregated lines from commodity bulk sauces and private-label alternatives. Price differentiation rests on certification tier and volume scale, with gluten-free and organic variants commanding manufacturing overhead premiums. Cost compression in standard-tier barbecue sauces is intensifying because FDA added-sugar disclosure rules force tapioca-based sweetener substitutions. Quick-serve chains exhibit highest price sensitivity due to centralized procurement leverage, while hotel and catering operators show lowest sensitivity for fresh-refrigerated salsa with HPP processing.
Supply Chain Analysis
Tariff exposure between the United States and Asian spice suppliers dominates supply chain risk planning for capsaicin-intensive formulations. Manufacturing concentration centers on Indonesia, Vietnam, and India for fermented soy and chili-forward varieties, with raw material dependencies on Guntur chili peppers, wheat-soy hydrolysates, and tapioca-derived sweeteners. Single-source vulnerability in EFSA-approved gellan and xanthan capacity creates bottleneck risk for European clean-label reformulations. Distribution runs through direct-to-restaurant digital platforms and centralized commissary hubs that displace traditional wholesale layers in Southeast Asian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dipping sauces are entering a cyclical recovery phase as street food formalization in Indonesia and Vietnam drives sustained procurement volume through centralized foodservice contracts. Input cost volatility in chili pepper belts and clean-label hydrocolloid capacity constraints define the recovery's amplitude.
For Market Incumbents: Build captive spice sourcing moats through backward integration into India's Guntur growing belt and Indonesia's regional commissary networks. McCormick-style infrastructure control over raw material costs defends against 18-24 month drought-driven price swings. Nestlé-pattern regional production facilities with localized viscosity tailoring neutralize emerging fermentation-specialized competitors. Prioritize allergen-segregated capacity additions to lock multinational foodservice contracts before co-manufacturing platforms achieve scale.
For New Entrants and Emerging Players: Vietnam's organized retail penetration in Ho Chi Minh City and Hanoi offers the most penetrable white-space for premium soy and fish sauce blends escaping traditional wet market confinement. Direct-to-restaurant platform partnerships bypass wholesale markups and aggregate fragmented independent operator demand. Target gluten-free certification gaps in India's BIS-regulated organized retail sector where capital deployment timelines stretch incumbent response capacity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation-specialized Asian sauce houses with entrenched placement in quick-serve supply chains. Long-term viability over the analysis window favors processors with laboratory-scale quality control systems and multi-location Scoville consistency capabilities. Acquisition target archetype: mid-volume regional suppliers with clean-label reformulation expertise and underutilized allergen-segregated lines. Monitor EFSA novel hydrocolloid approval timelines as inflection signal for European market access economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Allergen-Segregated Capacity Expansion | Dedicated filling lines and CIP systems unlock multinational foodservice contracts requiring gluten-free certification. |
| Direct-to-Restaurant Platform Integration | Digital procurement hubs in Jakarta and Ho Chi Minh City bypass traditional wholesale markups for mid-volume suppliers. |
| Clean-Label Reformulation Investment | Fermented rice vinegar and citrus-derived acidulants replace synthetic preservatives under REACH and FDA disclosure rules. |
| Microencapsulation Technology Adoption | Lipid-based wall materials protect heat-sensitive spice volatiles through ambient distribution without refrigeration. |
| Biodegradable Packaging Transition | Seaweed-based film barriers for single-serve condiments align with EU Green Deal mandates and foodservice sustainability procurement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA labeling guidance, EFSA novel ingredient evaluations, BIS certification standards, and trade flow data through the Port of Los Angeles. Primary interviews engaged R&D directors at diversified condiment conglomerates, procurement leads at Southeast Asian mall-based dining chains, quality control managers at regional sauce processors, and regulatory affairs specialists navigating REACH and FSSAI compliance. Secondary validation drew from customs records, foodservice distribution databases, and centralized commissary contract documentation. Bottom-up demand modeling across end-user segments triangulates against top-down value chain analysis.
Forecast inputs include formulation chemistry segmentation, temperature stability requirements, procurement channel evolution, and regional regulatory cluster divergence. The analytical framework models product type, ingredient certification tier, end-user category, and packaging format dimensions across the projection horizon. CAGRs derive from volume anchor identification in Indonesia's urban mall networks and substitution elasticity estimates for tapioca-based sweetener systems. Industry-specific inputs incorporate HPP cold-pasteurization adoption curves and clean-label hydrocolloid approval timelines.
Practitioners should monitor chili pepper drought cycles in Guntur and Chihuahua, EFSA novel texturizer evaluations, and direct-to-restaurant platform consolidation for early signals of forecast deviation. Forecasts reflect assumptions regarding street food formalization velocity and centralized procurement hub penetration. Material shifts in clean-label regulatory thresholds or fermentation-derived hydrocolloid capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Chocolate Syrup Market