
 Food Grade Release Agent Market | 2026-2036
Food Grade Release Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Release Agent Market Foresight
North American capacity expansion in food-grade emulsifier production is reconfiguring supply dynamics for release agent inputs. Cargill, Inc. leverages its integrated oilseed processing network to secure feedstock cost advantages. Palsgaard A/S specializes in emulsifier-release agent hybrids that reduce double-coating steps in industrial baking. Kerry Group anchors its position through bakery application labs in the United States and Ireland.
Food grade release agents are surface-active formulations, typically comprising vegetable oils, waxes, or silicone compounds at 0.5–2.0% application load, that prevent adhesion between food matrices and processing equipment. These agents must meet FDA 21 CFR 173.340 or EFSA purity specifications depending on destination market, with direct-contact variants requiring stricter residue limits than indirect-contact grades. Silicone-based agents dominate high-temperature frying and industrial conveyor applications where thermal stability exceeds 200°C, while vegetable oil-based alternatives are expanding fastest in European clean-label bakery segments as reformulation costs decline. Packaging type concentration sits with aerosol cans in artisan and mid-scale bakery channels where spray uniformity reduces over-application waste.
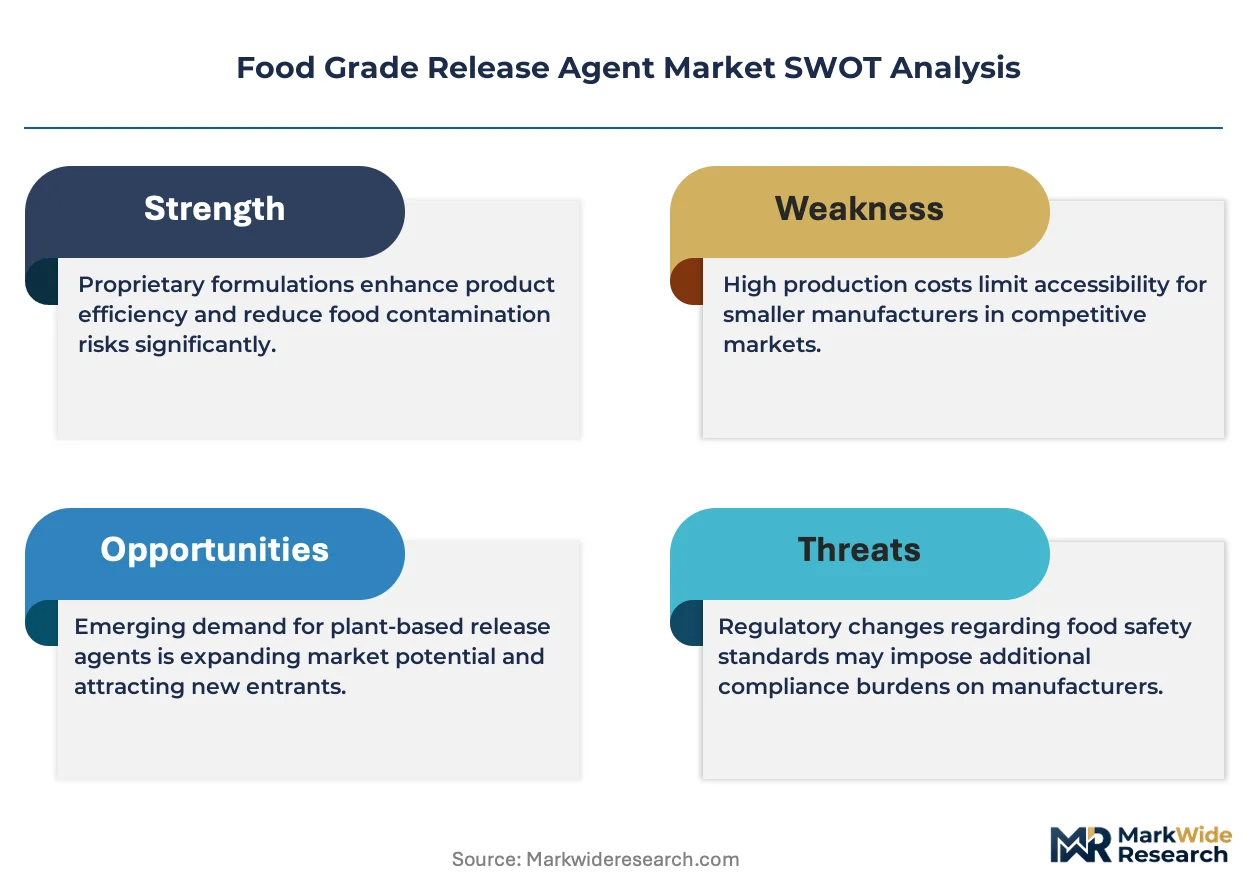
FDA, EFSA, and BIS frameworks collectively govern compositional limits, labeling thresholds, and migration testing protocols for food-contact release agents. EFSA's 2023 updated opinion on mineral oil hydrocarbons in recycled cardboard has redirected confectionery sector demand toward vegetable-derived barrier coatings. Stakeholders must monitor evolving maximum residue limits for siloxanes in infant food contact applications across multiple jurisdictions.
Market Dynamics
Clean-label reformulation mandates across EU member states are compressing silicone-based release agent margins while accelerating vegetable oil formulation R&D cycles in industrial bakery supply chains.
Growth Catalysts
- EFSA Additive Threshold Tightening:Commercial bakeries in Germany and France are expanding procurement of plant-derived release agents ahead of scheduled purity standard updates, redirecting formulation investment toward vegetable oil bases.
- High-Temperature Frying Expansion:Silicone compound thermal stability exceeding 200°C is capturing demand in industrial conveyor frying systems where process throughput requirements outpace clean-label alternatives.
- Dairy Processing Modernization:Western European dairy equipment upgrades are specifying food-grade emulsifier-release agent hybrids that eliminate double-coating steps in cheese mold release applications.
Market Restraints
- Vegetable Oil Feedstock Volatility:Sunflower and rapeseed oil price swings linked to Black Sea supply disruptions are compressing margin predictability for clean-label formulation specialists.
- Siloxane Residue Scrutiny:EFSA's evolving maximum residue limits for siloxanes in infant food contact applications are extending certification timelines and raising compliance costs for silicone-based product lines.
- Mineral Oil Hydrocarbon Substitution Costs:EFSA's 2023 updated opinion on mineral oil hydrocarbons in recycled cardboard has forced confectionery sector buyers to absorb premium pricing for vegetable-derived barrier coating alternatives.
Strategic Opportunities
- Clean-Label Bakery Penetration:France's artisan and mid-scale bakery channels present underexploited demand for aerosol can delivery formats where spray uniformity reduces over-application waste.
- Emulsifier-Release Agent Convergence:Hybrid formulations combining vegetable oil bases with integrated emulsifier functionality are opening double-digit cost reduction pathways for industrial baking operations.
- BIS Standard Alignment:India's Bureau of Indian Standards food-contact purity specifications are creating first-mover advantage windows for vegetable oil-based agents ahead of anticipated domestic manufacturing requirements.
Industry Challenges
- Migration Testing Capacity Bottlenecks:FDA 21 CFR 173.340 direct-contact residue limit verification requires specialized analytical infrastructure that third-party laboratories in secondary markets cannot reliably supply.
- Reformulation Technical Debt:Legacy silicone-dependent industrial baking lines face retrofit complexity when integrating vegetable oil-based alternatives with divergent viscosity and thermal conductivity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Release Agent Market |
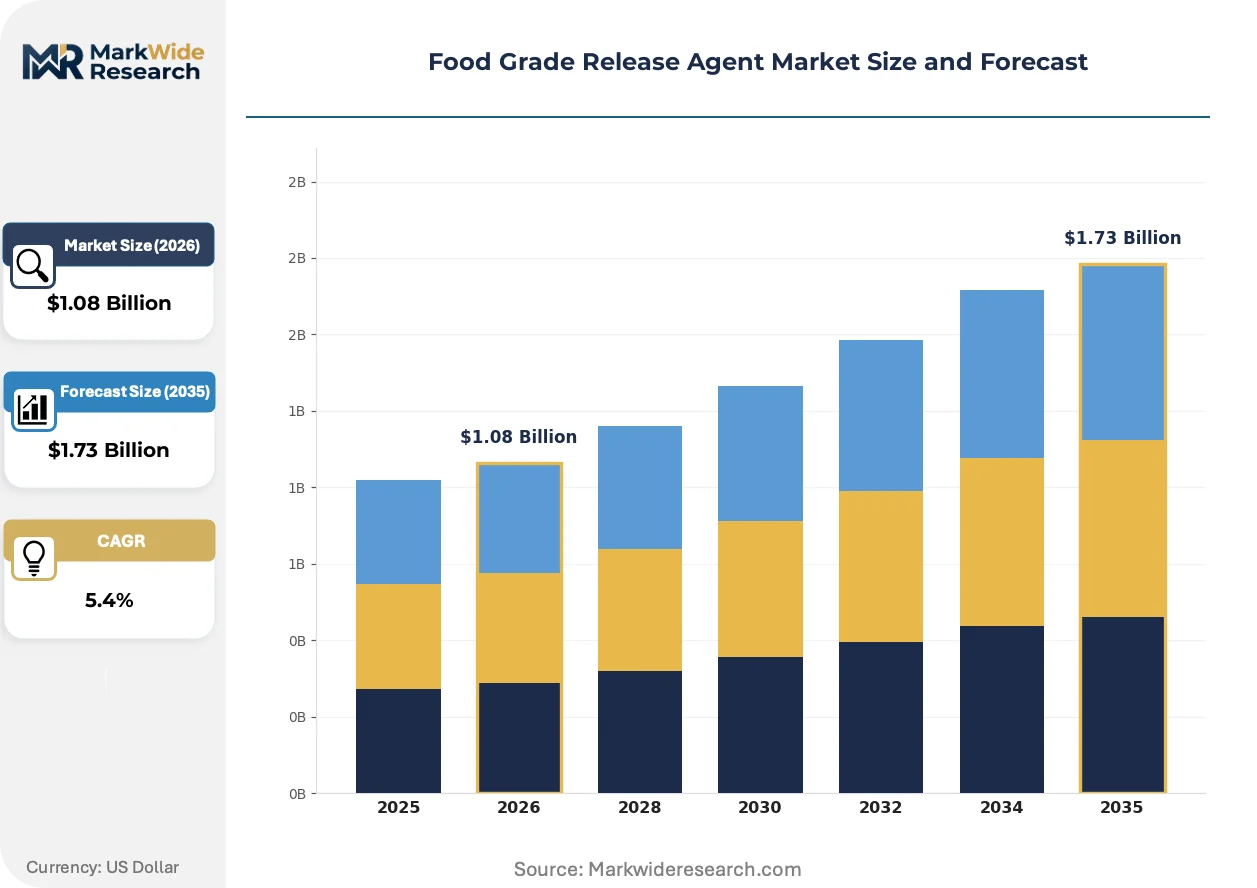
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Wax-Based, Mineral Oil-Based, Vegetable Oil-Based, Synthetic, Polymer-Based Application: Baking, Confectionery, Dairy Processing, Meat Processing, Beverage Production End User: Food Processing Units, Catering Services, Packaging Manufacturers, Commercial Bakeries Packaging Type: Aerosol Cans, Bottles, Drums, Pails, Sachets |
| Companies Covered | Cargill, Inc., Dow Chemical Company, Archer Daniels Midland Co., Baker Hughes, Kerry Group, BASF SE, Palsgaard A/S, Avatar Corp, Univar Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Release Agent Market Shifts & Advancements
Formulation chemistry is bifurcating between high-performance silicone variants for extreme thermal applications and bio-derived alternatives for clean-label positioning, with hybrid architectures emerging as the dominant R&D pathway.
Emulsifier-release agent hybrids are combining surface-active vegetable oil formulations with integrated emulsification functionality to eliminate separate coating steps. Industrial bakeries in Ireland and the United States are adopting these dual-purpose agents at accelerating rates to reduce line changeover downtime. This convergence is hybridizing what were previously distinct additive categories, compressing supplier margins in standalone emulsifier segments while rewarding integrated formulation capabilities.
REACH registration requirements for silicone-based substances are tightening substance volume tracking and safety data sheet granularity across EU manufacturing facilities. The regulatory burden is elevating compliance costs most acutely for mid-scale compounders lacking dedicated regulatory affairs functions. German and French release agent distributors are responding by consolidating supplier relationships toward vertically integrated oilseed processors with captive regulatory infrastructure.
Direct specification of release agents by retail-facing bakery brands rather than equipment OEMs is shortening procurement cycles and shifting technical validation responsibilities upstream. Brand-led formulation approval processes are displacing traditional equipment-manufacturer certification pathways in premium private-label segments. This buyer behavior rotation is most pronounced in UK and Scandinavian markets where retailer clean-label commitments translate directly into supplier selection criteria.
Food Grade Release Agent Market Segmentation
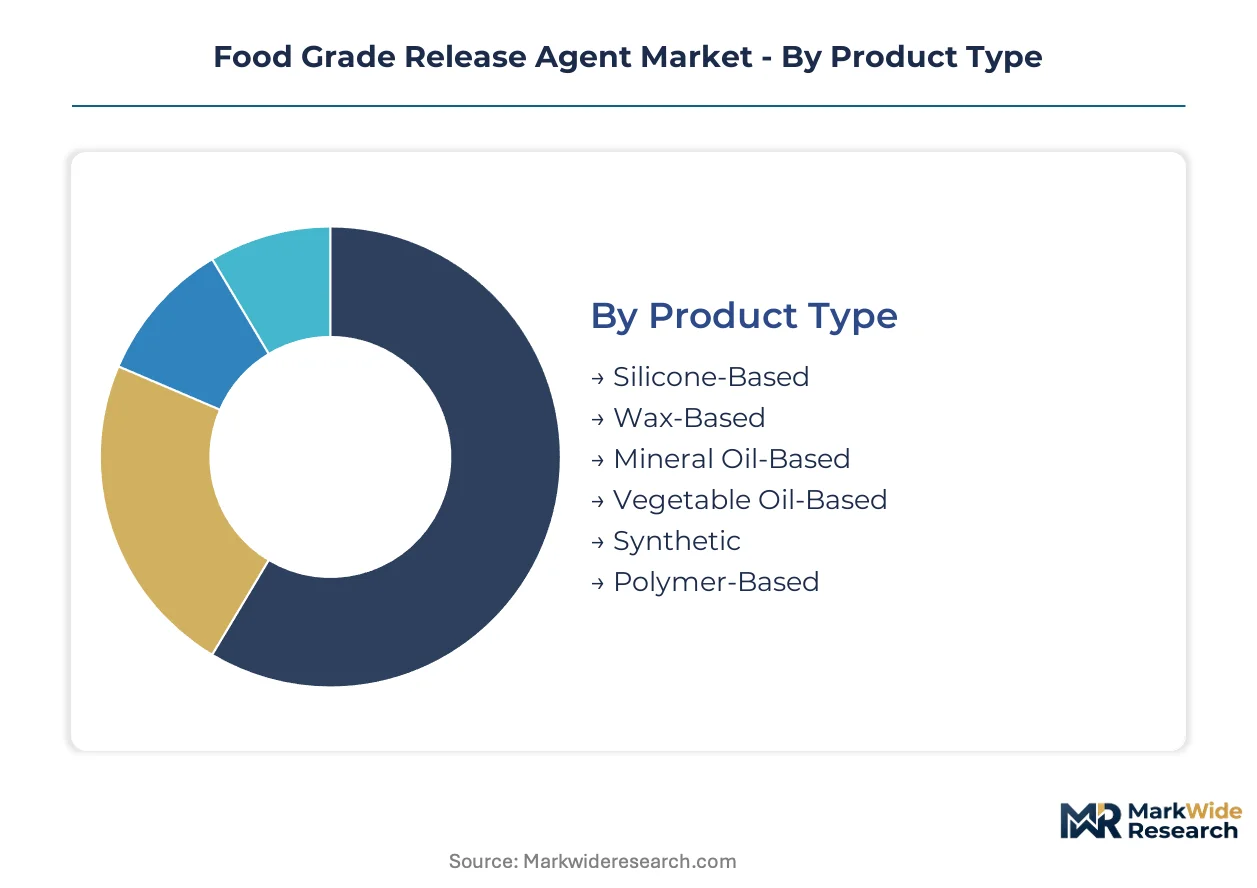
Release agent segmentation reflects divergent technical requirements across temperature regimes, regulatory jurisdictions, and operational scales. Formulation chemistry, application method, and end-use specifications create distinct commercial compartments with non-overlapping supplier capabilities.
Product Type:
Cost tier stratification separates premium thermal stability from economy clean-label positioning across six formulation bases.
- Silicone-Based:Polydimethylsiloxane formulations deliver thermal stability exceeding 200°C for industrial conveyor frying and high-speed baking lines. Demand concentrates in North American frozen dough processing where throughput requirements outpace vegetable oil alternatives.
- Vegetable Oil-Based:Refined sunflower and rapeseed oil emulsions with lecithin or monoglyceride additives serve EFSA-regulated clean-label bakery segments. German and French commercial bakeries are expanding procurement ahead of scheduled purity standard updates.
- Wax-Based:Carnauba and paraffin wax suspensions provide release functionality for chocolate molding and confectionery demolding applications.
- Mineral Oil-Based:Technical white mineral oils face substitution pressure from EFSA's mineral oil hydrocarbon scrutiny in recycled cardboard contact applications.
- Synthetic:Petrochemical-derived esters occupy mid-tier pricing for dairy processing equipment where thermal demands exclude vegetable bases.
- Polymer-Based:Polyethylene and polypropylene dispersions serve specialized meat processing release applications requiring film-forming properties.
Silicone-Based holds installed capacity. Vegetable Oil-Based is rotating up the share rankings.
Application:
End-use thermal profiles and regulatory exposure create five distinct demand pools with divergent formulation specifications.
- Baking:Pan grease and conveyor belt coatings for bread, pastry, and frozen dough production represent the largest volume application. Industrial bakeries in Ireland and the United States are adopting emulsifier-release agent hybrids to reduce line changeover downtime.
- Dairy Processing:Cheese mold release and equipment coating applications in Western Europe specify food-grade emulsifier hybrids that eliminate double-coating steps during equipment modernization cycles.
- Confectionery:Chocolate demolding and gummy production release functions face reformulation pressure from EFSA mineral oil hydrocarbon restrictions.
- Meat Processing:Slicer blade and forming equipment coatings require NSF H1 registration for incidental food contact in USDA-inspected facilities.
- Beverage Production:Bottle and can handling lubrication applications represent a specialized niche with distinct migration testing protocols.
Baking commands volume concentration. Dairy Processing is climbing the fastest among application segments.
End User:
Customer scale and technical specification authority separate four procurement archetypes with diverging validation requirements.
- Commercial Bakeries:Mid-scale and artisan operations across France and UK markets are driving aerosol can specification for spray uniformity benefits. Retail-facing bakery brands are displacing equipment OEMs as the primary formulation approvers in premium private-label segments.
- Food Processing Units:Large-scale industrial operators with captive regulatory affairs functions consolidate supplier relationships toward vertically integrated oilseed processors.
- Packaging Manufacturers:Confectionery sector buyers are absorbing premium pricing for vegetable-derived barrier coatings following EFSA's updated mineral oil hydrocarbon opinion.
- Catering Services:Central kitchen and contract food service operations represent fragmented demand with limited formulation specification authority.
Food Processing Units hold installed capacity. Commercial Bakeries is gaining share fastest through brand-led procurement.
Packaging Type:
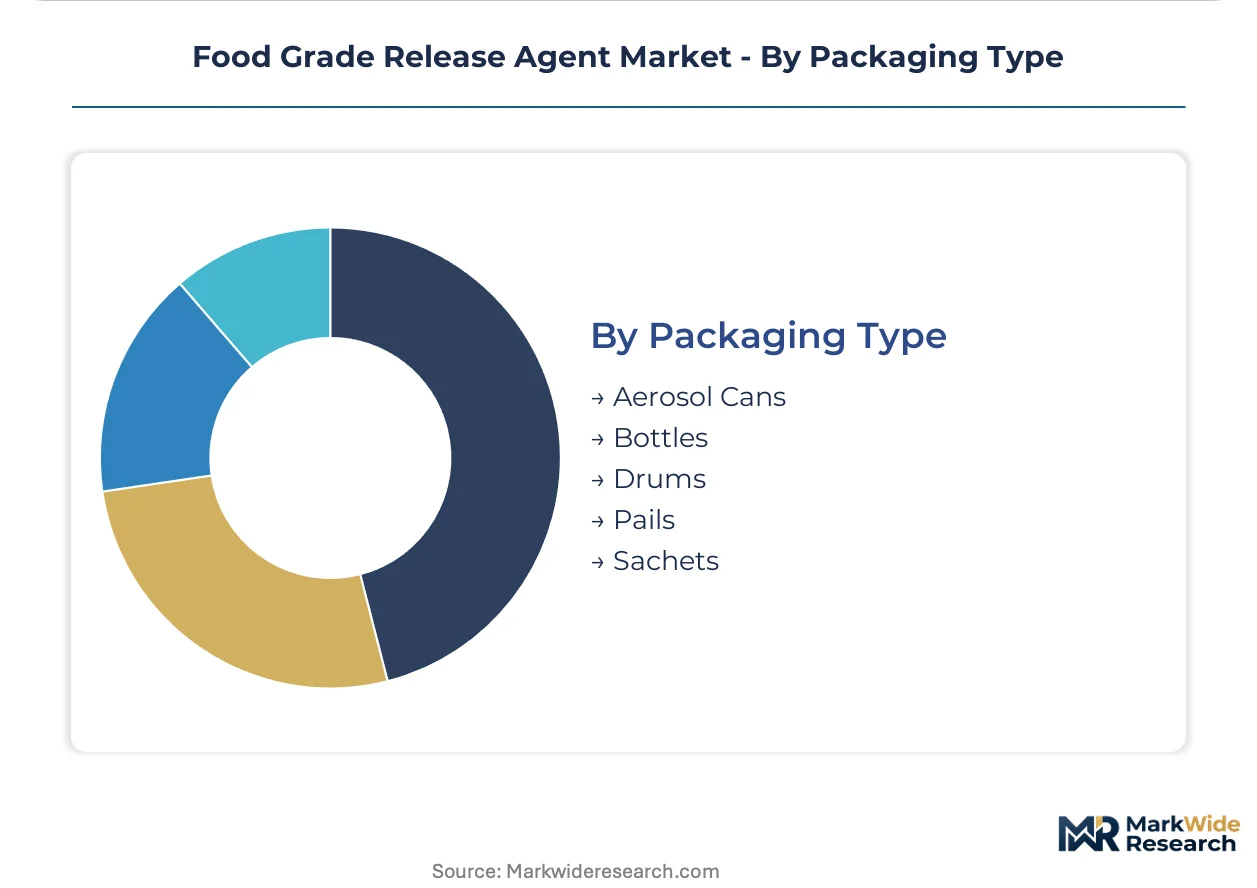
Delivery format selection reflects application precision requirements, storage constraints, and waste reduction priorities across five container categories.
- Aerosol Cans:Pressurized spray systems deliver uniform coating thickness for artisan and mid-scale bakery channels where over-application waste reduction justifies per-unit premium. France's bakery sector presents underexploited demand concentration.
- Drums:Bulk liquid delivery for industrial baking and dairy processing lines with automated application systems and volume procurement contracts.
- Pails:Intermediate volume packaging for regional bakery chains and food processing units with moderate throughput requirements.
- Bottles:Hand-application formats for catering services and small-scale operations with limited equipment investment.
- Sachets:Single-use portions for field catering and emergency food service applications with shelf stability priorities.
Drums hold installed capacity. Aerosol Cans is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA purity specifications in Germany are redirecting commercial bakery procurement toward vegetable oil-based formulations ahead of scheduled additive threshold updates. This regulatory anchor shapes demand patterns across Western European processing clusters.
Germany
Commercial bakeries in Bavaria and North Rhine-Westphalia are accelerating clean-label release agent procurement as EFSA tightens permissible additive thresholds. The country's Federal Office of Consumer Protection and Food Safety (BVL) enforces migration testing protocols that exceed baseline EU requirements. Industrial baking clusters around Munich and Hamburg specify aerosol can formats for mid-scale operations seeking spray uniformity benefits.
France
Artisan and mid-scale bakery channels in Île-de-France present underexploited demand concentration for vegetable oil-based aerosol formulations. ANSM oversight of food-contact substances aligns with EFSA's evolving mineral oil hydrocarbon restrictions in recycled cardboard applications. Lyon and Paris basin processing facilities are absorbing premium pricing for plant-derived barrier coatings in confectionery demolding operations.
United States
Frozen dough processing lines specify silicone-based agents where thermal stability exceeding 200°C outpaces clean-label alternatives. FDA 21 CFR 173.340 direct-contact residue limits require specialized analytical infrastructure concentrated in Midwest and Northeast corridor laboratories. Chicago and Minneapolis industrial baking clusters consolidate supplier relationships toward integrated oilseed processors with captive regulatory affairs functions.
India
Bureau of Indian Standards food-contact purity specifications are creating first-mover advantage windows for vegetable oil-based agents ahead of anticipated domestic manufacturing requirements. Maharashtra and Gujarat dairy processing modernization cycles specify emulsifier-release agent hybrids that eliminate double-coating steps. Mumbai and Ahmedabad equipment upgrade timelines are compressing certification timelines for suppliers with established BIS alignment.
United Kingdom
Retail-facing bakery brands in London and the Midlands are displacing equipment OEMs as primary formulation approvers in premium private-label segments. UK Food Standards Agency enforcement of EU-retained EFSA standards maintains clean-label pressure on supplier selection criteria. Yorkshire and Greater Manchester industrial bakeries are adopting hybrid emulsifier-release agents to reduce line changeover downtime.
Food Grade Release Agent Market Competitive Landscape
Integrated oilseed processors and specialized emulsifier compounders split the market between feedstock cost control and formulation convergence capabilities. The supplier base concentrates around vertically integrated agricultural conglomerates with captive oilseed crushing infrastructure and mid-scale European compounders with dedicated regulatory affairs functions. Three archetypes dominate: upstream-integrated agricultural processors, hybrid emulsifier-release agent specialists, and regional distribution-focused compounders. Competitive moves center on backward integration into vegetable oil feedstock supply and geographic expansion through application laboratory networks.
Within the upstream-integrated tier, Cargill, Inc. exemplifies agricultural processors leveraging captive oilseed networks to secure formulation cost advantages. Kerry Group anchors the hybrid specialist archetype through bakery application laboratories in Ireland and the United States. Palsgaard A/S occupies a position within the emulsifier convergence segment, representing integrated emulsifier-release agent formulation capabilities. These three companies illustrate the strategic segmentation between feedstock control, application technical service, and hybrid functionality development.
| Leading Market Players |
|---|
| Cargill, Inc. |
| Dow Chemical Company |
| Archer Daniels Midland Co. |
| Baker Hughes |
| Kerry Group |
| BASF SE |
| Palsgaard A/S |
| Avatar Corp |
| Univar Solutions |
| Others |
Supply & Pricing Matrix
Undercapacity in Western European vegetable oil processing is elevating feedstock spot premiums and compelling release agent compounders to absorb margin compression or pass through costs to EFSA-regulated bakery buyers. This utilization squeeze simultaneously tightens supplier pricing discipline and accelerates consolidation toward integrated oilseed processors with captive crushing infrastructure.
Pricing Analysis
Geographic price spreads between North American silicone-based formulations and European vegetable oil alternatives have widened as Black Sea sunflower supply disruptions ripple through rapeseed and palm oil benchmarks. Three-tier pricing structure across premium thermal stability, standard clean-label, and economy mineral oil grades reflects certification burden differentials under FDA 21 CFR 173.340 versus EFSA purity specifications. Pricing pressure stems from vegetable oil feedstock volatility as compounders lack hedging depth against seed oil futures swings. Small-scale artisan bakeries exhibit highest price sensitivity, while frozen dough processors prioritize thermal performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Cargill's oilseed processing network, Kerry Group's application laboratories, and Palsgaard's emulsifier compounding facilities across Denmark and the Netherlands. Supply draws from Argentina, Ukraine, and Canada for sunflower and rapeseed oil feedstocks, with lecithin and monoglyceride emulsifiers sourced from soy processing streams. Single-source vulnerability concentrates in Black Sea oilseed corridors where geopolitical disruption propagates through European formulation costs. Distribution runs through regional chemical distributors in Germany and France, with direct account management for multinational food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food grade release agent market is cycling through a recovery phase as EFSA regulatory clarity resets procurement calendars and deferred equipment upgrades resume across Western European dairy and bakery sectors. This cyclical upswing favors suppliers with pre-positioned clean-label formulations and BIS-aligned certification pathways.
For Market Incumbents: Harden defensive positions by deepening backward integration into South American oilseed sourcing and accelerating BIS pre-certification for India's anticipated domestic manufacturing mandates. Kerry Group and Palsgaard's hybrid emulsifier-release agent capabilities must expand application laboratory capacity in Mumbai and São Paulo before regional compounders replicate technical service models. Threat of margin compression from integrated agricultural processors demands proprietary formulation lock-in through equipment OEM specification partnerships.
For New Entrants and Emerging Players: Pursue white-space penetration in France's aerosol can bakery channel where spray uniformity benefits remain underexploited by drum-focused industrial suppliers. India's dairy processing modernization presents the most penetrable geography given compressed certification timelines for BIS-aligned entrants. Go-to-market execution should anchor on direct technical sales to retail-facing bakery brands displacing equipment OEMs as formulation approvers in UK and Scandinavian premium private-label segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across vegetable oil-based formulation sub-segments as toll manufacturing and contract compounding displace captive production. Long-term viability over the next decade rests on regulatory affairs infrastructure depth rather than scale economics alone. Acquisition targets should screen for dedicated EFSA and FDA compliance teams with established migration testing laboratory relationships. Signal to monitor: BIS standard finalization timelines and Maharashtra dairy equipment tender awards.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill's captive supply network neutralizes sunflower price volatility for EFSA-regulated bakery formulations. |
| Emulsifier-Release Agent Hybrid Development | Palsgaard's dual-functionality chemistry eliminates coating steps for Irish and US industrial bakeries. |
| BIS Pre-Certification Investment | Early alignment with India's food-contact purity specifications secures first-mover positioning in Gujarat dairy modernization. |
| Application Laboratory Expansion | Kerry Group's technical service density in Mumbai and Chicago anchors brand-led formulation approval shifts. |
| Aerosol Can Channel Penetration | Spray uniformity benefits in France's artisan bakery segment reduce over-application waste and justify per-unit premiums. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial bakery procurement directors, dairy processing equipment engineers, release agent formulation chemists, and EFSA regulatory affairs specialists. Secondary validation drew from FDA 21 CFR filings, EFSA scientific opinions on mineral oil hydrocarbons, BIS draft food-contact standards, and customs trade data for vegetable oil feedstock flows. Bottom-up volume estimates by application segment were triangulated against top-down market sizing from integrated oilseed processor disclosures.
Calibration across the analysis window employed a segmented growth framework modeling formulation chemistry type, application thermal profile, end-user procurement scale, and packaging delivery format. CAGRs were derived from elasticity-adjusted volume projections tied to EFSA regulatory implementation schedules and dairy equipment capital expenditure cycles. Forecast inputs incorporated vegetable oil price correlation matrices and clean-label reformulation cost curves from German and French bakery supply chain interviews.
Macroeconomic conditions sit as an overlay; deviation in sunflower and rapeseed oil benchmarks, EFSA siloxane residue limit finalization, or BIS enforcement intensity would shift the trajectory. Quarterly review of EU additive threshold announcements, Black Sea grain corridor status, and Indian dairy processing tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Curcumin Food Color Market