
 Global Hot Pot Condiment Market | 2026-2036
Global Hot Pot Condiment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hot Pot Condiment Market Analysis
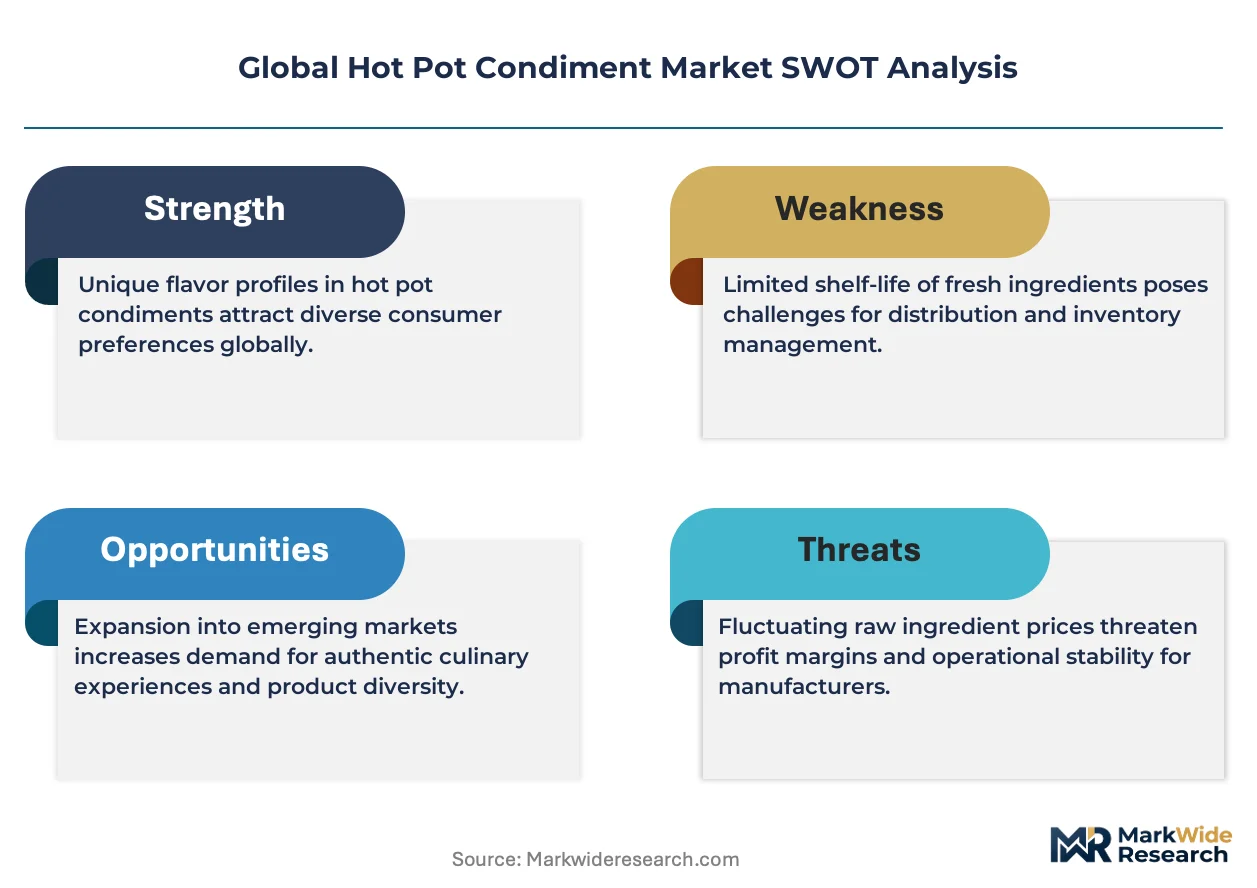
Recipe-based subscription services for hot pot meal kits is rebalancing how condiment bundles reach consumers. Hai Di Lao leverages its restaurant brand equity to anchor direct-to-consumer sauce subscriptions. Teway Food Group sustains manufacturing scale across multiple flavor formats. Ajinomoto competes on umami science integration in broth bases.
Hot pot condiments comprise blended sauces, oils, and seasonings formulated for tabletop cooking, typically featuring chili pepper extracts, fermented soybean pastes, and sesame derivatives with pH levels and preservative thresholds governed by food safety codes. These products serve the communal dining experience by delivering standardized flavor intensity across variable heat conditions. Spicy sauce and sesame sauce categories command the widest shelf presence, while sachet packaging gains traction in food service channels seeking portion control. The umami flavor profile leads retail preference, though spicy variants dominate in China's interior provinces where heat tolerance shapes repeat purchase behavior.
China's SAMR enforces GB standards for condiment additive limits and labeling accuracy, while the FDA in the United States governs import clearance and allergen disclosure for Asian sauce shipments. EFSA's flavoring substance evaluations in Europe affect formulation choices for brands exporting to EU markets. Stakeholders must monitor how carbon footprint disclosure rules under CSRD reshape packaging material selection and supplier qualification criteria across export destinations.
Market Dynamics
Recipe-based subscription services for hot pot meal kits are rebalancing how condiment bundles reach consumers, compressing traditional retail shelf cycles while expanding direct-to-consumer penetration. This channel shift forces manufacturers to reconfigure packaging formats and logistics networks around recurring delivery cadences rather than seasonal replenishment patterns.
Growth Catalysts
- China's NMPA food safety standards:GB standards for condiment labeling and additive limits create compliance barriers that favor scaled manufacturers with dedicated regulatory affairs teams.
- Chongqing and Sichuan province demand clusters:Hot pot culture anchors per-capita consumption intensity unmatched elsewhere, generating product development pull for premium chili oil and fermented base formulations.
- Sesame paste processing automation:Advanced grinding and pasteurization systems reduce batch variability and extend shelf stability without preservative load increases.
Market Restraints
- Chili pepper input volatility:Weather-driven harvest fluctuations in China's Guizhou and Henan growing regions create raw material cost instability for spicy sauce formulations.
- Supply concentration in Sichuan:Fermented soybean paste production clusters around Chengdu basin facilities, exposing buyers to single-source geographic risk during flooding or transport disruptions.
- EFSA flavoring substance evaluations:Pending assessments of certain pyrazine compounds used in umami broth bases threaten reformulation costs for EU-exporting brands.
Strategic Opportunities
- Indonesia's nascent hot pot segment:Jakarta and Surabaya restaurant chains are adopting Sichuan-style tabletop dining, creating first-mover advantage for sauce exporters with halal certification pathways.
- CSRD carbon footprint disclosure rules:Early compliance with EU packaging material traceability requirements positions suppliers for preferential procurement by sustainability-committed European distributors.
- AI-driven flavor profiling:Machine learning analysis of regional taste preference data enables localized formulation adjustments without extensive sensory panel investments.
Industry Challenges
- Fermentation microbiology expertise scarcity:Traditional doubanjiang and douchi production requires multi-year apprenticeship pipelines that industrial facilities struggle to replicate at scale.
- Dual certification timeline compression:Simultaneous pursuit of China's organic certification and EU organic equivalence approval demands parallel documentation streams that strain smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hot Pot Condiment Market |
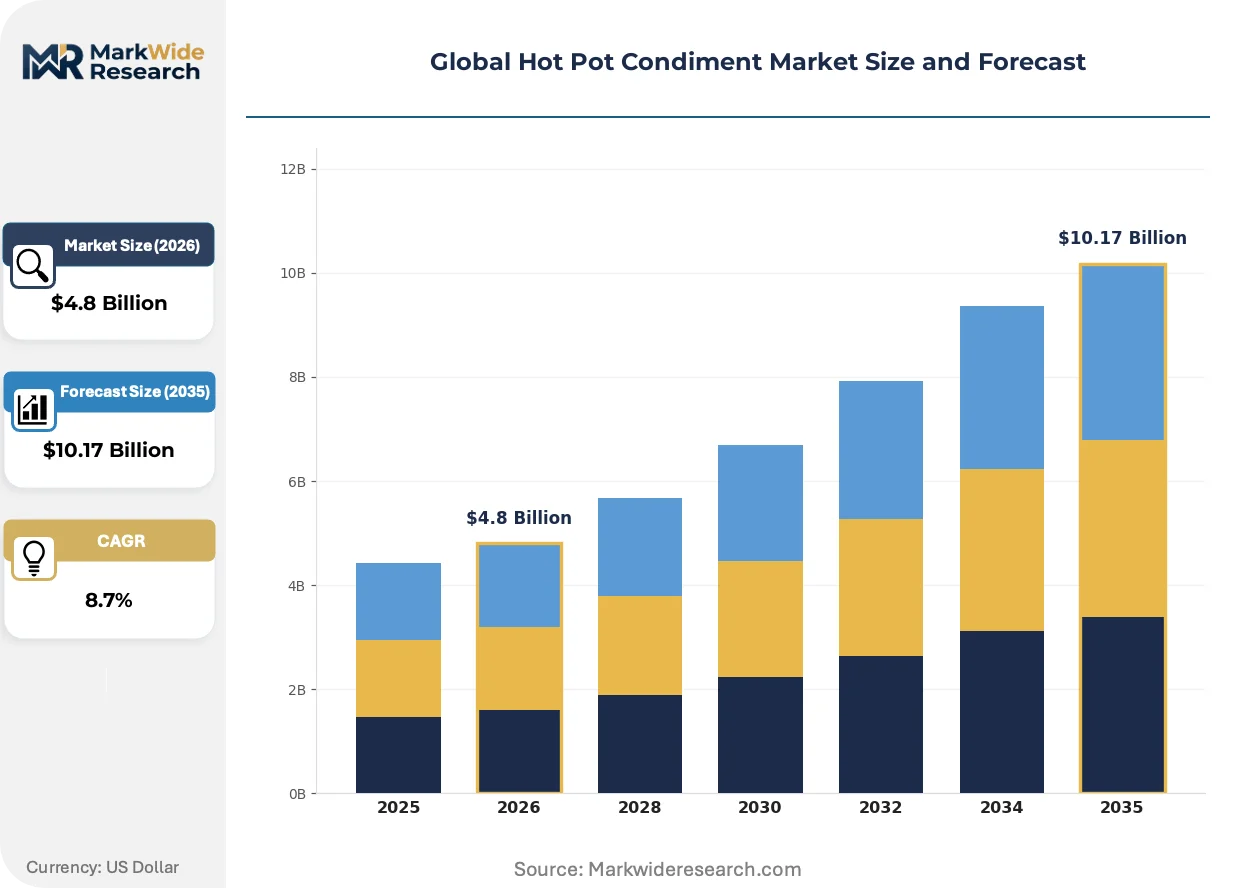
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spicy Sauce, Sesame Sauce, Soy Sauce, Hot Chili Oil Flavor Profile: Umami, Spicy, Savory, Sweet Packaging Type: Bottle, Sachet, Jar, Pouch Distribution Channel: Retail Store, Online Store, Food Service, Supermarket |
| Companies Covered | Hai Di Lao, Teway Food Group, Yihai, Laoganma, Inner Mongolia Red Sun, Little Sheep, Hongjiujiu, Ajinomoto, Lee Kum Kee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hot Pot Condiment Market Emerging Trajectories
Active fermentation monitoring systems and precision-controlled aging environments are transforming how traditional condiment bases achieve consistency. These technologies compress development cycles while preserving heritage flavor profiles that previously required decades of craft accumulation.
Precision fermentation technology is rewriting quality assurance protocols for fermented soybean pastes. Mid-tier restaurant chains in China's tier-two cities are adopting sensor-monitored production lots to reduce batch rejection rates. This capability is compressing the competitive gap between heritage brands and industrial-scale challengers by standardizing umami intensity previously dependent on master fermenter judgment.
CSRD carbon footprint disclosure rules are reshaping packaging material selection across EU-bound supply chains. Extended producer responsibility frameworks now mandate recycled content thresholds for plastic sachets and glass jars. Sauce exporters are responding by qualifying domestic biopolymer suppliers and redesigning multi-layer laminates for mechanical recyclability.
Home dining enthusiasts are displacing restaurant-derived trial as the primary adoption pathway for novel condiment formats. Direct-to-consumer subscription bundles featuring rotating regional variants are capturing shelf space traditionally reserved for established SKUs. This pattern concentrates in China's coastal provinces where delivery infrastructure supports cold-chain sauce preservation.
Global Hot Pot Condiment Market Segmentation
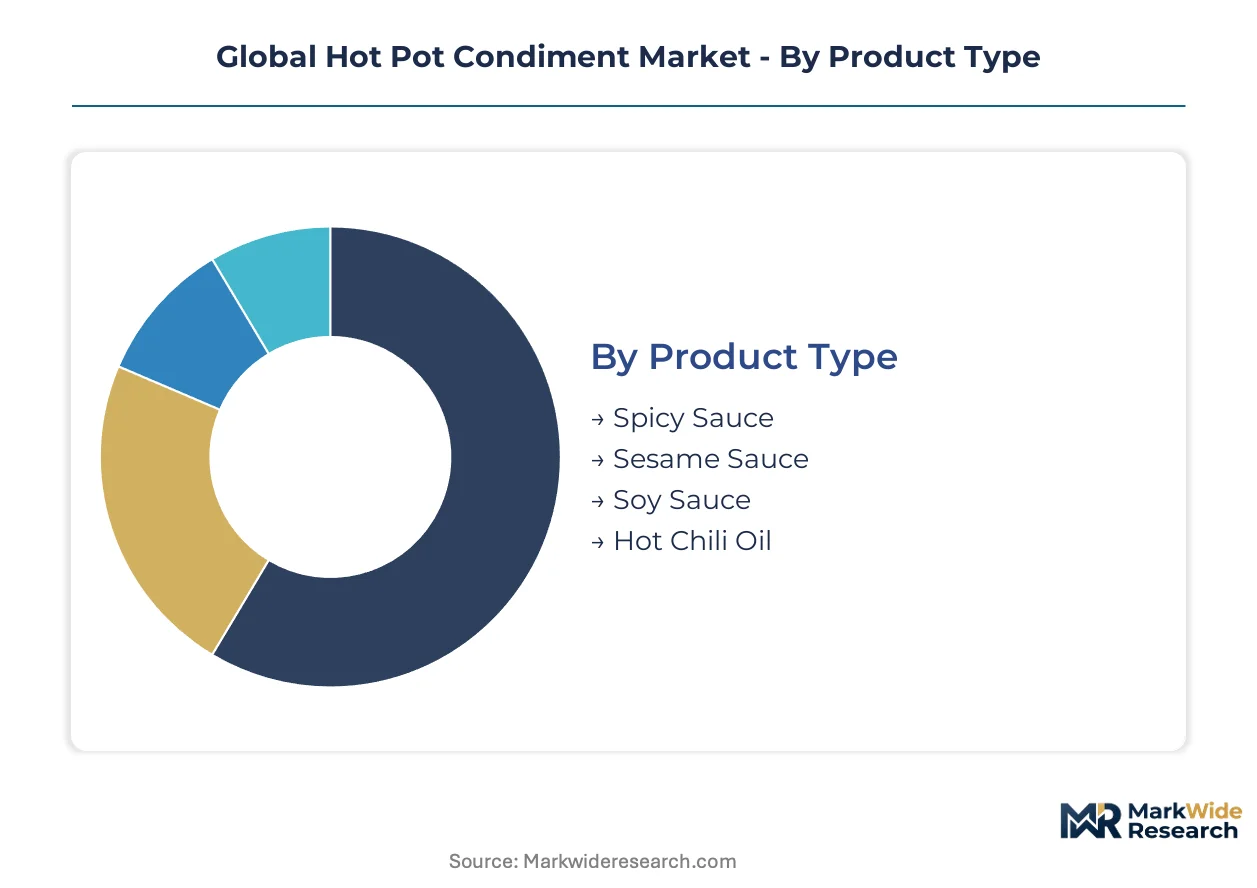
Hot pot condiment segmentation reveals how formulation chemistry, consumption context, and logistics infrastructure interact to shape commercial outcomes. Manufacturers configure product portfolios across multiple axes simultaneously, with packaging and flavor decisions often predetermining channel access and margin structure.
Product Type:
Formulation complexity and raw material processing intensity define competitive positioning within each product category.
- Spicy Sauce:Chili pepper extracts blended with fermented bean pastes and aromatic oils deliver Scoville-calibrated heat levels. Restaurant chains in Chongqing and Sichuan province specify custom heat tiers, while home cooks in coastal China gravitate toward milder, numbing-ma la variants.
- Sesame Sauce:Stone-ground white sesame paste with controlled roasting profiles provides creamy texture and nutty base notes. Automated grinding systems from Japanese equipment suppliers now enable shelf-stable formulations without rancidity acceleration.
- Soy Sauce:Brewed and chemically hydrolyzed variants serve distinct price tiers, with 180-day fermentation cycles commanding premium positioning.
- Hot Chili Oil:Crisp chili flake suspension in heated vegetable oil requires precise temperature control during infusion to prevent acrid off-notes.
Mature deployment sits with Spicy Sauce. Newer deployment is concentrated in Hot Chili Oil.
Flavor Profile:
Palate preference mapping across regional cuisines determines formulation R&D allocation and marketing messaging hierarchy.
- Umami:Disodium inosinate and guanylate amplification of fermented base notes creates depth without sodium overload. This profile dominates retail shelves in Shanghai and Beijing where consumers prioritize complexity over heat intensity.
- Spicy:Capsaicin-forward formulations with Sichuan peppercorn numbing effects anchor interior province consumption. Repeat purchase rates in Chengdu and Wuhan exceed coastal benchmarks by substantial margins.
- Savory:Mushroom and seafood extract fortification targets health-conscious segments seeking reduced sodium alternatives.
- Sweet:Hoisin-derived and caramelized onion bases serve younger demographics and fusion restaurant applications.
Umami and Spicy profiles generate equivalent revenue concentration. Sweet flavor adoption is climbing the fastest among urban millennials.
Packaging Type:
Portion control requirements and shelf-life engineering drive material selection and unit economics divergence.
- Sachet:Multi-layer aluminum laminates provide 12-month oxygen barrier protection for single-serve food service applications. QSR chains in Jakarta and Bangkok specify sachet formats for tabletop condiment caddies.
- Bottle:PET and glass containers with precision-dispensing closures dominate retail pantry stocking. European distributors increasingly mandate post-consumer recycled content thresholds under CSRD packaging rules.
- Jar:Wide-mouth glass with vacuum-sealed metal lids preserves fermented paste integrity across ambient supply chains.
- Pouch:Stand-up flexible packaging with spout fitments enables controlled portion dispensing for family-size meal kits.
Bottle formats command stable volume. Pouch deployment is expanding most quickly through direct-to-consumer subscription channels.
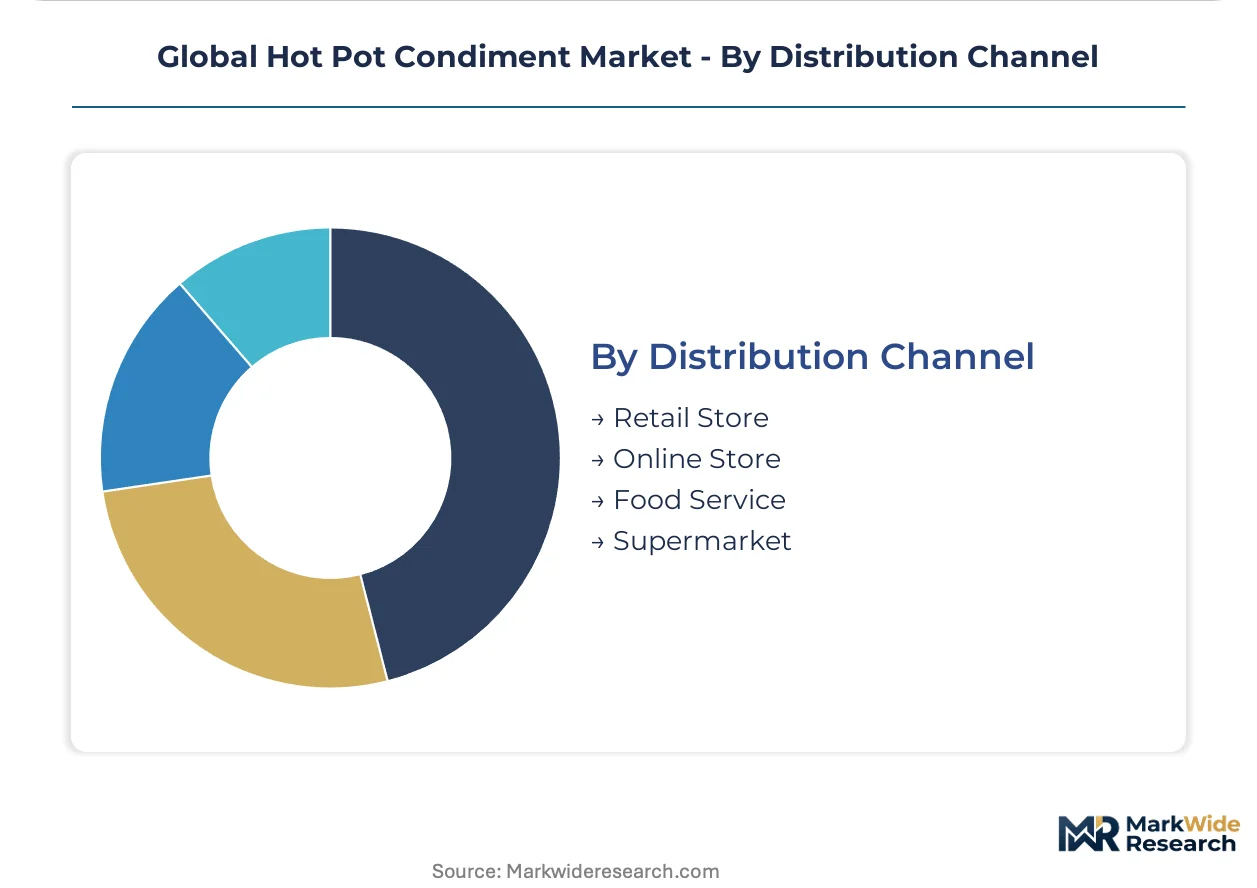
Distribution Channel:
Channel selection constrains permissible packaging formats, payment terms, and promotional investment intensity.
- Food Service:Bulk pails and institutional sachets serve restaurant chains with centralized procurement and standardized recipes. Hai Di Lao's captive supply network demonstrates backward integration advantages at scale.
- Online Store:Subscription bundling and cold-chain logistics enable regional variant discovery for home dining enthusiasts. Tmall and JD.com data feeds inform rapid SKU rotation decisions.
- Retail Store:Convenience store placement requires compact shelf footprints and impulse-oriented packaging graphics.
- Supermarket:Category management negotiations determine end-cap placement and promotional calendar participation.
Food Service and Supermarket channels represent entrenched volume concentration. Online Store penetration is gaining share fastest among coastal province households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of fermented base ingredients while consumption spreads across domestic and export markets. Japan and South Korea import premium chili oils for restaurant chains. Southeast Asian markets are developing localized halal-certified variants.
China
Sichuan and Chongqing provinces drive per-capita consumption intensity through embedded hot pot culture. SAMR enforces GB standards for additive limits and labeling accuracy that favor scaled manufacturers. Chengdu basin facilities cluster fermented soybean paste production, exposing supply chains to flooding risks during monsoon seasons.
Japan
Tokyo and Osaka restaurant chains import Sichuan-style condiments for authentic tabletop dining experiences. METI oversees food import safety assessments and additive approval timelines. Kansai region distributors specialize in premium sesame paste formulations targeting izakaya networks.
United States
Coastal metropolitan areas concentrate Asian diaspora demand for authentic dipping sauces. FDA governs import clearance and allergen disclosure requirements for sauce shipments. Los Angeles and New York City anchor retail distribution networks serving Korean barbecue and Chinese hot pot restaurant clusters.
South Korea
Seoul Capital Area consumers blend imported Sichuan chili oils with domestic gochujang traditions. MFDS regulates capsaicin content thresholds and preservative labeling for imported condiments. Busan-Ulsan logistics hubs handle bulk sauce imports from Chengdu manufacturing zones.
Indonesia
Jakarta and Surabaya restaurant chains are adopting Sichuan-style tabletop dining formats. The national halal certification authority mandates ingredient traceability for fermented paste imports. Surabaya-based distributors are building cold-chain networks for chili oil distribution across Java island.
Global Hot Pot Condiment Market Vendor Landscape
Capital-heavy producers compete with asset-light brand licensors across the condiment value chain. Manufacturing scale concentrates among integrated fermentation facilities with captive raw material sourcing. Three archetypes dominate: restaurant-backed vertical brands, independent sauce specialists, and diversified Asian food conglomerates. Capacity expansion and halal certification acquisition represent the primary competitive vectors.
Within the restaurant-backed tier, Hai Di Lao exemplifies backward integration into captive sauce production. Teway Food Group and Ajinomoto occupy positions as diversified food manufacturers with cross-category fermentation expertise. These three entities represent distinct strategic postures: direct-to-consumer brand extension, multi-format manufacturing scale, and umami science integration respectively.
| Leading Market Players |
|---|
| Hai Di Lao |
| Teway Food Group |
| Yihai |
| Laoganma |
| Inner Mongolia Red Sun |
| Little Sheep |
| Hongjiujiu |
| Ajinomoto |
| Lee Kum Kee |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between halal-certified export tiers and domestic non-certified bases manifests in both pricing premiums and supplier qualification burdens. Manufacturers serving Indonesia's MUI-certified channels absorb traceability documentation costs that commodity-grade producers in Sichuan bypass entirely, compressing margin structures at the premium tier while standard SKUs face raw material volatility.
Pricing Analysis
Margin tightening in standard-grade sesame paste reflects Guizhou chili harvest variability and automated grinding equipment amortization. Three-tier pricing structure across heritage craft, precision-fermented industrial, and commodity chemical-hydrolyzed levels separates buyers by fermentation method and additive disclosure. Price differentiation hinges on GB standard compliance depth and organic certification equivalence. Food service chains in Jakarta demonstrate lowest price sensitivity due to halal certification scarcity, while coastal Chinese home cooks gravitate toward promotional bundling.
Supply Chain Analysis
Halal certification gating by Indonesia's MUI and Malaysia's JAKIM forces ingredient traceability investments that reshape supplier networks. Manufacturing concentrates in China's Sichuan basin, Japan's Kansai region, and South Korea's Chungcheong province. Raw material flows draw from Henan chili cooperatives, Hokkaido sesame processors, and Indonesian palm oil estates. Single-source vulnerability sits with Chengdu basin doubanjiang facilities during monsoon flooding. Distribution runs through cold-chain logistics networks for fermented paste integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is displacing traditional apprenticeship-dependent production methods, compressing development cycles while preserving heritage flavor profiles previously requiring decades of craft accumulation.
For Market Incumbents: Lock in captive sesame sourcing from Hokkaido and Henan through multi-year offtake agreements before climate volatility accelerates. Defend position by deepening backward integration into chili oil extraction and AI-driven flavor profiling capabilities that emerging challengers lack. Prioritize dual organic certification pipelines to preempt EU CSRD packaging traceability mandates.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription bundles featuring rotating Sichuan regional variants to bypass entrenched retail shelf negotiations. Target Indonesia's nascent halal-certified hot pot restaurant segment where MUI documentation barriers filter out commodity competitors. Anchor initial positioning on precision-fermented consistency claims that heritage brands cannot match.
For Investors and Strategic Acquirers: Re-rating potential sits with precision-fermentation-enabled mid-tier manufacturers given AI flavor profiling scalability and carbon disclosure compliance advantages. Long-term viability favors facilities with automated grinding systems and domestic biopolymer packaging supplier relationships. Watch for MUI halal certification backlog clearance as inflection signal for Indonesia market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Machine learning-controlled aging environments standardize umami intensity without master fermenter dependency. |
| Halal Certification Pathway Investment | MUI traceability compliance unlocks Jakarta and Surabaya restaurant chain procurement pipelines. |
| Biopolymer Packaging Transition | CSRD mechanical recyclability mandates reshape EU-bound sachet and jar material specifications. |
| Direct-to-Consumer Subscription Launch | Cold-chain logistics enable regional variant discovery beyond traditional retail shelf constraints. |
| Backward Integration into Chili Sourcing | Henan and Guizhou growing region contracts buffer harvest volatility for spicy sauce formulations. |
Methodological Framework
Multi-period observation of fermentation technology adoption rates and halal certification issuance timelines anchored the trend analysis, supplemented by interviews with condiment manufacturing executives, regulatory affairs specialists at SAMR and MUI, restaurant chain procurement directors, and cold-chain logistics operators. Secondary validation drew from NMPA GB standard filings, Indonesia's halal certification registry, Japanese sesame import statistics, and EU CSRD packaging disclosure drafts. Bottom-up SKU volume aggregation and top-down market sizing triangulated segment-level estimates.
Input-output matrices mapped chili pepper harvest volumes, fermentation facility capacity utilization, and subscription channel growth trajectories across the projection horizon. Segmentation dimensions modeled include product formulation chemistry, flavor profile intensity, packaging material specifications, and distribution channel access tier. CAGRs derived from trend extrapolation of precision fermentation equipment deployment and halal certification pipeline clearance rates.
Climate-driven chili harvest disruption, MUI certification timeline delays, and EFSA pyrazine compound reassessment outcomes are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in CSRD packaging recycled content thresholds or SAMR additive limit amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Low Calorie Peanut Sauce Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Ketchup Concentrates Market