
 Organic Condiments Market | 2026-2036
Organic Condiments Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Condiments Market Analytics
Culinary formulation talent is rotating toward clean-label expertise as brands race to replace synthetic stabilizers with plant-based alternatives. Hain Celestial Group leverages its portfolio breadth to sustain refrigerated organic condiment lines across North American retail. Sir Kensington's differentiates through egg-free mayonnaise formulations that occupy the premium vegan slot in conventional grocery. Primal Kitchen specializes in avocado-oil-based dressings that control the paleo and keto consumer segments.
Organic condiments comprise shelf-stable and refrigerated flavor-enhancement products manufactured without synthetic pesticides, genetically modified organisms, or artificial preservatives, typically bearing third-party organic certification and achieving minimum ninety-five percent organic ingredient content by weight. Hot sauce and salad dressing command the widest margin pools as consumers trade up toward functional ingredients such as fermented peppers and cold-pressed oils. Ketchup remains the volume anchor in supermarkets, though pouches and single-serve tubs in foodservice channels represent the fastest-growing packaging configuration for away-from-home consumption.
The USDA National Organic Program and FDA food labeling standards govern ingredient declarations and organic seal usage across American supply chains, while the EPA regulates pesticide residue thresholds for raw agricultural inputs entering condiment production. Stakeholders must monitor evolving state-level packaging waste regulations and organic integrity enforcement actions that will reshape sourcing qualifications and label claims.
Market Dynamics
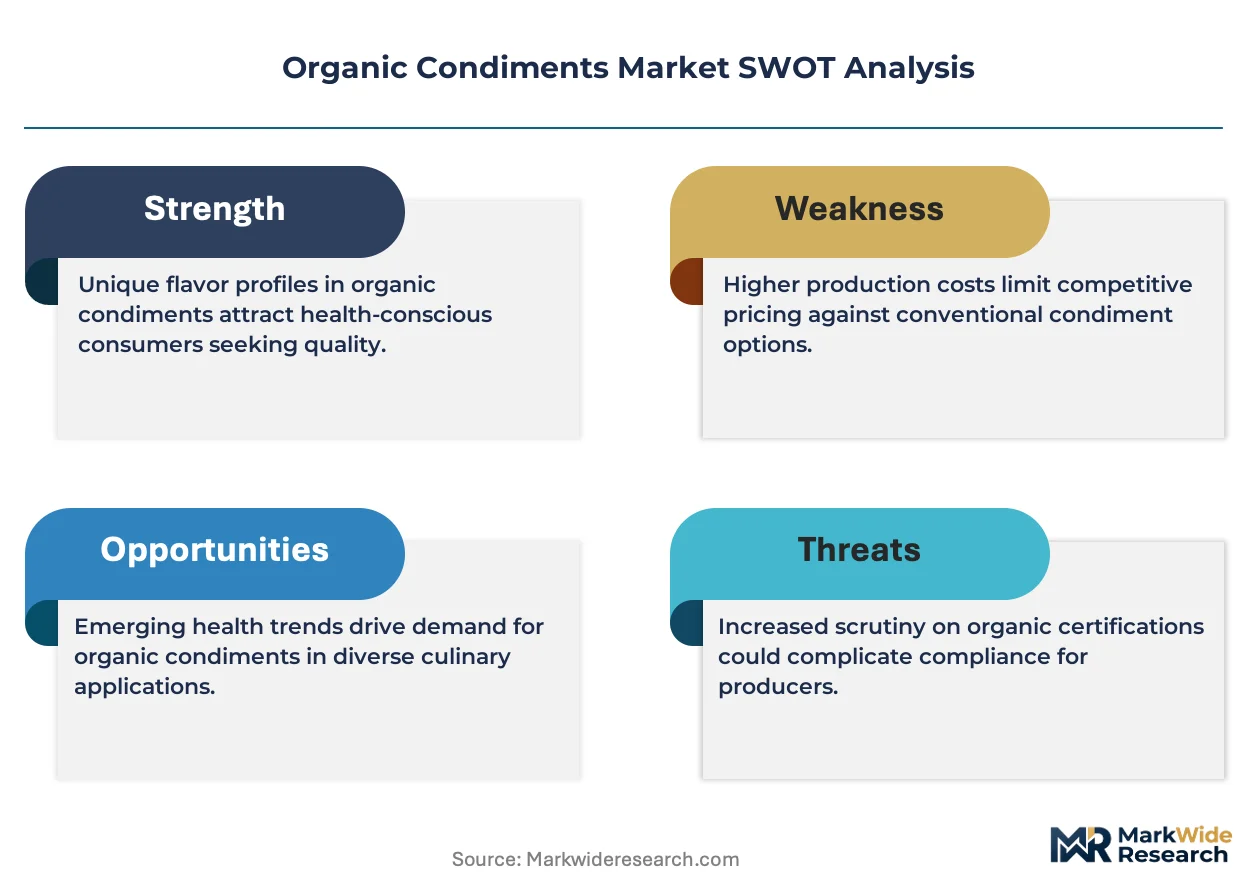
USDA organic certification tightening is forcing condiment manufacturers to rebuild supply chains around ingredient traceability, squeezing mid-tier brands that lack backward integration into organic agriculture.
Growth Catalysts
- Clean-label formulation technology:Plant-based stabilizers and fermentation-derived preservatives now replace synthetic additives in premium ketchup and hot sauce lines, satisfying retailer clean-shelf policies without shelf-life sacrifice.
- Farm-to-bottle network maturation:United States supply infrastructure for organic tomatoes, peppers, and vinegar has achieved sufficient scale to support national distribution of refrigerated organic condiment SKUs.
- EU Green Deal agricultural transition:European Union subsidies for organic farming are expanding raw material availability for condiment processors seeking dual USDA-EU organic certification.
Market Restraints
- Organic input cost volatility:Cold-pressed avocado oil and fermented pepper mash prices swing with climate-affected harvests in Mexico and California, compressing margin on premium mayonnaise and hot sauce lines.
- Single-source supply concentration:Organic vinegar production clusters in Modena, Italy and Jerez, Spain, creating geographic chokepoints for salad dressing manufacturers dependent on aged balsamic or sherry vinegar inputs.
- Substitution threat from conventional premium:Non-organic condiments bearing "natural" claims capture price-sensitive consumers in conventional grocery, limiting organic penetration in mid-market retail tiers.
Strategic Opportunities
- Foodservice single-serve expansion:Pouched organic ketchup and portion-control hot sauce tubs penetrate institutional catering and quick-service channels previously dominated by conventional bulk formats.
- Keto-paleo functional positioning:Avocado-oil-based dressings and sugar-free fermented sauces command shelf space in specialty diet sets, creating premium pricing power beyond organic certification alone.
- State-level packaging waste mandates:California and New York extended producer responsibility laws are accelerating compostable and recyclable packaging adoption, rewarding early movers with retailer preferred-vendor status.
Industry Challenges
- Clean-label formulation expertise scarcity:Food scientists capable of replacing xanthan gum and synthetic acids with fermented starches and fruit pectins command premium salaries, constraining R&D bandwidth at emerging brands.
- Dual certification timeline compression:Simultaneous USDA organic and Non-GMO Project verification requires 12-18 month ingredient qualification cycles, delaying new product launches against faster conventional competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Condiments Market |
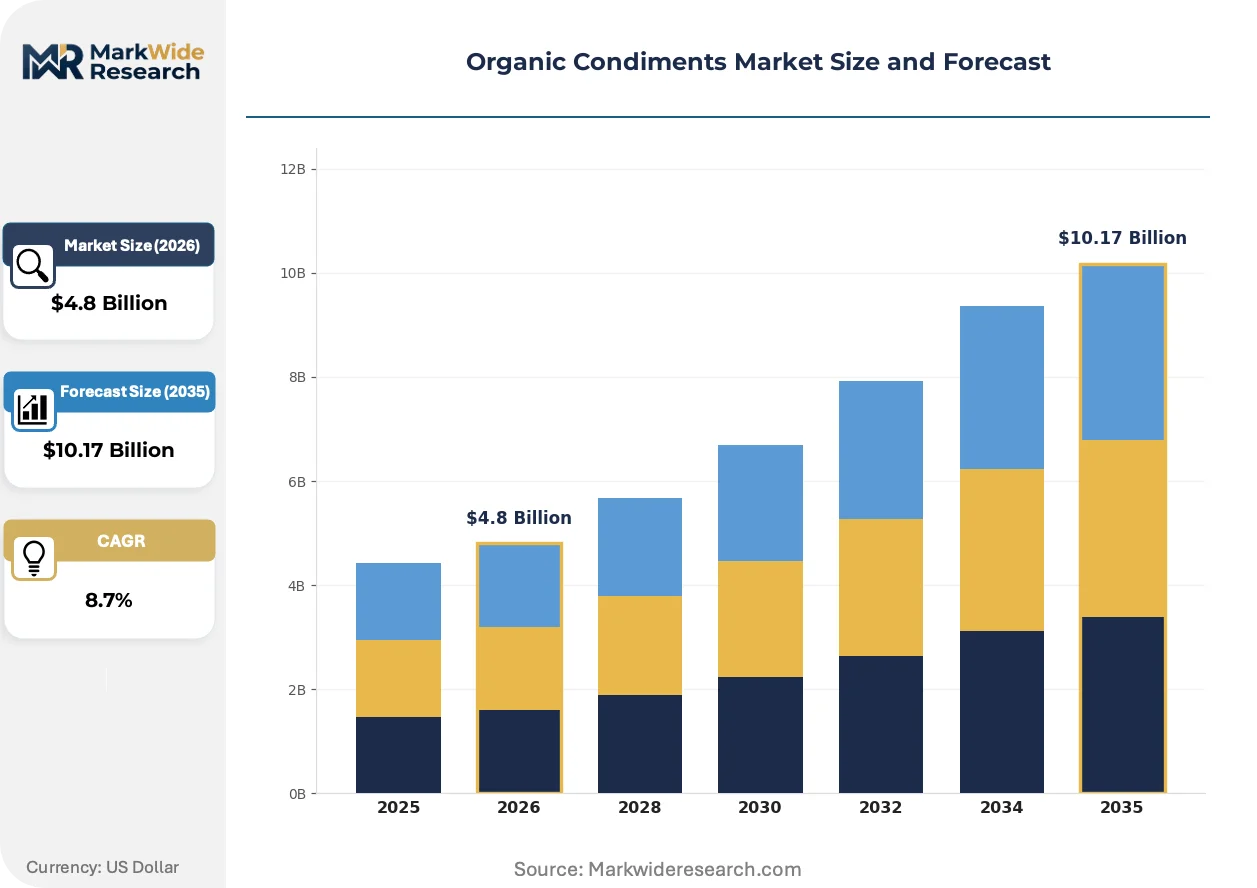
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Sauce, Ketchup, Mustard, Salad Dressing Ingredient Type: Herbs, Spices, Vinegar, Fruits Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales Packaging Type: Bottles, Jars, Pouches, Tubs |
| Companies Covered | Hain Celestial Group, Annie's Homegrown, Sir Kensington's, Primal Kitchen, Spectrum Organic Products, Organicville, Simply Organic, The Kraft Heinz Company, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Condiments Market Evolving Landscape
Fermentation technology and packaging material science are reshaping how organic condiments achieve shelf stability and environmental compliance without synthetic inputs.
High-pressure processing is bifurcating the refrigerated condiment segment from legacy pasteurized products. Clean-label brands in the natural channel have adopted HPP for organic mayonnaise and fresh salsa, eliminating thermal degradation of flavor compounds. This technology is compressing the shelf-life gap between refrigerated and shelf-stable formats, forcing conventional processors to defend position through price reduction.
REACH chemical restriction expansions are compelling European condiment manufacturers to reformulate around bio-based preservatives. The European Chemicals Agency's updated authorization lists have restricted several synthetic antimicrobials common in conventional sauces. Salad dressing producers serving EU export markets are accelerating vinegar fermentation and cultured dextrose adoption to maintain clean-label positioning.
Direct-to-subscription purchasing is fragmenting traditional grocery channel dominance for premium organic condiments. Specialty diet consumers in the United States and United Kingdom now replenish avocado-oil mayonnaise and sugar-free ketchup through curated monthly boxes. This channel shift is most visible among paleo and keto adherents who prioritize ingredient transparency over immediate retail availability.
Organic Condiments Market Segmentation
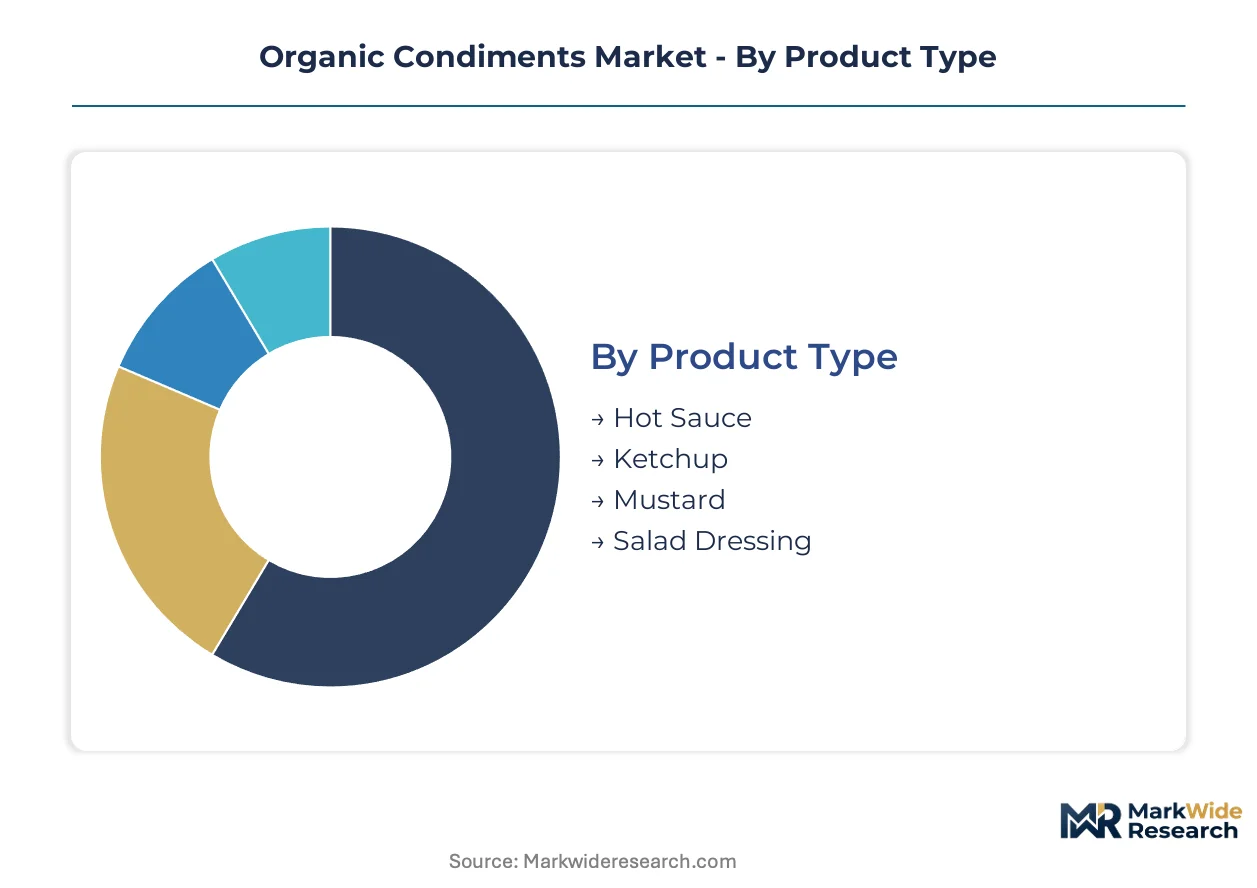
Organic condiment manufacturers navigate divergent margin profiles across product formats and channel structures. Segmentation reveals where refrigerated premium lines command pricing power versus shelf-stable volume plays, and which packaging innovations unlock foodservice penetration.
Product Type:
Domestic production concentrates on ketchup and mustard for North American grocery dominance, while hot sauce and salad dressing lines increasingly target export markets seeking functional ingredient positioning.
- Hot Sauce:Fermented pepper mashes and cold-pressed oil infusions define premium formulations. Export demand from United Kingdom and German specialty retailers drives small-batch artisanal production, constrained by climate volatility in Mexican and California pepper harvests.
- Ketchup:Tomato-based formulations with minimum ninety-five percent organic content anchor supermarket volume. United States farm-to-bottle networks in California and Florida supply national retail, though pouched single-serve formats now penetrate quick-service foodservice channels.
- Mustard:Seed-based varieties rely on Canadian and Montana organic mustard seed cultivation. The segment serves established deli and sandwich applications with limited innovation velocity compared to fermented sauce categories.
- Salad Dressing:Avocado-oil and cold-pressed vinegar formulations command paleo and keto consumer loyalty. Refrigerated SKUs require HPP technology investment, compressing participation to brands with capital for high-pressure processing infrastructure.
Ketchup commands the established base. The steepest expansion runs through hot sauce.
Ingredient Type:
Cost tier stratification separates commodity herb and spice inputs from premium fermented vinegar and fruit concentrates that justify organic certification price premiums.
- Herbs:Basil, oregano, and cilantro cultivation clusters in California's Central Valley and Mexico's organic greenhouse operations. Supply contracts with dried herb processors determine year-round availability for sauce manufacturers.
- Spices:Organic black pepper, turmeric, and paprika sourcing extends to Kerala, India and Kampot, Cambodia. Traceability documentation for USDA organic certification adds procurement complexity versus conventional spice trade.
- Vinegar:Aged balsamic from Modena and sherry vinegar from Jerez create geographic chokepoints for premium dressing producers. Domestic apple cider vinegar fermentation in Vermont and Washington offers supply diversification for mid-tier brands.
- Fruits:Organic tomato paste, date syrup, and citrus concentrates provide sweetness and body without synthetic additives. California's drought exposure elevates price volatility for tomato-dependent ketchup manufacturers.
Vinegar anchors premium positioning. The steepest expansion trajectory belongs to fruit-based clean-label sweeteners.
Distribution Channel:
Volume scale concentrates in supermarket retail, while margin capture and customer data ownership increasingly shift toward direct and digital channels.
- Supermarkets:Conventional grocery chains dominate ketchup and mustard velocity through center-store placement. Clean-shelf policies at Kroger and Albertsons now mandate organic certification for premium condiment facings.
- Online Retail:Amazon and Thrive Market subscription models capture paleo and keto adherents seeking ingredient transparency. Direct-to-consumer replenishment bypasses slotting fee structures that burden emerging brands in brick-and-mortar.
- Specialty Stores:Whole Foods and Sprouts Farmers Market curate refrigerated organic condiment sets with local and regional producer inclusion. These channels reward small-batch fermentation stories and transparent supply chain narratives.
- Direct Sales:Farmers market presence and restaurant supply relationships build brand authenticity before retail expansion. Foodservice penetration through independent chef networks validates formulation quality for subsequent grocery negotiation.
Supermarkets retain volume leadership. Direct sales channels are climbing the fastest for premium brand building.
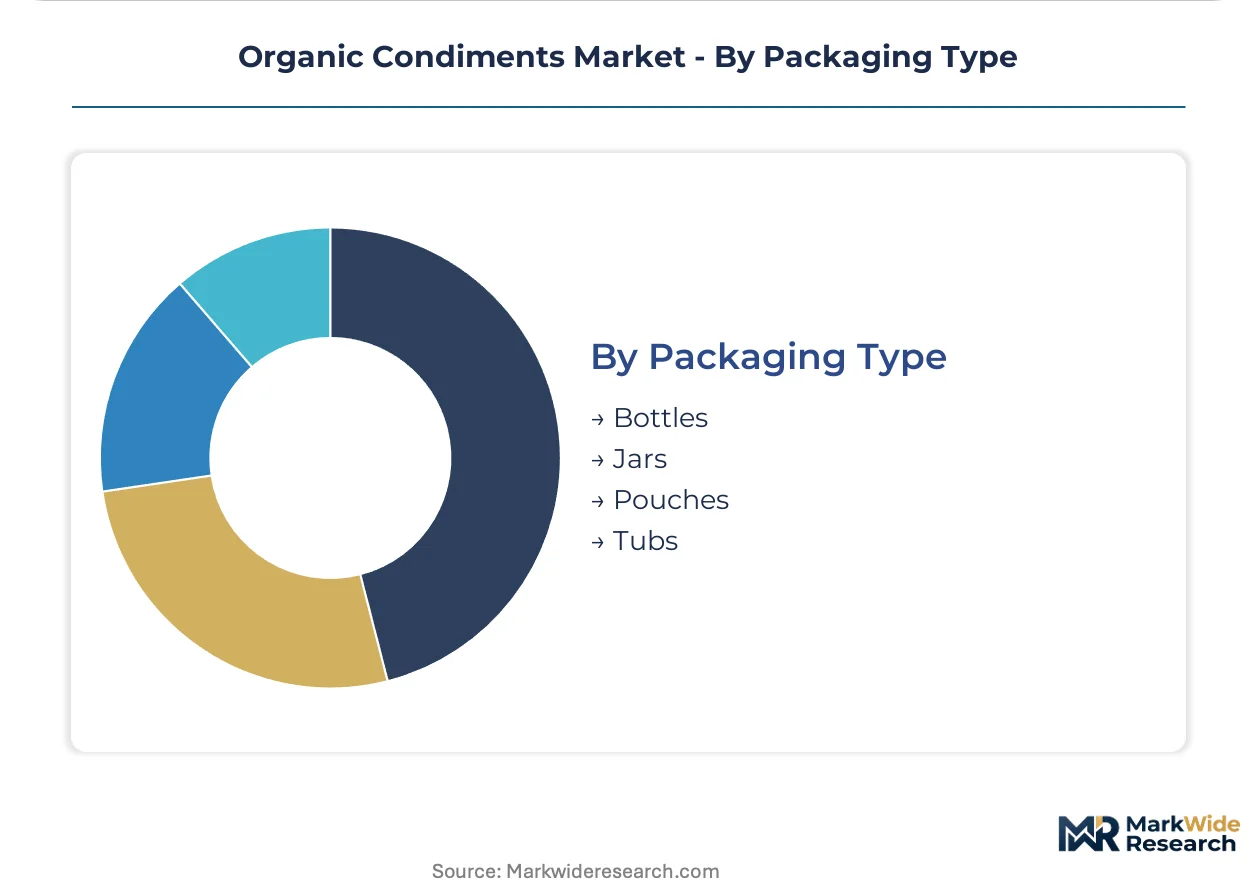
Packaging Type:
Material science investment separates sustainable packaging adopters from conventional formats as California and New York extended producer responsibility laws reshape supplier qualifications.
- Bottles:Glass and recycled PET containers dominate retail ketchup and hot sauce presentation. Lightweighting initiatives reduce freight cost but must maintain shelf stability for vinegar-based formulations.
- Jars:Wide-mouth glass formats suit mayonnaise and thick dressing textures requiring spoon access. Refrigerated distribution requirements limit jar adoption to brands with cold-chain logistics partnerships.
- Pouches:Flexible film formats reduce material weight and enable foodservice single-serve portioning. Quick-service chains in United States institutional catering now specify organic ketchup pouches for away-from-home consumption.
- Tubs:Deli-style containers serve foodservice bulk requirements and club store multi-serve retail. Compostable tub materials from molded fiber or PLA bioplastics attract retailer preferred-vendor status under state packaging mandates.
Bottles hold the established retail position. Pouches are gaining share fastest through foodservice channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic certification requirements anchor North American market development, while EU Green Deal subsidies reshape European raw material availability. Farm-to-bottle infrastructure maturity varies sharply by geography.
United States
California and Florida organic tomato cultivation supplies national ketchup manufacturing. The USDA National Organic Program tightened traceability mandates for ingredient sourcing. HPP technology adoption clusters in refrigerated condiment processing facilities across the Pacific Northwest and Northeast corridor.
Germany
Specialty retailers in Berlin and Munich expanded shelf space for fermented hot sauce imports. The EU Green Deal agricultural transition subsidies support domestic organic pepper cultivation. Modena-sourced aged balsamic vinegar flows through Hamburg distribution hubs for premium dressing manufacturers.
United Kingdom
Paleo and keto diet adherence drives direct-to-subscription purchasing of avocado-oil mayonnaise. ECHA REACH chemical restrictions accelerate bio-based preservative reformulation. London-based specialty food distributors curate small-batch fermentation brands for national retail placement.
Italy
Modena's concentrated organic vinegar production creates geographic chokepoints for aged balsamic supply. EU organic certification alignment with USDA standards enables dual-certified export production. Emilia-Romagna processing facilities supply premium vinegar inputs to multinational dressing manufacturers.
Canada
Organic mustard seed cultivation in Saskatchewan and Alberta supports domestic condiment manufacturing. Health Canada organic labeling standards align with USDA equivalency agreements. Toronto and Vancouver retail chains mandate organic certification for premium condiment facings under clean-shelf policies.
Organic Condiments Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with refrigerated HPP-equipped specialists commanding premium pricing against shelf-stable volume producers. The market structure tiers across portfolio conglomerates, clean-label specialists, and emerging fermentation-focused brands. Strategic archetypes include backward-integrated organic agriculture players, formulation technology licensors, and direct-to-consumer subscription operators. Dominant competitive moves center on farm-to-bottle supply chain construction and dual USDA-EU organic certification acquisition.
Within the clean-label specialist tier, Sir Kensington's and Primal Kitchen exemplify premium positioning through ingredient-driven differentiation, while Hain Celestial Group anchors the portfolio-scale archetype with refrigerated line breadth across North American retail. These three occupy positions that reflect divergent bets on technology investment versus brand narrative construction.
| Leading Market Players |
|---|
| Hain Celestial Group |
| Annie's Homegrown |
| Sir Kensington's |
| Primal Kitchen |
| Spectrum Organic Products |
| Organicville |
| Simply Organic |
| The Kraft Heinz Company |
| General Mills |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month dual certification timelines compress new product launch windows while simultaneously anchoring premium pricing tiers to verified organic provenance. This lead-time rigidity reinforces Modena vinegar and California tomato suppliers as gatekeepers for margin capture across refrigerated and shelf-stable formats.
Pricing Analysis
Modena-sourced aged balsamic commands a 40-60% premium over domestic apple cider vinegar alternatives, creating geographic price stratification that permeates finished dressing retail. Three-tier pricing structure across premium HPP-refrigerated, certified-organic shelf-stable, and conventional natural tiers separates Primal Kitchen's avocado-oil positioning from mid-market organic facings and price-driven conventional alternatives. Cost compression in mid-tier ketchup stems from drought-driven California organic tomato paste volatility. Quick-service foodservice buyers exhibit highest price sensitivity, while paleo and keto direct-subscription consumers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Modena's concentrated aged balsamic production and Jerez sherry vinegar aging create geographic chokepoints that constrain premium salad dressing output regardless of downstream demand. Organic tomato paste draws from California Central Valley and Florida farm-to-bottle networks, while fermented pepper mash sources cluster in Mexico and California. Single-source vulnerability concentrates in Italian and Spanish vinegar inputs subject to EU agricultural policy shifts. Distribution runs through national retail grocery chains, specialty natural channel distributors, and direct-to-consumer subscription platforms with divergent margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic condiments sector is recovering from input cost cyclicality as California drought conditions ease and EU Green Deal subsidies expand European raw material availability.
For Market Incumbents: Compound defensive positioning through backward integration into organic tomato and pepper cultivation in California and Florida, securing supply against climate-driven harvest volatility. Accelerate HPP technology deployment across refrigerated mayonnaise and dressing lines to compress shelf-life gaps with conventional pasteurized alternatives. Prioritize dual USDA-EU organic certification acquisition to preempt competitor access to German and United Kingdom specialty retail expansion. For New Entrants and Emerging Players: Anchor in foodservice single-serve pouch formats where institutional catering procurement standards are shifting toward organic specification without entrenched incumbent relationships. Target quick-service chain pilot programs for portion-control ketchup and hot sauce tubs as the most penetrable white-space segment. Build brand authenticity through farmers market presence and independent chef network validation before negotiating supermarket slotting fee structures. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent companies seeking portfolio simplification, particularly refrigerated condiment lines lacking scale alignment with core shelf-stable priorities. Mid-cap fermentation-focused specialists with established Modena vinegar supply contracts and HPP infrastructure represent highest long-term viability within a 5-10 year organic certification tightening trajectory. Monitor USDA enforcement action intensity as the critical inflection signal for accelerated supply chain restructuring and acquisition opportunity generation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous USDA and EU organic qualification unlocks German and United Kingdom retail placement. |
| HPP Infrastructure Deployment | High-pressure processing adoption bridges shelf-life gaps between refrigerated and shelf-stable formats. |
| Foodservice Pouch Expansion | Single-serve organic ketchup and hot sauce formats penetrate institutional catering previously dominated by conventional bulk. |
| Backward Integration | In-house organic tomato and pepper cultivation mitigates California drought-driven input cost volatility. |
| Direct-to-Subscription Channel | Paleo and keto consumer subscription models bypass brick-and-mortar slotting fee burdens. |
Research Methodology
A standing panel of brand managers at organic condiment manufacturers, category buyers at national grocery chains, fermentation technology R&D directors, and supply chain planners at vinegar processors provided ongoing calibration throughout the study. Primary interview findings combined with secondary validation from USDA National Organic Program enforcement records, FDA food labeling guidance documents, EU Green Deal agricultural subsidy disclosures, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, ingredient tier, distribution channel structure, packaging format, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of historical organic certification penetration rates cross-referenced with farm-to-bottle infrastructure buildout timelines. Forecast inputs incorporated HPP technology adoption curves and state-level extended producer responsibility law implementation schedules.
Material uncertainties — climate-driven organic harvest volatility, USDA enforcement intensity shifts, and EU-UK organic equivalency agreement revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline stability and foodservice channel conversion rates. Practitioners should keep alternative scenarios live as California water allocation policies and EU agricultural subsidy frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Asia-Pacific Condiments Market