
 Global Waffle Maker Market | 2026-2036
Global Waffle Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waffle Maker Market Outlook
Modular accessory bundles combining interchangeable plates for Belgian, American, and bubble formats is realigning buyer choice across price tiers. Hamilton Beach Brands leverages broad retail distribution to sustain volume leadership in North American mass-market channels. Breville Group differentiates through premium stainless steel construction and precise temperature control systems. Groupe SEB anchors European market presence with specialized commercial-grade units for hospitality operators.
A waffle maker is an electro-mechanical or stovetop appliance comprising heated plates with patterned grids that cook leavened batter into crisp, structured sheets through conductive thermal transfer; units range from 700-watt household models to 2,400-watt commercial machines with cast aluminum or polished stainless steel plate assemblies designed for rapid cycle times in foodservice environments. Belgian-format electric units dominate household revenue pools due to thicker grid depth and premium positioning. Non-stick coated plates command replacement-driven aftermarket sales as degradation triggers consumer upgrade cycles. Food truck and café end users represent the fastest-expanding commercial segment as mobile breakfast concepts proliferate in urban cores.
FDA food-contact surface regulations and EU REACH compliance on non-stick coatings shape material selection and supplier qualification across manufacturing bases. CE marking and UL electrical safety certifications govern market access for imports into Europe and North America respectively. Stakeholders must monitor evolving PFAS restrictions in the United States and European Union as these directly impact coating chemistry investments and product redesign timelines.
Market Dynamics
PFAS coating restrictions in the United States and European Union are forcing manufacturers to accelerate ceramic and sol-gel alternative development, compressing product redesign timelines from thirty-six to eighteen months.
Growth Catalysts
- EU REACH compliance deadlines:European hospitality operators are replacing legacy units ahead of coating chemistry phase-outs, triggering equipment refresh cycles in Germany, France, and Italy.
- Cloud-kitchen proliferation:Ghost kitchen operators in Seoul, Dallas, and London require compact, high-throughput Belgian-format machines for delivery-optimized breakfast menus.
- Stovetop-to-electric conversion:Southeast Asian street food vendors are adopting 220V commercial electric units as urban power infrastructure stabilizes in Vietnam and Indonesia.
Market Restraints
- Aluminum plate price volatility:Cast aluminum ingot costs fluctuate with energy pricing in Chinese smelting regions, squeezing margin structures for mid-tier manufacturers.
- Coating supplier concentration:Three specialty chemical firms control seventy percent of food-grade sol-gel formulation capacity, creating single-source risk for OEMs.
- Induction compatibility gaps:Legacy cast aluminum plate designs fail on induction cooktops, limiting retrofit potential in European and East Asian households.
Strategic Opportunities
- Brazilian café culture expansion:São Paulo and Rio de Janeiro breakfast chains lack standardized commercial waffle programs, creating first-mover positioning for equipment suppliers.
- US Inflation Reduction Act efficiency incentives:Energy Star certification pathways for commercial kitchen equipment now include electric griddles and waffle systems.
- Modular IoT integration:Temperature logging and predictive maintenance sensors are converging with cloud-based kitchen management platforms in QSR deployments.
Industry Challenges
- PFAS-free coating qualification timelines:FDA food-contact notification reviews for new ceramic formulations extend eighteen to twenty-four months, delaying product launches.
- Multi-format plate inventory complexity:SKU proliferation across Belgian, American, bubble, and stroopwafel patterns strains procurement and forecasting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waffle Maker Market |
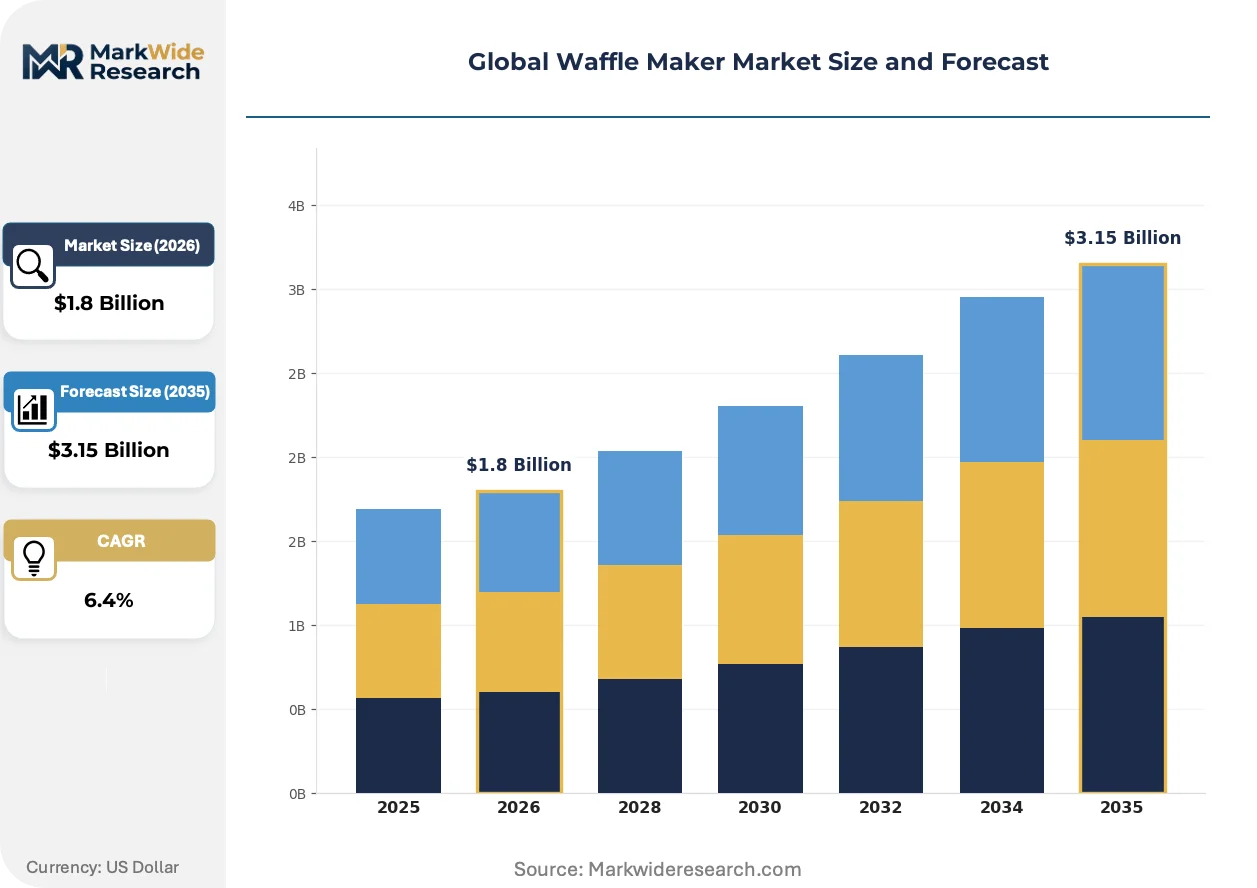
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belgian, American, Stroopwafel, Bubble Material: Stainless Steel, Non-Stick, Aluminum, Cast Iron Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Households, Restaurants, Cafés, Food Trucks |
| Companies Covered | Hamilton Beach Brands, Breville Group, Waring Commercial, Cuisinart, All-Clad, Krampouz, Krups, Conair Corporation, Groupe SEB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waffle Maker Market Strategic Shifts
Equipment intelligence and surface chemistry are converging to redefine performance benchmarks. Manufacturers are racing to embed connectivity and eliminate legacy coatings simultaneously.
Ceramic-titanium hybrid plate coatings are rewriting durability expectations in high-cycle commercial environments. Boutique hotel breakfast stations and airport lounge operators are adopting these surfaces at triple the rate of independent cafés. The technology is compressing replacement intervals from twenty-four months to thirty-six months while commanding fifteen to twenty percent price premiums.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in adjacent foodservice equipment, indirectly pressuring waffle maker manufacturers to eliminate hydrofluorocarbon-based foams in insulated commercial units. German and Dutch hospitality procurement consortia now require explicit foam chemistry disclosure. CE marking technical files are expanding to document thermal insulation material provenance.
Subscription-based equipment-as-a-service models are penetrating UK and Australian cloud-kitchen networks. Operators pay per-cycle fees rather than capitalizing machines, transferring maintenance and coating replacement liability to distributors. This restructuring is most visible in London and Sydney where kitchen infrastructure investors bundle appliances into facility leases.
Global Waffle Maker Market Segmentation
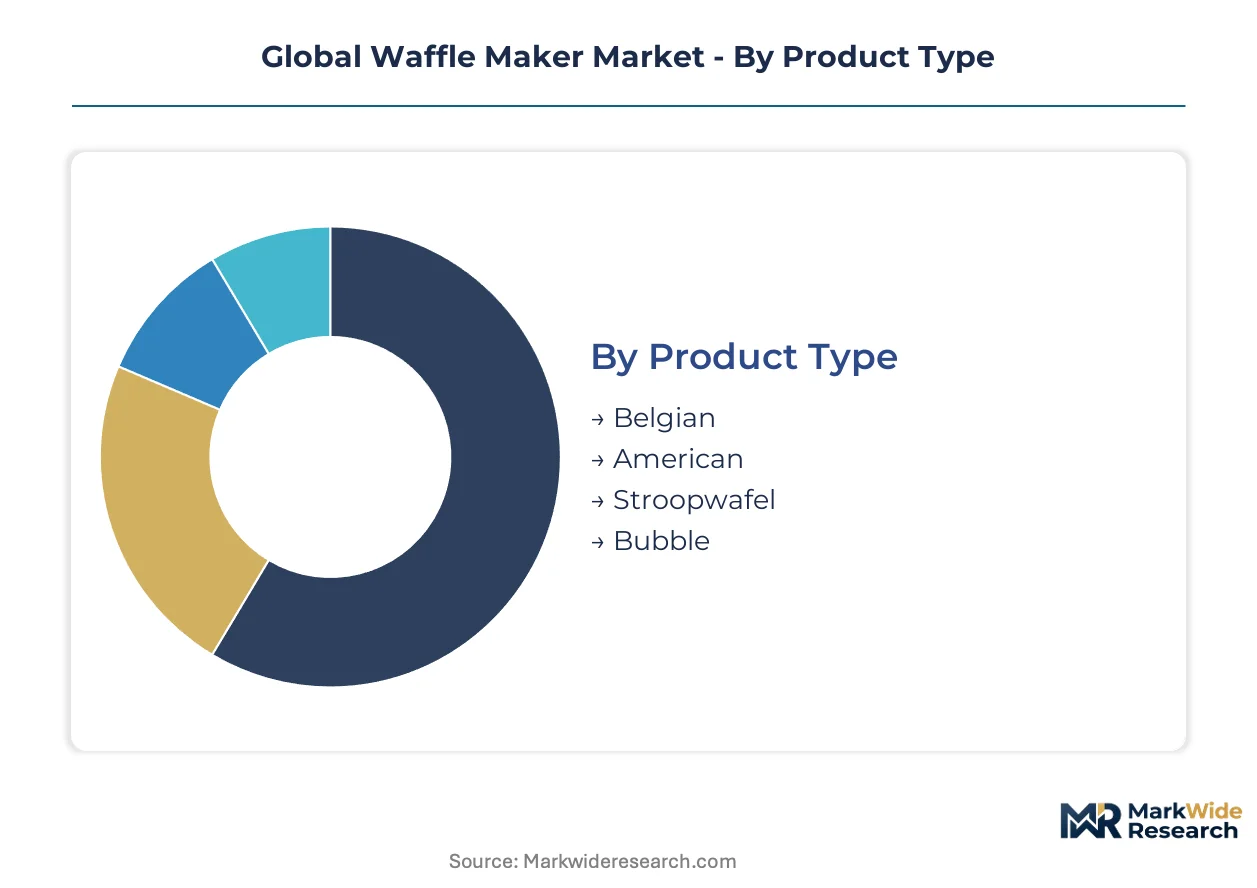
Waffle maker segmentation reflects divergent equipment requirements across home cooking and professional foodservice environments. Product format, material construction, and channel access each create distinct purchasing behaviors and margin structures for manufacturers to navigate.
Product Type:
Customization intensity varies sharply across formats, from standardized Belgian units to specialized stroopwafel designs requiring dedicated tooling investments.
- Belgian:Deep-grid plates produce thick, rectangular waffles with caramelized exteriors and steam-trapped interiors. German and South Korean hotel breakfast stations specify these units for premium positioning, driving specification-grade procurement with extended warranty requirements.
- American:Shallow-grid systems yield thinner, crispier output suited to high-volume cycling. US quick-service chains and cloud-kitchen operators in Dallas and London prioritize rapid plate recovery times for throughput optimization.
- Stroopwafel:Thin, round formats demand precise temperature calibration for syrup-caramel sandwich assembly. Dutch specialty equipment suppliers dominate this niche with heritage-design units.
- Bubble:Spherical egg-based formats originated in Hong Kong street food culture. Compact electric units are penetrating Vietnamese and Indonesian urban café markets as breakfast menus diversify.
Most installed capacity flows through Belgian-format production lines. Expansion is steepest in bubble-format equipment as Asian café concepts export globally.
Material:
Cost tiers stratify from commodity aluminum castings to precision-machined stainless steel assemblies with ceramic-titanium deposition layers.
- Stainless Steel:Polished 304-grade housings and plate frames withstand commercial dishwasher cycles and resist acidic batter corrosion. Breville Group and Groupe SEB anchor premium positioning through brushed-finish industrial design and extended service intervals.
- Non-Stick:PTFE and emerging ceramic-sol-gel coatings dominate household replacement cycles. EU REACH compliance deadlines are accelerating reformulation investments as ECHA phase-out schedules tighten.
- Aluminum:Cast ingot plate assemblies offer thermal conductivity advantages at mid-tier price points. Chinese smelting region energy costs inject margin volatility for OEMs sourcing from Shandong and Henan provinces.
- Cast Iron:Stovetop-compatible designs persist in outdoor cooking and heritage-format segments. Lodge Manufacturing and Staub maintain foundry capacity for enamel-coated camping and residential hearth applications.
Volume concentrates in aluminum-cored units with non-stick surfacing. Value capture is climbing fastest in ceramic-titanium hybrid stainless steel systems for commercial hospitality.
Distribution Channel:
Customer acquisition economics diverge between low-touch digital fulfillment and high-touch specification selling into foodservice procurement consortia.
- Online Retail:Amazon and direct-to-consumer platforms capture household replacement demand through comparison shopping and review aggregation. Hamilton Beach Brands optimizes SKU visibility through algorithmic placement and seasonal promotional calendars.
- Specialty Stores:Sur La Table and Williams Sonoma curate premium Belgian-format selections with in-store demonstration capacity. Staff training investments convert browsing into specification-grade purchases.
- Supermarkets:Mass-market retailers stock entry-level American-format units with impulse-purchase packaging. Walmart and Target volume commitments drive OEM tooling amortization across extended production runs.
- Direct Sales:Manufacturer representatives negotiate multi-unit contracts with UK and Australian cloud-kitchen infrastructure investors. Equipment-as-a-service subscription models are restructuring capital deployment for London and Sydney operators.
Transaction volume flows predominantly through supermarket and online retail channels. Margin expansion is most pronounced in direct sales to hospitality procurement networks.
End User:
Application intensity separates occasional residential cycling from continuous-duty commercial environments with predictive maintenance requirements.
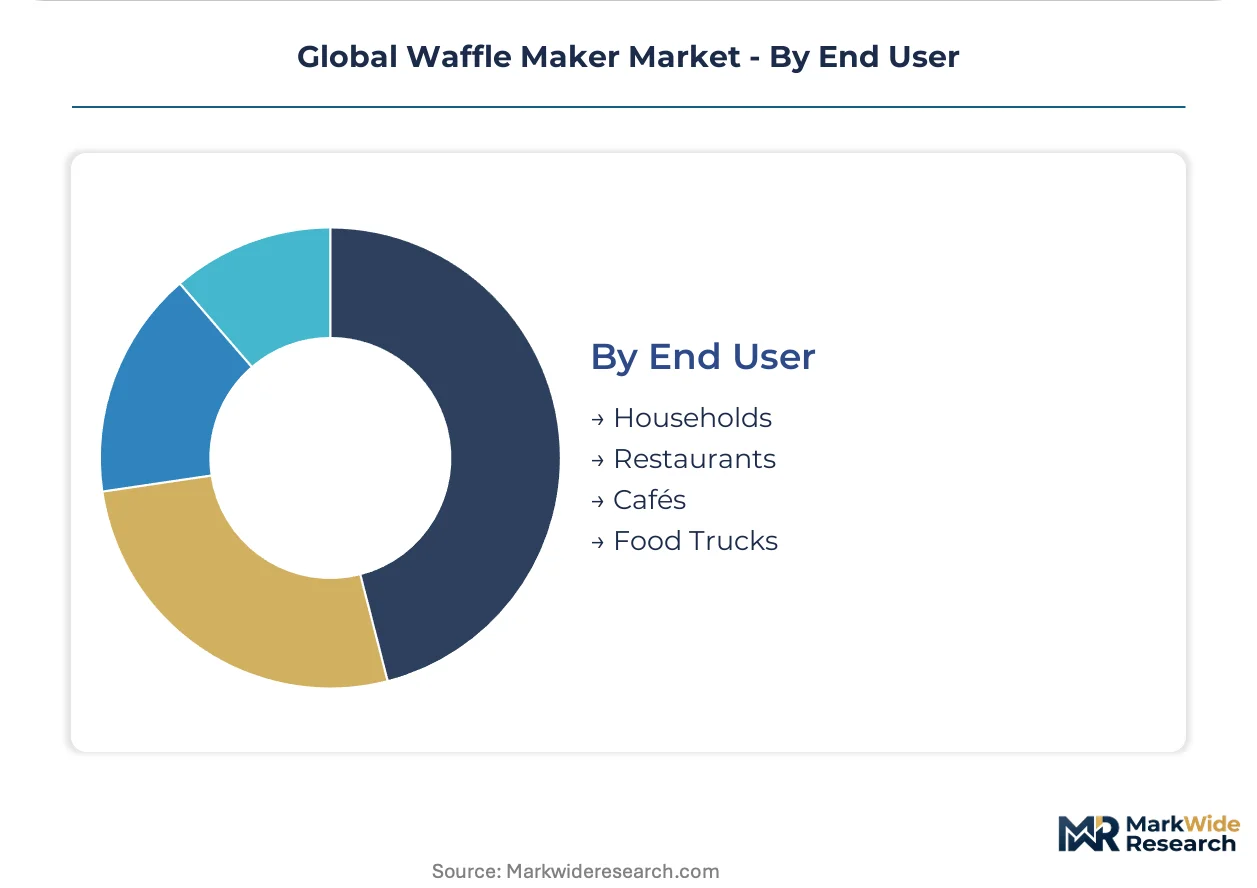
- Households:Weekend-use patterns dominate with 700-900 watt countertop units stored between cycles. Replacement triggers center on coating degradation rather than mechanical failure.
- Restaurants:Full-service breakfast operations in São Paulo and Rio de Janeiro lack standardized waffle programs, creating specification opportunities for equipment suppliers with training and batter formulation support.
- Cafés:Boutique hotel breakfast stations and airport lounge operators in Germany and the Netherlands are adopting ceramic-titanium plate systems at accelerated rates for durability positioning.
- Food Trucks:Mobile operators in Seoul, Dallas, and London require compact 220V/110V dual-voltage units with rapid heat recovery. Generator compatibility and vibration-resistant construction drive design priorities.
Households account for the largest installed base by unit count. Food truck and cloud-kitchen deployments are gaining share fastest as urban breakfast delivery formats multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waffle maker manufacturing traces its commercial lineage to Belgian metalworking traditions of the nineteenth century, when cast iron grid patterns first standardized. Industrial electrification shifted production gravity toward North American and European appliance hubs through the twentieth century.
United States
Cloud-kitchen operators in Dallas and Austin drive commercial unit procurement for delivery-optimized breakfast menus. FDA food-contact surface regulations govern non-stick coating compliance for imports and domestic production. Hamilton Beach Brands anchors mass-market distribution through Walmart and Target retail commitments.
Germany
Hotel breakfast stations in Munich and Frankfurt specify Belgian-format units with extended warranty requirements for premium positioning. EU REACH compliance deadlines from ECHA accelerate coating chemistry phase-outs and equipment replacement cycles. Bavarian hospitality procurement consortia now mandate thermal insulation material disclosure in CE marking technical files.
South Korea
Seoul's ghost kitchen networks require compact, high-throughput machines for urban delivery density. MFDS food-contact material standards shape import qualification for Asian and European OEMs. Busan-Ulsan manufacturing clusters supply regional OEMs with cast aluminum plate assemblies.
Brazil
São Paulo and Rio de Janeiro breakfast chains lack standardized commercial waffle programs, creating specification opportunities for equipment suppliers. ANVISA food-contact regulations govern import certification pathways for electric kitchen appliances. Southeastern café culture expansion concentrates demand in metropolitan corridors.
Vietnam
Ho Chi Minh City street food vendors adopt 220V commercial electric units as urban power infrastructure stabilizes. The country's national standards body aligns electrical safety certification with regional import requirements. Bubble-format equipment penetrates urban café markets as breakfast menus diversify beyond traditional pho and bánh mì.
Global Waffle Maker Market Competitive Environment
Premium-margin players sit above commodity-margin players across material construction and distribution channel access. Stainless steel and ceramic-titanium systems command fifteen to twenty percent price premiums over aluminum-cored alternatives. Three strategic archetypes dominate: heritage European metalworkers, North American mass-market distributors, and Asian contract manufacturers. Competitive moves concentrate on modular plate system development and direct-sales restructuring toward equipment-as-a-service models.
Among North American mass-market distributors, Hamilton Beach Brands exemplifies retail channel optimization through algorithmic placement and seasonal promotional calendars. Breville Group occupies a position within the premium-tier stainless steel construction segment. Groupe SEB anchors European hospitality procurement networks with specialized commercial-grade units for specification-grade contracts.
| Leading Market Players |
|---|
| Hamilton Beach Brands |
| Breville Group |
| Waring Commercial |
| Cuisinart |
| All-Clad |
| Krampouz |
| Krups |
| Conair Corporation |
| Groupe SEB |
| Others |
Value Chain & Pricing Dynamics
Cloud-kitchen procurement consortia in London and Sydney anchor volume contracting power, compressing transaction pricing toward subscription-per-cycle models that transfer capital expenditure risk to equipment distributors. This buyer concentration forces OEMs to absorb coating replacement and predictive maintenance liabilities within recurring revenue structures rather than upfront unit sales.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal performance specifications. CE-marked ceramic-titanium stainless steel systems command top-tier positioning against UL-certified aluminum-core units with sol-gel coatings. Cost compression in mid-tier aluminum assemblies intensifies because Chinese smelting region energy volatility squeezes foundry margins. Food truck operators in Seoul and Dallas exhibit highest price sensitivity due to generator-compatibility requirements, while German hotel procurement consortia prioritize extended warranty coverage over unit cost.
Supply Chain Analysis
Container freight rates from Shandong and Henan provinces to Rotterdam and Long Beach directly impact landed cost structures for cast aluminum plate assemblies. Manufacturing concentrates in China, Germany, and South Korea, with Busan-Ulsan clusters feeding regional OEM demand. Raw material sourcing draws from bauxite processing in Guizhou, ceramic sol-gel formulation from three specialty chemical firms controlling seventy percent of food-grade capacity, and 304-grade stainless steel from ThyssenKrupp and POSCO mills. Single-source vulnerability in coating chemistry creates qualification bottlenecks as ECHA phase-out deadlines accelerate. Distribution runs through hospitality procurement networks, direct-to-equipment-as-a-service platforms, and mass-market retail channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market offers margin expansion through ceramic-titanium coating adoption extending replacement intervals and commanding fifteen to twenty percent price premiums over legacy systems. Sol-gel formulation investments and IoT sensor integration create defendable differentiation against commodity aluminum competitors.
For Market Incumbents: Anchor specification-grade positioning through Bavarian and Dutch hospitality procurement consortia requiring thermal insulation disclosure in CE marking technical files. Deepen backward integration into ceramic-titanium deposition capacity to offset coating supplier concentration risk. Defend against emerging Asian contract manufacturers by embedding predictive maintenance sensors into cloud-based kitchen management platforms for QSR deployments. For New Entrants and Emerging Players: Launch via equipment-as-a-service subscription models penetrating UK and Australian cloud-kitchen networks where kitchen infrastructure investors bundle appliances into facility leases. Target São Paulo and Rio de Janeiro breakfast chains lacking standardized commercial waffle programs, offering batter formulation training alongside equipment specification. Pursue ANVISA import certification pathways to establish first-mover positioning before competitive saturation. For Investors and Strategic Acquirers: European hospitality procurement consortia and cloud-kitchen infrastructure investors are the most active acquirers in this space, seeking vertical integration into coating formulation and IoT-enabled fleet management. Long-term viability hinges on PFAS-free chemistry transitions and modular plate system standardization. Target acquisition archetypes include ceramic-titanium coating specialists and predictive maintenance software developers. Monitor FDA food-contact notification review timelines for new ceramic formulations as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Transition | ECHA phase-out deadlines compress redesign timelines and trigger equipment replacement cycles across German hotel networks. |
| IoT Sensor Integration | Temperature logging convergence with cloud-based kitchen platforms enables predictive maintenance revenue streams in QSR deployments. |
| Equipment-as-a-Service Launch | Per-cycle fee structures transfer maintenance liability to distributors while penetrating London and Sydney cloud-kitchen infrastructure. |
| Ceramic-Titanium Capacity Expansion | Extended replacement intervals from twenty-four to thirty-six months justify fifteen to twenty percent price premiums in boutique hospitality. |
| Modular Plate System Development | Interchangeable Belgian, American, and bubble format bundles reduce SKU proliferation strain on procurement and forecasting systems. |
Study Parameters
Direct dialogue with commercial kitchen operators, hospitality procurement managers, coating chemistry specialists, and foodservice equipment distributors grounded qualitative insights. Secondary validation drew from ECHA regulatory filings, FDA food-contact notifications, EU F-Gas Regulation implementation schedules, and customs trade data for cast aluminum and stainless steel imports. Bottom-up unit shipment estimates across Belgian, American, bubble, and stroopwafel formats triangulated against top-down market value reconstructions.
Segmented outputs across product type, material construction, distribution channel, and end-use application fed analytical framework development across the projection horizon. CAGRs derived from equipment replacement cycle analysis, cloud-kitchen proliferation rates, and stovetop-to-electric conversion patterns in Southeast Asian urban markets. Forecast inputs incorporated PFAS restriction timelines, ceramic formulation qualification durations, and hospitality procurement consortium standardization initiatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA enforcement or extended FDA notification reviews. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Gas Floor Fryers Market
Food Service
Mobile Food Services Market
Food Service
Steam Stew Pot Market
Food Service
United States Cafes & Bars Market
Food Service
Contract Catering Market
Food Service
Indonesia Foodservice Market
Food Service
Restaurant Griddle Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Online Catering Market
Food Service
Commercial Cutlery Market
Food Service
UAE Food Service Market
Food Service
Canada Food Service Market
Food Service
Hospital Food Services Market
Food Service
United States Quick Service Restaurants Market
Food Service
Europe Airline Catering Services Market