
 Low Salt Soy Sauce Market | 2026-2036
Low Salt Soy Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Low Salt Soy Sauce Market Insights
Potassium chloride is rebalancing cost structures across reduced-sodium formulations as brewers offset premium soybean expenses. Kikkoman Corporation leverages proprietary fermentation controls to maintain umami depth at lower sodium levels. Lee Kum Kee anchors its position through backward integration into soybean procurement across Guangdong province. Foshan Haitian Flavouring & Food Co., Ltd. dominates volume production with automated koji propagation systems that compress cycle times.
Low salt soy sauce denotes a brewed condiment with sodium content reduced through modified fermentation protocols, extended aging, or partial salt substitution, typically achieving sodium levels below standard soy sauce while preserving amino acid nitrogen above specified thresholds. The product serves health-conscious consumers and sodium-restricted diets without sacrificing the Maillard-derived flavor backbone essential to East Asian cuisine. Organic and gluten-free variants command premium shelf positioning as specialty retailers expand their fermented condiment assortments. Food manufacturers represent the fastest-growing end user segment as prepared sauce and ready-meal producers reformulate to meet clean-label and reduced-sodium specifications simultaneously.
Japan's Ministry of Health, Labour and Welfare enforces strict sodium labeling through Food with Nutrient Function Claims standards that directly shape product development priorities for exporters. China's National Health Commission and SAMR coordinate reduced-sodium dietary guidelines that pressure domestic brewers to accelerate reformulation timelines. The FDA's updated sodium reduction targets for processed foods in the United States create compliance-driven procurement shifts among importers. Stakeholders must monitor evolving fermentation patents and regional labeling harmonization to secure formulation advantages before regulatory deadlines tighten.
Market Dynamics
Japan's Food for Specified Health Uses labeling requirements are forcing brewers to accelerate reformulation timelines while maintaining amino acid nitrogen thresholds that preserve umami depth.
Growth Catalysts
- Potassium chloride substitution protocols:Brewers deploy partial salt replacement to achieve sodium reduction without extending fermentation cycles.
- China's coastal manufacturing clusters:Fermentation capacity expansion in Guangdong and Jiangsu provinces compresses supply lead times for reduced-sodium variants.
- Clean-label prepared meals:Food manufacturers reformulate sauces to meet simultaneous reduced-sodium and additive-free specifications.
Market Restraints
- Premium soybean input costs:Non-GMO and organic bean procurement prices fluctuate with harvest yields in Heilongjiang province.
- Extended aging requirements:Low-sodium formulations demand longer koji propagation periods that tie up fermentation tank capacity.
- Umami threshold technical limits:Sodium reduction below specific thresholds degrades glutamate perception regardless of amino acid nitrogen content.
Strategic Opportunities
- Southeast Asian export corridors:Vietnam and Thailand lack domestic reduced-sodium brewing capacity and rely on Chinese and Japanese imports.
- Automated koji propagation systems:Integration of machine vision with humidity controls reduces cycle variability and labor intensity.
- Organic certification premiums:JAS and USDA Organic labels command shelf price multiples in specialty retail channels.
Industry Challenges
- Master brewer skill scarcity:Traditional shoyu craftsmanship knowledge transfers slowly as automated systems displace apprentice pipelines.
- Dual certification timelines:Simultaneous organic and reduced-sodium label approvals require parallel documentation across SAMR and USDA systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Salt Soy Sauce Market |
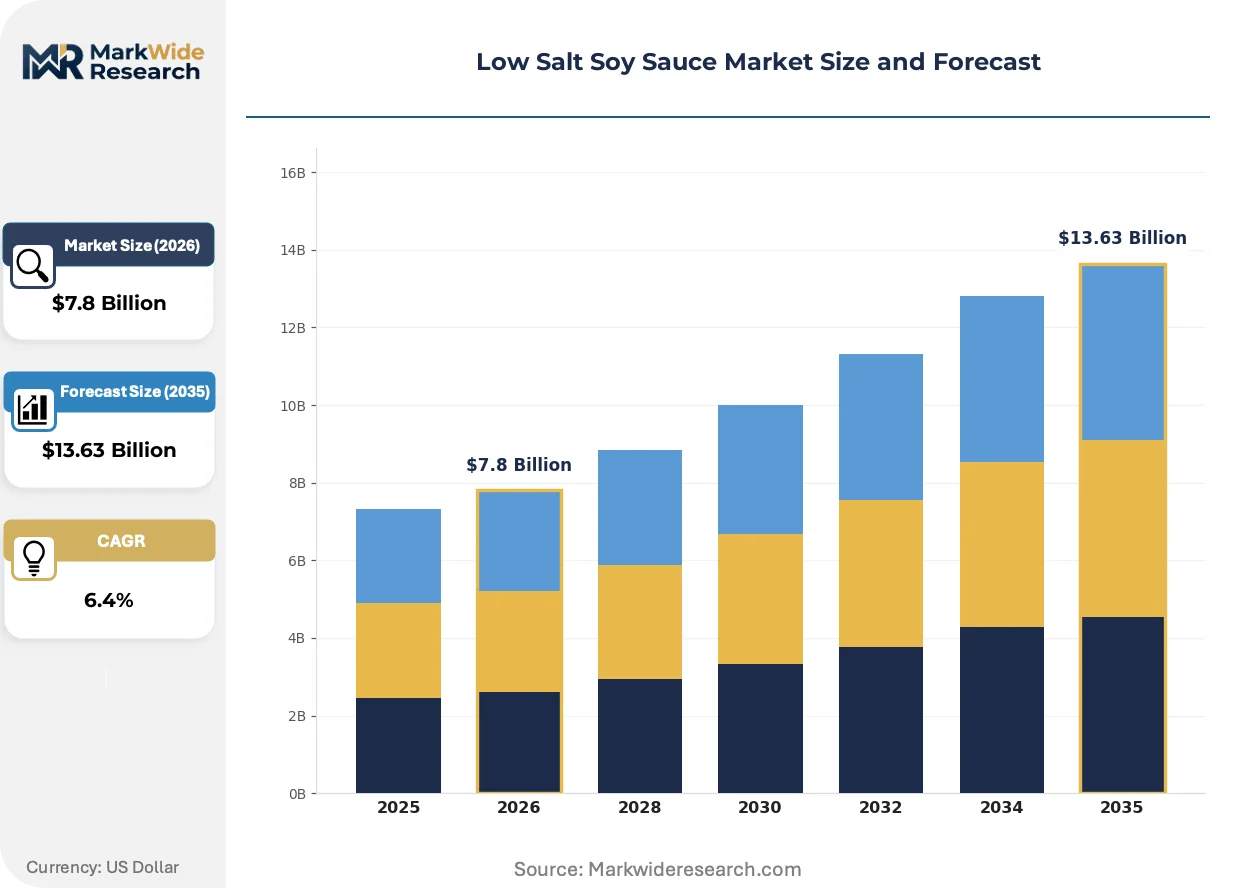
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Gluten-Free, Non-GMO Packaging Type: Bottles, Pouches, Cans, Bulk Containers End User: Household, Restaurants, Food Manufacturers, Culinary Schools Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service |
| Companies Covered | Kikkoman Corporation, Lee Kum Kee, Foshan Haitian Flavouring & Food Co., Ltd., SAN-J, Yamasa Corporation, Pearl River Bridge, Jiajia Food Group Co., Ltd., Koon Chun Sauce Factory Ltd., Wan Ja Shan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Salt Soy Sauce Market Trends and Innovations
Fermentation control technologies and regulatory labeling frameworks are compressing product development cycles while fragmenting procurement patterns across health-conscious consumer segments.
Precision koji temperature management is unifying enzymatic activity profiles across batch variations. Mid-sized brewers in Aichi prefecture adopt sensor-driven climate systems to standardize proteolysis rates. This convergence is unifying quality consistency between artisan and industrial production tiers.
Japan's Ministry of Health, Labour and Welfare tightened Food with Nutrient Function Claims sodium thresholds for condiment categories. Exporters must recalibrate formulations to maintain FOSHU eligibility on retail packaging. Prepared sauce manufacturers in Osaka and Nagoya industrial zones accelerate reformulation partnerships with established brewers.
Direct-to-restaurant distribution is displacing traditional wholesale channels for premium reduced-sodium variants. Specialty izakaya chains and ramen shops in Tokyo and Fukuoka negotiate contracted supply directly with regional breweries. This channel shift concentrates procurement decisions among executive chefs rather than centralized food service distributors.
Low Salt Soy Sauce Market Segmentation
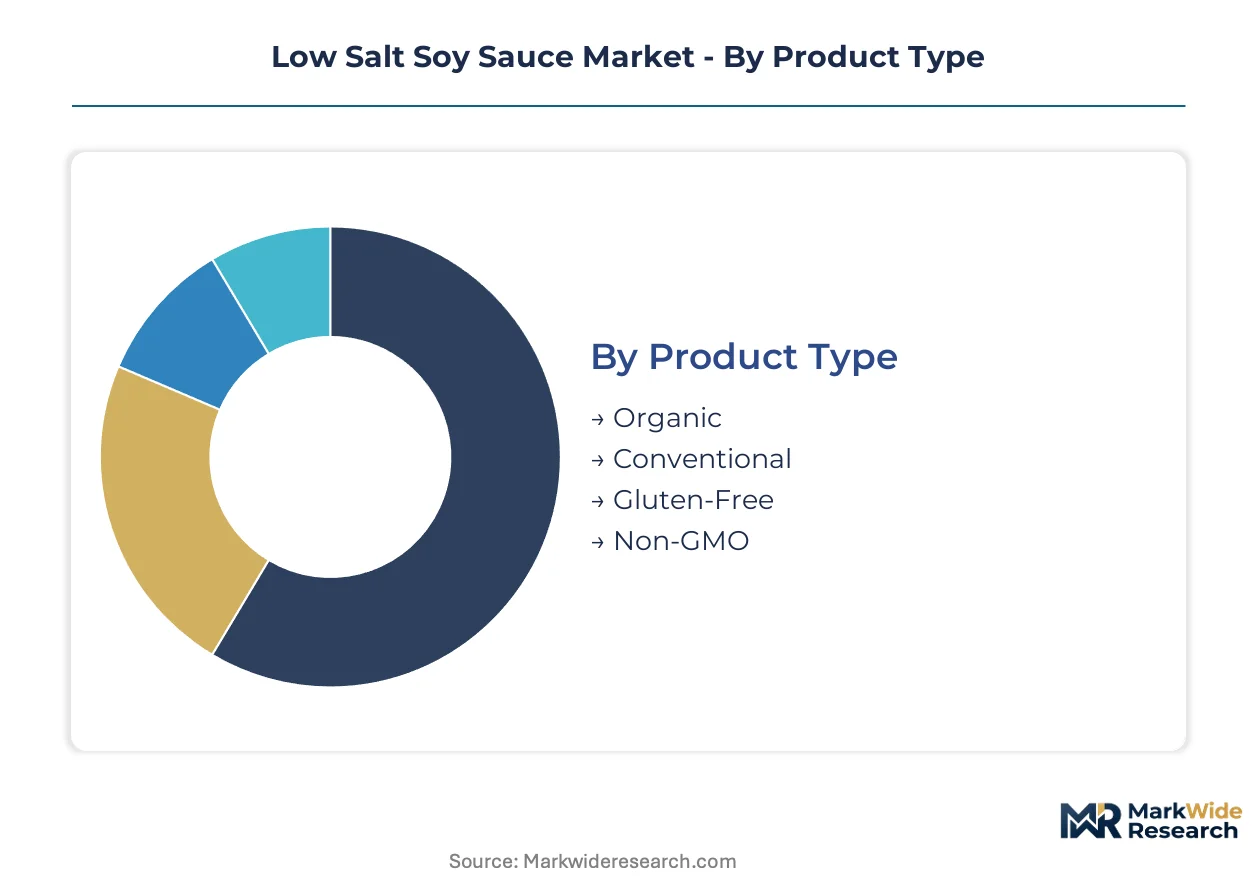
Low salt soy sauce markets fragment across health certifications, operational scale, and channel access requirements. Brewers must align fermentation protocols and packaging investments with distinct margin structures and regulatory exposure across each segment boundary.
Product Type:
Certification depth separates standalone premium positioning from embedded commodity supply, with organic and non-GMO variants commanding dedicated production lines while conventional products integrate into bulk food manufacturing.
- Organic:JAS and USDA Organic certification mandates non-GMO soybean sourcing and prohibited synthetic fermentation aids. Japanese specialty retailers in Tokyo and Osaka drive procurement premiums for certified imports from Aichi prefecture breweries.
- Conventional:Standard reduced-sodium formulations achieve cost parity with traditional soy sauce through potassium chloride substitution and compressed koji cycles. China's Guangdong manufacturing clusters supply prepared sauce producers across Southeast Asia.
- Gluten-Free:Tamari-style wheat-free brewing protocols address celiac and gluten-sensitive demographics. North American specialty retailers stock Japanese-imported gluten-free variants at shelf price multiples.
- Non-GMO:Identity-preserved soybean traceability from Heilongjiang province fields through fermentation tanks satisfies export documentation requirements. European importers prioritize non-GMO verification for retail channel access.
Conventional leads volumes today; organic is gaining share fastest.
Packaging Type:
Volume scale and shelf stability requirements shape format selection, with retail-facing units emphasizing convenience and food service prioritizing operational efficiency.
- Bottles:Glass and PET formats dominate supermarket and specialty retail channels. Japanese brewers deploy oxygen-barrier glass for premium aged variants targeting gift markets.
- Pouches:Flexible film reduces shipping weight and storage footprint for e-commerce fulfillment. Chinese online retailers favor pouch formats for last-mile delivery efficiency.
- Cans:Metal packaging extends shelf life for export shipments to Southeast Asian markets lacking cold chain infrastructure. Thai importers specify can formats for tropical climate stability.
- Bulk Containers:Stainless steel totes and drums supply industrial sauce manufacturers and restaurant chains. Osaka-based prepared meal producers contract direct bulk procurement from Kansai region breweries.
Bottles anchor retail presence; bulk containers capture industrial volume.
End User:
Application sophistication ranges from household table use to industrial formulation, with each tier demanding distinct sodium thresholds, umami intensity, and documentation depth.
- Household:Health-conscious consumers in Japan's urban centers prioritize FOSHU-labeled reduced-sodium variants for home cooking. Retail shelf placement near standard soy sauce drives trial conversion.
- Restaurants:Ramen chains and izakaya networks in Fukuoka and Sapporo negotiate contracted supply for house-blend sauce bases. Chefs specify amino acid nitrogen minimums for broth clarity.
- Food Manufacturers:Prepared sauce and ready-meal producers reformulate to meet simultaneous clean-label and reduced-sodium specifications. China's coastal manufacturing clusters integrate low-salt soy sauce into export-oriented product lines.
- Culinary Schools:Training institutions in Tokyo and Kyoto procure standard and premium variants for technique instruction. Curriculum requirements sustain steady volume through educational procurement channels.
Food manufacturers expand most quickly; households retain the largest absolute base.
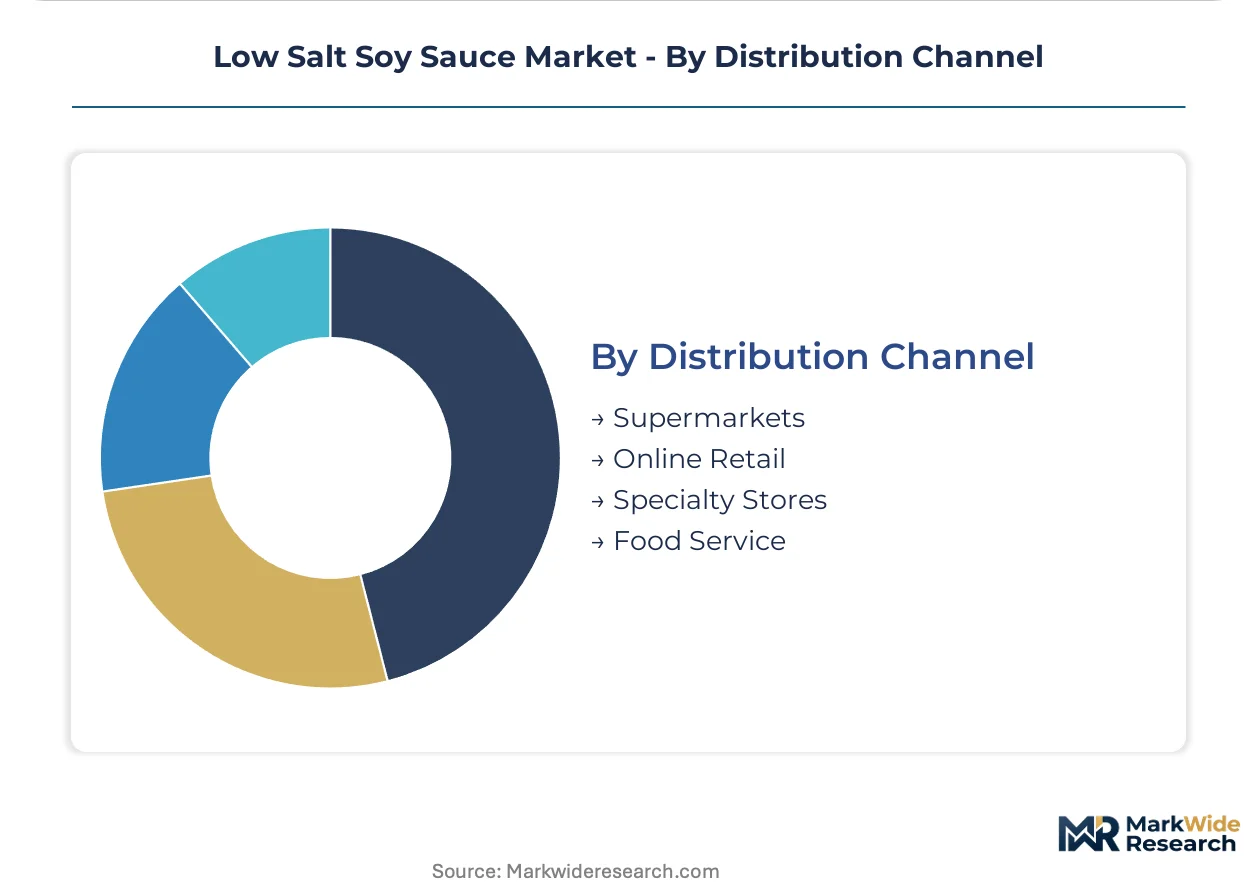
Distribution Channel:
Channel selection determines margin capture and brand control intensity, with direct relationships displacing traditional wholesale intermediaries in premium tiers.
- Supermarkets:Mass retail chains in Japan and China allocate shelf space based on turnover velocity and health claim certification. FOSHU labeling secures preferential positioning in Japanese supermarket condiment aisles.
- Online Retail:E-commerce platforms enable direct brewery-to-consumer relationships for specialty and organic variants. Chinese cross-border e-commerce channels import Japanese premium reduced-sodium products.
- Specialty Stores:Organic grocers and Asian food emporiums in North America and Europe curate fermented condiment assortments. JAS Organic certification commands placement in premium natural product retailers.
- Food Service:Distributors serving restaurant chains and institutional kitchens prioritize volume consistency and documentation compliance. Direct brewery contracts are displacing traditional food service intermediaries in Japan.
Supermarkets dominate transaction volume; online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong province fermentation corridors anchor production scale for reduced-sodium soy sauce manufacturing. Japan's Kansai and Kanto industrial belts concentrate premium brewing heritage alongside automated reformulation capacity. Regulatory divergence across FDA, Japan's Ministry of Health, Labour and Welfare, and China's SAMR shapes distinct compliance pathways for exporters.
China
Guangdong and Jiangsu coastal clusters drive fermentation capacity expansion for potassium chloride-substituted formulations. SAMR's reduced-sodium dietary guidelines pressure domestic brewers to accelerate reformulation timelines ahead of labeling enforcement. Foshan manufacturing zones deploy automated koji propagation systems that compress cycle times for export-oriented production.
Japan
Tokyo and Osaka metropolitan demand concentrates among health-conscious households prioritizing FOSHU-labeled variants. The Ministry of Health, Labour and Welfare enforces strict sodium thresholds through Food with Nutrient Function Claims standards that reshape product development priorities. Aichi prefecture breweries integrate sensor-driven climate controls to standardize proteolysis rates across batch variations.
United States
Specialty retailers in California and New York metro areas curate organic and gluten-free reduced-sodium assortments for health-focused demographics. FDA sodium reduction targets for processed foods create compliance-driven procurement shifts among prepared sauce importers. West Coast distribution hubs handle bulk imports from Japanese and Chinese brewing facilities for food service redistribution.
Vietnam
Hanoi and Ho Chi Minh City restaurant chains drive import dependency for reduced-sodium brewing capacity absent in domestic production. The country's national food safety regulator maintains import documentation requirements for fermented condiment categories. Central coastal provinces lack fermentation infrastructure and rely on Guangdong manufacturing clusters for supply continuity.
Thailand
Bangkok-based ramen chains and izakaya networks negotiate direct supply contracts for house-blend sauce bases with specific amino acid nitrogen minimums. Tropical climate stability requirements favor canned packaging formats from Chinese exporters over glass alternatives. Eastern seaboard industrial zones process imported bulk reduced-sodium variants into prepared meal formulations for ASEAN export.
Low Salt Soy Sauce Market Competitive Landscape
Global majors compete with regional champions across fermentation technology and distribution reach. The vendor base stratifies between heritage Japanese brewers with proprietary koji controls and Chinese volume producers leveraging automated propagation systems. Three archetypes dominate: premium heritage specialists, scale-driven commodity suppliers, and hybrid mid-tier regional exporters. Capacity expansion and backward integration into soybean procurement represent the dominant competitive moves across tiers.
Within the heritage brewing tier, Kikkoman Corporation and Yamasa Corporation exemplify proprietary fermentation control advantages. Lee Kum Kee and Foshan Haitian Flavouring & Food Co., Ltd. occupy positions on the scale-driven commodity vector. SAN-J represents the specialty certification archetype through gluten-free and organic positioning. These named entities anchor industry-level commentary without asserting specific strategic actions beyond visible operational patterns.
| Leading Market Players |
|---|
| Kikkoman Corporation |
| Lee Kum Kee |
| Foshan Haitian Flavouring & Food Co., Ltd. |
| SAN-J |
| Yamasa Corporation |
| Pearl River Bridge |
| Jiajia Food Group Co., Ltd. |
| Koon Chun Sauce Factory Ltd. |
| Wan Ja Shan |
| Others |
Pricing and Supply Chain Analysis
Automated koji propagation systems compress fermentation cycle times while simultaneously reducing labor intensity and concentrating production scale among Guangdong and Jiangsu manufacturers. This technological shift reshapes cost economics by lowering unit production costs for reduced-sodium variants while amplifying pricing power for operators with installed automation capacity.
Pricing Analysis
Input-cost pass-through from premium non-GMO soybean procurement in Heilongjiang province shapes margin structures across all tiers. Three-tier pricing structure across organic-certified, conventional reduced-sodium, and bulk industrial grades separates JAS-certified imports from potassium chloride-substituted domestic production. Pricing pressure stems from harvest yield volatility in northeast China bean-growing regions. Food manufacturers exhibit highest price sensitivity due to reformulation volume scale, while specialty retailers absorb premiums for certified organic positioning.
Supply Chain Analysis
Direct-to-restaurant channels displace traditional food service distributors for premium reduced-sodium variants in Tokyo and Osaka metropolitan markets. Supply concentrates in China's Guangdong fermentation corridors, Japan's Aichi prefecture brewing clusters, and Thailand's Bangkok-based import processing zones. Raw material flows draw from Heilongjiang non-GMO soybeans, potassium chloride suppliers, and automated koji equipment manufacturers. Single-source vulnerability exists in master brewer skill pipelines as automated systems displace traditional apprenticeship pathways. Distribution runs through contracted direct supply for restaurant chains, bulk container shipments for industrial sauce producers, and e-commerce platforms for specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum as Japan's Ministry of Health, Labour and Welfare tightens Food with Nutrient Function Claims sodium thresholds, forcing continuous reformulation investment across export-oriented supply chains.
For Market Incumbents: Deepen backward integration into Heilongjiang soybean procurement to insulate margin structures from harvest yield volatility. Expand automated koji propagation capacity in Guangdong manufacturing zones to compress cycle times and defend volume position against emerging Chinese competitors. Prioritize dual JAS-USDA Organic certification investment to capture specialty retail premiums before labeling deadlines tighten. For New Entrants and Emerging Players: Precision fermentation control technologies offer entry pathways into Southeast Asian import-dependent markets lacking domestic reduced-sodium brewing capacity. Vietnam and Thailand present penetrable white-space targets where restaurant chains negotiate direct supply for house-blend sauce bases. Lead with amino acid nitrogen specification guarantees and tropical-stability packaging formats to differentiate from established exporters. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional brewers with installed fermentation automation but underdeveloped export documentation capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than brand heritage alone. Monitor SAMR enforcement timelines for reduced-sodium labeling requirements as the inflection signal for consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Koji Propagation Deployment | Machine vision integration in Guangdong facilities compresses cycle variability and labor intensity. |
| Heilongjiang Soybean Procurement Integration | Captive supply of non-GMO beans insulates margin structures from harvest yield volatility. |
| JAS-USDA Organic Dual Certification | Dual labels command shelf price multiples in Tokyo specialty retail and North American natural product channels. |
| Direct-to-Restaurant Distribution Buildout | Contracted supply relationships with Fukuoka and Sapporo ramen chains displace food service intermediaries. |
| Southeast Asian Export Corridor Expansion | Vietnam and Thailand import dependency creates procurement opportunities for Chinese and Japanese brewers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume dynamics and operational constraints. Primary engagement included fermentation technology directors at Guangdong manufacturing clusters, procurement leads at Osaka prepared sauce producers, regulatory affairs specialists navigating SAMR and FDA compliance pathways, and category buyers at Japanese supermarket chains. Secondary validation drew from customs trade databases, SEC filings of listed brewing entities, Japan's Ministry of Health, Labour and Welfare FOSHU registration records, and USDA Organic certification directories. Bottom-up production capacity modeling and top-down demand segmentation triangulated market sizing across the analysis window.
Historical reference periods anchored volume and value trajectories to pre-reformulation baseline years and post-regulatory enforcement transition phases. Segmentation dimensions modeled include certification tier, packaging format, end-use application, and regional regulatory cluster. CAGRs derived from weighted average growth assumptions across these segments, calibrated against fermentation capacity expansion timelines and soybean procurement cost indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR enforcement intensity, potassium chloride supply disruptions, and master brewer skill pipeline constraints. Forecasts reflect documented assumptions regarding regulatory timeline adherence and harvest yield normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Latin America Pasta Sauce Market