
 Sauce Making Machine Market | 2026-2036
Sauce Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sauce Making Machine Market Analytics
Direct equipment sales channels is tilting toward integrated solution providers as buyers seek turnkey sauce processing lines rather than standalone units. Tetra Pak leverages its aseptic packaging heritage to bundle sauce preparation with filling systems. GEA Group anchors its position through extensive clean-in-place technology portfolios. Alfa Laval competes on heat transfer efficiency in steam-heated cooking vessels.
A sauce making machine is an industrial food processing system that cooks, mixes, homogenizes, and cools viscous liquid or semi-liquid condiments within temperature-controlled stainless-steel vessels, typically operating between 80°C and 140°C depending on product pasteurization requirements. These systems serve commercial food manufacturers and foodservice operators requiring consistent batch-to-batch quality at production volumes exceeding manual preparation capacity. Continuous processing technology leads the technology dimension due to throughput advantages in high-volume tomato sauce and mayonnaise operations, while fully automatic systems capture expanding margin pools as labor costs rise across food processing plants. Electric heating dominates new installations for precision temperature control, though steam heating sustains share in facilities with existing boiler infrastructure.
The FDA enforces Hazard Analysis Critical Control Point compliance for sauce manufacturing equipment sold into US food processing plants, mandating sanitary design standards that elevate stainless-steel construction requirements. The EU's Machinery Directive and CE marking framework governs equipment safety and electromagnetic compatibility for machines deployed across European food processing facilities. Buyers must evaluate total cost of ownership across energy consumption, cleaning cycle duration, and regulatory certification breadth when selecting between batch and continuous system architectures.
Market Dynamics
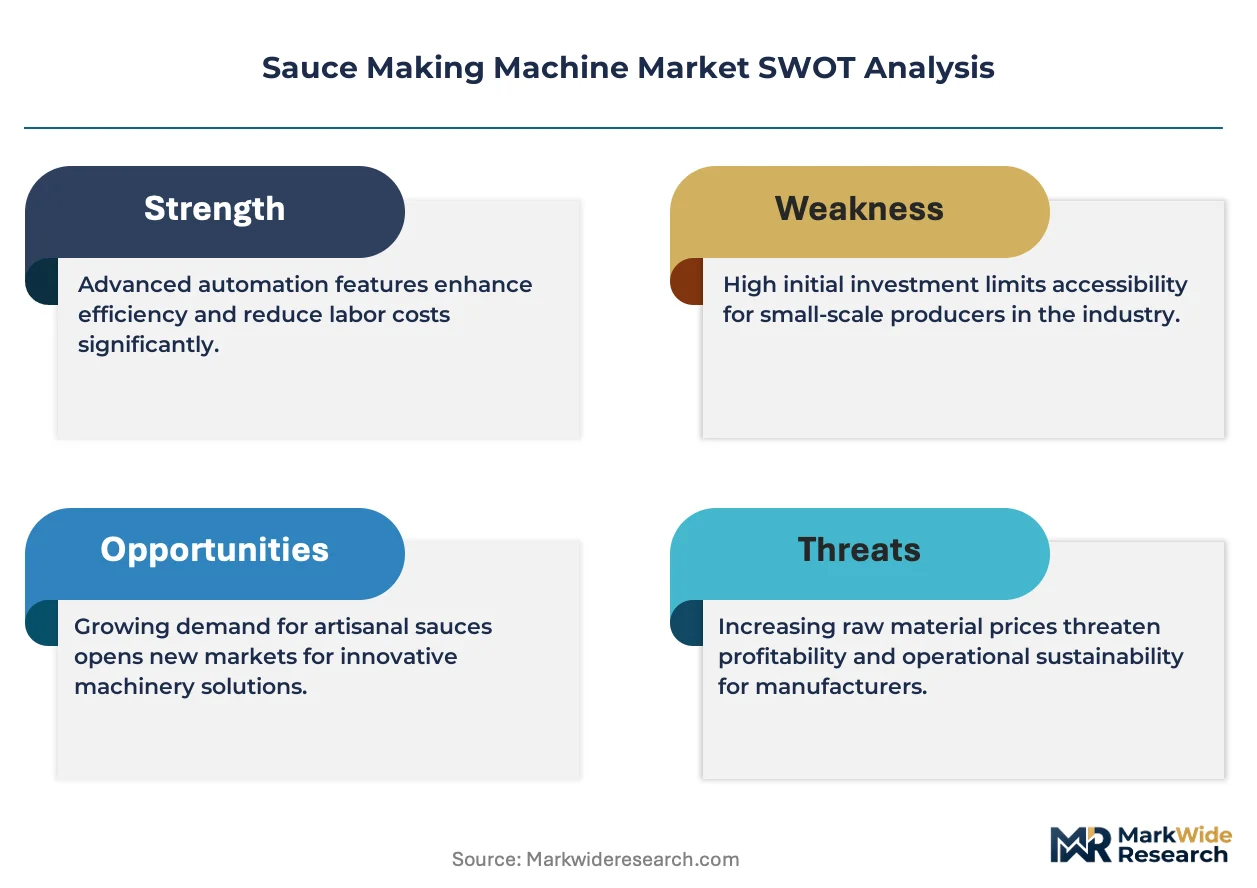
Commercial kitchens and restaurant chains are accelerating automated sauce production capacity to reduce labor dependency, while FDA enforcement of the Food Safety Modernization Act is mandating stainless-steel, clean-in-place equipment designs that reshape procurement criteria.
Growth Catalysts
- Regulatory Compliance Mandates:The FDA's updated Food Safety Modernization Act enforcement pushes processors toward sanitary equipment designs, expanding demand for stainless-steel construction and automated clean-in-place systems.
- Labor Cost Escalation:Food processing plants face rising wage pressures that accelerate replacement of manual sauce preparation with fully automatic continuous processing technology.
- Mid-Scale Modernization:Germany's food manufacturers are retrofitting legacy production lines with semi-automatic and continuous systems to improve throughput consistency.
Market Restraints
- Stainless-Steel Input Volatility:Fluctuating nickel and chromium prices squeeze margins for equipment fabricators dependent on food-grade 316L stainless construction.
- Specialized Component Concentration:Precision homogenizer pumps and aseptic valves concentrate supply among German and Italian precision engineering clusters.
- CE Marking Friction:The EU's Machinery Directive compliance timeline extends equipment certification cycles, delaying revenue recognition for manufacturers.
Strategic Opportunities
- Clean-Label Sauce Expansion:Cold-fill aseptic processing technology converges with reduced-preservative formulation trends, opening equipment upgrade cycles in natural and organic segments.
- Energy Efficiency Incentives:The EU Green Deal's industrial decarbonization subsidies favor electric-heated cooking vessels with precision temperature control over legacy steam infrastructure.
- Turnkey Integration Services:Buyers increasingly prefer integrated solution providers bundling preparation, cooking, and filling systems over standalone unit procurement.
Industry Challenges
- Sanitary Design Engineering Shortage:Food equipment manufacturers struggle to hire process engineers with dual expertise in thermal processing and FDA-compliant surface finish specifications.
- Legacy System Integration Complexity:Retrofitting continuous sauce lines into batch-oriented plant layouts requires custom piping and control architecture that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sauce Making Machine Market |
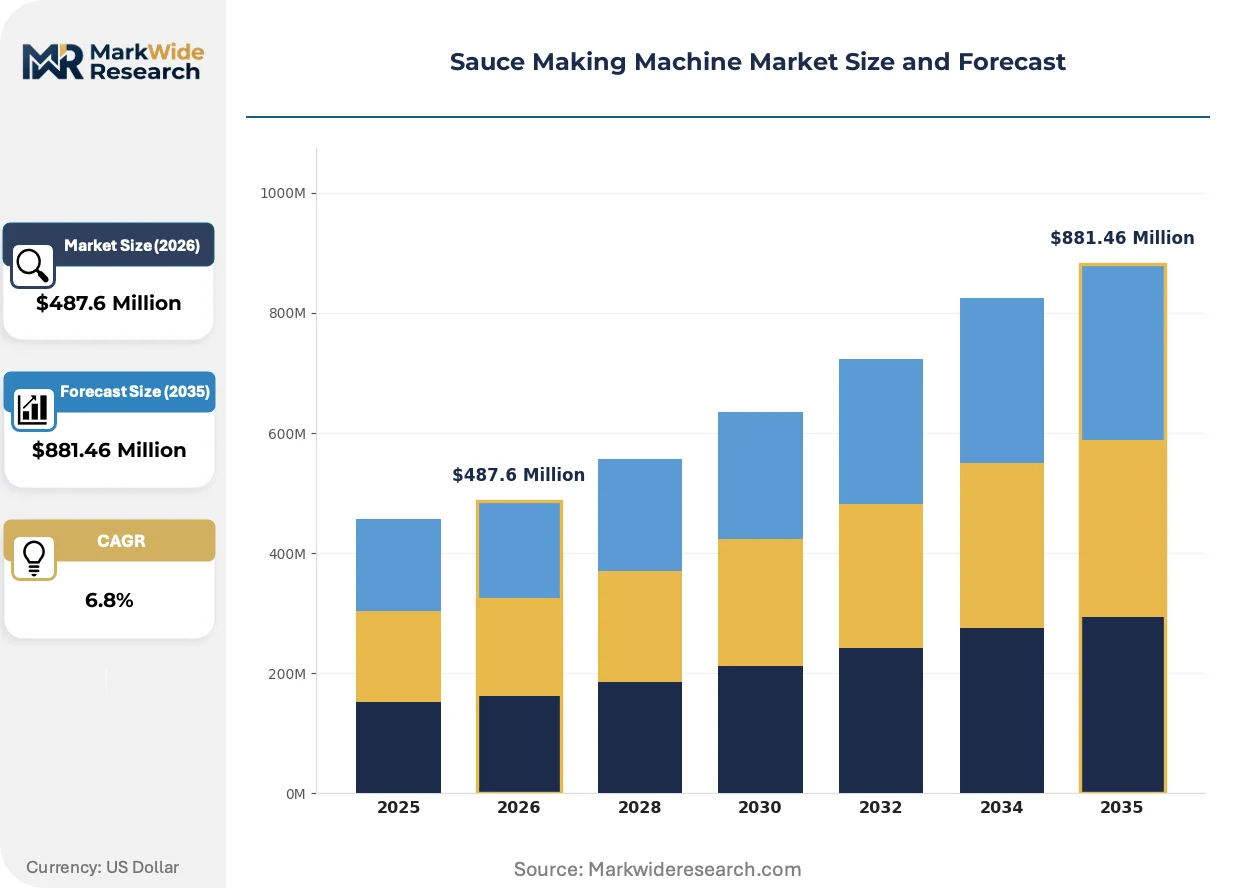
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch, Continuous, Semi-Automatic, Fully Automatic Technology: Steam Heating, Electric Heating, Microwave Heating, Direct Heating End User: Food Processing Plants, Restaurants, Catering Services, Home Use Capacity: Small Scale, Medium Scale, Large Scale, Industrial |
| Companies Covered | Tetra Pak, GEA Group, Alfa Laval, Buhler Group, Krones AG, Marel, Bertuzzi Food Processing, FENCO Food Machinery, SPX FLOW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sauce Making Machine Market Evolving Landscape
Equipment architecture is pivoting from standalone batch vessels toward modular continuous processing trains, driven by throughput demands in high-volume condiment operations and the need for real-time quality monitoring.
Advanced clean-in-place systems with automated sequencing and conductivity-based verification are rendering obsolete manual cleaning protocols that required extended downtime and labor-intensive disassembly. Mid-scale food manufacturers in Germany and the Netherlands are adopting these systems at accelerated replacement cycles. The technology is compressing total cost of ownership calculations by reducing water consumption and eliminating batch-to-batch contamination risks.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in cooling systems, forcing equipment redesigns toward ammonia or CO2-based refrigeration architectures. Sauce cooling modules face accelerated obsolescence timelines as 2024-2030 reduction targets tighten. Italian and Spanish equipment fabricators are responding with dedicated engineering teams for natural refrigerant transition programs.
Foodservice procurement patterns are consolidating vendor relationships around full-line solution providers capable of delivering integrated cooking, cooling, and packaging systems. Restaurant chains with centralized commissary operations are displacing fragmented equipment sourcing through single-source contracting. This concentration is most visible in North American fast-casual segments where quality consistency mandates span hundreds of locations.
Sauce Making Machine Market Segmentation
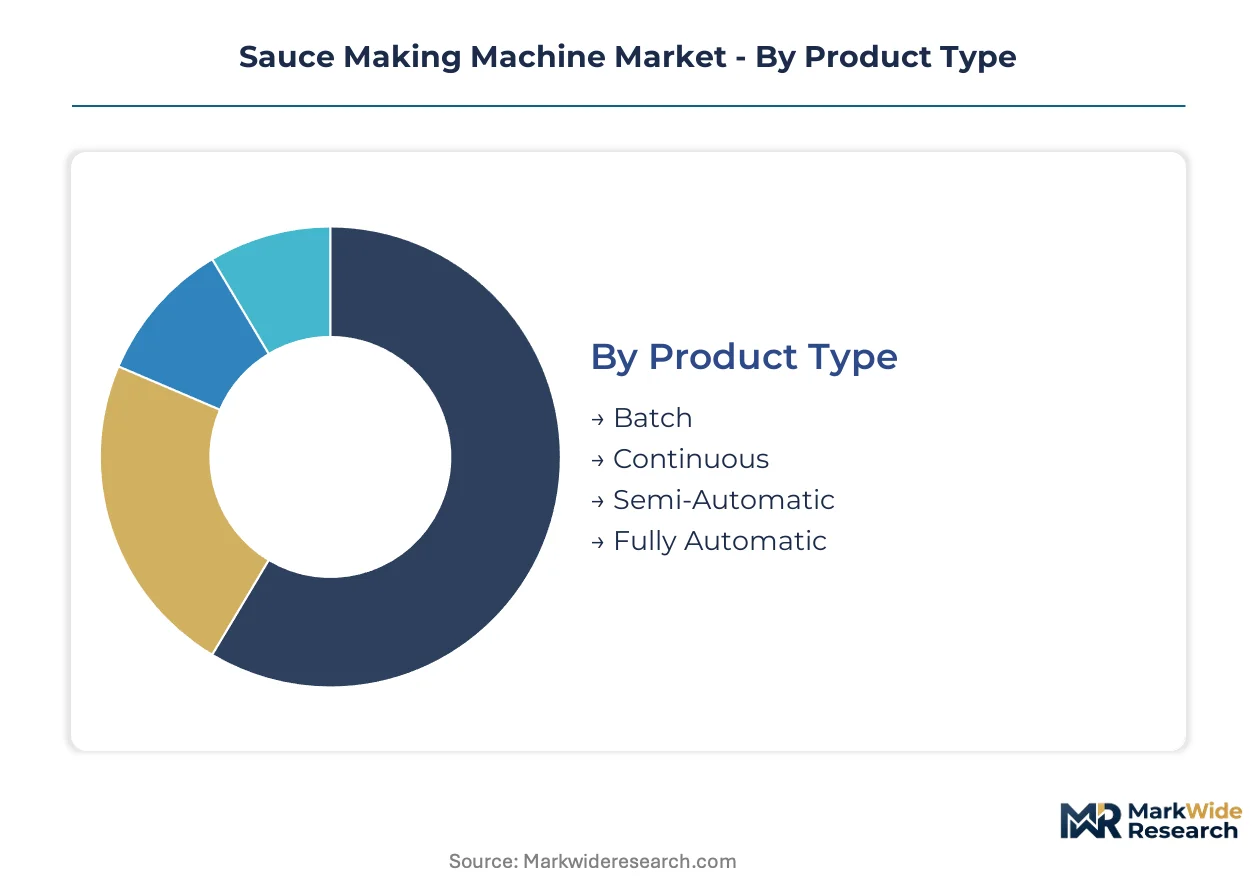
Sauce making machine procurement patterns diverge sharply across operational scales and thermal processing requirements. Equipment specifications must align with batch consistency demands, energy infrastructure, and regulatory compliance frameworks governing food contact surfaces.
Product Type:
Commercial kitchens deploy equipment across a spectrum from artisanal batch operations to integrated continuous lines serving multi-location restaurant chains.
- Batch:Standalone vessels process discrete quantities with manual loading and unloading cycles. Germany's mid-scale food manufacturers favor these systems for legacy line retrofits where footprint constraints prevent continuous line installation.
- Continuous:Integrated processing trains move product through cooking, homogenization, and cooling stages without interruption. High-volume tomato sauce and mayonnaise operations in North American fast-casual commissaries concentrate demand here.
- Semi-Automatic:Hybrid systems automate temperature control while retaining manual ingredient addition and discharge sequences.
- Fully Automatic:Complete process automation with recipe-driven PLC control and automated clean-in-place sequencing reduces labor dependency.
The dominant share belongs to Continuous systems, while Fully Automatic configurations are closing the gap fastest.
Technology:
Heating method selection hinges on existing plant infrastructure, precision requirements, and decarbonization incentives reshaping capital planning.
- Steam Heating:External jacket vessels leverage boiler infrastructure common in legacy food processing plants. Facilities with existing steam distribution sustain procurement preference despite slower temperature ramp rates.
- Electric Heating:Resistance or induction elements deliver precise temperature control with rapid response curves. EU Green Deal industrial decarbonization subsidies accelerate displacement of steam infrastructure in Netherlands and Danish plants.
- Microwave Heating:Volumetric energy absorption reduces thermal degradation in heat-sensitive formulations.
- Direct Heating:Steam injection or flame contact methods achieve rapid temperature elevation for high-viscosity products.
Electric Heating commands expanding installation share, with Steam Heating retaining position where boiler capital is already sunk.
End User:
Buyer sophistication spans from industrial-scale pasteurization compliance to countertop convenience for specialty foodservice.
- Food Processing Plants:Large-scale manufacturers require FDA-validated clean-in-place protocols and HACCP-compliant surface finishes. These buyers bundle preparation, cooking, and aseptic filling systems from integrated solution providers.
- Restaurants:Centralized commissary operations for restaurant chains displace fragmented equipment sourcing through single-source contracting. Quality consistency mandates across hundreds of locations drive standardization.
- Catering Services:Mobile and event-focused operators prioritize rapid cycle times and transportable batch sizes.
- Home Use:Specialty appliance segments serve artisanal producers and culinary enthusiasts with reduced-capacity countertop units.
Food Processing Plants anchor equipment revenue, though Restaurants are expanding automated capacity most aggressively.
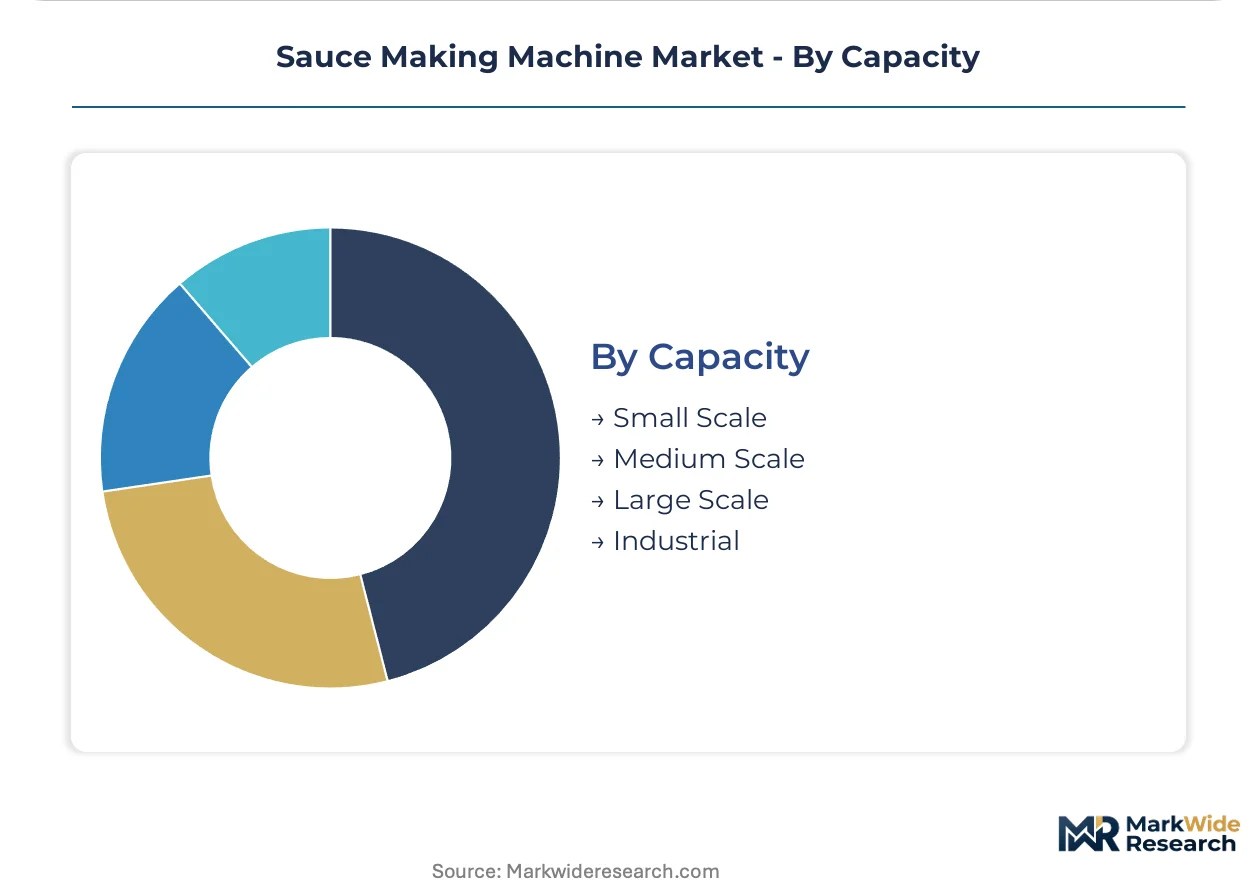
Capacity:
Throughput specifications align with production volume tiers from artisanal scale to industrial commodity output.
- Small Scale:Vessels under 100-liter capacity serve specialty sauce producers and test kitchen environments. German craft food startups favor these systems for organic and clean-label product development.
- Medium Scale:100-500 liter systems bridge artisanal and industrial operations. Netherlands-based mid-scale manufacturers modernizing legacy lines concentrate replacement demand in this tier.
- Large Scale:500-2000 liter vessels support regional distribution networks and multi-shift operations.
- Industrial:Systems exceeding 2000 liters with continuous feed architecture serve national brand manufacturers and export-oriented processors.
Medium Scale systems capture replacement cycle momentum, while Industrial capacity expands with centralized commissary buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government decarbonization subsidies and food safety enforcement are redirecting capital toward automated sauce processing infrastructure across major manufacturing economies.
Germany
Mid-scale food manufacturers in Baden-Württemberg and Bavaria are retrofitting legacy batch lines with continuous systems to reduce labor dependency. The EU Machinery Directive and CE marking requirements extend certification timelines but elevate equipment quality standards. Stuttgart's precision engineering cluster supplies homogenizer pumps to domestic fabricators modernizing tomato sauce operations.
United States
Fast-casual restaurant chains are consolidating commissary operations around integrated cooking and filling systems to enforce quality consistency across hundreds of locations. FDA enforcement of the Food Safety Modernization Act mandates stainless-steel construction and validated clean-in-place protocols. Chicago's food processing corridor anchors demand for industrial-scale continuous processing trains serving national distribution networks.
Netherlands
EU Green Deal industrial decarbonization subsidies accelerate displacement of steam-heated vessels with electric heating systems offering precision temperature control. The F-Gas Regulation phases down hydrofluorocarbon refrigerants in cooling modules, forcing equipment redesigns. Eindhoven's food technology cluster concentrates engineering expertise for natural refrigerant transition programs in sauce cooling applications.
Italy
Specialty sauce producers in Emilia-Romagna favor semi-automatic systems that automate temperature control while retaining manual ingredient handling for artisanal formulations. REACH compliance governs chemical safety in food contact materials and surface finishes. Parma's food machinery district fabricates clean-in-place systems for mid-scale European processors seeking batch-to-batch consistency.
China
Domestic condiment manufacturers are expanding automated capacity to serve urban foodservice chains requiring standardized output at volume. GB standards and SAMR oversight govern food equipment safety and electromagnetic compatibility. Shanghai's Yangtze River Delta manufacturing base concentrates stainless-steel vessel fabrication for regional sauce processing plant upgrades.
Sauce Making Machine Market Competitive Landscape
On the supply side, the industry is consolidating around integrated solution providers capable of bundling preparation, cooking, and packaging systems. Equipment fabricators compete across three strategic archetypes: diversified industrial conglomerates with thermal processing heritage, specialized food machinery engineers with clean-in-place expertise, and precision component suppliers integrating into full-line offerings. Competitive dynamics center on turnkey integration capabilities and regulatory certification breadth rather than standalone unit pricing.
Among European-based diversified industrial groups, Tetra Pak leverages aseptic packaging heritage to anchor turnkey positioning, while GEA Group exemplifies the clean-in-place technology specialist archetype through extensive sanitary design portfolios. Alfa Laval occupies a position emphasizing heat transfer efficiency in temperature-controlled cooking vessels. These three represent distinct competitive vectors: packaging-integrated solutions, sanitary engineering depth, and thermal processing optimization.
| Leading Market Players |
|---|
| Tetra Pak |
| GEA Group |
| Alfa Laval |
| Buhler Group |
| Krones AG |
| Marel |
| Bertuzzi Food Processing |
| FENCO Food Machinery |
| SPX FLOW |
| Others |
Value Network & Pricing Analysis
German and Italian precision engineering clusters for homogenizer pumps and aseptic valves capture upstream margin pools, concentrating pricing power among specialized component fabricators while downstream equipment assemblers compete on turnkey integration value.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated continuous systems with full clean-in-place automation from semi-automatic batch vessels and basic standalone units. Price differentiation hinges on certification grade—CE marking and FDA compliance tiers—and volume scale, with industrial-scale buyers securing substantial contract discounts. Pricing pressure stems from stainless-steel input volatility, particularly nickel and chromium price swings, compressing fabricator margins on fixed-price contracts. Food processing plants demonstrate lowest price sensitivity due to regulatory compliance mandates, while catering services and small-scale artisanal producers exhibit highest elasticity.
Supply Chain Analysis
Stainless-steel feedstock draws from Chinese, German, and Indian metallurgical producers, with food-grade 316L alloy specifications tightening qualification requirements for vessel fabricators. Critical component dependencies include precision homogenizer pumps from Stuttgart-area engineering clusters, aseptic valves from Italian precision manufacturers, and PLC control systems from Japanese automation specialists. Supply chain risk centers on single-source vulnerability for specialized sanitary fittings and extended lead times for CE-marked electrical assemblies. Distribution runs through integrated solution providers bundling preparation, cooking, and filling systems rather than standalone unit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sauce making machine market operates as a defensive-moat business where regulatory entrenchment—FDA validation protocols and CE marking requirements—creates substantial switching costs that protect incumbent positions.
For Market Incumbents: Pre-empt emerging competition from Asian equipment fabricators by deepening clean-in-place technology portfolios and securing backward integration into precision valve manufacturing. Anchor market position through capacity expansion in Netherlands and Germany where EU Green Deal subsidies accelerate electric heating system displacement of legacy steam infrastructure. Prioritize certification investment in ammonia-based refrigeration architectures ahead of F-Gas Regulation phase-down deadlines. For New Entrants and Emerging Players: Build out specialized engineering capabilities in natural refrigerant cooling modules, the most penetrable white-space segment given accelerated obsolescence timelines for hydrofluorocarbon-based systems. Target mid-scale food manufacturers in Baden-Württemberg and Bavaria modernizing legacy batch lines with continuous retrofit solutions. Pursue go-to-market positioning as clean-label processing specialists serving organic and reduced-preservative formulation trends. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed food machinery specialists holding clean-in-place expertise but lacking integrated packaging capabilities. Five-to-ten year viability hinges on consolidation toward turnkey solution providers capable of bundling preparation through aseptic filling. Watch for inflection signals in centralized commissary buildouts by North American fast-casual chains, which indicate acceleration in single-source contracting concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-in-Place Technology Acquisition | GEA Group's sanitary design depth demonstrates how CIP portfolios anchor premium positioning against standalone competitors. |
| Natural Refrigerant Transition Program | Italian fabricators' dedicated ammonia engineering teams capture EU F-Gas Regulation compliance premiums ahead of phase-down targets. |
| Turnkey Integration Partnership | Tetra Pak's aseptic packaging bundling with sauce preparation illustrates full-line solution provider competitive moats. |
| Electric Heating System Expansion | Netherlands-based manufacturers leverage EU Green Deal subsidies to displace steam infrastructure in Danish and Dutch plants. |
| Precision Component Backward Integration | Stuttgart homogenizer pump clusters concentrate supply leverage that vertical integration into valve manufacturing would neutralize. |
Research Methodology
The analysis maps batch, continuous, semi-automatic, and fully automatic system architectures, each validated through equipment procurement directors at food processing plants, plant engineers overseeing thermal processing lines, regulatory affairs specialists managing FDA and CE compliance, and aftermarket service heads tracking total cost of ownership metrics. Secondary validation draws from FDA Food Safety Modernization Act guidance documents, EU Machinery Directive technical files, SEC 10-K filings of listed industrial conglomerates, and customs data on stainless-steel vessel trade flows. Bottom-up equipment shipment tallies triangulate against top-down food manufacturing capital expenditure surveys.
Assumption sets held energy subsidy regimes and regulatory enforcement timelines fixed while varying labor cost escalation trajectories and stainless-steel price volatility bands across the analysis window. Segmentation dimensions modeled include product type, heating technology, end-user scale, and capacity tier alongside geographic regulatory cluster. CAGRs derive from installed base replacement cycles and greenfield commissary buildout pipelines. Industry-specific forecast inputs encompass EU F-Gas refrigerant phase-down schedules and FDA sanitary design inspection frequency trends.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fabricators or accelerated subsidy withdrawal by EU member states would shift outcomes beyond modeled ranges. Cross-checking against food processing plant capital expenditure surveys from industrial equipment trade associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Cooking Sauces Market