
 Chocolate Syrup Market | 2026-2036
Chocolate Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Syrup Market Intelligence
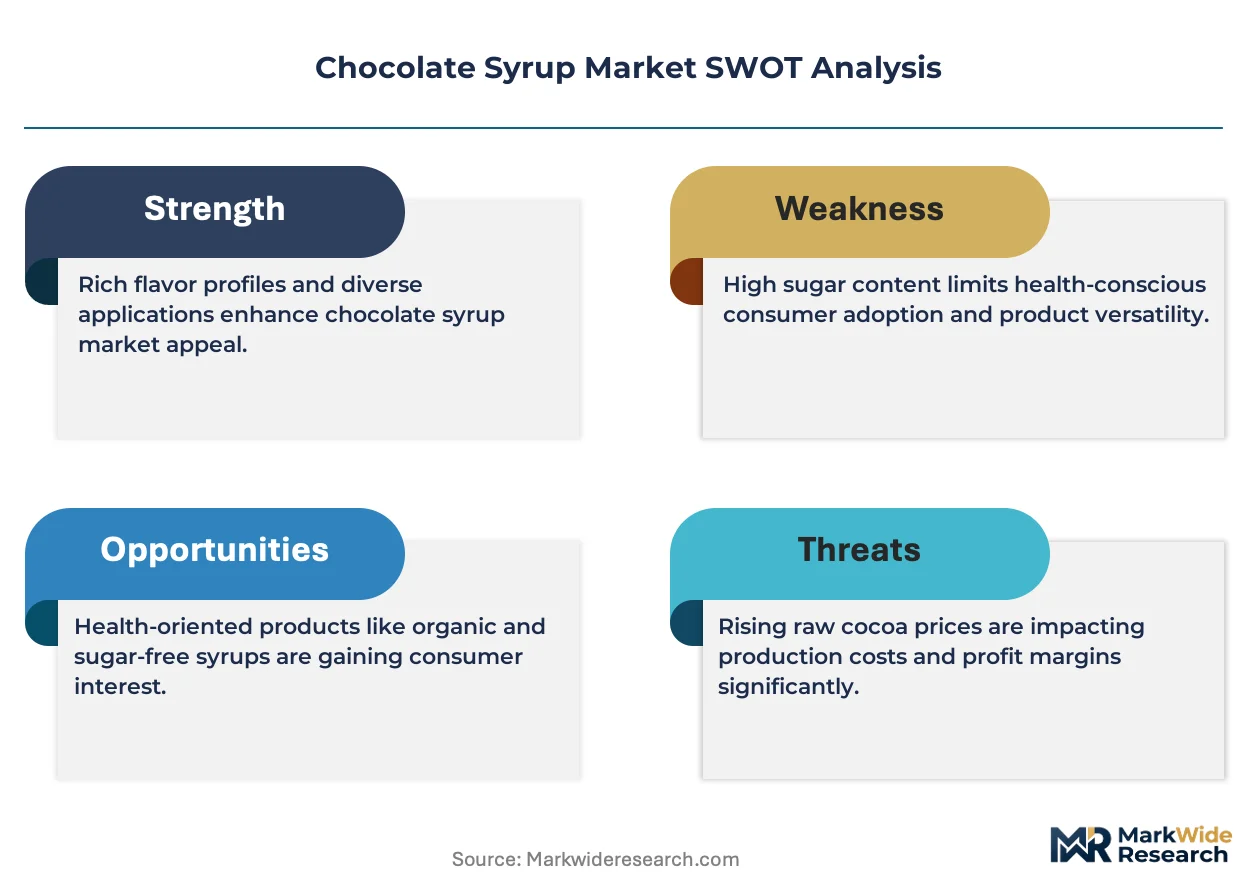
Organic and clean-label formulations are collapsing the distinction between premium and conventional chocolate syrups. This shift forces established brands to innovate beyond traditional offerings. The Hershey Company leverages its extensive retail distribution to introduce new product lines. In contrast, Monin S.A.S. specializes in the premium food service channel, supplying cafes and restaurants with a diverse flavor portfolio.
Chocolate syrup is a viscous condiment composed primarily of cocoa solids suspended in a sugar-based liquid, such as corn syrup or a sucrose solution. Its formulation is engineered for specific viscosity and flavor profiles, serving as a topping for desserts, a mix-in for beverages, or an ingredient in baking. While conventional syrup continues to lead in volume, sugar-free and dark syrup product types show significant growth, especially within the food service end-user segment. Squeeze bottles remain the dominant packaging type for retail channels due to consumer convenience.
Product formulation and labeling are governed by multiple regulatory bodies. The US FDA enforces standards for ingredients and nutritional information, while the EU's EFSA oversees food safety and allergen declarations. Global health guidelines, such as those from the WHO on sugar intake, indirectly shape new product development. Manufacturers must now balance compliance with these diverse standards against fluctuating cocoa commodity prices and evolving consumer health demands.
Market Dynamics
The central tension shaping the chocolate syrup market is the collision between consumer demand for clean-label, health-conscious ingredients and the product's inherent identity as an indulgent treat. This dynamic forces constant reformulation and repositioning by manufacturers globally.
Growth Catalysts
- Food Service Channel Growth:Expansion of coffee chains and dessert parlors, particularly in Asia-Pacific, increases bulk demand for syrups as a core ingredient and topping.
- Clean-Label Formulations:WHO guidelines on sugar intake are spurring development of organic and reduced-sugar syrups, opening a premium segment previously inaccessible to conventional products.
- Flavor Portfolio Diversification:The introduction of variants like dark chocolate, white chocolate, and salted caramel appeals to more sophisticated consumer palates, driving incremental purchases.
Market Restraints
- Cocoa Commodity Volatility:Price fluctuations for cocoa beans, primarily sourced from West Africa, directly impact manufacturing costs and create margin pressure for producers.
- Negative Health Perceptions:Public health campaigns against sugar and high-fructose corn syrup in markets like the United States and Europe create a structural headwind for conventional syrup sales.
- Ingredient Substitution Threat:The availability of alternative dessert toppings, including fruit-based coulis, caramel sauces, and nut butter spreads, provides consumers with numerous substitutes.
Strategic Opportunities
- Plant-Based and Vegan Syrups:Formulating products using oat or almond milk bases can capture the growing demographic of vegan and flexitarian consumers in developed markets.
- Functional Ingredient Fortification:Incorporating protein or fiber into syrup formulations allows brands to market products toward health-conscious consumers without sacrificing indulgence.
- Direct-to-Consumer E-Commerce:Online sales channels enable specialty and craft producers to bypass retail gatekeepers and build a direct relationship with niche consumer segments.
Industry Challenges
- Ethical Sourcing Verification:Manufacturers face significant operational complexity and cost in documenting and certifying their cocoa supply chains to meet demands for fair trade and sustainability.
- Reformulation Stability:Replacing sugar and corn syrup while maintaining the expected viscosity, flavor profile, and shelf life presents a considerable technical challenge for R&D teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Syrup Market |
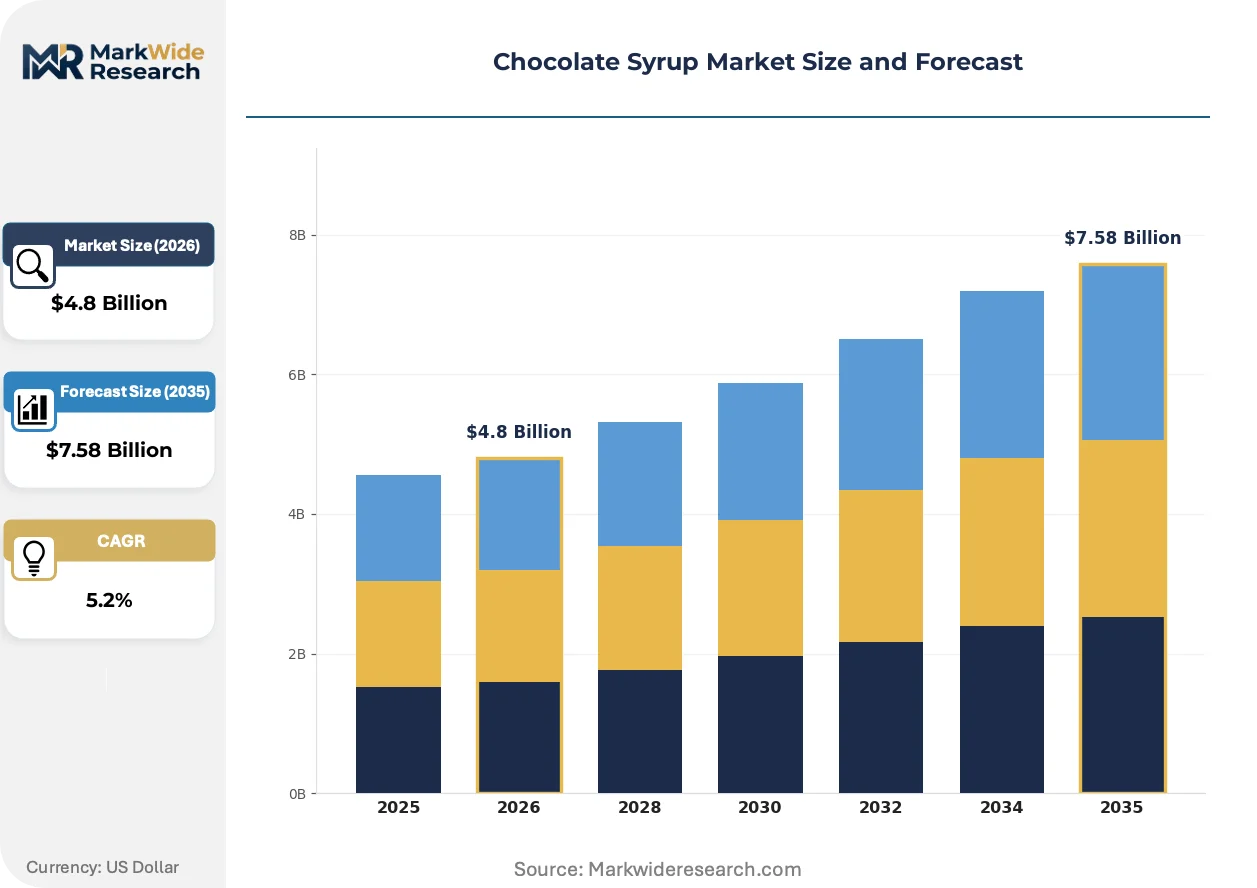
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Syrup, Conventional Syrup, Sugar-Free Syrup, Dark Syrup End User: Food Service, Retail, Bakeries, Home Consumers Packaging Type: Squeeze Bottles, Glass Jars, Pouches, Bulk Containers Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Specialty Stores |
| Companies Covered | The Hershey Company, Nestlé S.A., The J.M. Smucker Company, Torani, Monin S.A.S., Ghirardelli, Bosco Products, Inc., Hollander Chocolate, Inc., The Kroger Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Syrup Market Strategic Shifts & Innovations
Formulation science is at the core of market evolution, driven by a dual mandate for both cleaner ingredients and more complex flavor profiles. This shift redefines the product from a simple commodity topping into a sophisticated, value-added ingredient for both consumers and food service operators.
Advanced sugar-replacement systems, utilizing ingredients like allulose, monk fruit, and stevia blends, provide sweetness without the caloric load of sucrose or corn syrup. Premium brands and new market entrants are rapidly adopting these systems to appeal to health-conscious buyers. This technology is supplanting high-fructose corn syrup in new product development, altering the foundational chemistry of the category.
Global health frameworks, particularly the WHO's recommendations on reducing free sugar intake, are creating regulatory pressure. This influences national policies, such as front-of-pack nutrition labeling enforced by agencies like the US FDA and the EU's EFSA. The food service segment is most affected, now demanding compliant, lower-sugar formulations from suppliers to avoid negative menu labeling.
Consumer purchasing behavior is moving from acquiring a single, all-purpose syrup to curating a portfolio of flavors for specific applications like coffee, baking, or desserts. This trend disrupts the traditional retail model dominated by a single, large-format SKU, creating an opening for brands with diverse flavor offerings. This shift is most prominent within the at-home barista and gourmet dessert-making segments in North America and Europe.
Chocolate Syrup Market Segmentation
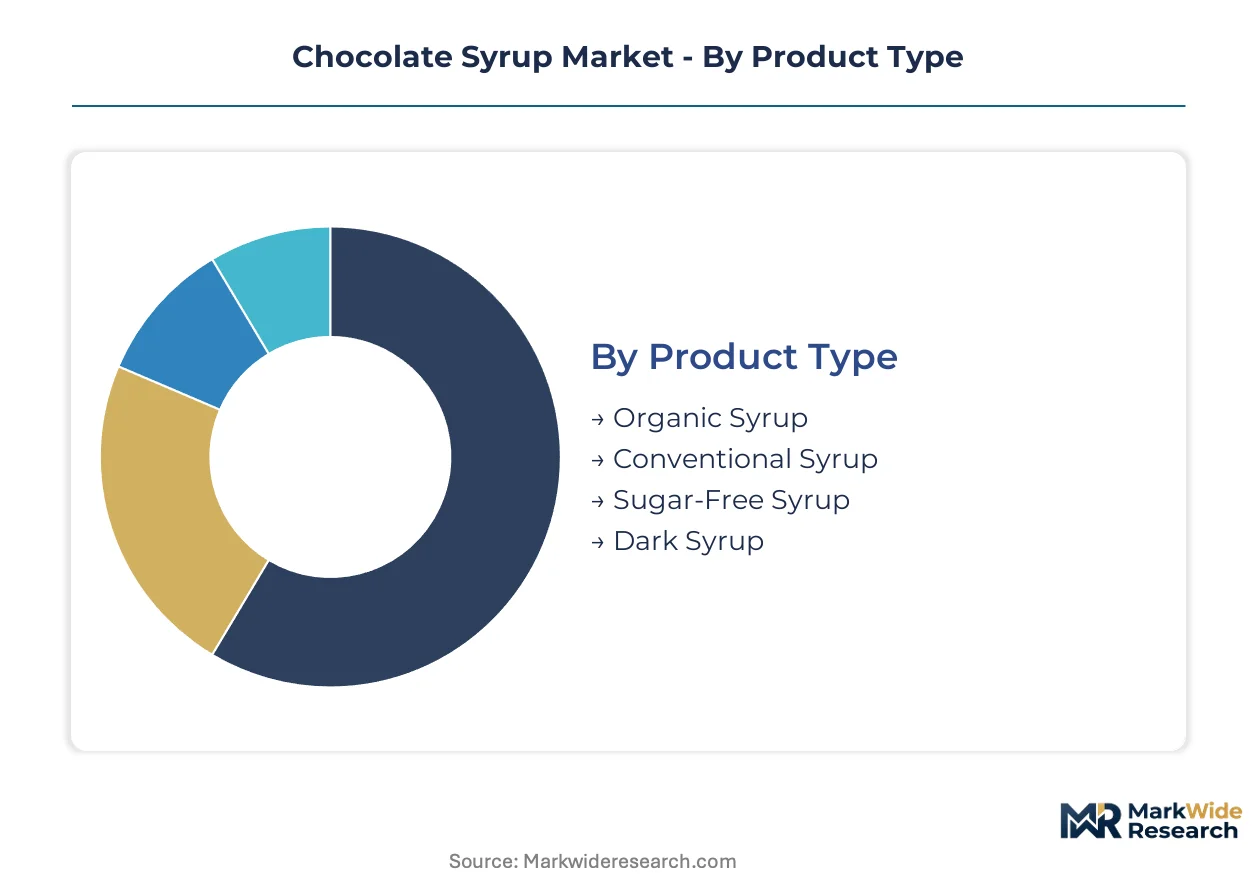
The chocolate syrup market differentiates across several key dimensions, reflecting diverse consumer preferences and varied application requirements. Understanding these segments provides clarity on demand drivers and strategic positioning for manufacturers. This granular view reveals how product innovation and distribution strategies are tailored to specific market niches.
Product Type:
Product types in the chocolate syrup market demonstrate distinct channel preferences, with some formulations designed for bulk food service procurement and others optimized for retail shelves.
- Conventional Syrup:Conventional syrup, typically formulated with high-fructose corn syrup or sucrose, represents the foundational offering in the category. Its widespread availability and cost-effectiveness drive significant volume in both retail channels across the United States and global food service operations.
- Sugar-Free Syrup:Sugar-free syrup utilizes advanced sweeteners like stevia, monk fruit, or allulose to deliver sweetness without added caloric load. Demand concentrates in developed markets such as Germany and the United Kingdom, driven by health-conscious consumers and WHO guidelines on sugar reduction.
- Organic Syrup:Organic syrup adheres to specific agricultural standards, appealing to consumers seeking natural ingredients and sustainable production methods.
- Dark Syrup:Dark syrup offers a richer, more intense cocoa flavor profile, often favored by specialty coffee shops and gourmet dessert parlors for premium applications.
By volume, Conventional Syrup leads the market. By growth pace, Sugar-Free Syrup is ahead, reflecting evolving health trends.
End User:
End-user segments dictate specific product attributes and packaging formats, aligning chocolate syrup formulations with distinct application requirements.
- Food Service:Food service encompasses cafes, restaurants, and dessert parlors that use chocolate syrup as an ingredient in beverages, desserts, and toppings. This segment demands bulk quantities and consistent quality, particularly in rapidly expanding Asian-Pacific markets like China and India, for operational efficiency.
- Retail:The retail segment includes supermarkets and hypermarkets, catering to individual consumers purchasing chocolate syrup for home use. Convenience-oriented packaging, such as squeeze bottles, drives sales in major markets like the United States and France, appealing to everyday household needs.
- Bakeries:Bakeries utilize chocolate syrup as a core ingredient for flavoring cakes, pastries, and other confectioneries, valuing consistent viscosity and heat stability.
- Home Consumers:Home consumers purchase chocolate syrup for personal consumption, using it as a topping for ice cream or a mix-in for milk and coffee at home.
The Food Service segment typically commands higher bulk volumes, while the Retail segment often yields higher per-unit margins due to consumer packaging.
Packaging Type:
Packaging types for chocolate syrup reflect varied cost structures and consumer convenience priorities, influencing both retail pricing and operational efficiency.
- Squeeze Bottles:Squeeze bottles, typically made from plastic, offer consumer convenience for controlled dispensing and are widely adopted for household use. Their popularity in retail channels across North America and Europe stems from ease of use and reduced mess for at-home applications.
- Bulk Containers:Bulk containers, including large plastic jugs or drums, are designed for high-volume storage and dispensing in commercial settings. Food service establishments and industrial bakeries in countries like Canada and Australia prefer these for cost-efficiency and reduced replenishment frequency.
- Glass Jars:Glass jars often cater to premium or specialty chocolate syrups, offering perceived quality and better product preservation for niche markets.
- Pouches:Pouches provide a lightweight and flexible packaging option, reducing material waste and offering refilling solutions for environmentally conscious consumers.
Squeeze Bottles dominate retail supply chains, while Bulk Containers are central to the food service supply network.
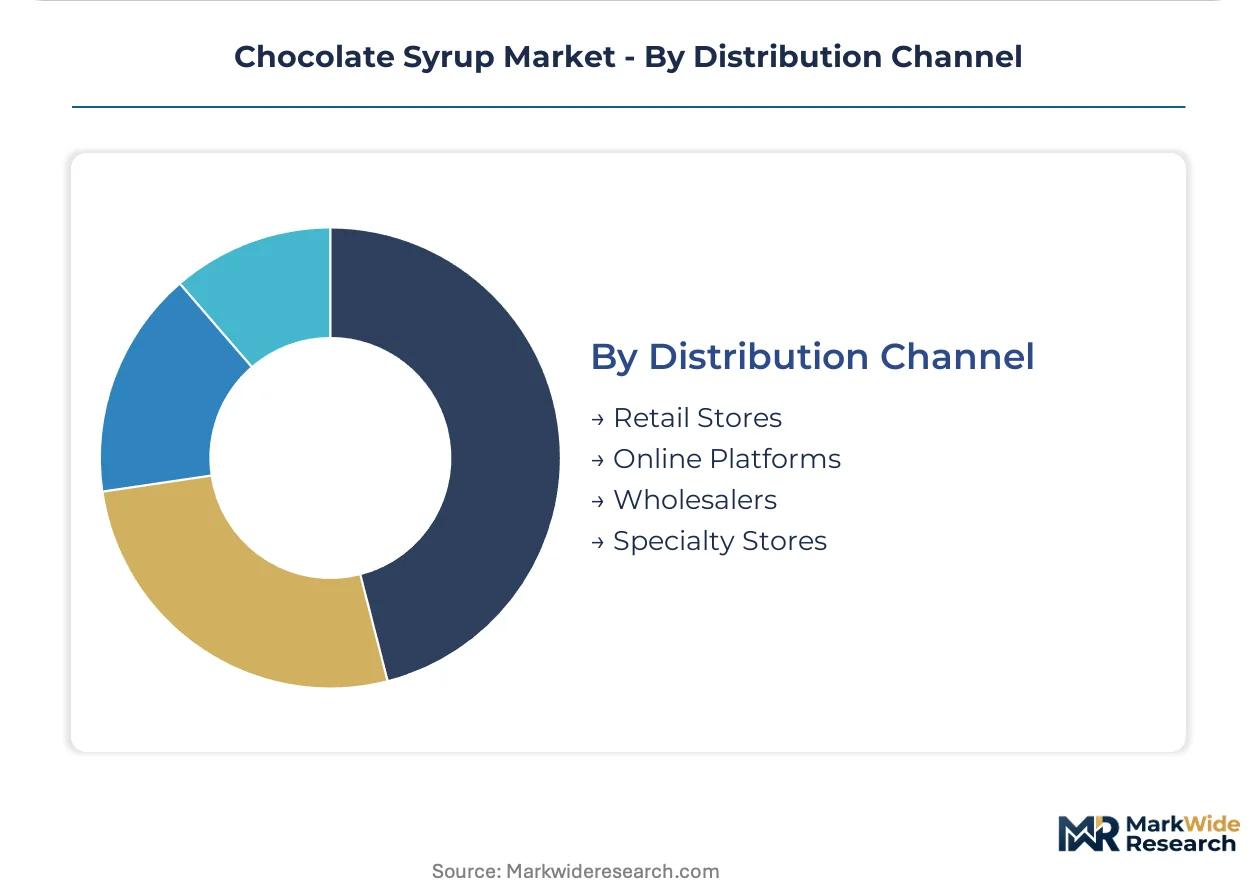
Distribution Channel:
Distribution channels are segmented by the type of customer they primarily serve, ranging from individual consumers to large commercial buyers.
- Retail Stores:Retail stores include supermarkets, hypermarkets, and convenience stores, acting as primary points of sale for consumer-packaged goods. This channel drives significant volume for chocolate syrup in established markets like the United States and Japan due to broad accessibility and impulse purchases.
- Online Platforms:Online platforms encompass e-commerce websites, direct-to-consumer brand sites, and online grocery delivery services for chocolate syrup. This channel experiences rapid growth in developed markets such as the United Kingdom and Germany, driven by consumer convenience and expanded product selection.
- Wholesalers:Wholesalers supply chocolate syrup in bulk to food service establishments, bakeries, and smaller retail outlets, prioritizing cost-efficiency and large-volume transactions.
- Specialty Stores:Specialty stores, including gourmet food shops and health food stores, cater to niche demand for organic, premium, or artisan chocolate syrup formulations.
Retail Stores represent a mature distribution channel, while Online Platforms demonstrate a rapidly evolving and expanding market presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chocolate syrup demand shows varied elasticity across regions, reflecting diverse economic conditions and consumer priorities. Developed markets like the United States exhibit lower price sensitivity for premium, specialty products, favoring quality and unique flavor profiles. Conversely, emerging economies often prioritize affordability, making conventional syrups more price-elastic and volume-driven.
United States
High demand for convenience in retail and diverse flavor profiles in food service drives chocolate syrup consumption. The US FDA regulates ingredient labeling and nutritional claims for all chocolate syrup products sold domestically. Major food manufacturers in Chicago and California innovate new product lines, responding to evolving consumer tastes.
Germany
Consumer preference for reduced-sugar and organic options shapes product development within the German market. EFSA guidelines influence food safety and allergen declarations for imported and domestic syrups, ensuring high standards. Berlin's vibrant cafe culture fuels demand for premium, specialty chocolate syrups, especially in urban centers.
China
Rapid expansion of coffee chains and dessert parlors increases bulk syrup procurement across China's urban centers. China's SAMR oversees food quality and safety standards for the growing market, impacting local and international suppliers. Shanghai's food service sector demands large volumes of consistent quality syrup for beverages and desserts.
India
Growing disposable incomes and urbanization boost demand for indulgent treats and cafe experiences across India. The FSSAI mandates specific food safety and quality parameters for all food products, including chocolate syrups. Delhi and Mumbai observe significant growth in dessert parlors utilizing chocolate syrup as a core ingredient.
United Kingdom
Strong consumer focus on health and wellness drives the sugar-free and clean-label segments in the United Kingdom. The UK's Food Standards Agency enforces labeling requirements and ingredient transparency for all food items. London's diverse culinary scene embraces premium and specialty syrup varieties, particularly in gourmet cafes.
Chocolate Syrup Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the chocolate syrup market. The market exhibits a tiered structure, with established food conglomerates alongside specialized premium brands and niche craft producers. Strategic archetypes include global diversified food giants, regional specialty manufacturers, and innovative clean-label startups. Portfolio diversification into health-conscious formulations and geographic expansion remain key competitive moves for market participants.
Within the global diversified food giants, The Hershey Company represents a major force, leveraging extensive retail distribution for conventional offerings. Monin S.A.S. exemplifies a specialized premium brand, focusing on the food service channel with a diverse flavor portfolio for cafes and restaurants. The J.M. Smucker Company occupies a position among established consumer packaged goods entities, supplying chocolate syrups for household use. These players anchor different segments of the market, from mass-market retail to high-end cafe applications, reflecting distinct strategic priorities.
| Leading Market Players |
|---|
| The Hershey Company |
| Nestlé S.A. |
| The J.M. Smucker Company |
| Torani |
| Monin S.A.S. |
| Ghirardelli |
| Bosco Products, Inc. |
| Hollander Chocolate, Inc. |
| The Kroger Co. |
| Others |
Cost & Logistics Intelligence
Two-week lead times for specialty cocoa beans from West Africa directly influence the cost structure of premium chocolate syrups, impacting retail pricing strategies.
Pricing Analysis
The refill revenue tier, generated by bulk container sales to food service operators, drives lifetime value for commercial chocolate syrup suppliers. Pricing in this market primarily follows a transactional model, tiered across conventional, sugar-free, and premium organic formulations. Brand premium and specific quality grades, such as organic certification, differentiate prices significantly. Cost compression in the conventional segment stems from consumer health perceptions, while premium offerings face upward pressure from fluctuating cocoa commodity prices. Retail consumers purchasing conventional syrup exhibit high price sensitivity, whereas specialty cafes sourcing dark syrup prioritize consistent quality over marginal cost savings.
Supply Chain Analysis
West Africa, particularly countries like Cote d'Ivoire and Ghana, anchors global cocoa bean production, a critical raw material for chocolate syrup. The supply chain draws from corn syrup and sucrose producers in North America and Europe, alongside specialized ingredient suppliers for alternative sweeteners. Cocoa commodity price volatility represents a structural risk, directly impacting manufacturing costs for all product tiers. Distribution runs through a dual model, with retail channels relying on supermarkets and hypermarkets, while food service establishments source via specialized wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chocolate syrup market represents a defensive-moat story, due to strong brand loyalty and regulatory entrenchment. This creates significant switching costs for consumers and food service operators.
For Market Incumbents:Compound investments in advanced sugar-replacement systems to neutralize clean-label startup threats. Incumbents must leverage retail distribution and brand equity for diversified product lines, like organic and dark syrups. Deepen vertical integration into alternative sweetener sourcing for input cost volatility. Focus R&D on maintaining viscosity and flavor with reduced sugar content.
For New Entrants and Emerging Players:Differentiate on plant-based and functional ingredient fortifications for health-conscious consumers. The gourmet cafe segment in developed markets, seeking unique flavor profiles, presents a penetrable niche. Offer specialized dark chocolate or single-origin cocoa syrups. Utilize direct-to-consumer e-commerce platforms to build brand identity.
For Investors and Strategic Acquirers:Long-term, this sits as a resilient consumer staple play because of chocolate syrup's enduring role as an indulgent treat, albeit with evolving health parameters. Target innovative clean-label brands or regional specialty manufacturers with strong food service presence. Focus on companies demonstrating robust R&D in sugar alternatives and sustainable cocoa sourcing. The signal to watch is widespread adoption of front-of-pack nutrition labeling.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Expanding into organic and sugar-free formulations captures health-conscious consumers in Germany. |
| Sustainable Sourcing Certification | Verifying cocoa supply chains addresses ethical consumer demands and regulatory pressures. |
| E-commerce Channel Expansion | Direct-to-consumer platforms enable niche brands to reach specialty segments in North America. |
| Food Service Partnership Programs | Collaborating with coffee chains and dessert parlors secures bulk volumes in Asian-Pacific markets. |
| Advanced Sweetener R&D | Developing new allulose and monk fruit blends meets WHO guidelines on sugar reduction. |
Research Approach
The analysis maps conventional, sugar-free, organic, and dark syrup sub-sectors, each validated through primary interviews with R&D directors, procurement managers, and brand managers. Secondary research complemented this, drawing from US FDA and EU EFSA regulatory filings, trade association reports, and customs data. Bottom-up market sizing was triangulated with top-down validation.
Forecast outputs were rigorously validated against external industry benchmarks, ensuring consistency across the analysis window. The analytical framework modeled dimensions including product type, end user, packaging type, distribution channel, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included cocoa commodity price forecasts and sugar reduction guideline adoption rates.
Forecasts assume regulatory continuity in US FDA and EU EFSA regimes; material policy shifts regarding sugar or clean-label standards would require re-modeling. Geopolitical shifts impacting cocoa supply or rapid advancements in alternative sweeteners represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Hot Sauce Market