
 Data Democratization in Healthcare Market | 2026-2036
Data Democratization in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Data Democratization in Healthcare Market Insights
The United States is rewriting competitive dynamics in healthcare data platforms through massive cloud infrastructure build-outs and federal interoperability mandates. Microsoft leverages its Azure health data services to anchor hospital system migrations, while Amazon Web Services sustains dominance through specialized analytics workloads for payers. Oracle competes via vertical integration into clinical databases and enterprise resource planning systems.
Data democratization in healthcare refers to the architectural and organizational practice of making clinical, operational, and financial data accessible to non-technical users through governed self-service interfaces, typically employing cloud-native architectures with role-based access controls and FHIR-compliant APIs. Its primary purpose is to accelerate clinical decision-making and operational improvement by eliminating traditional IT bottlenecks in data retrieval. Cloud Computing leads technology adoption as health systems retire on-premise data warehouses, while AI represents the fastest-expanding capability layer as vendors embed predictive models directly into clinician workflows. Among end users, Hospitals command the largest implementation budgets, though Research Institutions are capturing disproportionate growth in genomics and real-world evidence platforms.
The FDA's clinical decision support software guidance, HIPAA security rule provisions, and the ONC's information blocking regulations collectively determine product design requirements and go-to-market viability for platform vendors. These frameworks shape demand by mandating standardized APIs, patient access provisions, and algorithmic transparency that vendors must engineer into core architectures. Stakeholders should monitor how emerging state-level privacy laws and proposed federal AI governance frameworks alter compliance burdens and competitive differentiation in platform procurement decisions.
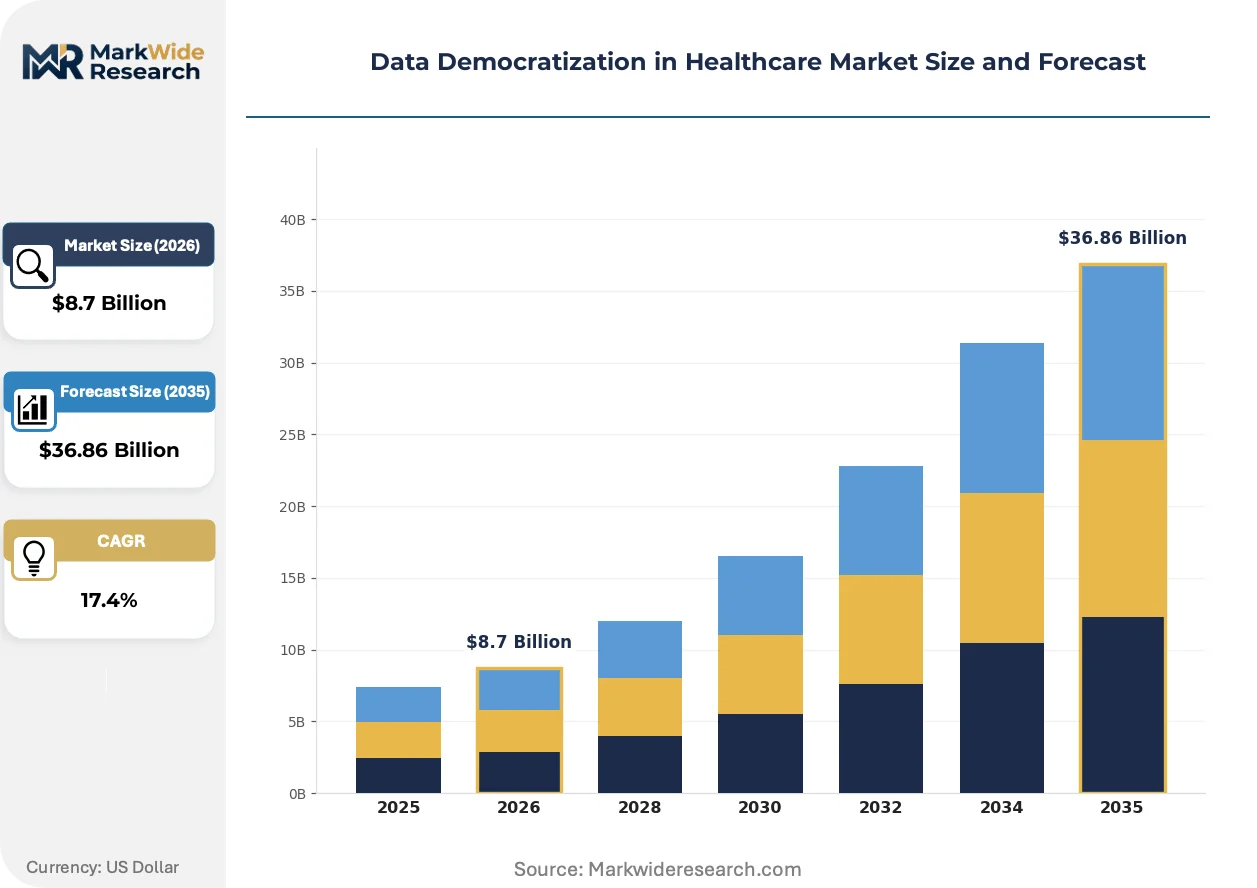
Market Dynamics
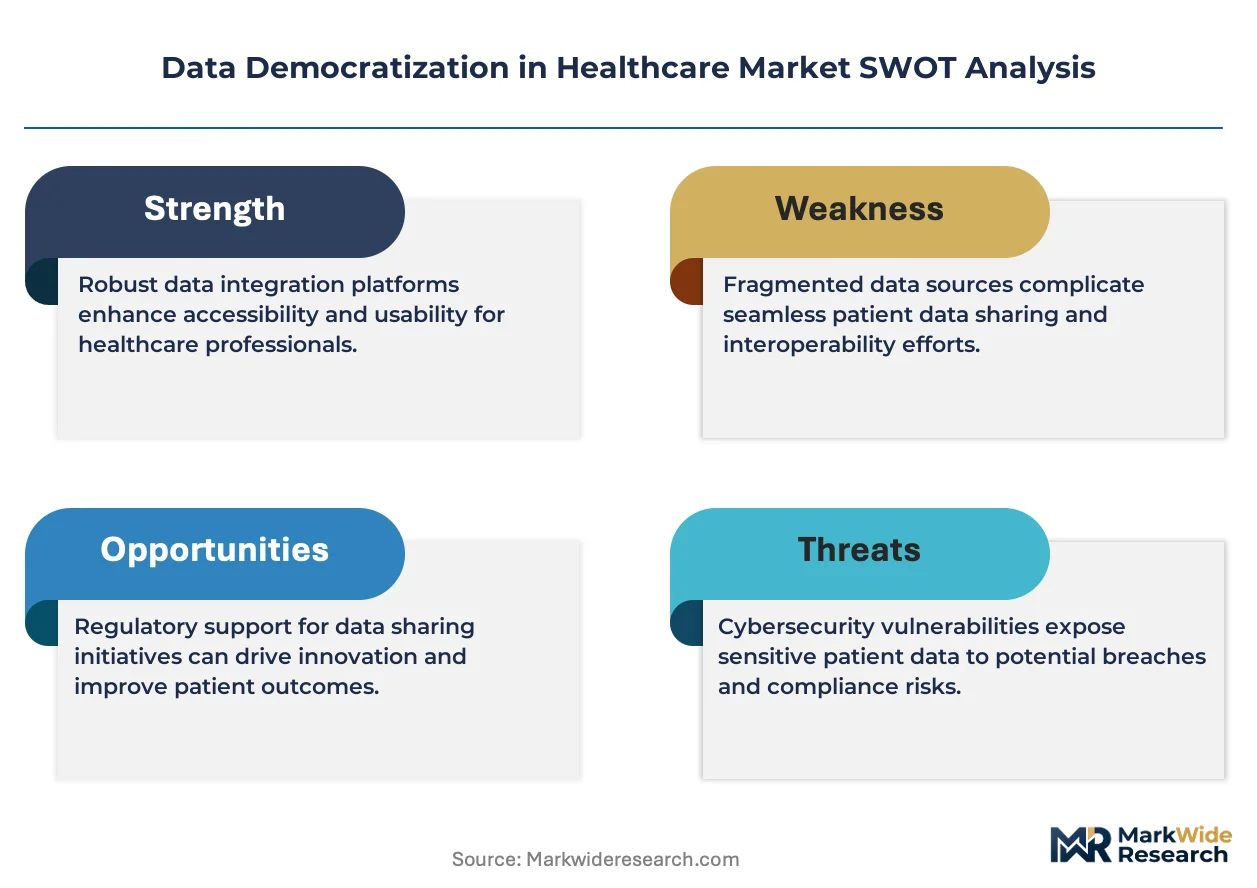
Cloud-native architectures are compressing data access latency from weeks to minutes, forcing health systems to restructure IT governance models around federated analytics rather than centralized data warehouses.
Growth Catalysts
- FHIR R4 APIs:The ONC's information blocking regulations mandate standardized data exchange protocols, compelling EHR vendors to expose patient data through interoperable interfaces that self-service platforms consume directly.
- Clinical workforce pressure:Nursing shortages and physician burnout are driving hospital executives to eliminate ticket-based reporting queues that delay bedside decisions.
- Real-world evidence mandates:The FDA's expanded guidance on using observational data for regulatory submissions is pushing pharmaceutical sponsors to deploy governed analytics sandboxes for epidemiologists.
Market Restraints
- Technical debt in legacy EHRs:Cerner and Epic installations built on MUMPS architectures require expensive abstraction layers to expose modern APIs, inflating implementation budgets.
- State privacy fragmentation:California's Consumer Privacy Act and Washington's My Health My Data Act create conflicting consent management requirements that complicate multi-state health system deployments.
- Cybersecurity insurance costs:Ransomware attacks against hospital data lakes have tripled premiums for cyber coverage, diverting capital from analytics infrastructure.
Strategic Opportunities
- Genomic data integration:Cancer centers in Texas and Massachusetts are building FHIR-based repositories linking tumor sequencing to clinical outcomes, creating templates for precision medicine platforms.
- Medicaid managed care:State agencies in Ohio and Arizona are procuring population health dashboards to monitor social determinants metrics, opening public-sector revenue streams.
- Edge computing convergence:Ambulatory surgery centers are deploying lightweight analytics nodes that preprocess data before cloud transmission, reducing bandwidth costs for rural networks.
Industry Challenges
- Biomedical informatics talent scarcity:Health systems compete with technology vendors for data engineers who understand both HL7 message structures and cloud data pipelines.
- Algorithmic audit requirements:The FDA's predetermined change control plans demand documentation rigor that most hospital IT departments lack, slowing AI deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Democratization in Healthcare Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Machine Learning, Blockchain, AI End User: Clinics, Hospitals, Research Institutions, Payers Application: Patient Engagement, Data Integration, Analytics, Reporting Service Type: Consulting, Support, Implementation, Training |
| Companies Covered | IBM, Amazon Web Services, Oracle, Microsoft, Innovaccer, Health Catalyst, Optum, Arcadia, CitiusTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Democratization in Healthcare Market Trends and Innovations
Healthcare data platforms are converging around zero-trust security models and containerized analytics workloads that abstract underlying infrastructure complexity from clinical end users.
Zero-trust network architecture is virtualizing perimeter-based security in hospital data environments. Health systems in Minnesota and Florida are replacing VPN-dependent access with continuous authentication protocols that verify every data query against user context and patient consent flags. This shift is compressing the attack surface for insider threats while enabling remote clinician access to sensitive registries.
The EU AI Act's risk classification framework is reshaping vendor development roadmaps for clinical decision support tools. Developers must now document training data provenance and performance metrics across demographic subgroups before deploying algorithms in European health networks. German university hospitals are piloting conformity assessment procedures that will likely propagate to US institutions seeking transatlantic data partnerships.
Self-service analytics procurement is consolidating around subscription models that unbundle implementation from software licensing. Integrated delivery networks in Pennsylvania and Georgia are negotiating outcome-contingent contracts where platform fees scale with measured reductions in length-of-stay or readmission rates. This restructures vendor incentives toward measurable operational impact rather than feature proliferation.
Data Democratization in Healthcare Market Segmentation
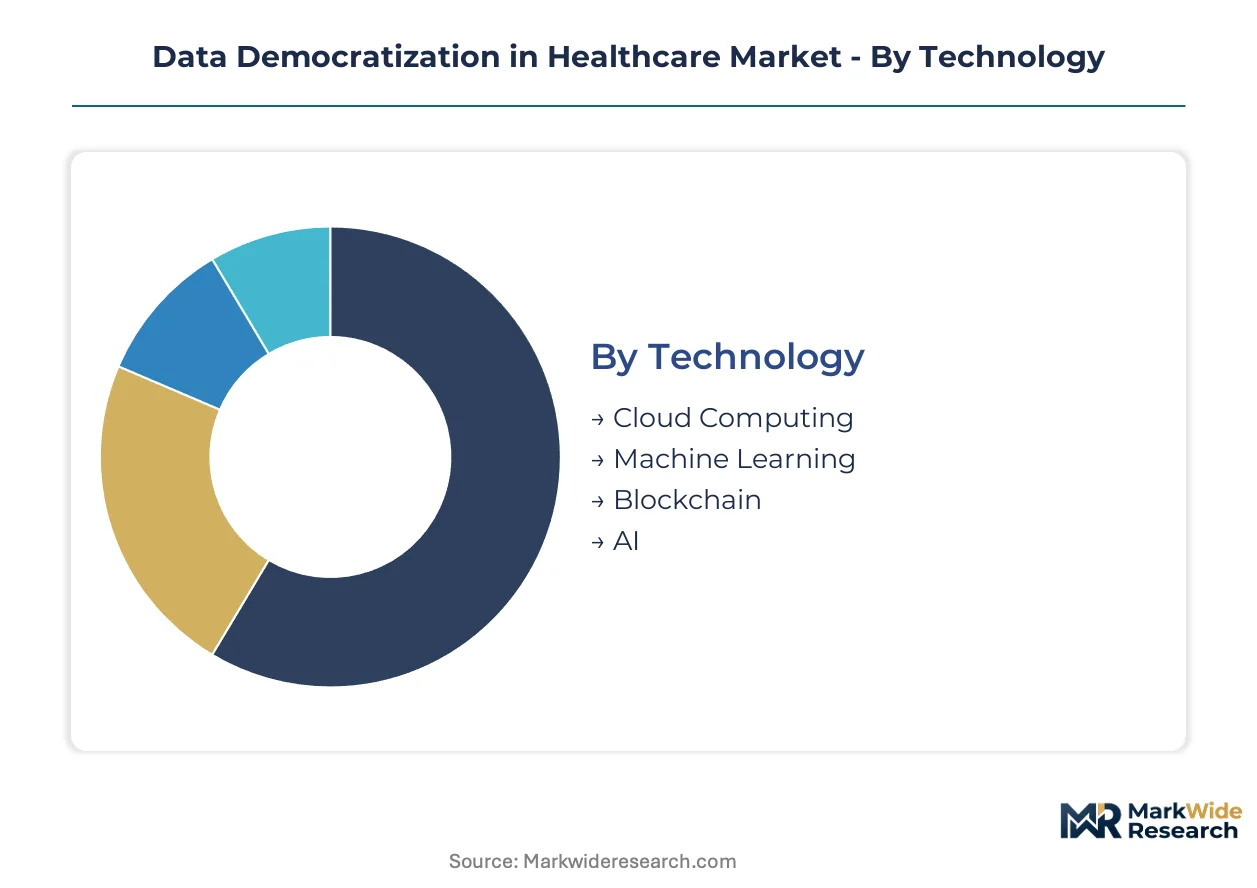
Technology deployment patterns in healthcare data democratization diverge sharply between mature infrastructure categories and emerging capability layers. Vendors must align product roadmaps with where health systems sit on this maturity curve.
Technology:
Mature cloud architectures anchor current spending while emerging AI layers capture disproportionate investment growth.
- Cloud Computing:Health systems in Minnesota and Texas are retiring on-premise data warehouses for Azure and AWS-native architectures. Demand concentrates among integrated delivery networks pursuing enterprise-wide data lakes with FHIR-compliant APIs.
- AI:Predictive models embedded directly into clinician workflows require continuous authentication protocols and algorithmic audit trails. FDA guidance on predetermined change control plans shapes vendor development priorities for bedside decision support.
- Machine Learning:Pattern recognition systems for readmission risk stratification.
- Blockchain:Immutable consent management for multi-site clinical trials.
Cloud Computing handles the majority of throughput; AI is the fastest mover on share.
End User:
Customer archetypes span from high-volume transactional environments to research-intensive institutions with specialized governance requirements.
- Hospitals:Nursing shortages and physician burnout are driving executives to eliminate ticket-based reporting queues. Epic and Cerner installations require expensive abstraction layers to expose modern APIs.
- Research Institutions:Genomic data integration for precision medicine platforms demands FHIR-based repositories linking tumor sequencing to clinical outcomes. Cancer centers in Massachusetts are building templates for multi-site deployment.
- Clinics:Ambulatory settings prioritize lightweight analytics nodes.
- Payers:Medicaid managed care agencies procure population health dashboards.
Hospitals command the largest implementation budgets; Research Institutions are expanding most quickly on platform investment.
Application:
Use case prioritization reflects tension between operational efficiency mandates and regulatory transparency requirements.
- Analytics:Self-service interfaces compress data access latency from weeks to minutes. Health systems restructure IT governance around federated analytics rather than centralized warehouses.
- Patient Engagement:ONC information blocking regulations mandate standardized patient access provisions. Portals must integrate with EHR workflows while maintaining HIPAA security rule compliance.
- Data Integration:Abstraction layers for legacy MUMPS architectures.
- Reporting:Real-world evidence submissions for FDA regulatory filings.
Analytics absorbs the dominant share of platform investment; Patient Engagement is climbing the fastest on procurement priority.
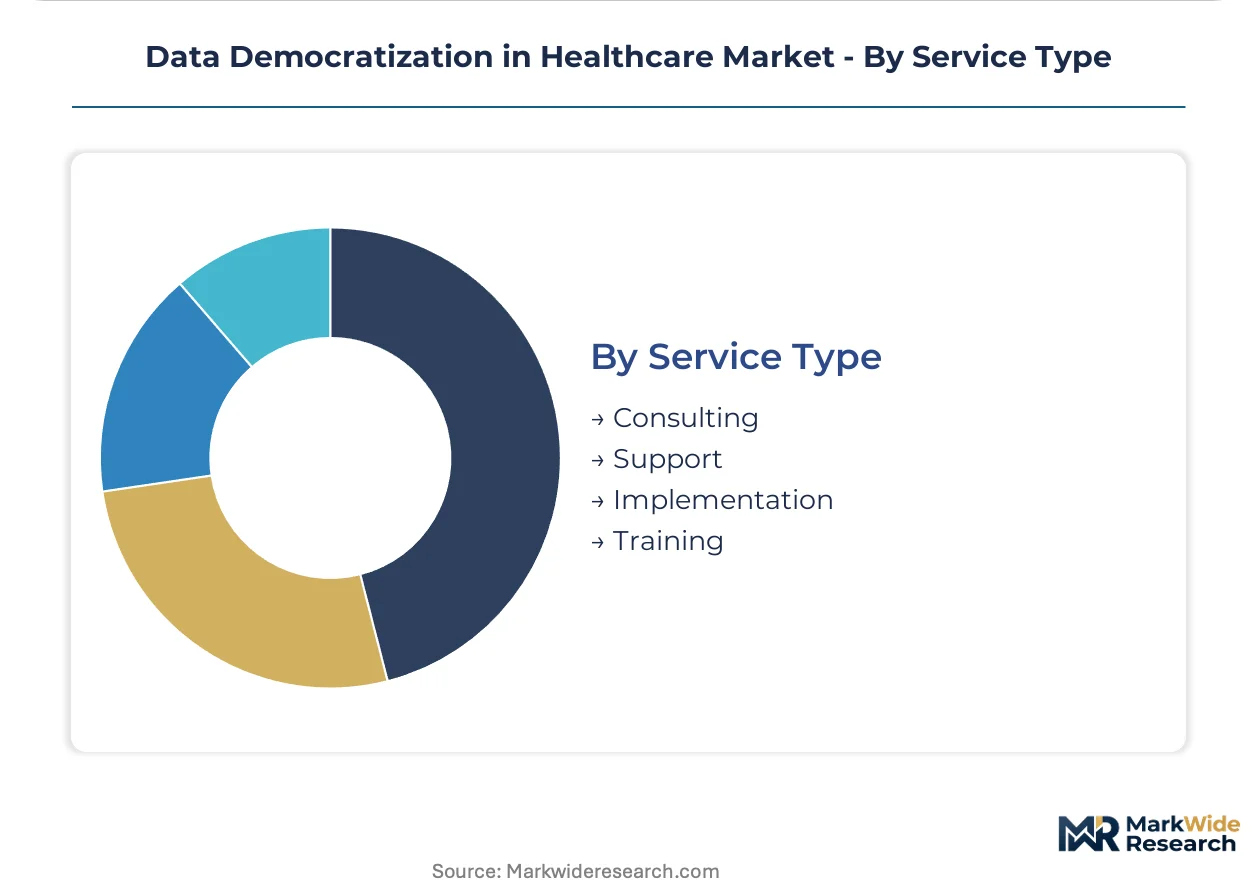
Service Type:
Revenue models are shifting from perpetual licensing toward outcome-contingent relationships that tie fees to measurable operational impact.
- Implementation:Cloud migration projects for hospital data lakes face tripled cybersecurity insurance premiums following ransomware attacks. Capital allocation tensions between security infrastructure and analytics capabilities constrain deployment timelines.
- Consulting:Biomedical informatics talent scarcity pits health systems against technology vendors for data engineers who understand both HL7 message structures and cloud pipelines. Firms command premium rates for FHIR expertise.
- Training:Change management for clinical workflow adoption.
- Support:Continuous authentication protocol maintenance.
Implementation represents the largest revenue pool; Consulting is gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud hyperscalers cluster in the United States while European health networks navigate stricter algorithmic governance, fragmenting deployment patterns across jurisdictions.
United States
Integrated delivery networks in Pennsylvania and Georgia are negotiating outcome-contingent contracts where platform fees scale with measured reductions in length-of-stay. The FDA's clinical decision support software guidance shapes vendor development priorities for bedside decision support. Microsoft leverages Azure health data services to anchor hospital system migrations in Minnesota and Texas.
Germany
University hospitals are piloting conformity assessment procedures under the EU AI Act's risk classification framework for clinical decision support tools. EMA documentation requirements for training data provenance are reshaping vendor development roadmaps. Berlin-based health networks are building templates for transatlantic data partnerships that satisfy both GDPR and HIPAA provisions.
United Kingdom
NHS trusts are procuring population health dashboards to monitor operational metrics across integrated care systems. The country's national health technology regulator is evaluating algorithmic transparency standards for AI-enabled diagnostic platforms. London health data networks are deploying federated analytics architectures that preserve patient privacy across hospital trusts.
Japan
PMDA guidance on software as a medical device is accelerating cloud migration timelines for hospital data lakes. METI funding programs support FHIR-based interoperability pilots connecting regional medical centers. Osaka-based cancer centers are building genomic data repositories linking tumor sequencing to clinical outcomes.
Australia
TGA software regulations are shaping procurement criteria for clinical decision support platforms in Queensland and Victoria. State health departments are deploying self-service analytics to reduce ticket-based reporting queues that delay clinical decisions. Sydney research institutions are capturing disproportionate growth in real-world evidence platforms for pharmaceutical sponsors.
Data Democratization in Healthcare Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying niche capabilities. The vendor base spans three tiers: hyperscale cloud providers with health-specific services, vertical healthcare analytics firms with EHR integration expertise, and boutique consultancies with FHIR implementation specialization. Strategic moves concentrate on outcome-contingent contracting structures and federated data governance partnerships that reduce client switching costs.
Among cloud-native platform providers, Amazon Web Services, Microsoft, and Oracle occupy positions representing distinct competitive archetypes. Amazon Web Services exemplifies the workload-specialization approach through analytics infrastructure for payer organizations. Microsoft anchors the enterprise productivity integration vector, leveraging existing hospital system relationships. Oracle represents vertical consolidation into clinical databases and enterprise resource planning systems, competing through backward integration rather than pure-play cloud services.
| Leading Market Players |
|---|
| IBM |
| Amazon Web Services |
| Oracle |
| Microsoft |
| Innovaccer |
| Health Catalyst |
| Optum |
| Arcadia |
| CitiusTech |
| Others |
Pricing and Supply Chain Analysis
Cloud hyperscaler concentration in the United States anchors margin pools downstream in implementation services and specialized consulting. Health systems negotiating enterprise data lake contracts face pricing power asymmetry against AWS, Azure, and Google Cloud, while regional system integrators capture value through FHIR expertise and change management services.
Pricing Analysis
FDA guidance on clinical decision support software dictates the pricing tier structure for healthcare data platforms. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-wide deployments with full AI capabilities from departmental analytics and basic reporting modules. Price differentiation rests on certification level for algorithmic audit trails and customization depth for EHR integration. Cost compression in standard tiers is intensifying because health systems are consolidating vendor relationships. Medicaid managed care agencies exhibit highest price sensitivity; research institutions with pharmaceutical sponsor funding show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent edge computing nodes. Component sourcing concentrates in Taiwan for semiconductors, South Korea for memory modules, and the United States for specialized networking equipment. Raw material dependencies include silicon wafers, rare earth elements for server magnets, and lithium for backup power systems. Single-source vulnerability in advanced GPU supply creates procurement bottlenecks for AI-enabled platforms. Distribution runs through value-added resellers with healthcare vertical expertise and direct enterprise sales teams for large integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data democratization in healthcare builds defensive moats through regulatory entrenchment—ONC information blocking mandates and FDA algorithmic guidance create compliance barriers that favor established vendors with documentation infrastructure and audit-ready architectures.
For Market Incumbents: Entrench market position by deepening backward integration into clinical database management and enterprise resource planning systems. Acquire boutique FHIR implementation specialists to capture consulting margin pools. Cloud hyperscalers expanding health-specific service portfolios pose the primary substitution threat; counter through outcome-contingent contracting that ties fees to length-of-stay reductions. For New Entrants and Emerging Players: Establish a beachhead in Medicaid managed care population health dashboards, where public-sector procurement cycles favor agile vendors over entrenched incumbents. Target ambulatory surgery centers in rural networks with lightweight edge analytics nodes. Lead with cybersecurity insurance cost reduction as the go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertical healthcare analytics firms with proven EHR integration expertise and existing hospital system relationships. Long-term viability hinges on regulatory compliance infrastructure rather than pure technology differentiation. Watch FDA enforcement patterns on predetermined change control plans as the inflection signal for AI-enabled platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification Investment | ONC information blocking mandates require standardized interfaces for market access. |
| Outcome-Contingent Contracting | Pennsylvania and Georgia health systems tie platform fees to readmission rate reductions. |
| Genomic Data Repository Partnership | Massachusetts cancer centers build precision medicine templates for multi-site deployment. |
| Zero-Trust Security Architecture Deployment | Minnesota and Florida health systems replace VPN access with continuous authentication protocols. |
| EU AI Act Conformity Assessment | German university hospitals pilot procedures that propagate to transatlantic data partnerships. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital CIOs, biomedical informatics directors, health system procurement committees, and GPO contracts managers; and secondary validation against CMS Medicare data, hospital procurement databases, FDA guidance documents, and ONC interoperability filings. Bottom-up sizing of platform deployments triangulated with top-down cloud hyperscaler health vertical revenue disclosures.
Forecast inputs span technology deployment patterns, end-user budget cycles, and regulatory compliance timelines across the analysis window. Segmentation dimensions modeled include cloud architecture maturity, AI capability integration depth, organization scale, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to historical EHR migration patterns and projected FHIR API penetration rates. Inputs include nursing shortage severity indices and pharmaceutical sponsor real-world evidence spending commitments.
Stress conditions across cybersecurity insurance premium trajectories, state privacy law fragmentation, and AI algorithmic audit requirement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about federal interoperability mandate enforcement and cloud infrastructure cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Medical Record Management System Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
US Population Health Management Market
Health Data Management
Big Data Healthcare Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Healthcare Predictive Analytics Market