
 Global Electronic Aspirin Market | 2026-2036
Global Electronic Aspirin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Aspirin Market Foresight
Hospital procurement consortiums is reshaping how electronic aspirin devices reach end users, with group purchasing organizations now screening suppliers for cybersecurity certifications and remote monitoring capabilities. Medtronic leverages its cardiac rhythm management infrastructure to cross-sell neurostimulation platforms into pain management service lines. Autonomic Technologies, Inc. anchors its position through exclusive partnerships with headache specialty centers in the United States and Western Europe. ElectroCore, Inc. differentiates by pursuing non-invasive vagus nerve stimulation pathways rather than implantable device architectures.
Electronic aspirin denotes digitally-enabled drug delivery and neuromodulation systems designed to replace or augment traditional acetylsalicylic acid therapy through programmable dosing, bioelectronic stimulation, or connected adherence monitoring. These devices typically incorporate microprocessor-controlled dispensing mechanisms, patient biometric sensors, and encrypted data transmission protocols to enable real-time therapeutic adjustment and adverse event flagging. Wearable device formats currently dominate revenue contribution due to recurring electrode and adhesive consumable requirements, while smart pill segments with embedded ingestible sensors represent the fastest-expanding category as pharmaceutical manufacturers seek compliance verification partnerships. Mobile app integration technology captures disproportionate margin pools through subscription-based clinician dashboard licensing rather than one-time hardware sales.
FDA breakthrough device pathways and EU MDR technical documentation requirements are elevating clinical evidence thresholds for market authorization, effectively filtering out early-stage developers lacking randomized trial capabilities. Japan's PMDA has introduced streamlined review tracks for software-as-medical-device pain management applications, accelerating time-to-market for Bluetooth-connected dosing platforms. Stakeholders must monitor evolving cybersecurity guidance from FDA and Health Canada, as connected analgesic devices face expanding post-market surveillance obligations for vulnerability patching and breach notification protocols.
Market Dynamics
FDA breakthrough device designations and EU MDR compliance timelines are compressing product development cycles, forcing developers to front-load clinical evidence generation before commercialization. This regulatory acceleration is filtering out early-stage developers lacking randomized trial capabilities while rewarding established players with existing infrastructure.
Growth Catalysts
- Japan's PMDA streamlined review tracks:Software-as-medical-device pain management applications face accelerated time-to-market for Bluetooth-connected dosing platforms, reducing authorization delays from 24 months to under 12 months.
- Wearable nerve stimulator procurement:Chronic pain clinics in Germany and the United States are expanding device procurement as alternatives to oral analgesics, driven by opioid reduction mandates and reimbursement code expansions.
- Home care aging demographics:Japanese elderly populations seek non-pharmacological pain interventions, creating sustained demand for patient-operated neuromodulation systems with simplified interfaces.
Market Restraints
- EU MDR technical documentation requirements:Clinical evidence thresholds for market authorization have elevated substantially, filtering out developers lacking randomized trial capabilities and extending time-to-revenue by 18-36 months.
- Silver and conductive polymer input volatility:Electrode manufacturing depends on precious metal supply chains concentrated in South African and Russian mining operations, exposing margins to commodity price swings.
- Implantable device substitution threat:Spinal cord stimulation systems from cardiac rhythm management divisions offer deeper neural targeting, capturing severe chronic pain cases that might otherwise trial external neuromodulation.
Strategic Opportunities
- Underpenetrated Brazilian outpatient networks:ANVISA has established abbreviated pathways for Class II pain management devices, enabling first-mover positioning in Latin America's largest private healthcare market.
- Reimbursement code innovation:CMS and commercial payers in the United States are creating discrete billing categories for remote therapeutic monitoring, enabling subscription revenue models beyond hardware sales.
- AI-embedded dosing algorithms:Machine learning integration with biometric sensors enables real-time therapeutic adjustment, differentiating premium tiers from basic programmable devices.
Industry Challenges
- Cybersecurity engineering talent scarcity:FDA and Health Canada post-market surveillance obligations for vulnerability patching require dedicated security operations centers, competing for talent against broader medical device and pharmaceutical sectors.
- Multi-jurisdiction certification synchronization:Simultaneous FDA 510(k), EU MDR, and PMDA submissions demand redundant clinical datasets and quality management system audits, straining mid-cap development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Aspirin Market |
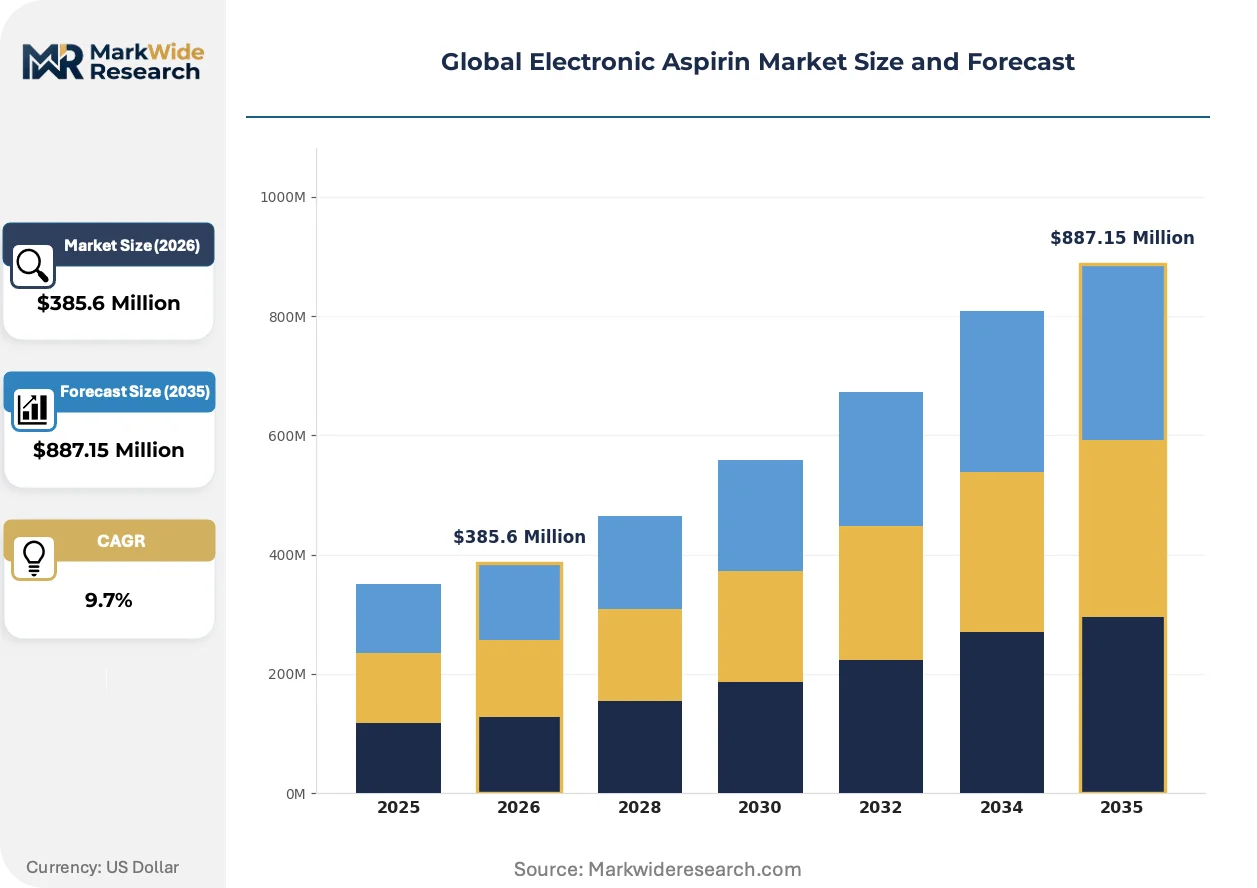
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $887.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet Dispenser, Wearable Device, Pain Relief Patch, Smart Pill, Capsule Tracker Application: Cardiovascular Health, Pain Management, Anti-Inflammatory Therapy, Blood Thinning, Fever Reduction End User: Specialty Clinics, Home Care, Pharmacy Chains, Geriatric Centers, Rehabilitation Facilities Technology: Bluetooth Connectivity, NFC, RFID Tracking, Mobile App Integration, Cloud Data Storage |
| Companies Covered | Autonomic Technologies, Inc., Medtronic, Bayer AG, Nevro Corp, NeuroSigma, Inc., LivaNova PLC, ElectroCore, Inc., ImThera Medical, EnteroMedics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Aspirin Market Shifts & Advancements
Neuromodulation hardware is converging with pharmaceutical adherence monitoring, creating hybrid therapeutic platforms that track both bioelectronic delivery and patient compliance. This convergence is compressing traditional boundaries between device and drug manufacturers.
Closed-loop vagus nerve stimulation is hybridizing cardiac autonomic monitoring with migraine prevention protocols. Pain management service lines at integrated delivery networks in the United States are piloting these systems for comorbid cardiovascular and headache patients. The technology is hybridizing previously separate therapeutic categories, enabling cross-specialty reimbursement and expanding addressable patient populations beyond single-indication devices.
EU MDR Article 10 post-market clinical follow-up requirements are mandating continuous real-world evidence collection for all Class IIa and above pain management devices. Manufacturers must now embed data transmission infrastructure from initial design phases rather than retrofitting connectivity post-launch. Wearable formats with recurring consumable requirements face the steepest compliance burden, as adhesive electrode replacement cycles generate substantial follow-up data obligations.
Hospital procurement consortiums now screen electronic aspirin suppliers for cybersecurity certifications and remote monitoring capabilities before inclusion in group purchasing organization formularies. Specialty clinics in Germany and the United States are consolidating vendor relationships around platforms offering encrypted clinician dashboards rather than standalone hardware. This consolidation is most visible in North American academic medical centers, where information security committees have gained veto authority over therapeutic device selections.
Global Electronic Aspirin Market Segmentation
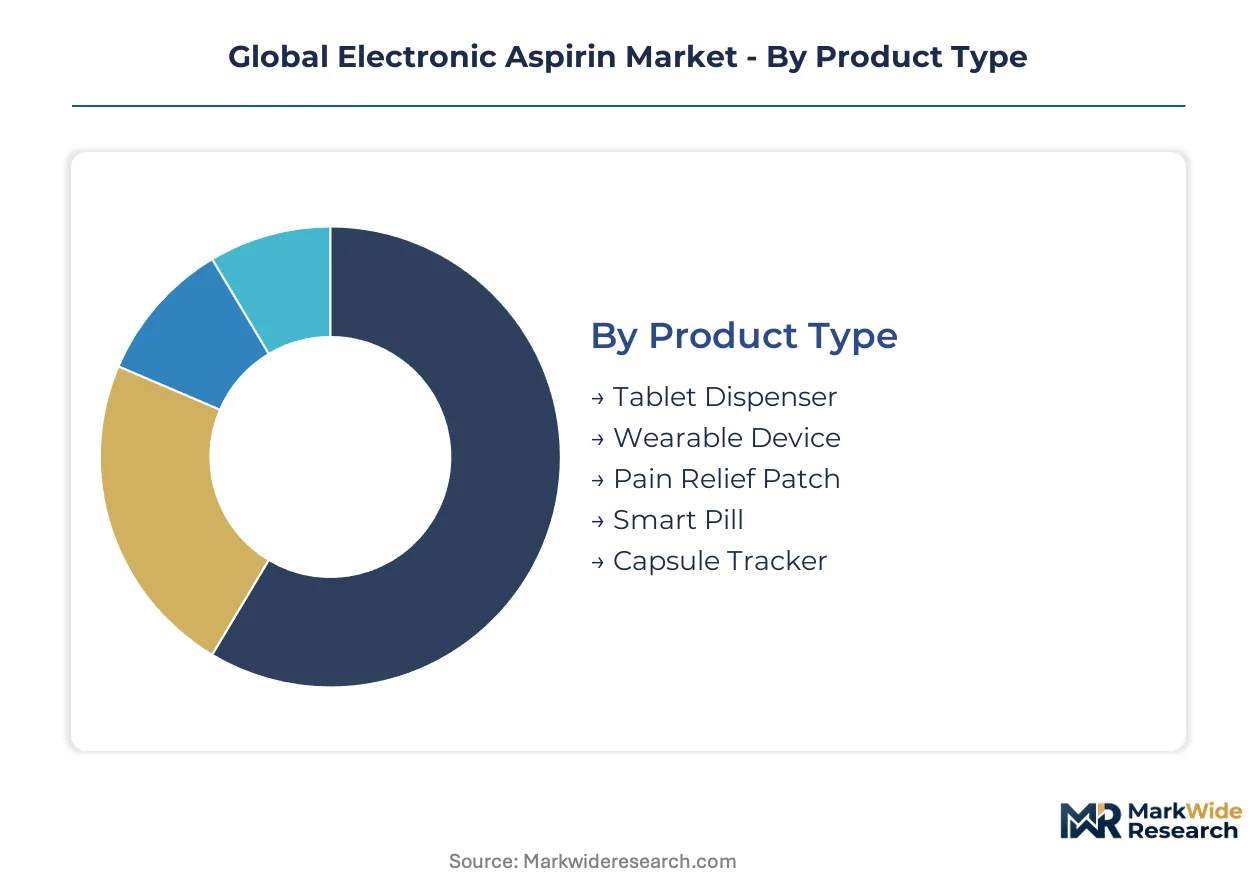
Electronic aspirin markets fragment across hardware formats, therapeutic targets, and connectivity architectures. Each dimension carries distinct margin profiles, replacement cycles, and regulatory pathways that reshape competitive positioning.
Product Type:
Wearable formats turn inventory fastest through recurring electrode consumables, while implantable systems lock in decade-long replacement horizons.
- Wearable Device:Microprocessor-controlled nerve stimulators with adhesive electrode arrays dominate procurement volumes. Chronic pain clinics in Germany and the United States favor these for opioid-sparing protocols, with electrode replacement cycles driving recurring revenue streams.
- Smart Pill:Ingestible sensors embedded in pharmaceutical formulations enable real-time compliance verification. Pharmaceutical manufacturers in Japan seek partnerships for these systems as PMDA accelerates software-as-medical-device reviews, expanding addressable populations beyond traditional device markets.
- Tablet Dispenser:Programmable dosing containers with biometric locks serve polypharmacy patients in geriatric settings.
- Pain Relief Patch:Transdermal delivery systems with iontophoresis or thermal modulation occupy mid-tier pricing.
- Capsule Tracker:Miniature ingestible sensors focus narrowly on gastric transit monitoring for specific therapeutic classes.
Wearable Device anchors the volume base while Smart Pill gains share at the steepest rate.
Application:
Cost tiers stratify sharply, with cardiovascular indications commanding premium reimbursement and fever reduction settling into commoditized positioning.
- Pain Management:Neuromodulation protocols for migraine, neuropathic pain, and musculoskeletal conditions absorb the majority of device procurement budgets. Integrated delivery networks in the United States pilot closed-loop vagus nerve systems for comorbid patients, expanding reimbursement codes beyond single-indication boundaries.
- Cardiovascular Health:Bioelectronic aspirin delivery for antiplatelet therapy targets post-stroke and atrial fibrillation populations. FDA breakthrough device pathways prioritize these applications, compressing development timelines for developers with existing cardiac rhythm management infrastructure.
- Anti-Inflammatory Therapy:Targeted cytokine modulation through peripheral nerve stimulation addresses rheumatoid arthritis and similar conditions.
- Blood Thinning:Programmable anticoagulant delivery with INR monitoring integration serves warfarin management protocols.
- Fever Reduction:Basic thermal regulation applications face price pressure from conventional pharmacological alternatives.
Pain Management captures the largest absolute spend while Cardiovascular Health climbs fastest on breakthrough designation momentum.
End User:
Customer concentration patterns diverge: institutional procurement favors bundled service contracts, while home care demands simplified interfaces and direct-to-patient logistics.
- Specialty Clinics:Headache centers and chronic pain facilities in the United States and Western Europe consolidate vendor relationships around encrypted clinician dashboards. Hospital procurement consortiums now mandate cybersecurity certifications before group purchasing organization inclusion.
- Home Care:Aging populations in Japan drive demand for patient-operated neuromodulation with simplified interfaces. Non-pharmacological intervention preferences sustain this segment despite higher upfront device costs versus oral analgesics.
- Pharmacy Chains:Retail distribution networks seek over-the-counter wearable formats with minimal clinical oversight requirements.
- Geriatric Centers:Long-term care facilities prioritize medication adherence monitoring for polypharmacy populations.
- Rehabilitation Facilities:Post-surgical pain protocols incorporate temporary external stimulation during recovery windows.
Specialty Clinics anchor the volume base while Home Care expands most quickly on demographic tailwinds.
Technology:
Supply concentration in semiconductor and cloud infrastructure layers creates divergent margin exposures across connectivity architectures.
- Mobile App Integration:Subscription-based clinician dashboard licensing captures disproportionate margin pools versus hardware sales alone. CMS and commercial payers in the United States are creating discrete billing categories for remote therapeutic monitoring, enabling recurring revenue models.
- Bluetooth Connectivity:Low-energy protocols dominate wearable device architectures due to battery life optimization and smartphone ubiquity. PMDA streamlined review tracks have reduced authorization delays for these platforms.
- NFC:Near-field communication enables tap-to-pair simplicity for elderly patient populations.
- RFID Tracking:Inventory and adherence monitoring for institutional pharmacy settings.
- Cloud Data Storage:Backend infrastructure for EU MDR Article 10 post-market clinical follow-up requirements.
Bluetooth Connectivity anchors the volume base while Mobile App Integration captures margin expansion at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese home care channels and German specialty clinics, while Brazilian outpatient networks compete on volume-driven accessibility.
United States
Chronic pain clinics in the United States expand procurement of wearable nerve stimulators as alternatives to oral analgesics under opioid reduction mandates. FDA breakthrough device designations compress development timelines for developers with existing cardiac rhythm management infrastructure. Hospital procurement consortiums in academic medical centers now mandate cybersecurity certifications before group purchasing organization inclusion.
Germany
German chronic pain clinics drive demand for external neuromodulation systems as reimbursement codes expand for opioid-sparing protocols. EU MDR technical documentation requirements elevate clinical evidence thresholds, filtering out developers lacking randomized trial capabilities. The Baden-Württemberg medical technology cluster concentrates manufacturing capabilities for electrode arrays and microprocessor-controlled dispensing mechanisms.
Japan
Japanese elderly populations seek non-pharmacological pain interventions, sustaining demand for patient-operated neuromodulation systems with simplified interfaces. PMDA streamlined review tracks for software-as-medical-device applications reduce authorization delays from twenty-four months to under twelve months. Tokyo-based integrated delivery networks pilot closed-loop vagus nerve systems for comorbid cardiovascular and headache patients.
Brazil
Brazilian private healthcare networks present underpenetrated opportunities for Class II pain management device manufacturers seeking first-mover positioning. ANVISA has established abbreviated regulatory pathways, accelerating market entry timelines relative to FDA or EU MDR processes. São Paulo outpatient clinics represent the primary demand concentration for wearable formats with minimal clinical oversight requirements.
United Kingdom
United Kingdom headache specialty centers consolidate vendor relationships around platforms offering encrypted clinician dashboards rather than standalone hardware. MHRA post-Brexit regulatory alignment with EU MDR maintains elevated clinical evidence requirements for market authorization. The London-Oxford-Cambridge life sciences cluster hosts pilot programs for AI-embedded dosing algorithms with biometric sensor integration.
Global Electronic Aspirin Market Competitive Landscape
Cardiac rhythm management conglomerates and neuromodulation specialists split the market between implantable device architectures and external stimulation platforms. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with cross-selling infrastructure, pure-play neuromodulation developers with exclusive specialty center partnerships, and pharmaceutical manufacturers seeking device partnerships for compliance verification. Dominant competitive moves include strategic partnerships with integrated delivery networks and portfolio diversification into software-as-medical-device subscription models.
Among diversified medical technology conglomerates, Medtronic leverages existing cardiac rhythm management infrastructure to cross-sell neurostimulation platforms into pain management service lines. Autonomic Technologies, Inc. anchors the specialty center partnership archetype through exclusive relationships with headache centers in the United States and Western Europe. ElectroCore, Inc. occupies a distinct position pursuing non-invasive vagus nerve stimulation pathways rather than implantable device architectures, representing the external neuromodulation specialization vector.
| Leading Market Players |
|---|
| Autonomic Technologies, Inc. |
| Medtronic |
| Bayer AG |
| Nevro Corp |
| NeuroSigma, Inc. |
| LivaNova PLC |
| ElectroCore, Inc. |
| ImThera Medical |
| EnteroMedics Inc. |
| Others |
Supply & Pricing Matrix
Silver and conductive polymer input volatility in South African and Russian mining operations compresses margin buffers while forcing tiered sourcing strategies across premium electrode arrays and standard consumable lines. This commodity exposure widens pricing spreads between FDA breakthrough-designated systems and basic programmable devices, as manufacturers pass through precious metal costs or absorb them to defend specialty clinic relationships.
Pricing Analysis
The customization-premium spread separates configured-to-order implantable platforms from standard wearable nerve stimulators. Subscription-based clinician dashboard licensing captures recurring revenue pools beyond hardware sales, while per-unit transactional pricing dominates electrode consumable replacement cycles. Price differentiation hinges on cybersecurity certification tier and remote therapeutic monitoring integration, with academic medical centers least price-sensitive due to information security committee mandates. Cost compression in standard wearable formats intensifies as group purchasing organizations consolidate vendor relationships around bundled service contracts.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for microprocessor-controlled dispensing mechanisms and Bluetooth connectivity modules. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while electrode manufacturing draws from South African silver and Russian conductive polymer feedstocks. Single-source vulnerability in adhesive array substrates threatens production continuity for wearable formats with recurring consumable requirements. Distribution runs through hospital procurement consortiums and integrated delivery networks rather than direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution from spinal cord stimulation systems offered by cardiac rhythm management divisions, which capture severe chronic pain cases that might otherwise trial external neuromodulation.
For Market Incumbents: Build regulatory data moats through EU MDR Article 10 post-market clinical follow-up infrastructure that early-stage developers cannot replicate. Vertical integration into electrode array manufacturing mitigates silver price volatility exposure. Capacity addition in the Baden-Württemberg medical technology cluster secures proximity to German chronic pain clinic demand. Certification investment in FDA breakthrough device pathways maintains development timeline advantages against randomized trial-capable entrants. For New Entrants and Emerging Players: Establish a beachhead in Brazilian private healthcare networks where ANVISA abbreviated pathways enable first-mover positioning ahead of FDA or EU MDR timelines. Underpenetrated São Paulo outpatient clinics represent the most accessible entry point for Class II pain management devices with minimal clinical oversight requirements. Direct-to-patient logistics partnerships with pharmacy chains bypass hospital procurement consortium gatekeeping. For Investors and Strategic Acquirers: Pure-play neuromodulation developers with exclusive headache specialty center partnerships represent the most defensible acquisition target archetype in a five-to-ten-year viability window. These assets command premium positioning through encrypted clinician dashboard relationships that conglomerates struggle to replicate organically. The signal to watch is CMS reimbursement code innovation for remote therapeutic monitoring, which validates subscription revenue model durability beyond hardware replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses development timelines for cardiac rhythm management infrastructure holders. |
| EU MDR Technical Documentation Investment | Elevates clinical evidence thresholds that filter out randomized trial-incapable developers. |
| Hospital System Partnership | Secures group purchasing organization inclusion through cybersecurity certification compliance. |
| Software Companion Development | Enables subscription-based clinician dashboard licensing beyond one-time hardware sales. |
| Reimbursement Strategy | Captures CMS remote therapeutic monitoring code innovation for recurring revenue models. |
Research Methodology
A standing panel of chronic pain clinic procurement directors, biomedical engineers, GPO contracts managers, and FDA regulatory affairs leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, PMDA submission records, and hospital procurement consortium contract disclosures. Bottom-up wearable device shipment estimates and top-down neuromodulation market sizing were triangulated against adhesive electrode replacement cycle data.
Scenario-bracketing framed volume and value outputs across the analysis window through sensitivity testing of opioid reduction mandate enforcement intensity and PMDA streamlined review track expansion. Segmentation dimensions modeled include hardware format, therapeutic target, connectivity architecture, and regional regulatory cluster. CAGRs were derived from trend extrapolation of specialty clinic procurement patterns and home care aging demographic trajectories, with AI-embedded dosing algorithm adoption curves and cybersecurity engineering talent scarcity serving as industry-specific forecast inputs.
Sensitivities concentrate around silver commodity price spikes, EU MDR post-market surveillance obligation expansion, and spinal cord stimulation reimbursement code bundling. Forecasts reflect assumptions regarding PMDA review track permanence and CMS remote monitoring billing category stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Global Osteoporosis Drugs Market