
 Clinical Mobility Market | 2026-2036
Clinical Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Mobility Market Outlook
The clinical mobility landscape is pivoting on a widening gap between premium connected platforms and basic mechanical aids. Philips Healthcare leverages deep vertical integration across sensors, software, and service networks to command the high end. Zebra Technologies competes through ruggedized hardware and enterprise-grade asset tracking that sustains loyalty among large hospital systems. OMRON Healthcare anchors its position in homecare settings with blood pressure and monitoring devices that bridge clinical and consumer mobility.
Clinical mobility encompasses powered and non-powered devices, wearable biosensors, and software platforms that enable patient movement, remote monitoring, and real-time data transmission across care environments. These systems integrate Bluetooth Low Energy, cellular connectivity, and rechargeable lithium-ion powertrains to support continuous operation during ambulatory care and inpatient transport. Telehealth and wearable devices represent the fastest-expanding technology segments as reimbursement codes mature and clinical evidence accumulates for remote patient management. Mobile health applications sit at the center of margin pools because subscription revenue and data analytics services generate recurring income beyond hardware sales. Patient lifts and mobility scooters remain volume-heavy categories where price competition limits profitability for undifferentiated suppliers.
FDA cybersecurity guidance, EU MDR software classification, and HIPAA interoperability mandates collectively reshape product development timelines and market access requirements for clinical mobility vendors. The EU AI Act adds emerging compliance layers for algorithmic diagnostic features embedded in mobility platforms. Stakeholders must monitor how reimbursement authorities in target markets classify connected mobility services relative to traditional durable medical equipment.
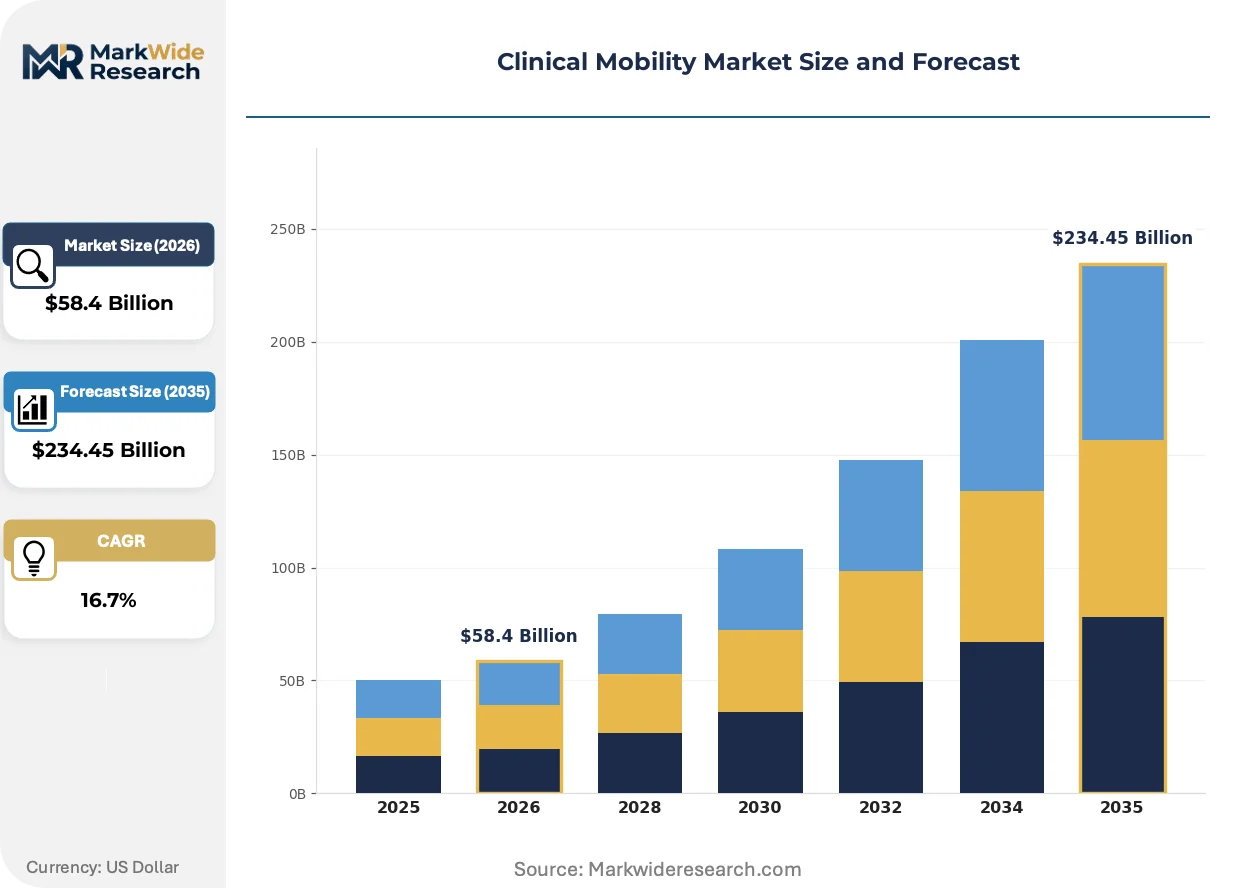
Market Dynamics
Hospital procurement committees now prioritize platforms that unify patient monitoring, asset tracking, and clinical communication into single vendor relationships, compressing the supplier base and elevating software-integrated hardware over standalone devices.
Growth Catalysts
- FDA Cybersecurity Guidance:Manufacturers investing in pre-market security documentation capture faster 510(k) clearances, accelerating revenue recognition for connected mobility platforms.
- Remote Patient Monitoring:CMS reimbursement codes for continuous glucose and cardiac monitoring expand addressable demand for wearable biosensors in ambulatory settings.
- Japan's Super-Aged Society:METI funding for home-based care infrastructure channels capital toward motorized wheelchairs and patient lift systems with telehealth integration.
Market Restraints
- Lithium-Ion Supply Concentration:Cathode material processing clusters in China create input cost volatility and forced localization requirements under the EU Critical Raw Materials Act.
- EU MDR Software Classification:Reclassification of algorithm-driven mobility aids as Class IIa or higher medical devices extends conformity assessment timelines by 12-18 months.
- Mechanical Aid Substitution:Basic non-powered walkers and canes retain preference in price-sensitive long-term care facilities, capping premium product penetration.
Strategic Opportunities
- Germany's Hospital Future Act:Federal capital grants for digital infrastructure create procurement windows for integrated mobility platforms with real-time location systems.
- 5G-Enabled Surgical Trolleys:Convergence of private 5G networks and edge computing permits intraoperative video streaming during patient transport, opening perioperative workflows.
- Direct-to-Patient Subscription:Bypassing durable medical equipment distributors through manufacturer-managed leasing reduces channel capture and builds recurring revenue.
Industry Challenges
- Cybersecurity Engineering Talent:Shortage of embedded systems security specialists delays product development cycles for wireless-enabled mobility devices.
- Legacy EHR Integration:Proprietary data formats in Cerner and Epic deployments force costly custom interface development for connected mobility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Mobility Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $234.45 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Lifts, Mobility Scooters, Wheelchairs, Walking Aids Technology: Telehealth, Wearable Devices, RFID, Mobile Health Applications End User: Hospitals, Nursing Homes, Homecare Settings, Rehabilitation Centers Service Type: Maintenance, Rental, Training, Consultation |
| Companies Covered | Philips Healthcare, Cerner Corporation, Oracle Corporation, Cisco Systems, Zebra Technologies, OMRON Healthcare, AirStrip Technologies, GE HealthCare, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Mobility Market Strategic Shifts
Clinical mobility is converging with ambient intelligence, where environmental sensors and wearable devices coordinate without patient intervention. This shift demands new architectures in power management, edge analytics, and seamless handoff between care settings.
Bluetooth Low Energy mesh networks are expanding into hospital-wide patient tracking and equipment localization. Large integrated delivery networks in Texas and California deploy these systems to reduce bed turnover delays and locate critical infusion pumps. The technology is expanding into post-acute facilities where real-time visibility was previously cost-prohibitive.
The EU AI Act imposes conformity requirements on mobility platforms with diagnostic algorithms, including risk classification and human oversight mandates. Manufacturers must restructure quality management systems to address algorithmic transparency and post-market monitoring. German and French notified bodies are developing specialized assessment pathways for AI-embedded rehabilitation robotics.
Hospital supply chain directors now unbundle service contracts from hardware purchases, negotiating separate agreements for preventive maintenance and software updates. This pattern concentrates in US academic medical centers with dedicated clinical engineering departments. Third-party service providers capture margin pools that OEMs previously controlled through bundled pricing.
Clinical Mobility Market Segmentation
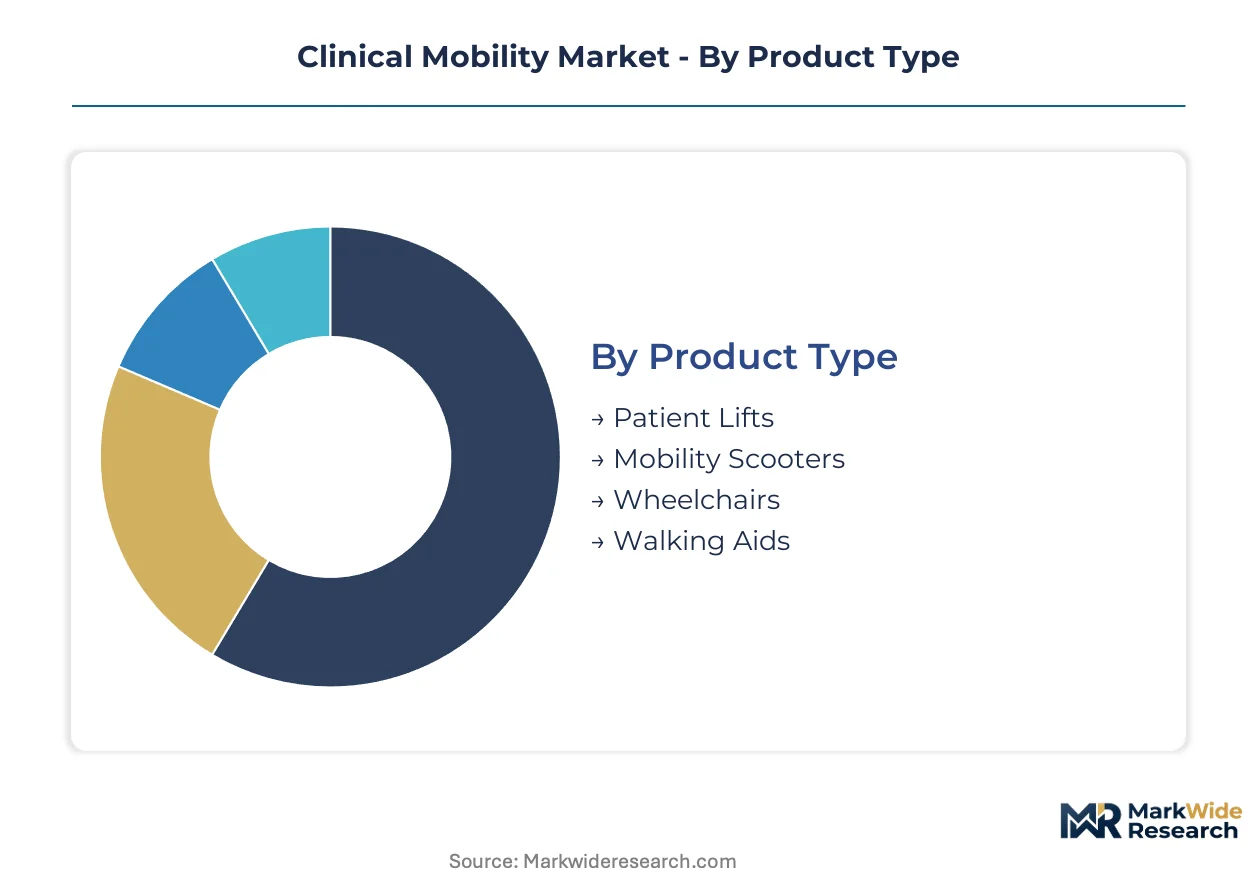
Clinical mobility procurement decisions split between capital-intensive hardware investments and recurring service contracts, with reimbursement pathways determining which segments capture margin. Understanding these divides reveals where vendors can escape commodity pricing.
Product Type:
Customization intensity varies sharply across this category, from configurable powertrains to standardized mechanical frames.
- Patient Lifts:Hydraulic and electric ceiling-mounted systems with sling configurations rated for bariatric loads. Demand clusters in US nursing homes facing OSHA safe patient handling mandates, though capital budgets limit replacement cycles.
- Mobility Scooters:Three-wheel and four-wheel configurations with lithium-ion powertrains reaching speeds up to 8 mph. Medicare Advantage plans in Florida and Arizona drive volume through supplemental benefit riders.
- Wheelchairs:Manual and powered variants with tilt-in-space and standing capabilities.
- Walking Aids:Canes, crutches, and rollators with height-adjustable aluminum frames.
Most installed capacity flows through Wheelchairs. Expansion is steepest in Patient Lifts.
Technology:
Margin pools concentrate in software layers that hardware vendors struggle to monetize directly.
- Telehealth:Video consultation platforms with FDA-cleared peripherals for remote vital capture. CMS reimbursement codes for chronic care management expand deployment in Texas and California integrated delivery networks.
- Wearable Devices:Continuous glucose monitors and cardiac event recorders with Bluetooth Low Energy transmission. Germany's DiGA fast-track approval channel accelerates adoption for algorithm-driven diagnostics.
- RFID:Passive and active tags for real-time location tracking of infusion pumps and wheelchairs.
- Mobile Health Applications:Subscription-based platforms for medication adherence and fall risk assessment.
Hardware attachment rates are highest for Wearable Devices. Telehealth is gaining share fastest among new hospital construction projects.
End User:
Procurement authority and reimbursement access create distinct customer archetypes with diverging price sensitivity.
- Hospitals:Integrated delivery networks with centralized value analysis committees. Germany's Hospital Future Act capital grants favor platforms with real-time location system integration.
- Nursing Homes:For-profit chains and nonprofit operators with thin capital reserves. Japan's LTCI reimbursement revisions favor motorized wheelchairs with telehealth connectivity.
- Homecare Settings:Medicare-certified agencies and private-duty providers.
- Rehabilitation Centers:Inpatient and outpatient facilities with specialized seating clinics.
Volume concentrates in Hospitals. Steepest expansion trajectory belongs to Homecare Settings.
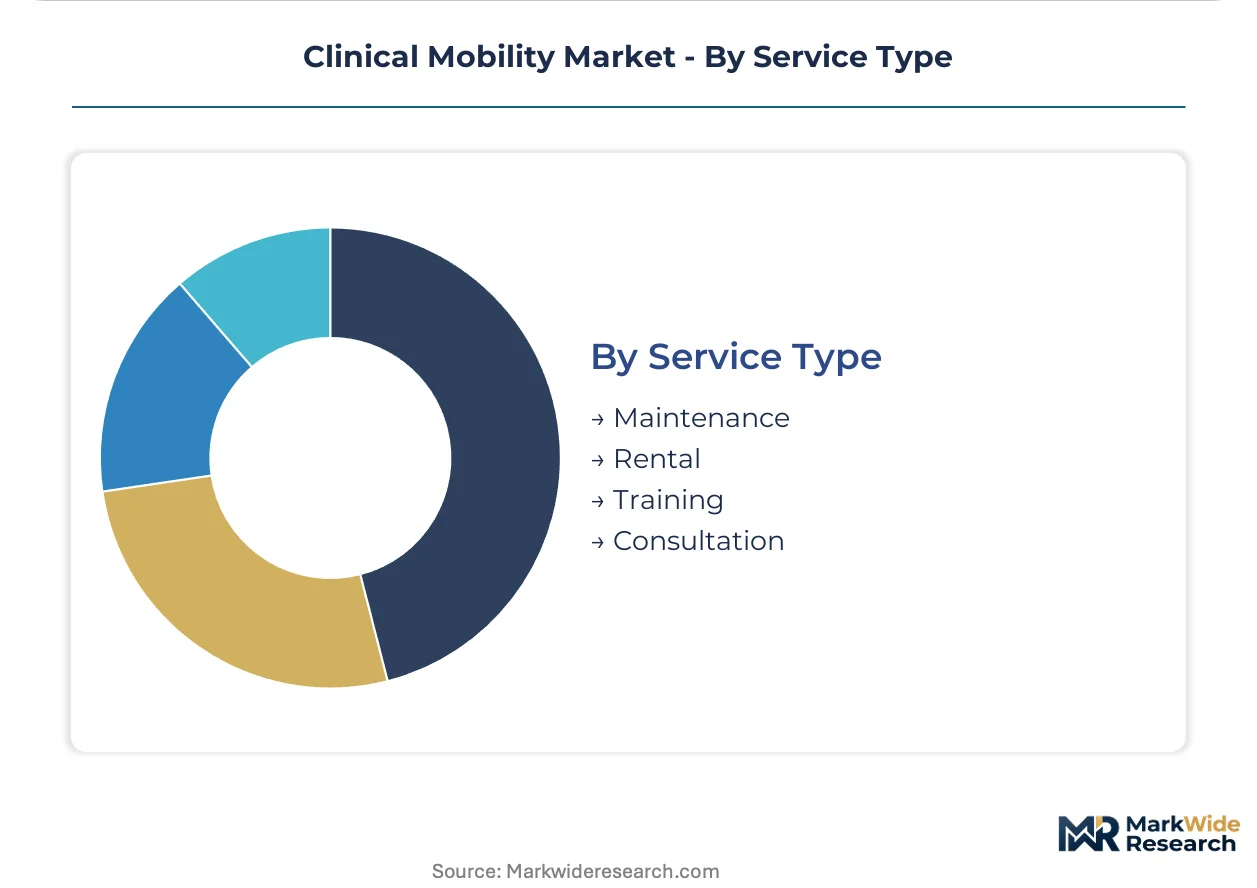
Service Type:
Revenue predictability separates asset-heavy models from knowledge-based offerings.
- Maintenance:Preventive service contracts and corrective repair dispatch. US academic medical centers unbundle these from hardware purchases, concentrating contracts with third-party clinical engineering specialists.
- Rental:Short-term and long-term leasing with swap-out provisions. Direct-to-patient subscription models bypass durable medical equipment distributors in California and New York.
- Training:Safe patient handling certification and equipment operation instruction.
- Consultation:Ergonomic assessment and workflow optimization services.
Contract value concentrates in Maintenance. Rental is climbing the fastest as payers shift toward episodic reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces Japan in integrated platform deployment, while the United States dominates wearable biosensor volumes through Medicare reimbursement expansion.
United States
CMS reimbursement codes for continuous glucose and cardiac monitoring drive wearable biosensor demand across Texas and California integrated delivery networks. FDA cybersecurity guidance accelerates 510(k) clearances for connected mobility platforms with pre-market documentation. Academic medical centers in Boston and the Research Triangle unbundle service contracts from hardware purchases, concentrating maintenance agreements with third-party clinical engineering specialists.
Germany
The Hospital Future Act channels federal capital grants toward digital infrastructure, creating procurement windows for mobility platforms with real-time location systems. EU MDR software classification rules extend conformity assessment timelines for algorithm-driven rehabilitation robotics. Medical device clusters in Baden-Württemberg and North Rhine-Westphalia house notified bodies developing specialized assessment pathways for AI-embedded mobility aids under the EU AI Act.
Japan
METI funding for home-based care infrastructure directs capital toward motorized wheelchairs and patient lift systems with telehealth integration. Japan's Super-Aged Society demographic profile expands addressable demand for connected mobility in community care settings. Industrial concentrations in the Kansai region around Osaka and the Chubu region near Nagoya manufacture lithium-ion powertrains for ambulatory care devices.
United Kingdom
NHS Long Term Plan targets for reducing emergency admissions stimulate investment in remote patient monitoring platforms across integrated care systems. MHRA alignment with EU MDR post-Brexit maintains stringent software classification requirements for algorithmic diagnostic features. London and Greater Manchester health innovation clusters pilot ambient intelligence deployments coordinating environmental sensors with wearable devices.
China
NMPA regulatory pathways for innovative medical devices accelerate market access for domestic manufacturers of powered wheelchairs and patient lifts. Dual carbon goals and the Critical Raw Materials Act drive cathode material localization requirements for lithium-ion supply chains. Manufacturing concentrations in the Yangtze River Delta and Pearl River Delta process battery components for export to European mobility platform assemblers.
Clinical Mobility Market Competitive Environment
Top-tier vendors anchor premium connected platforms, while mid-tier specialists compete on ruggedized hardware and asset tracking capabilities. The supplier base compresses as hospital procurement committees prioritize unified platforms over standalone devices. Three archetypes dominate: vertically integrated healthcare conglomerates, enterprise-grade hardware specialists, and homecare-focused monitoring device manufacturers. M&A activity concentrates on software layer acquisitions, while geographic expansion targets German and Japanese reimbursement windows.
Within the integrated healthcare technology tier, Philips Healthcare and GE HealthCare exemplify archetypes combining sensor hardware, software platforms, and service networks. Zebra Technologies occupies a position among enterprise-grade hardware specialists with ruggedized device portfolios. OMRON Healthcare anchors the homecare monitoring segment with consumer-clinical bridge products. These three represent distinct competitive vectors rather than direct substitutes, reflecting how procurement authority fragments across hospital systems, nursing facilities, and direct-to-patient channels.
| Leading Market Players |
|---|
| Philips Healthcare |
| Cerner Corporation |
| Oracle Corporation |
| Cisco Systems |
| Zebra Technologies |
| OMRON Healthcare |
| AirStrip Technologies |
| GE HealthCare |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Embedded systems security specialists in the Research Triangle and Boston clusters command wage premiums that compress margins on mid-tier connected mobility platforms, widening spreads between premium integrated systems and economy mechanical aids. This labor-cost differential forces vendors to stratify offerings across certification-grade tiers or absorb margin erosion in competitive bids.
Pricing Analysis
The bundled-vs-unbundled service split now defines competitive positioning in clinical mobility procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared connected platforms with cybersecurity documentation from basic mechanical aids without wireless capabilities. Price differentiation rests on ISO 13485 certification status and real-time location system integration depth. Cost compression in the standard tier is intensifying because hospital value analysis committees unbundle maintenance contracts and force competitive rebidding. Nursing home chains exhibit the highest price sensitivity, while academic medical centers with dedicated clinical engineering departments tolerate premium pricing for unified vendor relationships.
Supply Chain Analysis
Workforce availability for embedded firmware development in Taiwan, South Korea, and Japan constrains production scaling for algorithm-driven mobility platforms. Lithium-ion cathode processing draws from Chinese chemical clusters, while precision sensor fabrication sources from German and Japanese industrial bases. Single-source vulnerability in rare earth magnet supply creates exposure to export restriction shocks. Distribution runs through durable medical equipment distributors in the United States and direct hospital contracts in Germany, with emerging direct-to-patient subscription models bypassing traditional channels in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical mobility functions as a stable compounder where aging demographics in developed economies generate replacement demand cycles that outlast typical technology hardware obsolescence patterns.
For Market Incumbents: Cement platform stickiness by deepening software subscription attach rates and capturing preventive maintenance contracts that hospital systems now unbundle from hardware purchases. Defend against emerging cloud-native entrants by accelerating FDA 510(k) clearances with pre-market cybersecurity documentation. Prioritize backward integration into lithium-ion battery management systems to offset cathode material cost volatility.
For New Entrants and Emerging Players: Launch via direct-to-patient subscription models in Medicare Advantage supplemental benefit channels, bypassing entrenched durable medical equipment distributor relationships. Target homecare settings in Japan's Super-Aged Society municipalities where METI funding reduces customer acquisition costs. Exploit white-space in ambient intelligence coordination layers that incumbent hardware vendors struggle to monetize.
For Investors and Strategic Acquirers: Enterprise software vendors with healthcare verticals are the most active acquirer in this space, seeking mobility data streams to enrich existing analytics platforms. The five-to-ten-year viability window favors targets with DiGA fast-track approvals or CMS reimbursement code alignment. Watch for inflection when hospital procurement committees mandate single-vendor relationships across monitoring, asset tracking, and clinical communication.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures multi-year enterprise agreements with integrated delivery networks in Texas and California. |
| Software Companion Development | Captures recurring SaaS revenue beyond hardware margins through subscription-based analytics. |
| FDA Submission | Accelerates market access via pre-market cybersecurity documentation for wireless-enabled platforms. |
| CE Marking Pathway | Unlocks procurement windows under Germany's Hospital Future Act capital grant programs. |
| Reimbursement Strategy | Aligns product positioning with CMS remote patient monitoring codes and Japan LTCI revisions. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down lithium-ion supply chain tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital value analysis committee members, GPO contracts managers, and clinical engineering directors combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body registers, and METI funding disclosure records. Triangulation between demand-side procurement patterns and supply-side component availability ensures cross-verified volume estimates.
Input-output matrices map wheelchair, patient lift, and biosensor unit economics against lithium cathode pricing, embedded systems labor rates, and software development cost curves across the projection horizon. Segmentation dimensions include product type, technology layer, end-user setting, and service contract structure, with additional modeling of certification tier and reimbursement pathway. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns in comparable medical device categories, adjusted for regulatory timeline uncertainties and reimbursement code expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement delays or lithium supply disruption scenarios. Projections assume continued CMS reimbursement expansion for remote monitoring and stable FDA cybersecurity guidance interpretation. Material deviation in FDA 510(k) clearance timelines or EU MDR software reclassification scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
North America Healthcare Machine Vision System Market