
 Artificial Saliva Market | 2026-2036
Artificial Saliva Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Saliva Market Analysis
Subscription-based replenishment programs for homecare patients is recalibrating how artificial saliva reaches chronic dry mouth sufferers. Fresenius Kabi AG leverages its hospital infusion network to bundle liquid formulations with existing oncology supportive care protocols. GlaxoSmithKline PLC anchors consumer mindshare through retail pharmacy placement and over-the-counter brand recognition across European markets. Perrigo Company PLC specializes in private-label manufacturing, supplying multiple pharmacy chains with store-brand gel and spray alternatives.
Artificial saliva comprises buffered aqueous solutions containing electrolytes, mucin substitutes such as carboxymethylcellulose or xanthan gum, and preservative systems formulated to mimic natural salivary pH and viscosity. Manufacturers compound these ingredients under ISO 13485 quality systems for mucosal contact applications, with terminal sterilization or aseptic filling determined by packaging format. Liquid formulations occupy the largest volume share due to ease of administration in clinical settings and compatibility with nebulized delivery devices. Spray formats represent the fastest-expanding segment as geriatric homecare patients prioritize portability and discrete dosing without auxiliary equipment. Tablet formulations sustain niche positioning where water-free administration matters, such as palliative care or travel scenarios.
The FDA regulates artificial saliva as a Class I medical device under 21 CFR 872.6070, requiring adherence to biocompatibility standards and quality system regulations without premarket notification for most formulations. The EU Medical Device Regulation mandates notified body involvement for saliva substitutes claiming therapeutic benefit beyond mere moisture replacement, elevating documentation burdens for CE-marked products. Japan's PMDA applies Pharmaceutical and Medical Device Act classification tiers that distinguish cosmetic mouth moisturizers from reimbursed medical-grade preparations. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies, as these classifications determine whether patients bear out-of-pocket costs or secure prescription coverage.
Market Dynamics
The EU Medical Device Regulation's tightened biocompatibility protocols for oral cavity products is forcing manufacturers to recertify legacy formulations and elevating barriers for new market entrants across European oncology and geriatric care channels.
Growth Catalysts
- Radiation oncology protocols:German clinics now stock artificial saliva as standard supportive care for xerostomia patients, embedding the product into institutional purchasing workflows.
- REACH compliance evolution:Streamlined substance registration for mucin substitutes is accelerating formulation development cycles for carboxymethylcellulose-based products.
- Japan's Pharmaceutical and Medical Device Act:Reimbursement classification tiers that distinguish medical-grade preparations from cosmetic alternatives are expanding prescription coverage for homecare patients.
Market Restraints
- Preservative system costs:Benzalkonium chloride and paraben alternatives face price volatility due to specialty chemical supply concentration in Chinese manufacturing hubs.
- Terminal sterilization capacity:Gamma irradiation and aseptic filling infrastructure remains geographically concentrated in Western Europe and North American contract manufacturers.
- Natural saliva stimulants:Pilocarpine and cevimeline prescriptions compete for the same xerostomia patient pool, particularly in US Medicare reimbursement frameworks.
Strategic Opportunities
- Subscription replenishment models:Direct-to-patient delivery platforms bypass pharmacy intermediaries for chronic dry mouth sufferers in Japan's homecare sector.
- Palliative care tablet formats:Water-free administration addresses unmet needs in hospice settings where liquid dosing proves impractical.
- ISO 13485 certification arbitrage:Quality system investments transfer to adjacent oral mucosal products including wound dressings and dental adhesives.
Industry Challenges
- Aseptic manufacturing workforce:Qualified technicians for pharmaceutical-grade filling operations command premium wages in tight labor markets.
- CE-marking documentation burdens:Notified body involvement for therapeutic claims extends time-to-market by 12-18 months for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Saliva Market |
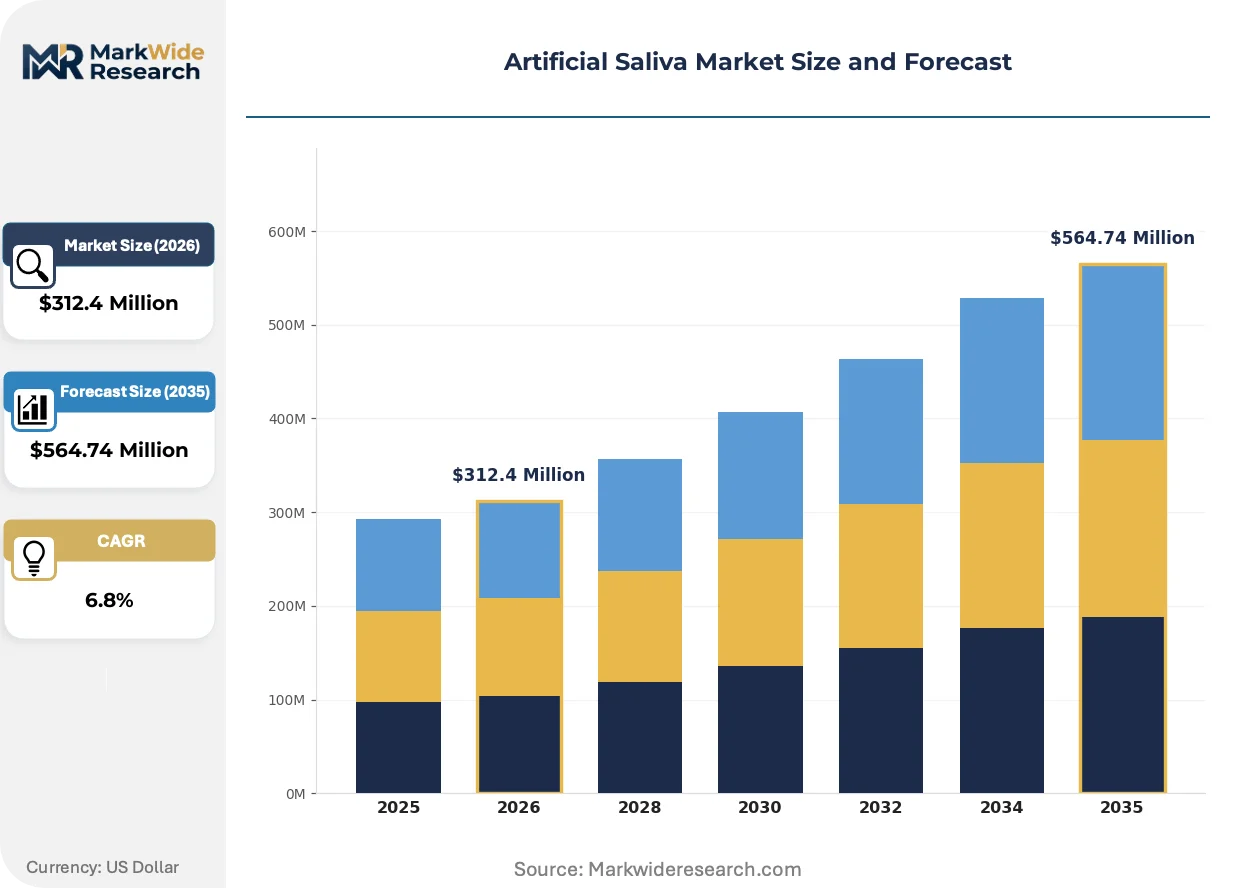
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Form, Gel Form, Spray Form, Tablet Form Application: Dry Mouth Relief, Oral Care, Dental Procedures, Gastrointestinal Disorders End User: Hospitals, Clinics, Homecare, Research Laboratories Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Fresenius Kabi AG, Perrigo Company PLC, GlaxoSmithKline PLC, Forward Science, Biocosmetics Laboratories, Cipla Ltd, Mission Pharmacal Company, ICPA Health Pvt. Ltd., Bausch Health Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Saliva Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape how artificial saliva reaches end-users, with portability and regulatory precision displacing one-size-fits-all liquid formats.
Electrolyte-buffered spray systems are decentralizing administration authority from clinical settings to individual patients. Geriatric homecare users in Japan now self-dose without auxiliary equipment, compressing reliance on nurse-assisted liquid applications. This shift is decentralizing volume share toward pharmacy-shelf formats and away from hospital procurement channels.
The EU Medical Device Regulation's 2021 recast elevated saliva substitutes claiming therapeutic benefit to Class IIa or higher classifications. Manufacturers must now secure notified body review for CE marking, extending documentation timelines and elevating quality system investments. Oncology clinics in Germany and France are prioritizing suppliers with existing MDR certifications to minimize supply disruption.
Discrete portable formats are displacing institutional bulk purchasing as the dominant demand signal. Patients prioritize pocket-sized spray containers over multi-dose bottles, forcing reformulation for stability in non-vented packaging. This preference shift is most visible in Japan's pharmacy retail sector, where self-administered products now dominate shelf space previously allocated to prescription liquids.
Artificial Saliva Market Segmentation
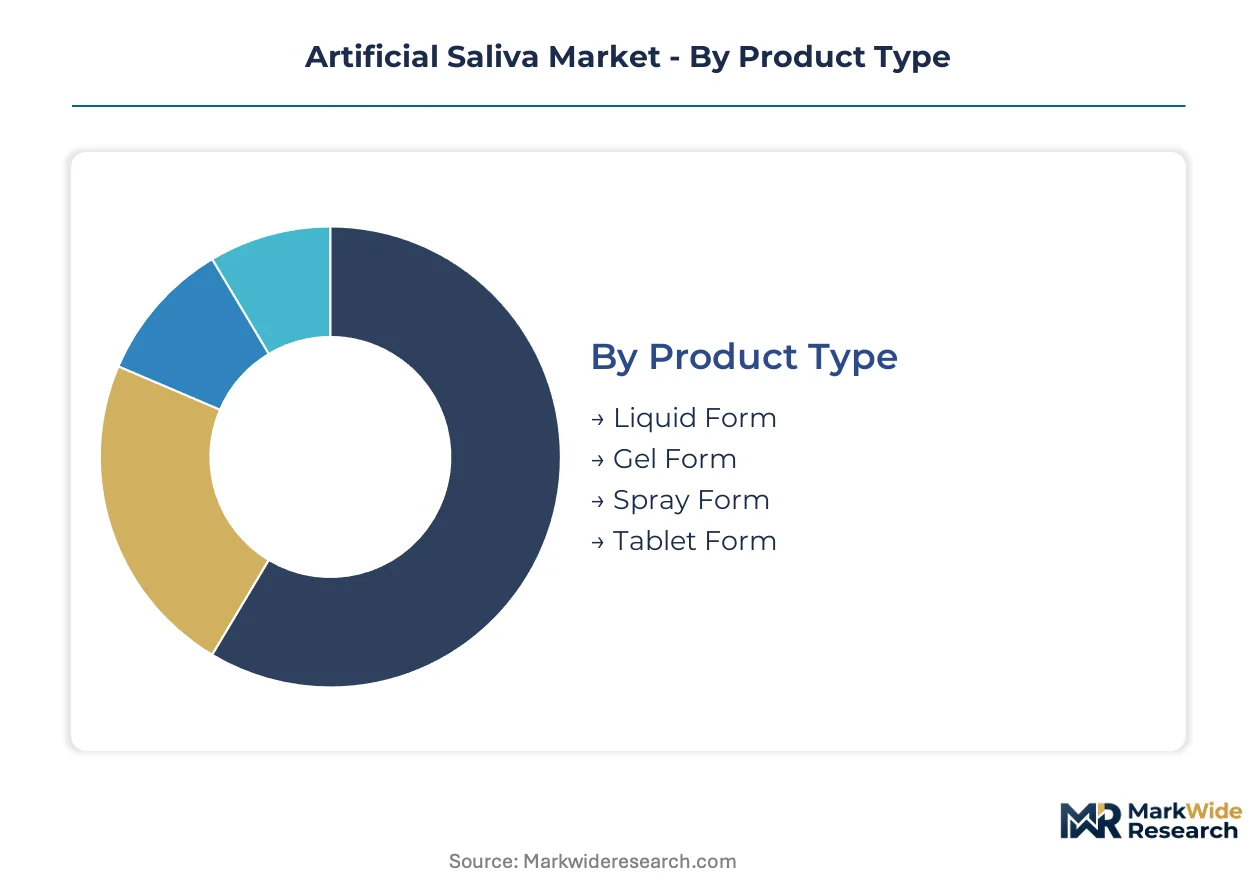
Artificial saliva manufacturers calibrate formulation viscosity, packaging format, and preservative systems to match distinct administration environments. Segmentation reveals where technical specifications align with reimbursement pathways and patient self-efficacy preferences across oncology, geriatric, and dental channels.
Product Type:
Customization intensity spans from standardized bulk liquids to precision-dosed individual formats, with viscosity and sterility requirements determining manufacturing location and margin structure.
- Liquid Form:Buffered aqueous solutions with electrolyte balance and carboxymethylcellulose viscosity modifiers dominate hospital infusion protocols. German oncology clinics specify sterile multi-dose bottles for radiation-induced xerostomia patients, with procurement tied to institutional supportive care contracts.
- Spray Form:Non-vented portable containers with discrete dosing mechanisms prioritize geriatric self-administration. Japan's pharmacy retail sector allocates expanding shelf space to pocket-sized formats as homecare patients bypass nurse-assisted applications.
- Gel Form:Thickened mucin substitutes with extended residence time on oral mucosa serve dental procedure applications.
- Tablet Form:Lyophilized or compressed preparations enable water-free administration in hospice and travel scenarios.
Most installed capacity flows through liquid formulations. Expansion is steepest in spray formats.
Application:
Clinical severity and reimbursement coding create divergent margin profiles across therapeutic versus cosmetic positioning.
- Dry Mouth Relief:Xerostomia management for radiation oncology and Sjögren's syndrome patients commands medical-grade pricing. Japan's PMDA reimbursement tiers distinguish prescription preparations from over-the-counter moisturizers, expanding covered access for chronic sufferers.
- Oral Care:Maintenance formulations for age-related salivary hypofunction compete in pharmacy retail without prescription requirements.
- Dental Procedures:Chairside moisture control during impression-taking and cementation uses lower-viscosity variants.
- Gastrointestinal Disorders:Swallowing facilitation for dysphagia patients represents an emerging off-label utilization pattern.
Revenue concentrates in dry mouth relief applications. Regulatory clarity is advancing fastest in oral care.
End User:
Procurement authority shifts from centralized hospital purchasing to individual patient decision-making across the care continuum.
- Homecare:Self-directed chronic patients in Japan's aging population drive volume through subscription replenishment and pharmacy retail. Discrete packaging formats and reimbursement eligibility determine brand selection without clinician intermediation.
- Hospitals:Oncology and palliative care units in Germany and France embed artificial saliva into standardized supportive care order sets.
- Clinics:Outpatient dental and radiation oncology settings favor single-patient dose packaging.
- Research Laboratories:Biocompatibility testing and formulation development consume small-batch reference standards.
Patient-directed purchasing dominates volume in homecare. Contract penetration is deepest in hospitals.
Distribution Channel:
Channel selection determines margin capture versus patient access trade-offs, with direct models bypassing wholesale markups.
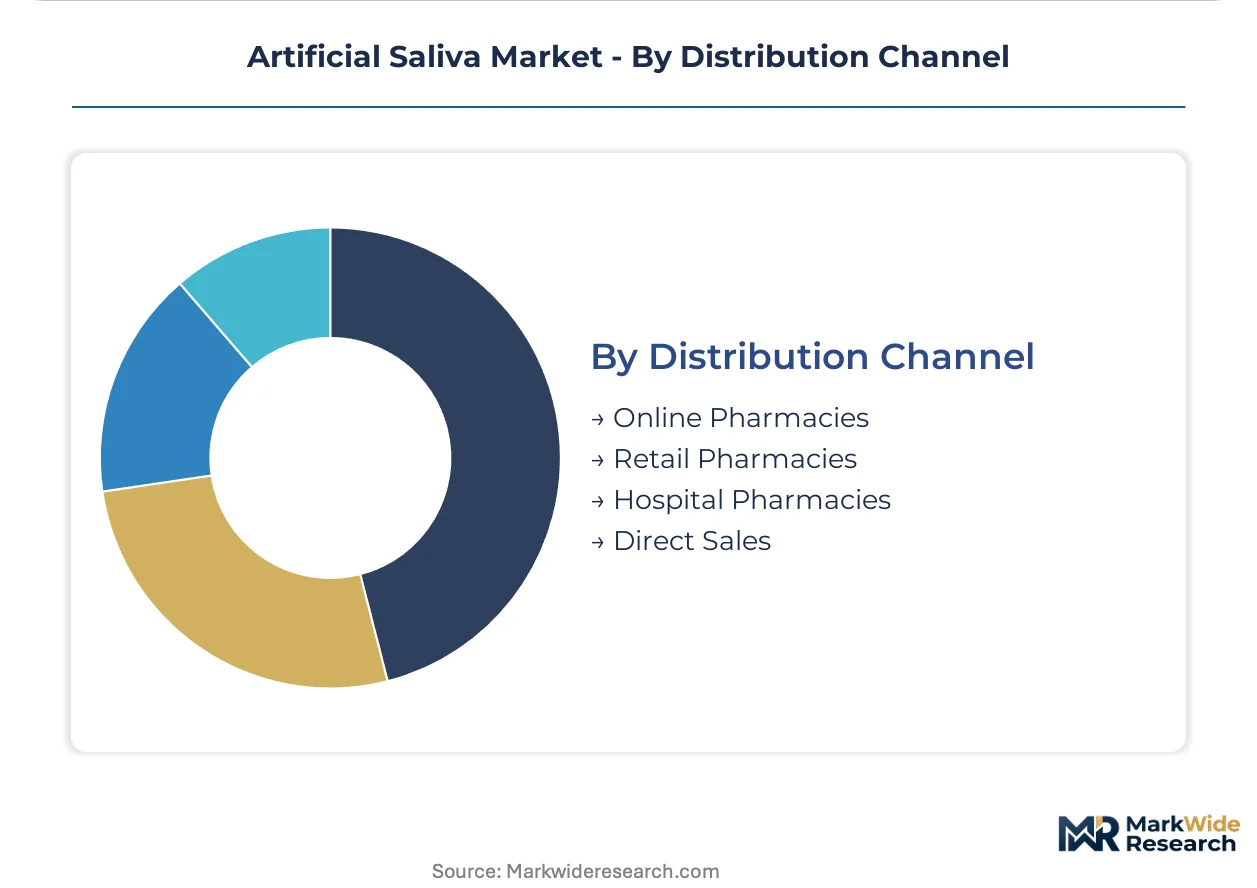
- Online Pharmacies:Subscription-based replenishment platforms in Japan bypass physical pharmacy intermediaries for chronic dry mouth sufferers. Automated reorder algorithms align with consumption patterns in dispersed geriatric populations.
- Retail Pharmacies:Over-the-counter placement in European markets depends on CE-marking status and brand recognition.
- Hospital Pharmacies:Formulary inclusion requires MDR certification for therapeutic claims in EU oncology settings.
- Direct Sales:Manufacturer-to-institution contracts serve bulk liquid requirements in radiation oncology centers.
Transaction volume flows predominantly through retail pharmacies. Margin expansion is most rapid in online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany embeds artificial saliva into institutional oncology workflows, while Japan channels volume through geriatric pharmacy retail. The United States, United Kingdom, and India round out the five-country landscape with divergent reimbursement and regulatory pathways.
United States
Medicare reimbursement frameworks for xerostomia management and Sjögren's syndrome patients drive prescription volume through hospital outpatient settings. The FDA regulates artificial saliva as a Class I medical device under 21 CFR 872.6070, exempting most formulations from premarket notification. California's concentration of contract manufacturers supplies gamma-irradiated sterile liquids to radiation oncology centers nationwide.
Germany
Radiation-induced xerostomia protocols in university hospitals embed artificial saliva into standardized supportive care order sets. The EU Medical Device Regulation mandates notified body involvement for therapeutic claims, elevating documentation burdens for CE-marked products. The Munich-Stuttgart medical technology corridor hosts sterilization infrastructure serving Central European distribution networks.
United Kingdom
NHS formulary inclusion for palliative care patients sustains demand for water-free tablet formats in hospice settings. MHRA post-Brexit regulatory alignment with MDR timelines creates transitional certification complexity for legacy suppliers. The Oxford-Cambridge-London life sciences cluster concentrates biocompatibility testing capacity for oral cavity products.
Japan
PMDA reimbursement classification tiers distinguish medical-grade preparations from cosmetic mouth moisturizers, expanding prescription coverage for homecare patients. The Pharmaceutical and Medical Device Act creates regulatory clarity for chronic dry mouth sufferers seeking reimbursed access. Tokyo-Osaka pharmacy retail chains allocate expanding shelf space to self-administered spray formats.
India
CDSCO medical device registration requirements for imported saliva substitutes create compliance thresholds for multinational suppliers entering the market. Price-sensitive demand concentrates in over-the-counter oral care segments outside formal reimbursement pathways. Maharashtra's pharmaceutical manufacturing belt supplies private-label gel formulations to domestic pharmacy chains.
Artificial Saliva Market Vendor Landscape
Top-tier vendors anchor hospital procurement channels, while private-label manufacturers and regional specialists populate pharmacy retail and direct-to-consumer segments. The market exhibits tiered concentration around three strategic archetypes: institutional suppliers with infusion network leverage, consumer health multinationals with retail pharmacy dominance, and contract manufacturers with private-label scale. Competitive moves concentrate on MDR certification acceleration and subscription platform deployment.
Among hospital-focused suppliers, Fresenius Kabi AG exemplifies the institutional archetype through oncology supportive care bundling. GlaxoSmithKline PLC occupies a position in consumer health channels across European markets. Perrigo Company PLC represents private-label manufacturing scale, supplying store-brand alternatives to multiple pharmacy chains. These three entities illustrate the tripartite competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Fresenius Kabi AG |
| Perrigo Company PLC |
| GlaxoSmithKline PLC |
| Forward Science |
| Biocosmetics Laboratories |
| Cipla Ltd |
| Mission Pharmacal Company |
| ICPA Health Pvt. Ltd. |
| Bausch Health Companies Inc. |
| Others |
Supply Flow & Price Mechanics
Carboxymethylcellulose spot pricing volatility in Chinese manufacturing hubs cascades through formulation costs, compressing margins on economy-tier gels while premium spray formats absorb input shocks through subscription bundling in Japan's homecare channels.
Pricing Analysis
Capacity additions in Maharashtra's pharmaceutical belt are reshaping price floors for private-label gel formulations across Indian pharmacy chains. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified sprays from CE-marked liquids and unbranded moisturizers. Pricing pressure stems from benzalkonium chloride substitute sourcing constraints. Hospital procurement committees exhibit lowest price sensitivity; geriatric homecare patients in Japan show highest.
Supply Chain Analysis
Return flows of expired multi-dose bottles from German oncology clinics feed into specialized pharmaceutical waste streams rather than refurbishment channels. Gamma irradiation infrastructure concentrates in Germany, the United States, and Belgium. Formulation draws from carboxymethylcellulose, xanthan gum, and electrolyte precursor supply. Single-source vulnerability sits with Chinese specialty chemical hubs for preservative alternatives. Distribution runs through hospital pharmacy formularies in oncology settings and retail pharmacy shelves in homecare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Japan's reimbursed prescription tiers and India's over-the-counter oral care segments exploits a regulatory differential that rewards MDR certification investments with pricing power in Tokyo while rewarding volume scale in Mumbai.
For Market Incumbents: To counter private-label erosion in European pharmacy retail, Fresenius Kabi and GlaxoSmithKline should accelerate MDR recertification timelines for legacy liquid formulations and deepen backward integration into carboxymethylcellulose supply through captive agreements with Indian excipient manufacturers. For New Entrants and Emerging Players: Online pharmacy subscription platforms represent the most penetrable channel wedge, particularly for spray formats targeting Japan's dispersed geriatric population through automated replenishment algorithms that bypass wholesale markups entirely. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers holding ISO 13485 certification and existing sterilization infrastructure, as MDR documentation burdens extend time-to-market for competitors and consolidate procurement authority around qualified suppliers. Long-term viability hinges on reimbursement coding decisions by national health technology assessment bodies. Acquisition targets should demonstrate notified body relationships and spray-format stability expertise. Practitioners should monitor PMDA reimbursement tier expansions and EU MDR enforcement consistency as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Acceleration | Notified body relationships secure oncology formulary inclusion in German university hospitals. |
| Subscription Platform Deployment | Direct-to-patient algorithms capture chronic dry mouth volume in Japan's aging homecare sector. |
| Spray Format Reformulation | Stability in non-vented packaging meets discrete dosing preferences displacing liquid applications. |
| Backward Integration into Excipients | Captive carboxymethylcellulose supply hedges Chinese specialty chemical price volatility. |
| Palliative Care Tablet Development | Water-free administration addresses hospice procurement requirements in NHS formulary pathways. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oncology supportive care pharmacists, hospital procurement managers, PMDA reimbursement specialists, and geriatric homecare nurses with secondary validation against FDA 510(k) filings, EUDAMED device registrations, and Japanese Ministry of Health reimbursement bulletins. Bottom-up formulation volume estimates and top-down market sizing triangulated across spray, liquid, gel, and tablet format segments.
Historical reference periods anchored demand modeling to pre-MDR and post-MDR regulatory transitions, with CAGRs derived from segmented growth trajectories across the projection horizon. Segmentation dimensions included product viscosity tier, packaging sterility requirement, reimbursement classification status, and end-user procurement authority. Forecast inputs incorporated PMDA tier expansion timelines and EU notified body capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to benzalkonium chloride regulatory restrictions and gamma irradiation infrastructure expansion. Forecasts reflect documented assumptions about reimbursement coding stability and specialty chemical supply concentration. Practitioners should monitor CDSCO medical device registration enforcement and REACH substance registration evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Elderly Walker Market