
 United States Fusion Splicer Market | 2026-2036
United States Fusion Splicer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Fusion Splicer Market Intelligence
Core-alignment specification tier is rotating toward dominance as carriers deploy higher-fiber-count cables in metropolitan rings. Fujikura leverages its position in precision electrode systems to serve tier-one network builds. Sumitomo Electric Industries anchors the workshop deployment segment with bench-top platforms optimized for cable operator central offices. INNO Instrument competes aggressively on portability, targeting field technicians who splice in pole-mounted and underground environments.
A fusion splicer is a precision instrument that thermally joins two optical fibers by melting their glass cores and cladding under controlled arc discharge, achieving splice loss below 0.01 dB for single-mode fiber. The device incorporates microscopic cameras, motorized alignment stages, and real-time image processing to ensure geometric concentricity before fusion. Ribbon splicers command the premium product tier due to their throughput advantage in data center interconnects and backbone routes. Core alignment technology leads the equipment category because it minimizes insertion loss for single-mode applications, while cladding alignment systems serve cost-sensitive multimode installs in enterprise LANs.
The FCC's BEAD program and USDA's ReConnect initiative shape procurement standards by mandating Buy America compliance and technical certification for funded projects. OSHA's electrical safety regulations and the Telecommunications Industry Association's TIA-568 standards govern field deployment protocols and equipment specifications. Stakeholders must monitor how state broadband offices translate federal funding timelines into concrete equipment purchase orders and installer certification requirements.
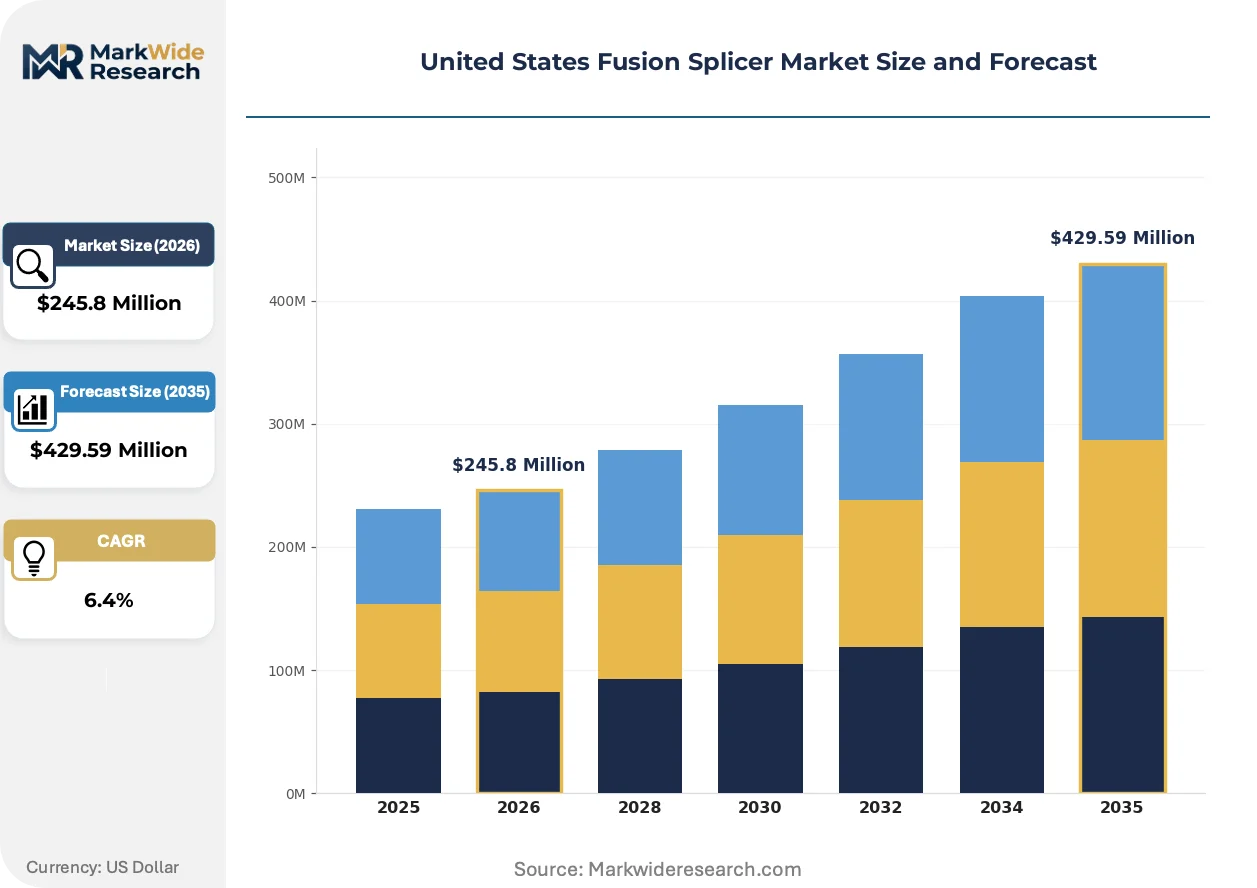
Market Dynamics
Federal broadband infrastructure funding is restructuring equipment procurement timelines across state broadband offices, compressing installer certification cycles and elevating technical specification thresholds for fusion splicer vendors.
Growth Catalysts
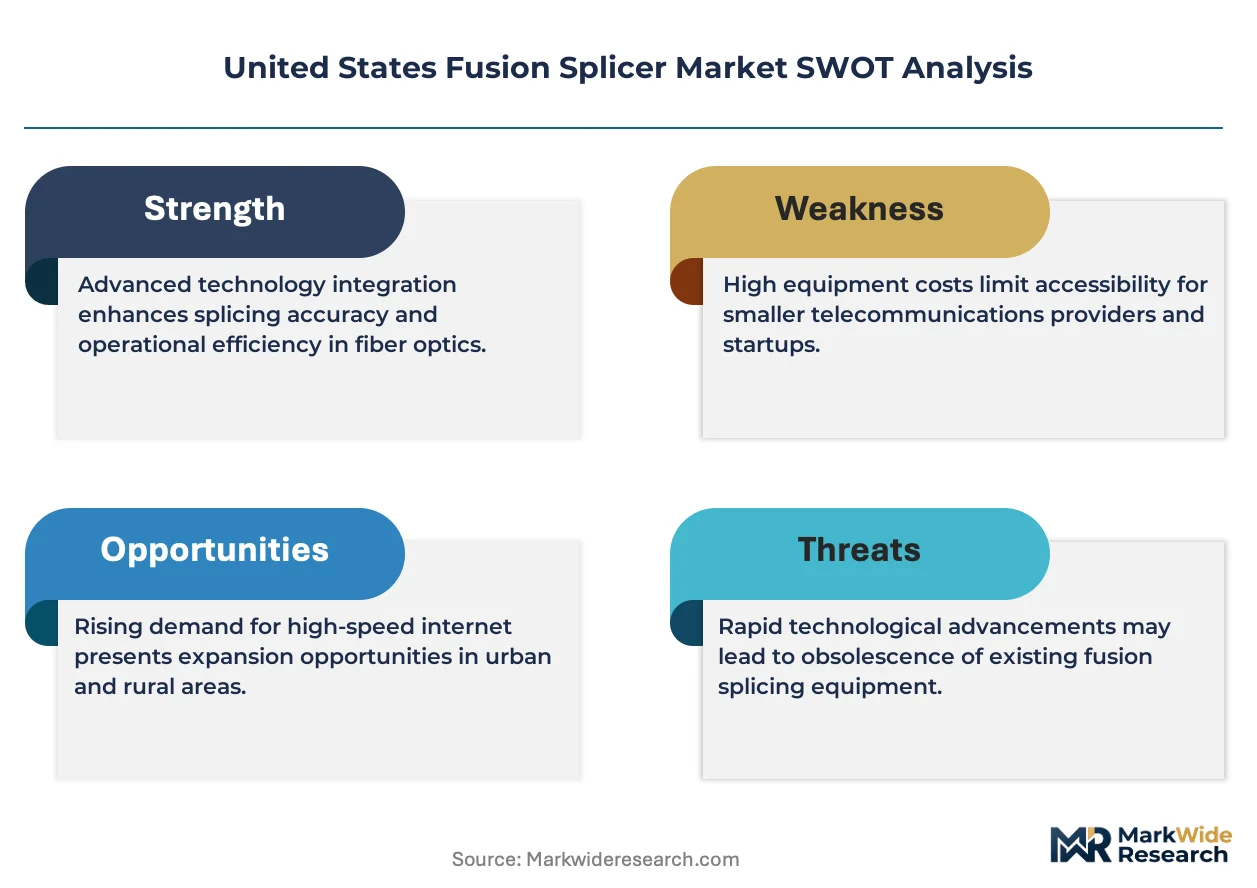
- BEAD Program Deployment:The FCC's Broadband Equity, Access, and Deployment program mandates fiber buildouts in underserved census tracts, generating equipment demand through state broadband offices in Georgia, North Carolina, and Texas.
- Rural Electric Cooperative Expansion:USDA's ReConnect initiative funds fiber-to-the-home projects by member-owned utilities, creating splicer demand in Appalachian and Great Plains service territories.
- Higher-Fiber-Count Cable Migration:Metro ring upgrades by tier-one carriers require core-alignment splicers capable of handling 864-fiber and 1,728-fiber ribbon cables.
Market Restraints
- Precision Electrode Supply Concentration:Japanese and German suppliers dominate ceramic electrode manufacturing, exposing US equipment assemblers to extended lead times and input cost volatility.
- Buy America Compliance Friction:Domestic content requirements under the Infrastructure Investment and Jobs Act constrain sourcing flexibility for imported optical components and precision stages.
- Cladding Alignment Commoditization:Low-cost Asian manufacturers flood enterprise LAN segments with basic splicers, compressing margin pools for standard-grade equipment.
Strategic Opportunities
- Data Center Interconnect Buildouts:Hyperscale cloud campuses in Northern Virginia and Dallas-Fort Worth require ribbon splicers for high-density fiber backbones between facilities.
- 5G Midhaul Fiberization:Mobile network densification drives dark fiber leasing and new construction, expanding addressable demand beyond traditional telecom carriers.
- State Certification Program Partnerships:Equipment vendors can secure preferred-supplier status by embedding training modules into broadband office workforce development initiatives.
Industry Challenges
- Certified Technician Scarcity:The Telecommunications Industry Association's fiber optic technician credential requires 144 hours of coursework, creating bottlenecks as deployment timelines compress.
- Multi-Vendor Fleet Integration:Contractors operating mixed splicer inventories face calibration protocol conflicts and inconsistent splice loss reporting formats across Fujikura, Sumitomo, and INNO Instrument platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Fusion Splicer Market |
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $429.59 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ribbon Splicers, Single Fusion Splicers, Multimode Splicers, Optical Splicer Technology: Active Alignment, Passive Alignment, Core Alignment, Cladding Alignment End User: Telecom Providers, Cable Operators, System Integrators, Network Installers Deployment: On-Site, Workshop, Industrial, Field |
| Companies Covered | Fujikura, Sumitomo Electric Industries, Furukawa Electric, INNO Instrument, 3M, Tektronix, Emerson Electric, Northrop Grumman, GAO Tek, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Fusion Splicer Market Strategic Shifts & Innovations
Active fiber alignment architectures and AI-assisted arc calibration are redefining splice quality benchmarks. Equipment manufacturers now compete on software-defined workflow automation rather than hardware specifications alone.
AI-driven image recognition is supplanting manual fiber inspection protocols in high-volume deployment environments. Tier-one carriers and large contractors are adopting machine-vision systems that auto-detect cladding defects and core eccentricity before fusion. This technology is compressing technician training curves while reducing splice loss variance across less-experienced field crews.
The FCC's equipment authorization rules under Part 15 and Part 68 are tightening electromagnetic compatibility testing for battery-powered field splicers. Vendors must now submit revised certification packages for lithium-ion power systems, extending product launch timelines by four to six months. Workshop-grade platforms with AC tethering face lighter compliance burdens and faster market entry.
Equipment-as-a-service arrangements are displacing outright purchase models among regional contractors and electric cooperatives. Monthly per-splicer subscriptions bundle maintenance, calibration, and software updates, reducing capital deployment for federally funded projects with uncertain continuation timelines. This shift is most pronounced in Southeast states where BEAD subgrantees face clawback provisions if buildout milestones slip.
United States Fusion Splicer Market Segmentation
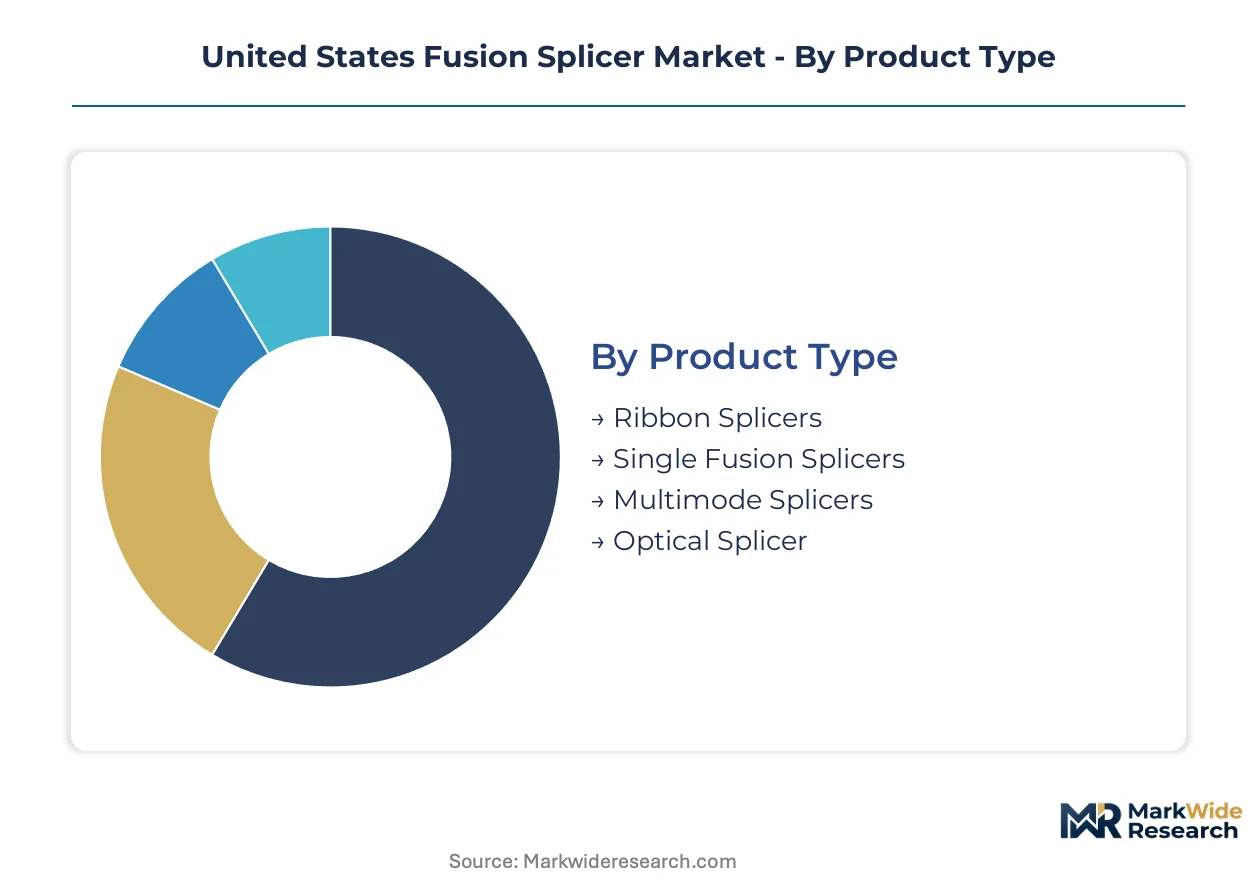
Fusion splicer procurement patterns diverge sharply across deployment contexts, with ribbon splicers commanding premium positioning in data center interconnects while single-fiber units dominate rural fiber-to-the-home rollouts. Equipment specifications tighten progressively from enterprise LAN installations through carrier backbone routes.
Product Type:
Premium margin pools concentrate in high-throughput ribbon platforms serving hyperscale data center operators, while single-fiber splicers generate volume through state broadband office procurement cycles.
- Ribbon Splicers:These systems fuse multiple fibers simultaneously using precision V-groove arrays and automated ribbon preparation, achieving splice times under 20 seconds per 12-fiber ribbon. Demand concentrates in Northern Virginia and Dallas-Fort Worth hyperscale campuses where 864-fiber and 1,728-fiber cable counts mandate throughput efficiency. The FCC's BEAD program timeline compression favors ribbon deployment for backbone routes serving multiple counties.
- Single Fusion Splicers:Individual fiber alignment systems dominate field technician toolkits through portability and battery operation. Georgia and North Carolina state broadband offices specify single-fiber units for last-mile drops to residential premises, where splice density remains low and access constraints favor lightweight equipment. Core alignment variants in this category capture margin from tier-one carrier metro ring contracts.
- Multimode Splicers:Cladding alignment systems serve enterprise LAN retrofits and campus network upgrades where insertion loss tolerances exceed single-mode specifications.
- Optical Splicer:Specialty platforms address submarine cable repair depots and aerospace fiber harness fabrication with hermetic sealing capabilities.
The dominant share belongs to Single Fusion Splicers, while Ribbon Splicers is closing the gap fastest.
Technology:
Active alignment architectures extract price premiums through real-time image processing, whereas cladding alignment competes on capital efficiency for multimode enterprise applications.
- Active Alignment:Motorized stages adjust fiber position during arc discharge using feedback from CMOS cameras and edge-detection algorithms, minimizing splice loss variance below 0.02 dB. Tier-one carriers deploying 400G coherent optics in Texas metro rings specify active alignment to meet strict optical signal-to-noise budgets. The technology's software-defined calibration protocols reduce technician recertification burdens.
- Core Alignment:Direct core imaging through refractive index profiling achieves lowest-loss splices for single-mode fiber, commanding specification in carrier backbone and data center interconnect procurement. Appalachian electric cooperatives under USDA ReConnect funding increasingly specify core alignment as network design horizons extend toward 25G PON.
- Passive Alignment:Fixed V-groove positioning serves high-volume ribbon applications where fiber geometry tolerances enable reliable splicing without active feedback.
- Cladding Alignment:Outer-surface referencing reduces equipment cost for multimode fiber installations in commercial building LANs and campus environments.
Core Alignment holds the installed base leadership, with Active Alignment expanding most quickly in tier-one carrier specifications.
End User:
Procurement authority concentrates in telecom provider engineering departments with multi-year capital planning horizons, while network installer purchasing cycles track quarterly construction seasonality.
- Telecom Providers:AT&T, Verizon, and Lumen Technologies specify fusion splicers through centralized procurement with technical certification requirements tied to TIA-568 standards. Their Southeast fiber expansion programs generate equipment demand through multi-year master service agreements with rental fleet operators.
- Cable Operators:Charter Communications and Cox Communications deploy splicers in hybrid fiber-coaxial upgrade projects and fiber-deep architectures, favoring workshop-grade platforms with AC power for headend and hub site installations.
- System Integrators:Turnkey network construction firms serving BEAD subgrantees face equipment financing constraints that favor subscription-based splicer access.
- Network Installers:Small contractors and electrical trades entering fiber deployment through state workforce programs drive demand for training-embedded equipment packages.
Telecom Providers account for the largest procurement volume, though Network Installers is gaining share fastest through federally funded rural buildouts.
Deployment:
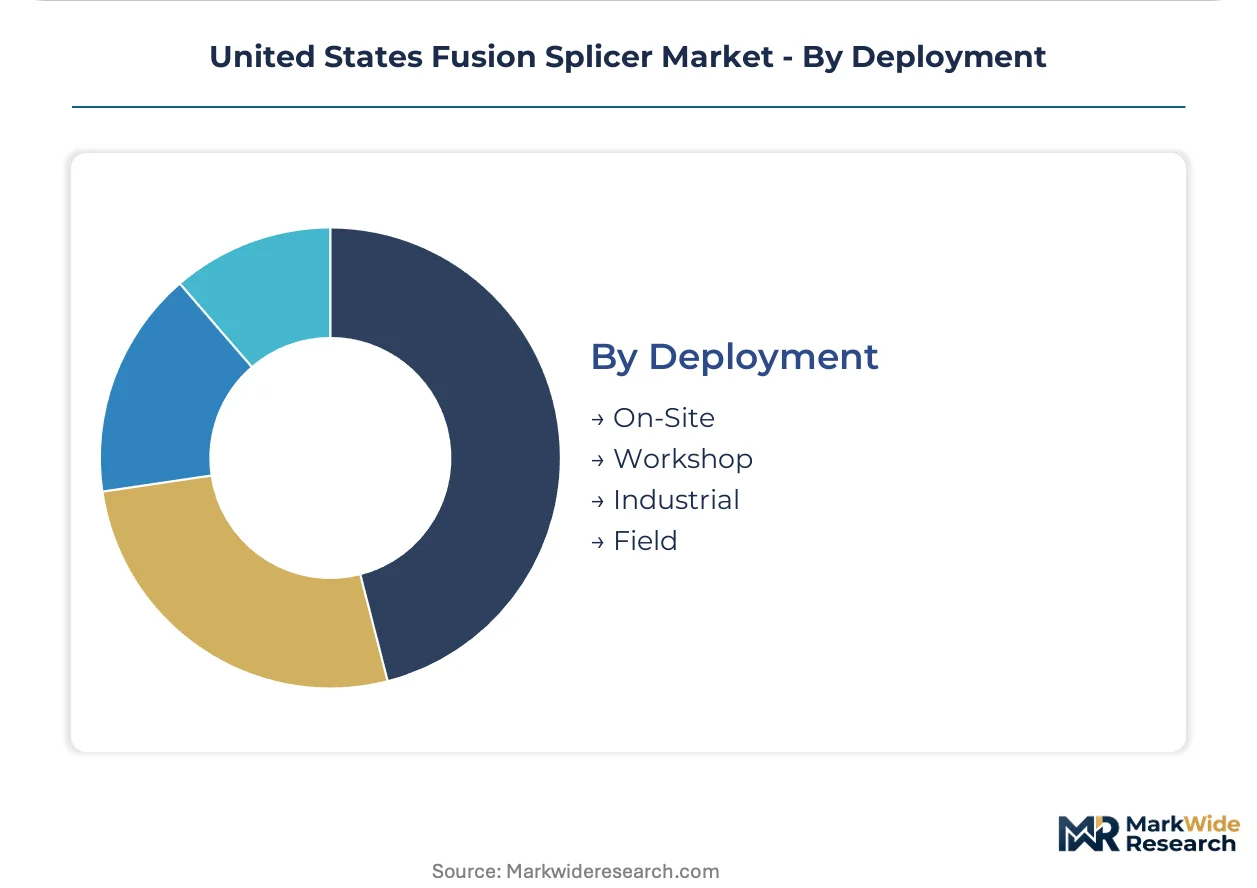
Field deployment generates highest unit volumes through pole-mounted and underground splicing requirements, while workshop environments sustain margin through precision calibration services.
- Field:Battery-powered, weather-sealed splicers with touchscreen interfaces dominate technician toolkits for aerial and buried plant construction. OSHA electrical safety regulations and TIA-568 field deployment protocols govern equipment specifications for Georgia and North Carolina contractor crews.
- On-Site:Rapid-response repair units address fiber cuts and emergency restoration in carrier networks, requiring portable shelters and generator compatibility.
- Workshop:Bench-top platforms with precision stages and environmental control serve cable operator central offices and electric cooperative staging facilities.
- Industrial:Hardened splicers with explosion-proof ratings address oil field fiber deployments and utility substation automation networks.
Field deployment captures the dominant equipment volume, with On-Site applications climbing the fastest as network reliability targets tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for precision electrodes and ceramic stages exceeds domestic fabrication capacity, while export volumes remain minimal given the specialized nature of fusion splicing equipment. State broadband offices in the Southeast and Texas are absorbing inbound equipment shipments at accelerating rates. Regional procurement patterns now track federal funding disbursement timelines more closely than traditional carrier capital cycles.
Southeast
Georgia and North Carolina state broadband offices command the densest concentration of BEAD-funded splicing contracts, with fiber-to-the-home deployment targets compressing installer certification schedules. OSHA electrical safety regulations and TIA-568 field deployment protocols govern contractor equipment specifications across both states. Atlanta anchors equipment distribution logistics, while Raleigh-Durham research corridors drive specification feedback into vendor product roadmaps.
Texas
Higher-fiber-count cable migration in Dallas-Fort Worth metro rings generates ribbon splicer demand from tier-one carriers deploying 400G coherent optics. The FCC's BEAD program channels subgrantee funding toward rural county buildouts in the Permian Basin and Rio Grande Valley. Houston serves as Gulf Coast staging hub for offshore fiber repair depots requiring hermetic sealing capabilities.
Appalachia
USDA's ReConnect initiative funds electric cooperative fiber projects across Kentucky, Tennessee, and West Virginia, creating sustained demand for single-fiber field units. Appalachian electric cooperatives increasingly specify core alignment technology as network designs extend toward 25G PON horizons. Pittsburgh anchors technical training partnerships between equipment vendors and regional workforce development boards.
Pacific Northwest
Hyperscale data center interconnect buildouts in Oregon and Washington state concentrate ribbon splicer procurement among cloud infrastructure operators. State environmental regulations in Washington govern battery disposal protocols for lithium-ion powered field equipment. Seattle tech corridors influence software-defined workflow automation requirements across vendor development priorities.
Southwest
Arizona and New Mexico broadband gap-closing timelines lag national averages, creating deferred equipment demand as BEAD funding reaches later implementation phases. OSHA electrical safety regulations apply uniformly across desert deployment environments with extreme temperature operating requirements. Phoenix serves as inland distribution node for equipment staged toward Mountain West expansion routes.
United States Fusion Splicer Market Key Industry Players
Listed leaders compete with private specialists across capital access and technology licensing dimensions, producing a tiered structure where scale advantages concentrate in Japanese industrial conglomerates while agility resides in Korean and Chinese specialists. The vendor base stratifies across precision electrode system ownership, software-defined calibration capabilities, and rental fleet operator relationships. Three archetypes dominate: integrated industrial electronics groups with captive component supply, specialized optical equipment pure-plays, and diversified testing and measurement platforms seeking adjacency expansion. Competitive moves center on equipment-as-a-service subscription models and state certification program embedding.
Among Japanese industrial electronics groups, Fujikura and Sumitomo Electric Industries exemplify the integrated archetype with precision electrode system capabilities. INNO Instrument represents the Korean specialist tier competing on portability and field-optimized form factors. These three anchors illustrate the geographic clustering of competitive advantage around East Asian component supply chains and North American deployment specification influence.
| Leading Market Players |
|---|
| Fujikura |
| Sumitomo Electric Industries |
| Furukawa Electric |
| INNO Instrument |
| 3M |
| Tektronix |
| Emerson Electric |
| Northrop Grumman |
| GAO Tek |
| Others |
Cost & Logistics Intelligence
Core-alignment electrode substitution for legacy cladding systems simultaneously concentrates procurement leverage in Japanese ceramic suppliers and compresses margin pools for US equipment assemblers facing Buy America compliance friction. Tier-one carriers absorbing ribbon splicer premiums in Texas metro rings offset this pressure, while rural electric cooperatives under USDA ReConnect funding face extended lead times for precision components.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the United States Fusion Splicer Market. Price differentiation hinges on TIA-568 certification grade and active alignment capability, with core-alignment systems commanding substantial premiums over cladding-alignment commodity units. Cost compression in the single-fiber field tier is intensifying because low-cost Asian manufacturers flood enterprise LAN segments. Rural electric cooperatives exhibit highest price sensitivity due to equipment financing constraints, while hyperscale data center operators in Northern Virginia demonstrate lowest sensitivity given throughput-critical deployment economics.
Supply Chain Analysis
Strategic stockpiling of precision electrodes and ceramic V-groove arrays dominates inventory strategy among US equipment assemblers confronting Japanese and German supply concentration. Geographic supply concentrates in Japan, Germany, and South Korea for ceramic electrode manufacturing, optical fiber preparation tools, and CMOS camera modules. Raw material dependencies include zirconia ceramic substrates, tungsten-rhenium electrode alloys, and lithium-ion battery cells. Single-source vulnerability in Japanese precision electrode fabrication exposes assemblers to tariff exposure under Section 301 enforcement. Distribution runs through Atlanta and Dallas-Fort Worth staging hubs serving Southeast and Texas state broadband offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Fusion Splicer Market rewards ownership of certified technician training infrastructure and precision electrode supply relationships, with scarcity concentrated in field crews capable of sub-0.02 dB splice loss consistency under compressed BEAD deployment timelines.
For Market Incumbents: Shield core-alignment specification dominance by embedding calibration protocols into state broadband office certification programs before low-cost Asian manufacturers achieve TIA-568 compliance. Deepen backward integration into electrode ceramic fabrication through Korean or Japanese joint ventures to deflect supply concentration risk. Prioritize software-defined workflow automation R&D to differentiate beyond hardware specifications as AI-assisted arc calibration commoditizes. For New Entrants and Emerging Players: Anchor in Appalachian electric cooperative territories where USDA ReConnect funding outpaces incumbent service coverage and technician scarcity creates equipment-as-a-service white space. Target single-fiber field deployment segments in Georgia and North Carolina where BEAD subgrantees face clawback provisions favoring subscription models over capital purchase. Pursue state workforce development board partnerships to embed training modules into preferred-supplier status pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional rental fleet operators holding multi-year master service agreements with tier-one carriers. Long-term viability centers on recurring revenue attachment rates from calibration and software update subscriptions rather than equipment shipment volumes. Acquisition targets should demonstrate embedded relationships with state broadband offices translating federal funding timelines into concrete purchase order flow. Monitor BEAD disbursement velocity through state broadband office procurement dashboards as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Subscription Launch | Reduces capital deployment friction for BEAD subgrantees facing milestone clawback provisions in Georgia and Texas. |
| State Certification Program Embedding | Secures preferred-supplier status through workforce development partnerships with North Carolina and Appalachian broadband offices. |
| Precision Electrode Backward Integration | Mitigates Japanese supply concentration risk while satisfying Buy America compliance for federally funded rural fiber builds. |
| AI-Assisted Arc Calibration Deployment | Compresses technician training curves for field crews under compressed installer certification schedules. |
| Ribbon Splicer Platform Expansion | Captures hyperscale data center interconnect demand in Northern Virginia and Dallas-Fort Worth metro rings. |
Research Approach
Operator-level perspectives from fiber optic technician training directors, state broadband office procurement leads, electric cooperative engineering managers, and tier-one carrier network deployment executives anchored the qualitative base. These primary insights combined with secondary validation from FCC BEAD program disbursement records, USDA ReConnect award databases, OSHA electrical safety regulatory filings, and TIA-568 standards documentation. Bottom-up equipment shipment tracking across ribbon, single-fiber, and multimode splicer categories triangulated against top-down federal funding allocation analysis.
Sensitivity analysis tested forecast robustness across BEAD implementation velocity scenarios and precision electrode supply disruption assumptions over the projection horizon. Segmentation dimensions modeled include product type, alignment technology, end-user archetype, and deployment environment. CAGRs derived from equipment procurement cycle analysis tied to state broadband office milestone schedules and carrier capital expenditure disclosure patterns. Industry-specific forecast inputs encompassed certified technician pipeline capacity and lithium-ion battery certification timeline impacts under FCC Part 15 and Part 68 rules.
Material uncertainties — federal funding clawback enforcement, Japanese electrode export licensing shifts, and 25G PON specification finalization — sit outside the modeled envelope. Forecasts reflect assumptions regarding state broadband office procurement velocity and carrier migration timelines toward higher-fiber-count cable architectures. Revision becomes warranted when BEAD disbursement-to-procurement conversion rates cross threshold deviations from historical infrastructure program patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Washdown Scales Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Fusion Splicer Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Electro-Pneumatic Systems Market