
 Global Cryostat Market | 2026-2036
Global Cryostat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cryostat Market Foresight
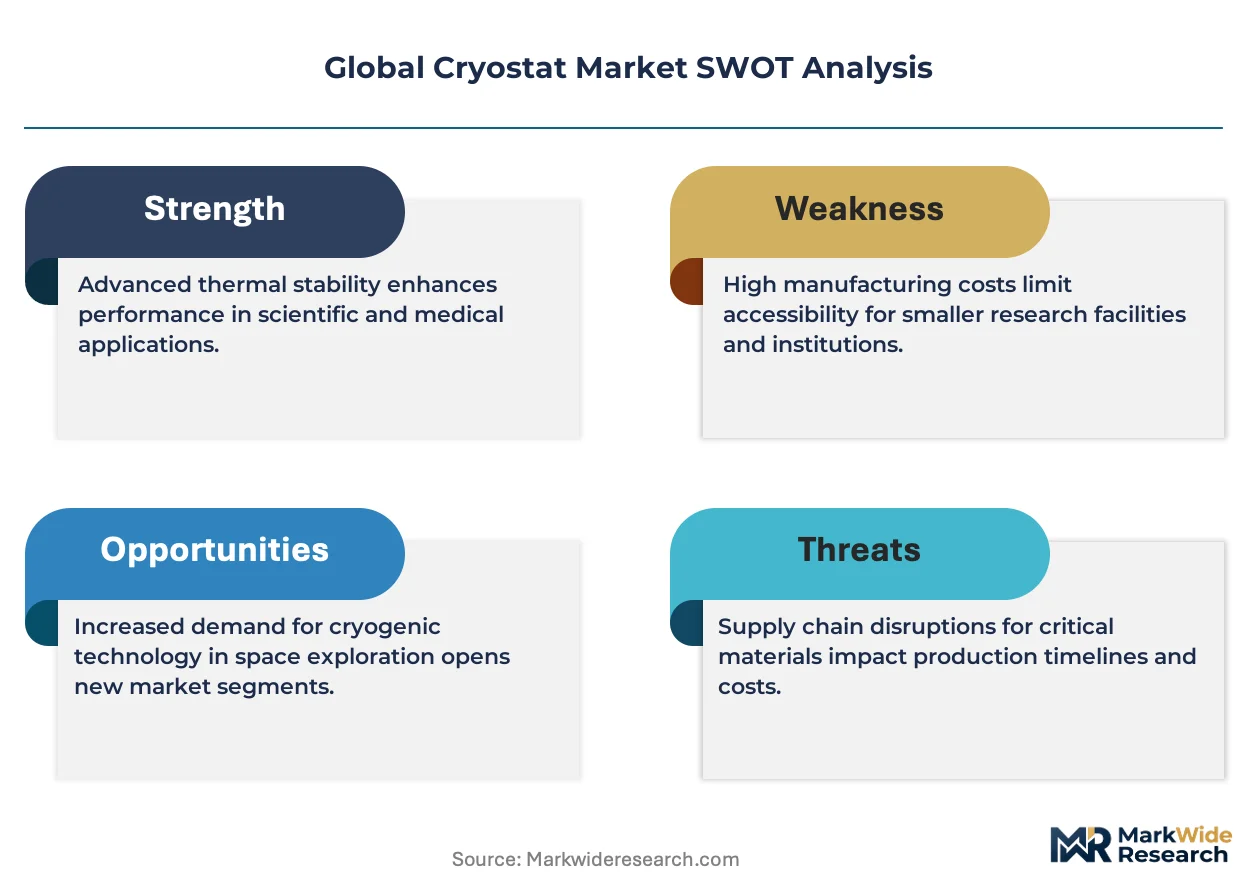
The EU Green Deal and its F-Gas Regulation is realigning procurement criteria for cryogenic cooling systems across European research consortia. Thermo Fisher Scientific Inc. leverages its installed base in semiconductor fabs to sustain service revenue streams. Cryomech Inc. anchors North American supply through in-house pulse tube manufacturing. Leica Biosystems competes in histopathology cryostats with differentiated automation features for clinical laboratories.
A cryostat is a vacuum-insulated vessel that maintains samples at cryogenic temperatures, typically below 123 Kelvin, using liquid helium, nitrogen, or mechanical refrigeration cycles; its primary purpose is to enable material characterization, biological preservation, and quantum state manipulation at temperatures where thermal noise becomes negligible. Closed cycle systems dominate installed capacity due to eliminating cryogen logistics, while dilution refrigeration leads technology investment as quantum computing roadmaps demand sub-10 millikelvin environments. Pulse tube cryocoolers capture expanding share in semiconductor testing applications where vibration sensitivity constrains Gifford-McMahon alternatives.
The EPA regulates refrigerant emissions under Section 608 of the Clean Air Act, pushing manufacturers toward closed-loop architectures, while Japan's METI funds cryogenic infrastructure through its quantum technology national program. ISO 9001 and ISO 13485 certifications govern medical and research device quality systems, creating compliance barriers for new entrants. Stakeholders must monitor how national quantum sovereignty initiatives redirect procurement toward domestic cryostat suppliers.
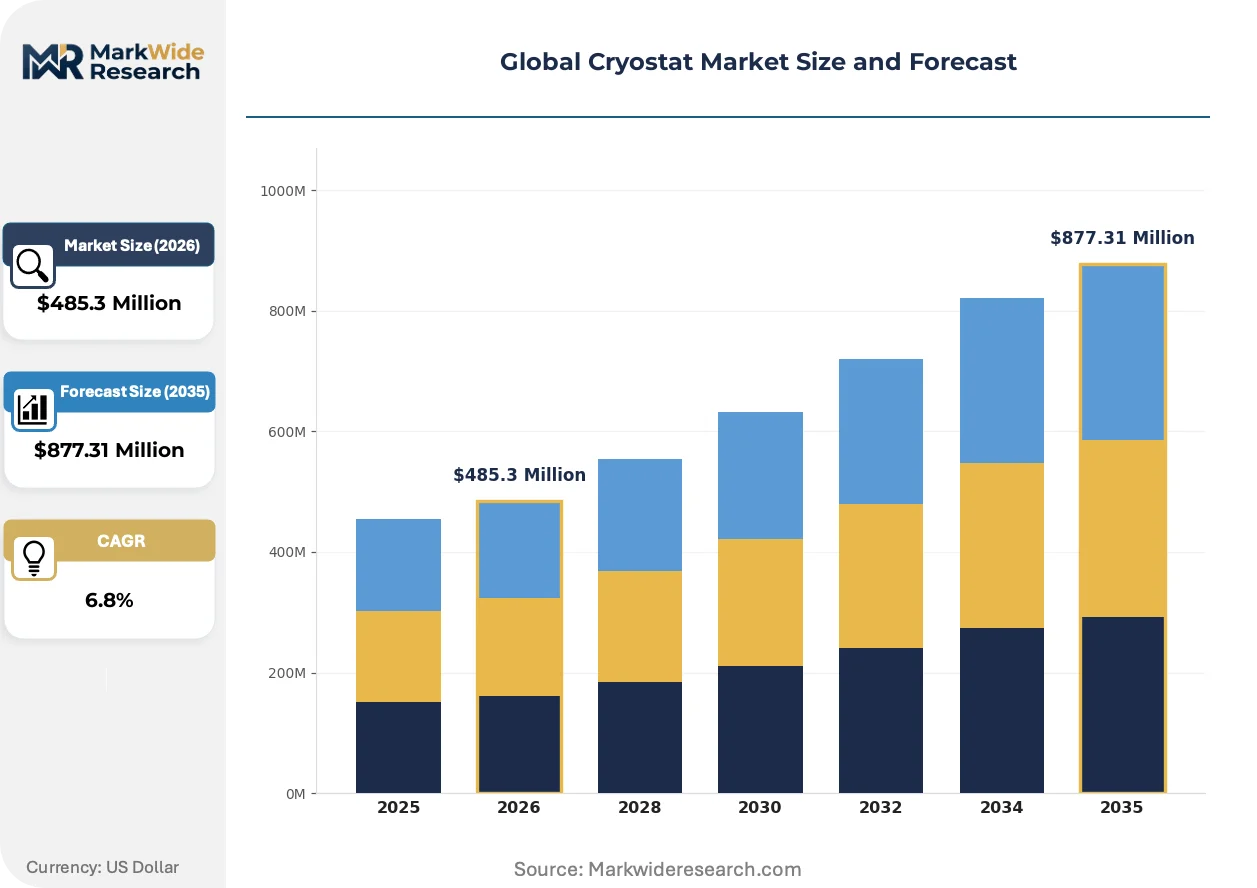
Market Dynamics
Quantum computing roadmaps at IBM and Google are compressing procurement cycles for dilution cryostats while Europe's F-Gas Regulation simultaneously constrains conventional refrigerant supply chains.
Growth Catalysts
- Quantum sovereignty programs:National initiatives in Germany, Japan, and the United States channel public funding into cryogenic infrastructure for quantum research.
- Closed-cycle architecture:Elimination of liquid helium logistics reduces operational complexity for semiconductor testing facilities and materials laboratories.
- EPA Section 608 enforcement:Emission restrictions under the Clean Air Act accelerate manufacturer migration toward closed-loop refrigeration designs.
Market Restraints
- Helium supply concentration:Geographic concentration of helium extraction in Qatar, Russia, and Algeria creates input cost volatility for open-cycle systems.
- ISO 13485 compliance barriers:Medical device quality system certification requirements extend timeline and capital burden for new histopathology cryostat entrants.
- Pulse tube technical ceiling:Vibration sensitivity constraints limit pulse tube cryocooler penetration in electron microscopy applications below certain resolution thresholds.
Strategic Opportunities
- India's PLI scheme extension:Production-linked incentives for semiconductor manufacturing create latent demand for test-stage cryogenic cooling.
- Biobank automation convergence:Integration of cryogenic storage with robotic sample handling opens clinical laboratory workflows previously served by manual systems.
- EU Green Deal procurement realignment:Research consortia are rewriting technical specifications to favor low-global-warming-potential refrigerant architectures.
Industry Challenges
- Cryogenic engineering talent scarcity:Sub-10 millikelvin system design requires specialized expertise concentrated at a handful of national laboratories and university programs.
- Legacy Gifford-McMahon retrofit complexity:Semiconductor fabs face integration friction when upgrading established vibration-sensitive test stations to pulse tube alternatives.
- CE marking timeline under MDR:Medical device regulation transition extends certification cycles for histopathology equipment destined for European clinical markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cryostat Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Cycle, Open Cycle, Continuous Flow, Bath Cryostat Technology: Pulse Tube, Gifford-McMahon, Dilution, Adiabatic Demagnetization Application: Superconductivity Research, Semiconductor Testing, Material Science, Quantum Computing End User: Academic Research Centers, Semiconductor Manufacturers, Defense Laboratories, Medical Device Firms |
| Companies Covered | Leica Biosystems, Cryomech Inc., Thermo Fisher Scientific Inc., Advanced Research Systems, Amos Scientific, Bright Instruments, Jinhua YIDI Medical Appliance Co., Ltd., SLEE Medical GmbH, Epredia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cryostat Market Shifts & Advancements
Dilution refrigeration is consolidating its position as the dominant platform for quantum processor development while regulatory pressure on fluorinated gases reshapes equipment specifications across research and clinical segments.
Pulse tube cryocooler technology is consolidating its capture of semiconductor testing applications where vibration sensitivity disqualifies Gifford-McMahon alternatives. Advanced packaging fabs in Taiwan and South Korea are specifying pulse tube systems for probe station cooling below 10 Kelvin. This consolidation is compressing the addressable market for legacy mechanical refrigeration in high-precision metrology.
Europe's F-Gas Regulation is prohibiting new equipment using refrigerants with global warming potential above specified thresholds, forcing manufacturers to redesign compressor-based systems around hydrofluoroolefin alternatives or abandon those product lines. Research consortia in Germany and France are now requiring low-GWP compliance in public tender specifications. Cryostat suppliers serving European quantum programs are responding by accelerating closed-cycle dilution systems that eliminate compressor refrigerants entirely.
Service contract unbundling is separating hardware procurement from maintenance and cryogen supply in institutional buyer negotiations. National laboratories in the United States are negotiating multi-year performance agreements that transfer operational risk to vendors. This shift is most visible at Department of Energy facilities where total-cost-of-ownership models now dominate capital allocation decisions for cryogenic infrastructure.
Global Cryostat Market Segmentation
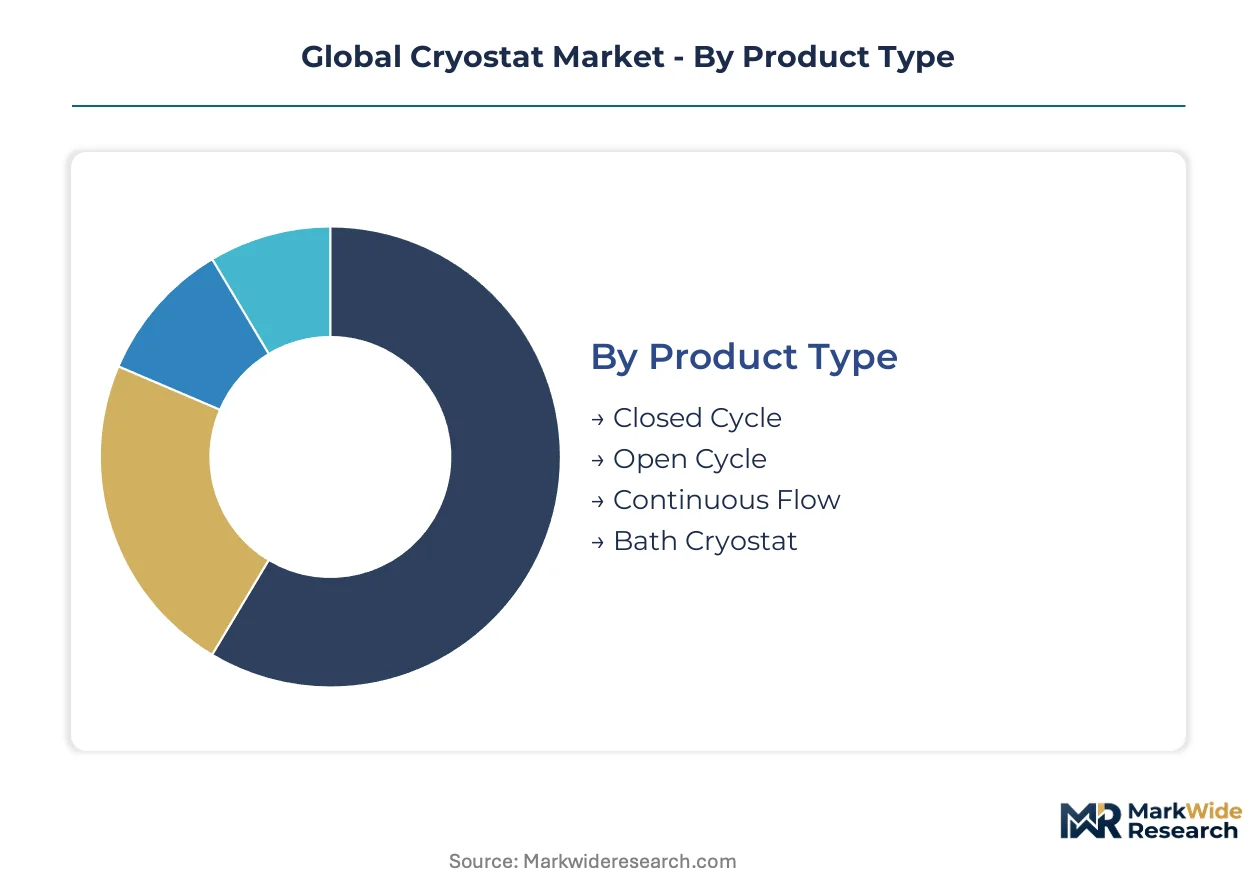
Cryostat procurement patterns diverge sharply between high-volume semiconductor testing and premium quantum research installations. Understanding these splits enables suppliers to align cooling architectures with operational constraints and total-cost-of-ownership expectations across distinct buyer segments.
Product Type:
Closed cycle systems dominate volume procurement while open cycle configurations retain niche positions where helium logistics remain manageable.
- Closed Cycle:Mechanical refrigeration eliminates liquid helium dependency through Gifford-McMahon or pulse tube architectures. Semiconductor manufacturers in Taiwan and South Korea specify these systems for probe station cooling to reduce operational complexity and supply chain exposure.
- Open Cycle:Direct liquid helium or nitrogen consumption enables sub-4 Kelvin operation without mechanical complexity. Academic research centers in Germany and Japan maintain installed bases where cryogen supply contracts remain economically viable against capital-intensive closed-cycle alternatives.
- Continuous Flow:Variable cooling power suits sample-in-vacuum configurations requiring rapid temperature cycling. Materials laboratories favor this architecture for transport property measurements across broad temperature ranges.
- Bath Cryostat:Immersion cooling provides thermal stability for sensitive detector applications in astrophysics and particle physics facilities.
Mature deployment sits with Open Cycle systems at legacy physics installations. Newer deployment is concentrated in Closed Cycle configurations as helium supply volatility accelerates buyer migration toward mechanical refrigeration.
Technology:
Pulse tube and dilution approaches are displacing legacy mechanical cooling as application requirements harden around vibration sensitivity and millikelvin reach.
- Pulse Tube:Absence of moving cold-head components reduces vibration to levels compatible with electron microscopy and precision probe stations. Advanced packaging fabs specify pulse tube systems below 10 Kelvin where Gifford-McMahon alternatives introduce measurement artifacts.
- Gifford-McMahon:Displacer-based architecture retains cost advantages for less vibration-sensitive applications above 10 Kelvin. Retrofit friction at established semiconductor test facilities slows displacement despite pulse tube performance superiority.
- Dilution:Mixing of helium isotopes achieves sub-10 millikelvin temperatures essential for quantum processor coherence. IBM and Google procurement roadmaps are compressing delivery timelines for these systems as qubit counts scale.
- Adiabatic Demagnetization:Solid-state cooling reaches microkelvin regimes for specialized condensed matter experiments without liquid helium consumption.
Established infrastructure favors Gifford-McMahon for routine cooling loads. Steepest expansion trajectory belongs to Dilution systems as national quantum programs channel funding into sub-millikelvin infrastructure.
Application:
Quantum computing roadmaps are reshaping technology investment priorities while semiconductor testing sustains near-term volume demand.
- Superconductivity Research:Characterization of high-temperature superconductors and novel materials requires variable temperature platforms with high magnetic field compatibility. National laboratories in the United States maintain concentrated demand for versatile cryogenic infrastructure.
- Semiconductor Testing:Parametric testing of devices at cryogenic temperatures identifies defect populations and validates radiation hardness. Probe station cooling represents the largest installed base by unit volume across fabrication facilities in East Asia.
- Material Science:Transport and magnetometry measurements on quantum materials drive demand for multi-axis sample rotation and optical access configurations.
- Quantum Computing:Dilution refrigeration enables superconducting and topological qubit operation by suppressing thermal decoherence. Public funding through Germany's quantum initiative and Japan's METI program is accelerating procurement cycles.
Volume concentration sits with Semiconductor Testing across fabrication ecosystems. Emerging deployment is concentrated in Quantum Computing as hardware roadmaps harden around specific qubit modalities.
End User:
Procurement authority splits between centralized national programs and decentralized industrial capital allocation processes.
- Academic Research Centers:University physics and chemistry departments operate diverse cryogenic infrastructure serving individual investigator programs. Funding through the National Science Foundation and European Research Council sustains replacement cycles for aging open-cycle systems.
- Semiconductor Manufacturers:Foundries and integrated device manufacturers specify cryogenic testing for advanced node validation and radiation-tolerant design verification. Taiwan and South Korean fabs drive regional demand concentration for closed-cycle probe station cooling.
- Defense Laboratories:Secure quantum communication and sensing applications require domestic cryogenic supply chains with cleared personnel access. Classified procurement channels limit vendor visibility into specific program requirements.
- Medical Device Firms:Histopathology cryostats for frozen section diagnosis and biobank preservation operate under ISO 13485 quality systems with distinct regulatory pathways from research equipment.
Institutional procurement maturity sits with Academic Research Centers. Accelerated deployment is concentrated in Semiconductor Manufacturers as process node complexity extends cryogenic testing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany, Japan, and the United States where quantum programs channel public funding into cryogenic infrastructure. Consumption patterns diverge as semiconductor testing demand surges across East Asian fabrication hubs while research procurement dominates Western markets.
United States
Department of Energy national laboratories drive dilution cryostat procurement for quantum processor development. EPA Section 608 enforcement under the Clean Air Act accelerates manufacturer migration toward closed-loop refrigeration designs. Greater Boston anchors superconducting qubit research with concentrated startup activity around MIT and Harvard facilities.
Germany
Federal quantum initiative funding supports sub-millikelvin infrastructure expansion at Max Planck institutes and Fraunhofer centers. EU F-Gas Regulation prohibits new equipment using high-global-warming-potential refrigerants, forcing redesigns around hydrofluoroolefin alternatives. Munich-Stuttgart corridor concentrates cryogenic engineering talent with specialized university programs.
Japan
METI quantum technology national program funds cryogenic infrastructure for superconducting and topological qubit roadmaps. Domestic semiconductor manufacturers specify pulse tube systems for advanced packaging test stations below 10 Kelvin. Tsukuba science city hosts concentrated national laboratory capacity for materials characterization at cryogenic temperatures.
South Korea
Memory and logic foundries extend cryogenic testing requirements as process node complexity advances beyond 3 nanometers. National semiconductor strategy directs capital allocation toward probe station cooling infrastructure. Seoul-Pyeongtaek corridor dominates regional demand concentration for closed-cycle mechanical refrigeration.
China
Domestic quantum computing programs accelerate dilution refrigeration procurement despite technology access constraints. National standards bodies advance indigenous cryocooler development for semiconductor testing independence. Beijing-Shanghai axis concentrates research demand while Hefei hosts specialized superconducting quantum facilities.
Global Cryostat Market Competitive Landscape
The competitive structure tilts toward technology specialists with in-house manufacturing capabilities. Vendor positioning fragments across four distinct tiers: integrated life science conglomerates, dedicated cryogenic engineering houses, regional medical device fabricators, and quantum-focused system integrators. Dominant competitive moves include strategic partnerships with national quantum programs and geographic expansion through local service subsidiaries.
Among integrated life science conglomerates, Thermo Fisher Scientific Inc. occupies a position exemplifying installed-base leverage for service revenue streams. Cryomech Inc. and Leica Biosystems represent contrasting archetypes: the former anchors North American supply through captive manufacturing capabilities, while the latter exemplifies clinical laboratory automation differentiation in histopathology segments. Jinhua YIDI Medical Appliance Co., Ltd. sits within the regional fabricator tier serving cost-sensitive medical markets.
| Leading Market Players |
|---|
| Leica Biosystems |
| Cryomech Inc. |
| Thermo Fisher Scientific Inc. |
| Advanced Research Systems |
| Amos Scientific |
| Bright Instruments |
| Jinhua YIDI Medical Appliance Co., Ltd. |
| SLEE Medical GmbH |
| Epredia |
| Others |
Supply & Pricing Matrix
Closed-cycle dilution refrigeration is displacing open-cycle helium architectures across quantum research facilities, simultaneously compressing capital expenditure thresholds for buyers and concentrating manufacturing leverage among vendors with captive pulse tube capabilities. This technology transition redraws cost economics as helium supply volatility from Qatar and Algeria forces institutional procurement committees toward total-cost-of-ownership models that privilege mechanical refrigeration despite higher upfront capital requirements.
Pricing Analysis
Cost-down pressure on standard closed-cycle systems accelerates as Taiwan and South Korean semiconductor fabs consolidate procurement volumes and demand service unbundling. Three-tier pricing structure across premium, standard, and economy levels separates quantum-grade dilution systems from probe station cooling equipment and entry-level histopathology units. ISO 13485 certification tier and after-sales service bundling drive price differentiation, with academic research centers exhibiting highest price sensitivity and defense laboratories showing lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from IBM and Google quantum programs, while distributor networks serve fragmented academic procurement. Manufacturing concentrates in Germany, Japan, and the United States, with specialized cryocooler components sourcing from Switzerland and the United Kingdom. Helium-3 isotope supply rests on nuclear weapons stockpile depletion programs and limited Russian production, creating single-source vulnerability for dilution refrigeration below 10 millikelvin. Distribution runs through national laboratory procurement offices and semiconductor fab capital equipment committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cryostat Market is becoming a vertical-integration race as vendors pursue backward integration into pulse tube cryocooler manufacturing to escape helium supply volatility and capture service revenue streams.
For Market Incumbents: Acquire specialized cryogenic engineering talent pools concentrated at Max Planck institutes and MIT programs. Lock in long-term helium-3 supply agreements before nuclear stockpile depletion accelerates. Defend against emerging Chinese cryocooler manufacturers by accelerating CE marking timelines under MDR for European clinical markets. For New Entrants and Emerging Players: The mid-market gap between premium dilution systems and economy histopathology units offers white-space opportunity in automated biobank storage integration. Target India's PLI scheme extension for semiconductor test equipment procurement. Enter through service contract unbundling partnerships with national laboratory procurement offices seeking operational risk transfer. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by life science conglomerates seeking cryogenic infrastructure exposure. Five-to-ten year viability favors vendors with quantum program partnerships and captive manufacturing rather than pure assembly operations. Watch IBM and Google qubit count roadmaps as inflection indicators for dilution cryostat procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Tube Manufacturing | Cryomech Inc. anchors North American supply through in-house production eliminating external cryocooler dependency. |
| Quantum Program Partnership Formation | Germany's federal quantum initiative channels public funding into preferred vendor relationships for sub-millikelvin infrastructure. |
| Service Contract Unbundling | Department of Energy facilities now negotiate multi-year performance agreements transferring operational risk to vendors. |
| CE Marking Acceleration under MDR | European clinical markets demand faster certification cycles as Medical Device Regulation transition extends approval timelines. |
| Helium-3 Supply Agreement Lock-in | Dilution refrigeration vendors secure isotope access from nuclear stockpile programs before Russian supply constraints tighten. |
Research Methodology
SEC filings, customs trade databases, and national laboratory procurement records formed the secondary backbone, supplemented by primary interviews with cryogenic engineering directors, semiconductor fab capital equipment managers, quantum research program officers, and histopathology laboratory supervisors. Bottom-up unit demand modeling across closed-cycle, open-cycle, continuous flow, and bath configurations triangulated against top-down spending analysis from Germany, Japan, and United States national quantum initiatives.
Historical trendline analysis of dilution refrigeration procurement cycles at IBM and Google informed projection elasticity for quantum computing application growth. Segmentation dimensions spanned product type, cooling technology, application vertical, and end-user category across the analysis window. CAGRs derived from installed base replacement cycles, quantum roadmap hardware targets, and semiconductor process node complexity trajectories. Forecast inputs incorporated helium spot price volatility indices and EPA Section 608 enforcement intensity assumptions.
Inputs from cryostat vendor order backlogs and national laboratory budget appropriations were available through the study window; gaps in classified defense procurement channels introduce uncertainty bands around military end-use estimates. Forecasts reflect documented assumptions regarding quantum qubit coherence scaling and F-Gas Regulation refrigerant phase-out timelines. Periodic stress-testing of base assumptions against METI funding announcements and EU Green Deal procurement specification changes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
Jet Dispenser Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
Press-Insertion Systems Market