
 Global Hybrid Fiber Coaxial Market | 2026-2036
Global Hybrid Fiber Coaxial Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid Fiber Coaxial Market Foresight
Asian cable equipment manufacturing clusters are recalibrating output priorities toward higher-margin DOCSIS 4.0 components. CommScope leverages its vertically integrated coaxial and fiber portfolio to anchor North American supply contracts. Huawei Technologies competes aggressively on total cost of ownership across emerging market deployments. Nokia differentiates through its unified cable access platform that spans both fiber and coaxial termination.
Hybrid Fiber Coaxial networks combine optical fiber trunk lines with coaxial cable last-mile distribution, typically operating at 1 GHz or higher spectrum bandwidth with upstream/downstream channel bonding. The architecture enables cable operators to deliver multi-gigabit internet, video broadcast, and voice services over existing coaxial drops without full fiber-to-the-home replacement. DOCSIS technology dominates capital allocation as operators prioritize backward-compatible upgrades over rip-and-replace strategies. Fiber Deep and Node+0 architectures capture the fastest expansion as providers push optical termination closer to subscriber premises to eliminate amplifier cascades and reduce signal degradation.
The Federal Communications Commission shapes US market access through broadband subsidy eligibility rules that favor gigabit-capable infrastructure. China's Ministry of Industry and Information Technology enforces GB standards for coaxial equipment interoperability within national broadband strategies. The European Telecommunications Standards Institute coordinates DOCSIS harmonization across EU member states under the Electronic Communications Code. Stakeholders must monitor spectrum reallocation debates and energy efficiency mandates that could force premature amplifier retirement cycles.
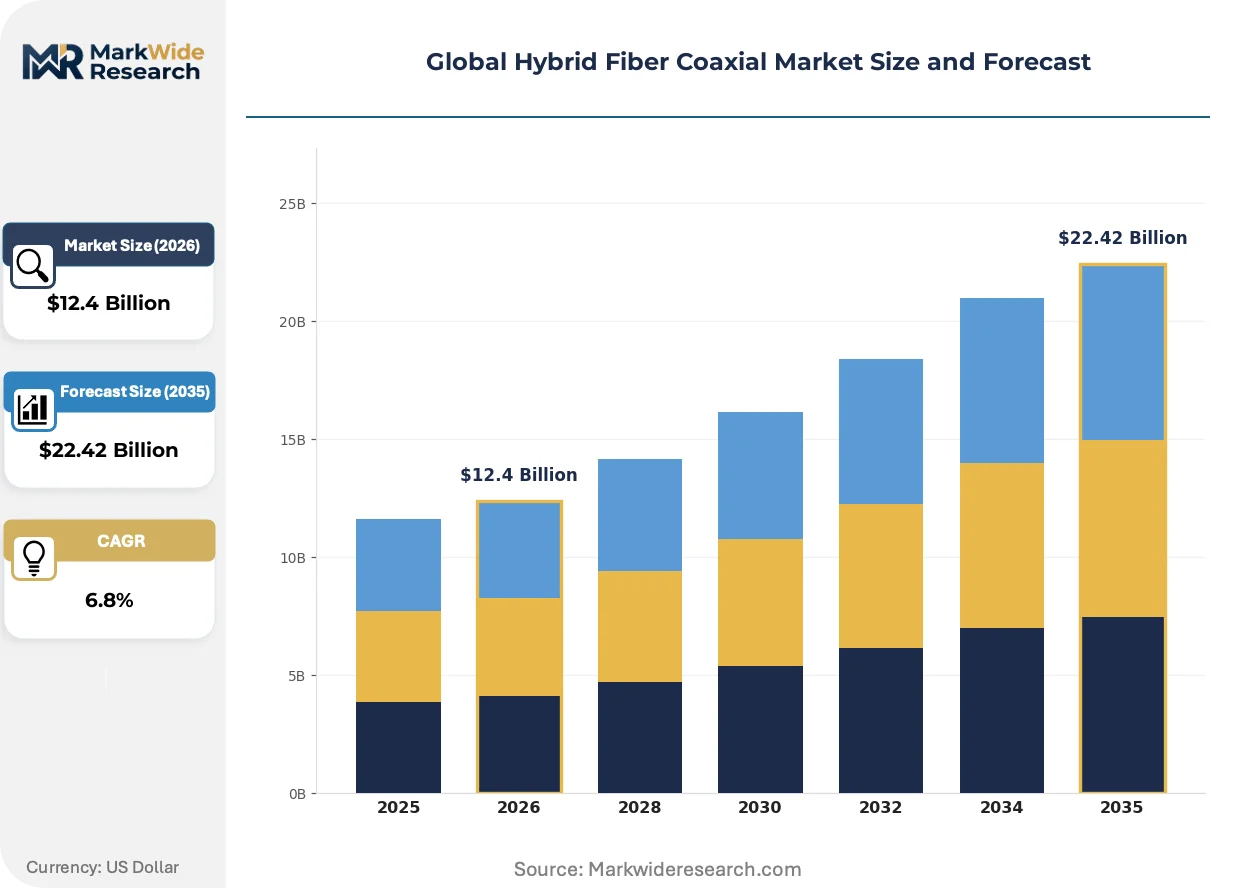
Market Dynamics
DOCSIS 4.0 migration is compressing upgrade timelines across legacy coaxial infrastructure as cable operators race to match fiber-to-the-home performance without full network replacement. This technology inflection is redistributing capital allocation between fiber-deep extensions and amplifier retirement cycles.
Growth Catalysts
- China's MIIT broadband modernization mandates:State-backed fiber-deep programs prioritize hybrid architectures in tier-two cities, creating sustained equipment procurement cycles.
- Multi-gigabit residential demand:Streaming, cloud gaming, and remote work applications are pulling bandwidth requirements beyond 1 Gbps thresholds.
- FCC broadband subsidy eligibility:Gigabit-capable infrastructure requirements under US federal programs are accelerating DOCSIS 4.0-compliant deployments.
Market Restraints
- Copper and aluminum input volatility:Coaxial cable manufacturing faces margin pressure from commodity price swings in conductor metals.
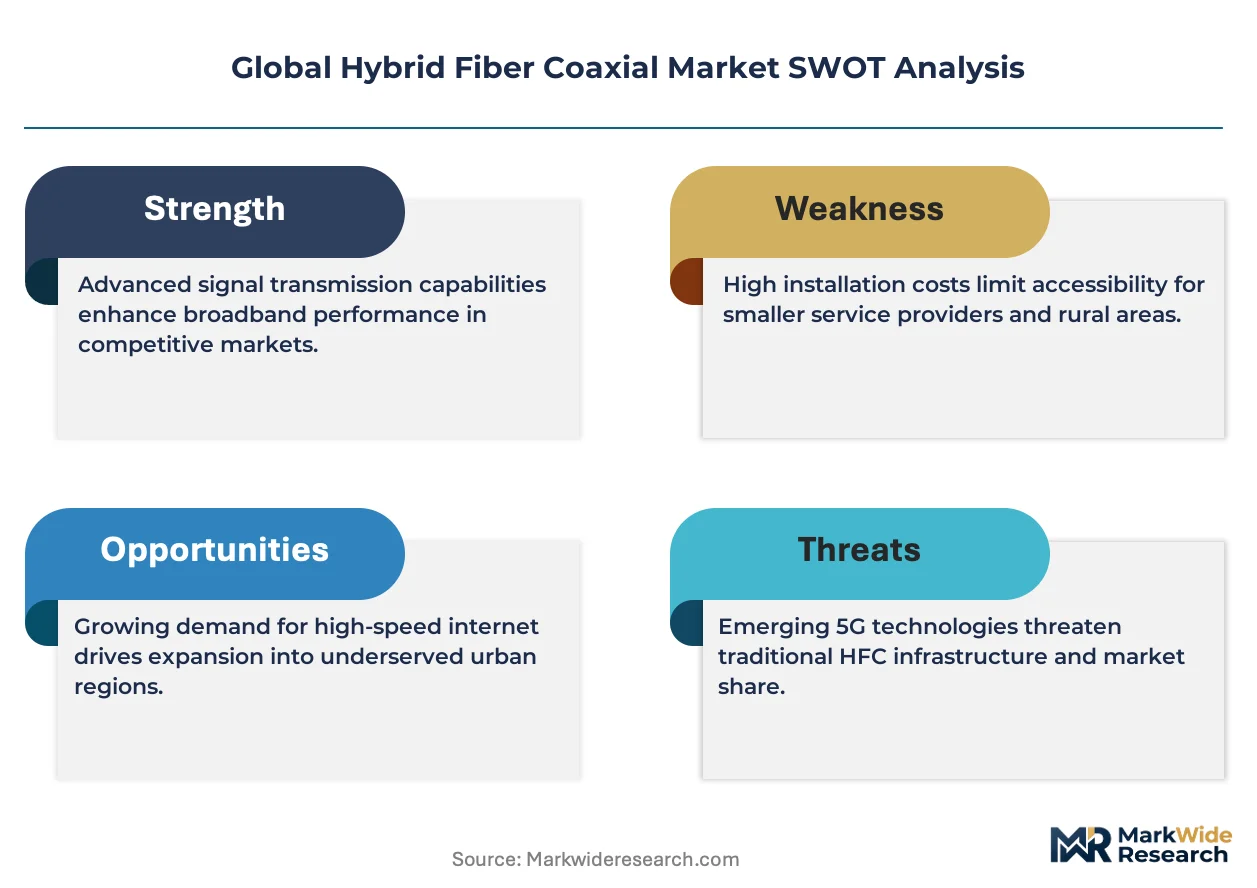
- Amplifier cascade technical ceiling:Legacy 1 GHz spectrum limits constrain upstream capacity expansion without node segmentation.
- Full-fiber substitution threat:Fiber-to-the-home deployments in greenfield developments capture addressable subscriber bases permanently.
Strategic Opportunities
- India's underpenetrated cable broadband:TRAI licensing reforms are opening addressable markets for hybrid infrastructure in secondary cities.
- Node+0 architecture convergence:Combining remote PHY with fiber-deep termination eliminates amplifier maintenance and power consumption.
- EU Green Deal energy efficiency tailwinds:Reduced amplifier counts align with mandated carbon reduction targets for telecommunications infrastructure.
Industry Challenges
- DOCSIS 4.0 certification timelines:Interoperability testing delays between vendors and cable operators compress deployment windows.
- Legacy backoffice integration friction:Billing and provisioning systems require costly adaptation to support new spectrum allocation models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid Fiber Coaxial Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Modems, Set-Top Boxes, Distribution Amplifiers, Network Switches End User: Telecom Operators, Cable Service Providers, Data Centers, Enterprises Technology: DOCSIS, RFoG, Fiber Deep, Node+0 Application: Internet Services, Video Distribution, VoIP Services, IPTV |
| Companies Covered | CommScope, Cisco Systems, Corning Incorporated, Huawei Technologies, Nokia, Arris, Ciena Corporation, Comcast, Technicolor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid Fiber Coaxial Market Shifts & Advancements
Upstream spectrum expansion is redefining service tier architectures as cable operators seek symmetry with fiber competitors. Three interconnected developments are reshaping equipment specifications and deployment economics.
Full-duplex DOCSIS is expanding into upstream spectrum blocks previously reserved for downstream traffic. Major North American MSOs are piloting 5-6 GHz upstream allocations in select markets. This technology is expanding into rural and semi-urban footprints where fiber overbuild economics remain unfavorable.
Europe's Electronic Communications Code harmonization under ETSI coordination is mandating open access provisions for cable infrastructure. Member state regulators are interpreting these rules to require wholesale availability of hybrid fiber coaxial capacity. Germany and France are experiencing the most visible compliance-driven capex reallocations toward modular access platforms.
Enterprise procurement patterns are fragmenting away from decade-long exclusive supplier contracts toward multi-vendor interoperability requirements. Large cable operators are unbundling CPE procurement from network infrastructure awards. This shift is most visible in US and Canadian markets where vertically integrated equipment strategies face procurement committee resistance.
Global Hybrid Fiber Coaxial Market Segmentation
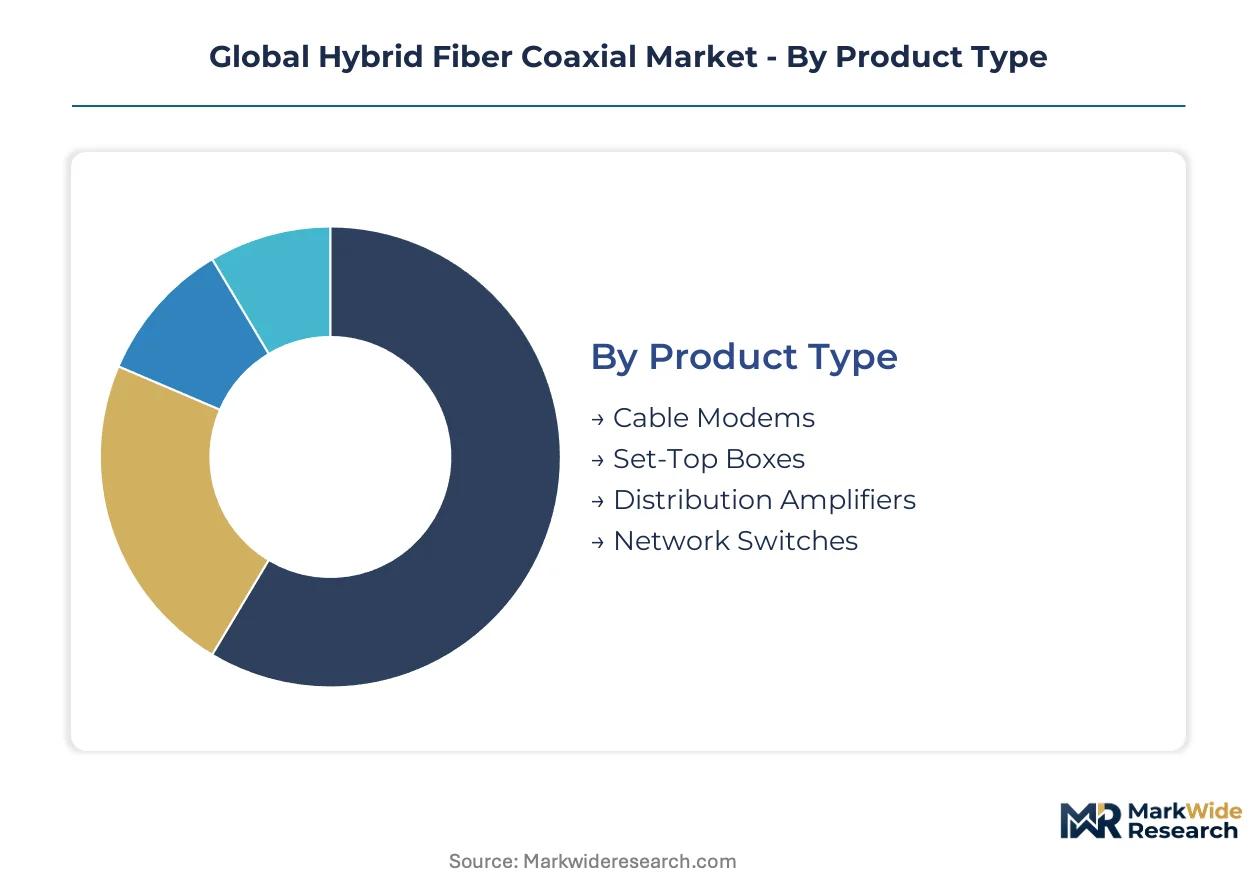
Segmentation in the Hybrid Fiber Coaxial market reveals distinct procurement patterns across infrastructure layers. Equipment specifications diverge sharply between greenfield fiber-deep deployments and legacy coaxial upgrade cycles, reshaping vendor portfolio priorities.
Product Type:
Standalone network equipment dominates capital allocation, while embedded subscriber devices operate on shorter replacement cycles tied to service tier migrations.
- Cable Modems:DOCSIS 4.0-capable modems incorporate full-duplex spectrum allocation and multi-gigabit throughput capability. Demand concentrates in North American MSO upgrade programs where FCC broadband subsidy rules mandate gigabit-capable CPE.
- Set-Top Boxes:IP-enabled video terminals integrate streaming applications alongside traditional QAM decoding. Procurement in European markets accelerates under ETSI harmonization requirements for interoperable access platforms.
- Distribution Amplifiers:Legacy 1 GHz amplifiers face replacement pressure from fiber-deep architectures eliminating cascade stages. China's MIIT fiber-deep mandates in tier-two cities sustain residual procurement.
- Network Switches:Converged cable access platforms combine fiber and coaxial termination in unified chassis designs. Data center interconnect applications in India drive adoption following TRAI licensing reforms.
Volume placements concentrate in Cable Modems; the faster expansion belongs to Network Switches.
End User:
Customer-type segmentation tracks procurement authority concentration, with infrastructure owners capturing multi-year capex cycles versus tenant-managed equipment purchasing.
- Telecom Operators:Incumbent operators deploy hybrid architectures as defensive strategy against fiber overbuilds. European operators under EU Green Deal mandates prioritize Node+0 architectures to eliminate amplifier power consumption.
- Cable Service Providers:MSOs dominate DOCSIS 4.0 migration timelines with backward-compatible upgrade roadmaps. US cable operators leverage FCC Rural Digital Opportunity Fund eligibility requirements to justify infrastructure refresh cycles.
- Data Centers:Edge computing facilities require low-latency interconnects over existing coaxial plant. Secondary city deployments in China absorb capacity from state-backed broadband modernization programs.
- Enterprises:Commercial buildings procure private hybrid networks for integrated voice, video, and data services. Multi-tenant office complexes in Indian metropolitan areas represent emerging addressable demand.
Procurement authority clusters with Cable Service Providers; enterprise verticals are climbing the fastest.
Technology:
Technology segmentation distinguishes legacy compatibility layers from next-generation spectrum architectures, with migration timelines varying by infrastructure vintage and competitive pressure intensity.
- DOCSIS:Dominant cable access standard spanning 3.1 and 4.0 specifications with full-duplex upstream expansion. North American operators prioritize DOCSIS 4.0 certification to match fiber-to-the-home performance benchmarks.
- RFoG:Radio frequency over glass enables coaxial service emulation over passive optical networks. Niche deployments persist in greenfield developments where fiber infrastructure precedes service activation.
- Fiber Deep:Architecture pushes optical termination to within 500 meters of subscriber premises. China's MIIT-mandated fiber-deep programs in provincial cities sustain equipment procurement momentum.
- Node+0:Eliminates amplifier cascades through remote PHY placement at fiber-coaxial boundary. EU Green Deal energy efficiency targets accelerate Node+0 adoption across German and French cable networks.
Deployment scale favors DOCSIS; Node+0 architectures are gaining share fastest.
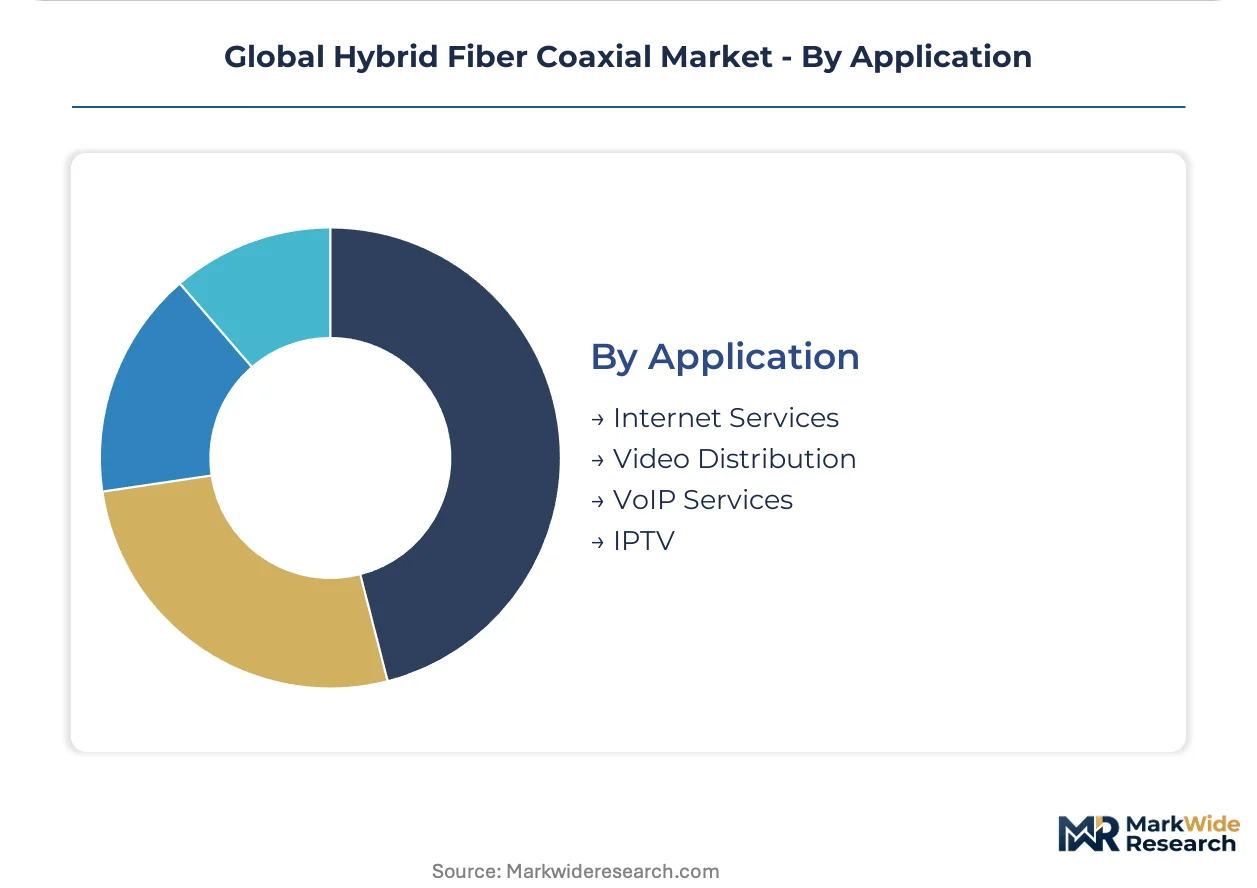
Application:
Application segmentation tracks service revenue attribution, with bandwidth-intensive uses commanding infrastructure priority in capacity-constrained network segments.
- Internet Services:Multi-gigabit residential broadband represents the primary revenue driver for hybrid infrastructure investment. Cloud gaming and remote work applications in US and Canadian markets pull bandwidth requirements beyond legacy provisioning.
- Video Distribution:Linear broadcast and on-demand streaming converge on IP-based delivery architectures. European open access mandates under the Electronic Communications Code reshape wholesale video capacity pricing.
- VoIP Services:Voice over IP termination leverages guaranteed upstream spectrum allocation in DOCSIS 3.1 and 4.0. Enterprise PBX replacement cycles in India drive secondary market demand.
- IPTV:Managed television services compete with over-the-top streaming through quality-of-service guarantees. Chinese state-owned operators bundle IPTV with broadband subscriptions under national broadband strategy targets.
Revenue concentration rests with Internet Services; IPTV applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and aluminum smelting clusters in northern China anchor raw material supply for coaxial cable manufacturing, with downstream fabrication concentrated in coastal provinces serving domestic broadband modernization and export markets.
United States
Multi-gigabit residential demand from cloud gaming and remote work applications drives DOCSIS 4.0 upgrade cycles. FCC Rural Digital Opportunity Fund eligibility rules mandate gigabit-capable infrastructure for subsidy access. Equipment procurement concentrates in Denver and Atlanta metro areas where cable operator headquarters coordinate national deployment roadmaps.
China
State-backed fiber-deep programs in tier-two cities sustain equipment procurement momentum for hybrid architectures. MIIT enforces GB standards for coaxial equipment interoperability within national broadband strategies. Manufacturing clusters in Jiangsu and Guangdong provinces recalibrate output toward higher-margin DOCSIS 4.0 components.
Germany
EU Green Deal energy efficiency mandates accelerate Node+0 adoption to eliminate amplifier power consumption. ETSI coordinates DOCSIS harmonization across member states under the Electronic Communications Code. Cable network modernization concentrates in North Rhine-Westphalia where incumbent operators deploy converged access platforms.
India
TRAI licensing reforms open addressable markets for hybrid infrastructure in secondary cities with underpenetrated cable broadband. National broadband targets prioritize multi-technology deployment flexibility. Procurement activity clusters in Mumbai and Bengaluru where cable operators pilot fiber-deep extensions.
Global Hybrid Fiber Coaxial Market Competitive Landscape
Global majors compete with regional champions across technology licensing and equipment supply, producing a tiered structure where scale-driven vendors anchor North American contracts while cost-optimized specialists capture emerging market share. The vendor base spans vertically integrated cable component fabricators, converged access platform developers, and subscriber equipment specialists. Three archetypes dominate: full-stack infrastructure providers, modular component specialists, and operator-captive equipment divisions. Competitive intensity concentrates on backward integration into coaxial cable manufacturing and strategic partnerships for DOCSIS 4.0 certification acceleration.
Within the infrastructure tier, CommScope leverages its vertically integrated portfolio to anchor North American supply relationships, while Huawei Technologies competes aggressively on total cost of ownership across emerging market deployments. Nokia occupies a distinct position through its unified cable access platform spanning fiber and coaxial termination. These three exemplify the strategic divergence between geographic market focus and technology integration depth.
| Leading Market Players |
|---|
| CommScope |
| Cisco Systems |
| Corning Incorporated |
| Huawei Technologies |
| Nokia |
| Arris |
| Ciena Corporation |
| Comcast |
| Technicolor |
| Others |
Supply & Pricing Matrix
FCC Rural Digital Opportunity Fund gigabit mandates are compressing procurement timelines for DOCSIS 4.0-compliant equipment, forcing manufacturers to absorb certification acceleration costs while cable operators demand extended warranty bundles that compress upfront hardware margins.
Pricing Analysis
Extended field-service warranties and DOCSIS 4.0 interoperability certifications are increasingly unbundled from base hardware quotes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Price differentiation stems from backward integration into coaxial cable manufacturing versus component sourcing. Cost compression in economy-tier amplifiers is intensifying because fiber-deep architectures eliminate cascade stages. Tier-two city cable operators in China exhibit highest price sensitivity; North American MSOs prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Direct-to-MSO channels handle hyperscale buyer demand for converged access platforms, while distributor networks serve secondary city deployments in India and tier-two China markets. Manufacturing concentrates in China, Vietnam, and Mexico for coaxial cable fabrication and amplifier assembly. Raw material flows draw from copper smelters in northern China, aluminum conductors from domestic mills, and specialty optical components from Japan and South Korea. Single-source vulnerability in DOCSIS 4.0 silicon creates bottleneck risk for remote PHY deployments. Distribution runs through operator-direct procurement for infrastructure tiers and retail channels for subscriber equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive DOCSIS 4.0 certification pipelines, as interoperability testing delays force smaller equipment suppliers into distressed exits.
For Market Incumbents: Deepen backward integration into coaxial cable manufacturing to defend against commodity metal price volatility. Anchor North American supply relationships through vertically integrated fiber-coaxial portfolios. Prioritize Node+0 architecture R&D to capture EU Green Deal amplifier retirement cycles. Lock in multi-year MSO service contracts that bundle extended warranties with hardware refresh programs. For New Entrants and Emerging Players: Begin with India's underpenetrated cable broadband segment where TRAI licensing reforms have fragmented procurement authority. Target secondary city fiber-deep deployments where state-backed programs absorb capacity without exclusive supplier requirements. Pursue modular remote PHY component supply rather than full-stack infrastructure competition. Establish technical partnerships with established certification labs to compress DOCSIS 4.0 approval timelines. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive DOCSIS 4.0 certification pipelines and established China manufacturing footprints. Long-term viability hinges on backward integration depth and operator-direct channel control. Watch for DOCSIS 4.0 interoperability testing completion rates as the inflection signal separating viable vendors from distressed assets.| Strategic Initiative | Industry Significance |
|---|---|
| DOCSIS 4.0 Certification Acceleration | Compresses vendor approval timelines under FCC gigabit subsidy deadlines. |
| Fiber-Deep Architecture Deployment | Aligns with China's MIIT mandates in provincial tier-two city programs. |
| Node+0 Remote PHY Convergence | Captures EU Green Deal energy efficiency mandates across German networks. |
| Backward Integration into Coaxial Manufacturing | Defends margin position against copper and aluminum commodity volatility. |
| Multi-Vendor Interoperability Partnership | Responds to North American MSO procurement committee unbundling preferences. |
Research Methodology
Trade association filings, customs import records, and FCC equipment authorization databases formed the secondary backbone for market sizing. Primary interviews with cable operator network planning executives, DOCSIS certification lab directors, and coaxial cable procurement managers at Tier 1 MSOs validated equipment shipment assumptions. Bottom-up triangulation across vendor-reported deployment volumes and top-down reconciliation against national broadband subsidy disbursements anchored value estimates.
Bottom-up modeling aggregated operator capex disclosures by technology segment, while top-down constraints applied national broadband targets from MIIT, FCC, and EU Electronic Communications Code harmonization schedules. Segmentation dimensions spanned product type, end user procurement authority, technology migration stage, and regional regulatory framework. CAGRs were derived from fitted adoption curves for DOCSIS 4.0 migration timelines and fiber-deep architecture penetration rates across the analysis window. Forecast inputs incorporated commodity metal price trajectories and amplifier retirement cycle assumptions under EU energy efficiency mandates.
DOCSIS 4.0 certification delays, copper price volatility spikes, and fiber-to-the-home substitution acceleration in greenfield developments are the dominant revision risks. Forecasts reflect documented assumptions regarding operator upgrade cycle timing and interoperability testing completion rates. Practitioners should monitor FCC subsidy disbursement velocity and MIIT provincial procurement announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market