
 Electro-Pneumatic Systems Market | 2026-2036
Electro-Pneumatic Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electro-Pneumatic Systems Market Analytics
Capital-intensity divergence between integrated component manufacturers and modular subsystem suppliers is reorganizing competitive tiers in electro-pneumatic systems. Emerson Electric Co. leverages captive semiconductor fabrication for its valve controller chipsets, sustaining margin protection against commodity actuator pricing. Parker Hannifin Corporation anchors its position through backward integration into high-performance elastomer sealing compounds. Festo SE & Co. KG differentiates via embedded IoT diagnostics that preempt field failures in automotive customer plants.
Electro-pneumatic systems integrate electrically actuated solenoid valves, position sensors, and programmable logic interfaces to convert electronic control signals into precise mechanical motion using compressed air at typical operating pressures of 4 to 10 bar. These assemblies execute positioning, clamping, and motion sequences in environments where electric motor alternatives risk ignition hazards or electromagnetic interference. Valve and actuator product categories command the largest installed base but face margin compression from Asian producers, while digital control technology segments extract premium pricing through firmware-locked predictive maintenance capabilities. Feedback systems technology is expanding fastest as end users demand closed-loop verification for robotic assembly line applications in automotive and electronics manufacturing.
ISO 4414 pneumatic fluid power standards, EU Machinery Directive 2006/42/EC safety requirements, and OSHA compressed air safety regulations in the United States collectively shape product certification burdens and aftermarket service obligations. REACH chemical compliance in Europe and RoHS substance restrictions constrain elastomer and coating material selections for valve manufacturers serving medical and food processing end users. Stakeholders must monitor evolving cybersecurity mandates for networked pneumatic controllers as factory digitization exposes previously isolated air systems to remote access vulnerabilities.
Market Dynamics
Automotive assembly plants in Germany and Japan are accelerating their replacement of discrete pneumatic components with intelligent valve arrays, compressing procurement cycles and forcing subsystem suppliers to absorb firmware development costs previously borne by end users.
Growth Catalysts
- EU F-Gas Regulation:Tightening permissible leakage rates for compressed air infrastructure is compelling plant operators to upgrade legacy valve networks, generating replacement demand across European manufacturing corridors.
- Shanghai-Shenzhen industrial corridor:East Asian electronics contract manufacturers are deploying closed-loop electro-pneumatic positioning systems for smartphone assembly automation at scale.
- Intelligent valve arrays:Embedded IoT diagnostics that preempt field failures are reducing unplanned downtime penalties in automotive customer plants.
Market Restraints
- Semiconductor input volatility:Captive fabrication capacity for valve controller chipsets remains concentrated among integrated manufacturers, exposing modular suppliers to foundry allocation risk.
- High-performance elastomer supply:Backward integration into specialized sealing compounds by dominant players creates entry barriers for new subsystem assemblers.
- Electric servo substitution:Precision motion applications below 4 bar operating pressure increasingly migrate to brushless DC alternatives where ignition hazards do not apply.
Strategic Opportunities
- Underpenetrated medical device manufacturing:REACH and RoHS-compliant valve configurations for sterile processing equipment remain underserved by incumbent industrial-focused suppliers.
- Cybersecurity mandate convergence:Factory digitization exposes previously isolated pneumatic controllers to remote access vulnerabilities, creating aftermarket security retrofit demand.
- Predictive maintenance firmware:Firmware-locked diagnostic capabilities enable recurring revenue streams distinct from commodity actuator hardware margins.
Industry Challenges
- Multi-standard certification complexity:ISO 4414 pneumatic fluid power standards, EU Machinery Directive 2006/42/EC, and OSHA compressed air safety regulations impose overlapping compliance timelines for multinational deployments.
- Legacy system integration friction:Closed-loop feedback systems require retrofitting position sensors onto existing pneumatic cylinders, complicating upgrade economics for depreciated plant equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro-Pneumatic Systems Market |
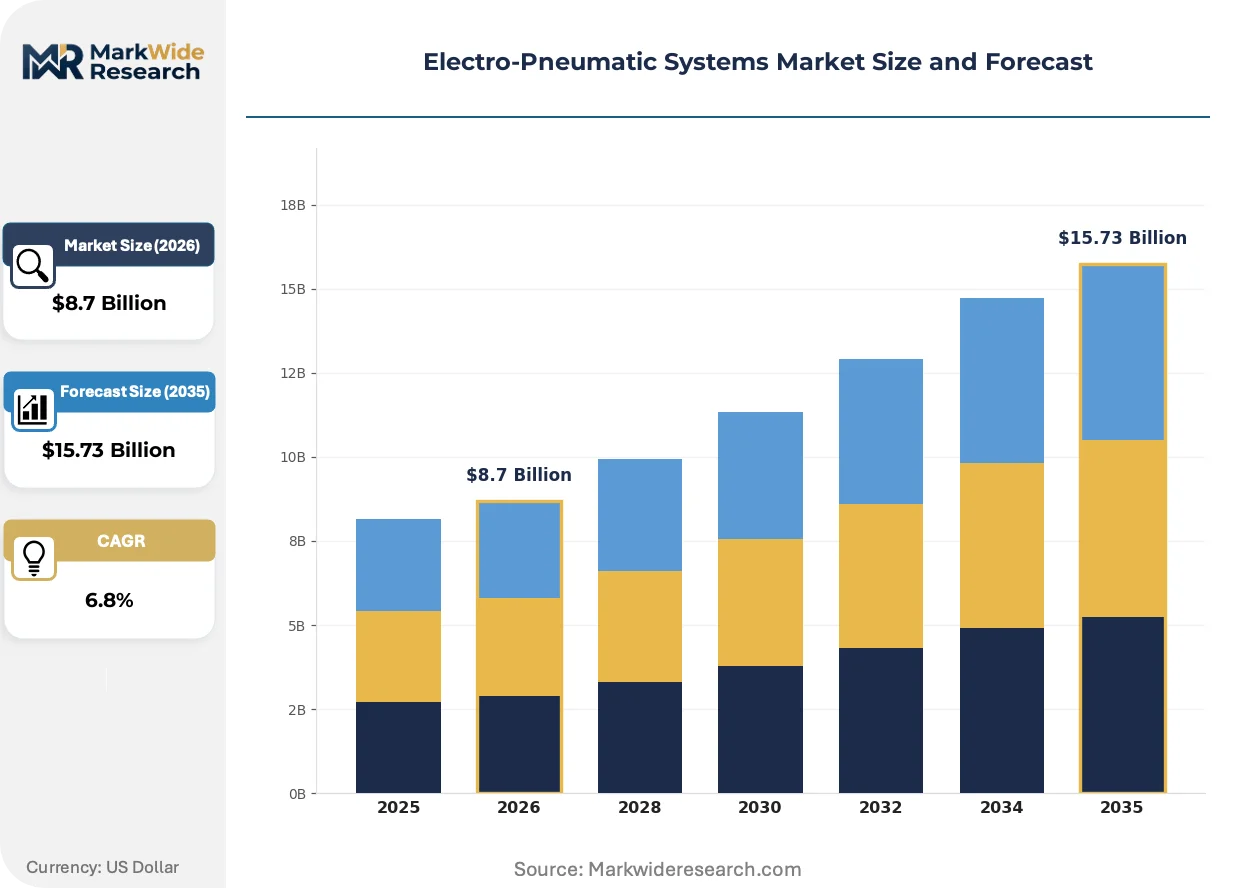
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valves, Actuators, Sensors, Controllers End User: Manufacturing, Automotive, Healthcare, Aerospace Technology: Digital Control, Feedback Systems, Communication Protocols, Energy Management Application: Material Handling, Robotics, Assembly Lines, Process Automation |
| Companies Covered | Emerson Electric Co., Parker Hannifin Corporation, Festo SE & Co. KG, SMC Corporation, Bosch Rexroth AG, Rotork plc, Airtac International Group, IMI Precision Engineering, Danfoss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro-Pneumatic Systems Market Evolving Landscape
Digital control technology segments are extracting premium pricing through embedded diagnostics, while valve and actuator hardware faces persistent margin compression from Asian manufacturing scale.
Intelligent valve arrays with integrated position sensing and edge computing capability are fragmenting the traditional separation between pneumatic actuation and electronic control. Automotive OEMs in Stuttgart and Toyota City are specifying these subsystems for new robotic welding lines. The technology is fragmenting procurement patterns as end users bypass discrete component distributors to source complete motion modules directly from subsystem integrators.
REACH chemical compliance and RoHS substance restrictions are constraining elastomer and coating material selections for valve manufacturers serving medical and food processing end users. Industrial consequence includes accelerated qualification cycles for alternative compound formulations. Medical device manufacturers in Ireland and Switzerland are responding by consolidating supplier bases to vendors with pre-validated material portfolios.
After-sales service unbundling is compressing traditional maintenance contract structures as end users demand à-la-carte diagnostic subscriptions separate from hardware procurement. Distributor networks in the US Midwest and German Ruhr region are being disrupted by direct manufacturer-to-plant digital service platforms. Electronics contract manufacturers around Shenzhen exhibit the most aggressive adoption of this consumption-pattern shift.
Electro-Pneumatic Systems Market Segmentation
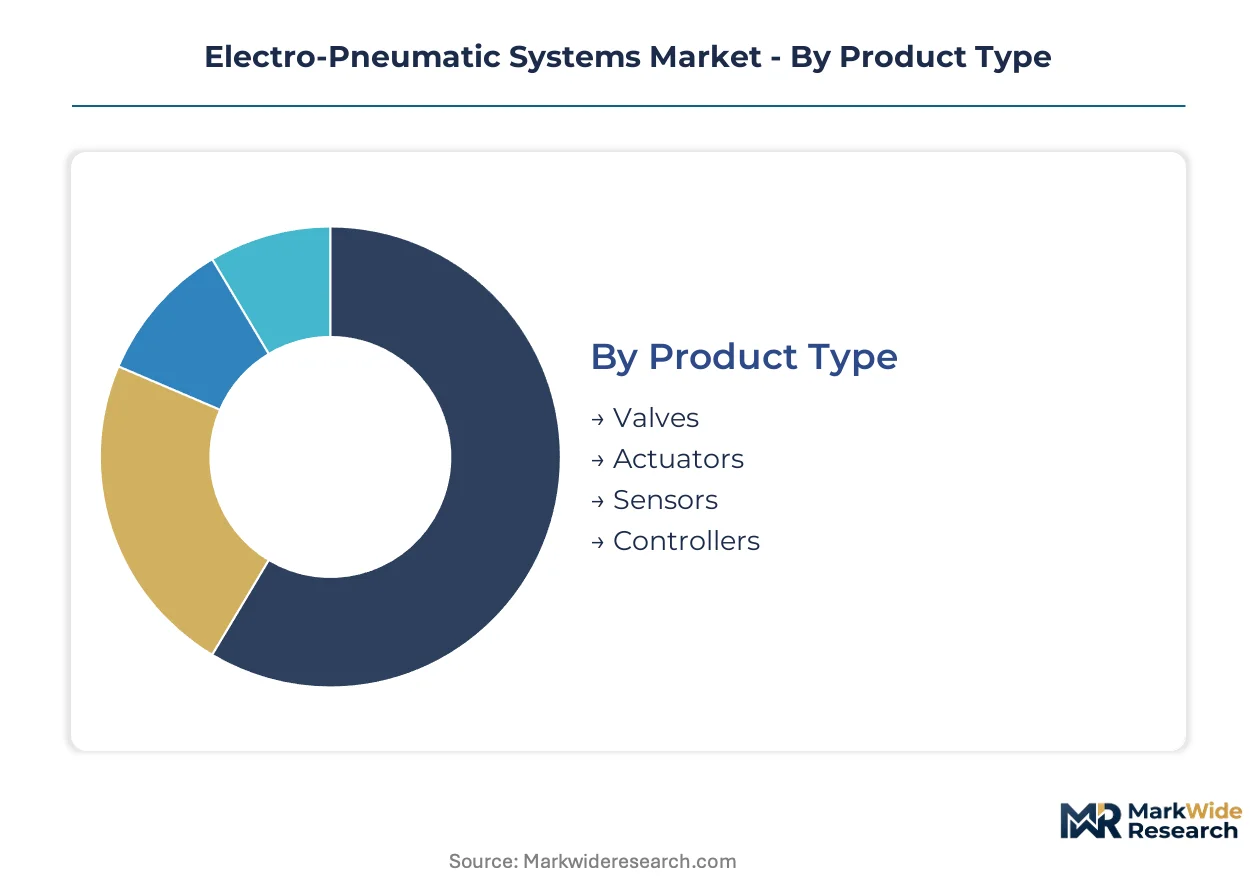
Segmentation in electro-pneumatic systems reveals how substitution pressures from electric servo technologies concentrate in specific product tiers while digital control segments extract defensive margins through firmware differentiation. Understanding these fracture lines guides capital allocation across hardware commoditization zones and software-anchored value pools.
Product Type:
Electric servo substitution threats intensify most acutely in valve and actuator hardware, where Asian manufacturing scale compresses pricing power and pushes integrated suppliers toward captive semiconductor strategies.
- Valves:Solenoid-operated directional and proportional valves regulate compressed air flow at 4-10 bar operating pressures. Automotive assembly plants in Germany specify intelligent valve arrays with embedded diagnostics, absorbing firmware costs that discrete component suppliers struggle to match.
- Actuators:Pneumatic cylinders and rotary actuators convert air pressure into linear or rotational mechanical motion. Material handling operations in the US Midwest face compressed air infrastructure upgrades driven by OSHA safety compliance and leakage reduction mandates.
- Sensors:Position and pressure transducers enable closed-loop control verification.
- Controllers:Programmable logic interfaces with valve driver electronics command premium pricing through predictive maintenance firmware locked to specific hardware configurations.
Valves retain volume leadership; controllers hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive automotive and aerospace installations from price-sensitive manufacturing segments where maintenance contract unbundling disrupts traditional supplier economics.
- Manufacturing:General industrial automation spans food processing, packaging, and metalworking applications. Electronics contract manufacturers around Shenzhen industrial zones deploy closed-loop positioning systems for smartphone assembly at scale.
- Automotive:OEMs and tier suppliers specify intelligent valve arrays for robotic welding and precision assembly sequences. Toyota City and Stuttgart plants demand embedded IoT diagnostics that preempt unplanned downtime penalties.
- Healthcare:Medical device manufacturers in Ireland and Switzerland require REACH and RoHS-compliant valve configurations for sterile processing equipment.
- Aerospace:Flight control surface actuation and landing gear systems utilize electro-pneumatic assemblies where ignition hazard constraints exclude electric alternatives.
Manufacturing commands the largest installed base; healthcare climbs the fastest as regulatory compliance consolidates supplier relationships.
Technology:
Application maturity divides established digital control architectures from emerging feedback systems where closed-loop verification demands reshape procurement toward subsystem integrators.
- Digital Control:Programmable logic controllers and valve driver electronics with embedded firmware extract recurring revenue through diagnostic subscriptions separate from hardware procurement.
- Feedback Systems:Integrated position sensing and edge computing capability fragment traditional boundaries between pneumatic actuation and electronic control. Automotive OEMs specify these modules for new robotic lines, bypassing discrete component distributors.
- Communication Protocols:Industrial Ethernet and fieldbus interfaces enable networked pneumatic controller integration.
- Energy Management:Air consumption monitoring and demand-based compressor control reduce operating costs in high-volume compressed air installations.
Digital control dominates current revenue; feedback systems gain share fastest as end users consolidate motion module sourcing.
Application:
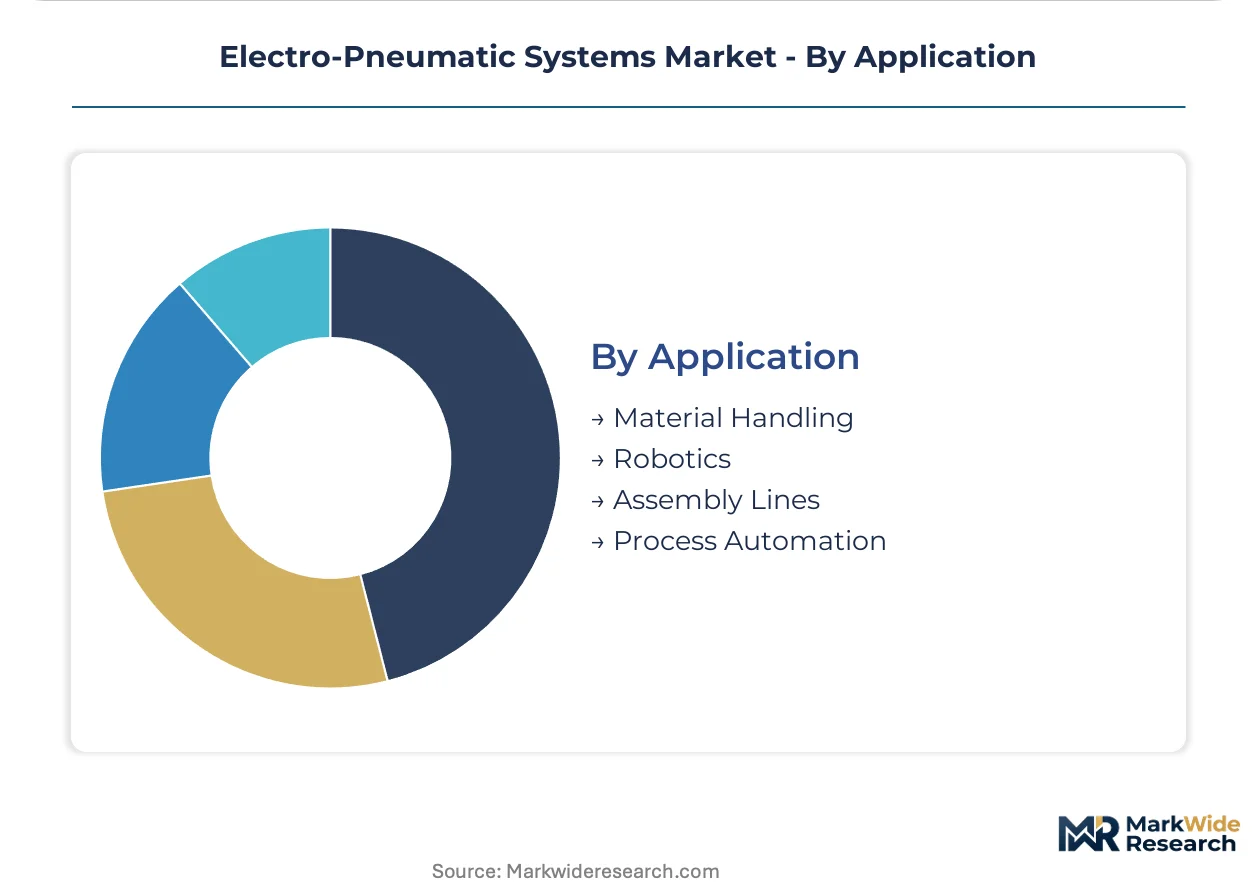
Customer type concentration in electronics contract manufacturing concentrates demand for precision positioning while process automation retains legacy infrastructure friction that complicates upgrade economics.
- Material Handling:Conveyor systems, pick-and-place mechanisms, and automated guided vehicles utilize pneumatic actuation for cost-effective motion sequences below 4 bar pressure thresholds where electric servos compete aggressively.
- Robotics:Articulated arm and Cartesian coordinate systems require closed-loop electro-pneumatic positioning for welding, painting, and assembly operations. Shanghai-Shenzhen corridor manufacturers scale deployment for consumer electronics production.
- Assembly Lines:Clamping, pressing, and fastening operations in automotive body shops.
- Process Automation:Valve networks for chemical and pharmaceutical batch processing face multi-standard certification complexity across ISO 4414, EU Machinery Directive 2006/42/EC, and OSHA compressed air regulations.
Material handling sustains the broadest deployment footprint; robotics exhibits the sharpest trajectory acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German automotive buyers absorb firmware premiums for intelligent valve arrays, while electronics assemblers in Shenzhen industrial zones prioritize unit cost minimization for high-volume pneumatic positioning systems.
Germany
Automotive OEMs in Stuttgart specify embedded IoT diagnostics for robotic welding lines, accepting higher subsystem costs to preempt unplanned downtime penalties. EU F-Gas Regulation tightening leakage rates compels compressed air infrastructure upgrades across Baden-Württemberg manufacturing corridors. Festo SE & Co. KG anchors intelligent valve array supply from its Esslingen headquarters to Toyota City and Stuttgart plants.
China
Electronics contract manufacturers in Shanghai and Shenzhen deploy closed-loop electro-pneumatic positioning systems for smartphone assembly automation at massive scale. MIIT industrial digitization directives accelerate factory automation adoption in Yangtze River Delta manufacturing zones. Dual carbon goals from MEE pressure compressed air energy efficiency improvements in Pearl River Delta electronics clusters.
United States
OSHA compressed air safety regulations drive valve network replacements in Midwest material handling operations, particularly around Chicago industrial corridors. FDA compliance requirements for medical device manufacturers in Minnesota and Massachusetts constrain elastomer and coating material selections. Parker Hannifin Corporation leverages its Cleveland-area presence to serve automotive and aerospace customers with backward-integrated sealing compound supply.
Japan
METI factory automation incentives support intelligent valve array adoption at Toyota City and Nagoya automotive assembly plants. JIS standards harmonization with ISO 4414 reduces certification friction for pneumatic subsystem exports. SMC Corporation anchors domestic supply chains from its Tokyo headquarters while expanding embedded diagnostic capabilities for automotive robotics applications.
Switzerland
Swissmedic medical device regulations and REACH chemical compliance consolidate supplier relationships for sterile processing equipment manufacturers in Basel and Zurich. Medical device OEMs demand pre-validated elastomer portfolios that industrial-focused valve suppliers struggle to match. Precision engineering heritage supports premium positioning for feedback systems technology in pharmaceutical automation applications.
Electro-Pneumatic Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated component manufacturers with captive semiconductor fabrication defend margin positions against modular subsystem suppliers exposed to foundry allocation risk. Three archetypes dominate: diversified industrial conglomerates with backward integration into sealing compounds, precision automation specialists with embedded IoT diagnostics, and scale-driven Asian component fabricators. Competitive dynamics center on M&A activity consolidating elastomer supply chains and strategic partnerships bridging firmware development costs between valve array suppliers and automotive OEMs.
Among diversified industrial conglomerates, Emerson Electric Co., Parker Hannifin Corporation, and Festo SE & Co. KG exemplify contrasting defensive strategies. Emerson leverages captive semiconductor fabrication for valve controller chipsets. Parker anchors position through in-house production of high-performance elastomer sealing compounds. Festo differentiates via embedded IoT diagnostics that preempt field failures in automotive customer plants. These three represent the premium-tier vector where firmware-locked capabilities extract recurring revenue distinct from commodity hardware margins.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Parker Hannifin Corporation |
| Festo SE & Co. KG |
| SMC Corporation |
| Bosch Rexroth AG |
| Rotork plc |
| Airtac International Group |
| IMI Precision Engineering |
| Danfoss |
| Others |
Value Network & Pricing Analysis
Electric servo substitution in sub-4 bar precision motion applications simultaneously shifts procurement geography toward Asian manufacturing clusters and compresses pricing power in commodity valve and actuator tiers. This displacement dynamic forces electro-pneumatic suppliers to absorb firmware development costs previously borne by end users while concentrating margin defense in controller segments with captive semiconductor fabrication.
Pricing Analysis
After-sales diagnostic subscriptions now drive lifetime value beyond hardware procurement, with firmware-locked predictive maintenance capabilities extracting recurring revenue distinct from commodity actuator margins. Three-tier pricing structure across premium intelligent valve arrays, standard discrete components, and economy Asian-manufactured actuators reflects certification grade and embedded IoT capability differentiation. Cost compression in valve and actuator hardware intensifies because electronics contract manufacturers in Shenzhen prioritize unit cost minimization for high-volume positioning systems. Electronics assemblers exhibit the sharpest price sensitivity, while German automotive OEMs absorb firmware premiums for downtime-prevention diagnostics.
Supply Chain Analysis
Strategic stockpiling of high-performance elastomer compounds and semiconductor controller chipsets dominates inventory strategy as foundry allocation volatility exposes modular subsystem suppliers to input disruption. Supply concentrates in Germany for precision automation subsystems, Japan for compact valve technology, and China for high-volume actuator fabrication. Raw material dependencies center on specialized sealing compounds, rare-earth magnetic materials for solenoid cores, and silicon wafers for valve controller fabrication. Single-source vulnerability in captive semiconductor fabrication capacity among integrated manufacturers creates supply chain risk. Distribution runs through direct manufacturer-to-plant digital service platforms that displace traditional Midwest and Ruhr region distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation tightening leakage mandates constitutes a high-growth disruption, compelling compressed air infrastructure upgrades that generate replacement demand across European manufacturing corridors while elevating compliance costs for legacy system operators.
For Market Incumbents: Secure backward integration into high-performance elastomer sealing compounds to defend margin positions against modular subsystem assemblers exposed to raw material volatility. Capture embedded IoT diagnostic capabilities through firmware-locked predictive maintenance subscriptions that preempt field failures in automotive customer plants and create recurring revenue streams insulated from commodity hardware pricing pressure.
For New Entrants and Emerging Players: Cybersecurity retrofit demand for networked pneumatic controllers exposes a service-layer gap where industrial-focused incumbents under-serve factory digitization requirements. Target medical device manufacturing in Ireland and Switzerland with REACH and RoHS-compliant valve configurations that sterile processing equipment OEMs struggle to source from pre-validated supplier portfolios. Pursue direct digital service platform partnerships with electronics contract manufacturers around Shenzhen to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by accelerating replacement cycles for legacy valve networks and consolidating procurement toward subsystem integrators with compliance-ready product portfolios. Long-term viability over the projection horizon favors precision automation specialists with embedded diagnostic capabilities and diversified industrial conglomerates with captive semiconductor fabrication. Watch for cybersecurity mandate convergence as the signal indicating inflection toward aftermarket security retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Compounds | Parker Hannifin Corporation's in-house elastomer production anchors margin defense against commodity pricing pressure. |
| Firmware-Locked Diagnostic Subscriptions | Festo SE & Co. KG extracts recurring revenue from automotive OEMs through predictive maintenance capabilities. |
| Direct Digital Service Platform Launch | Manufacturer-to-plant channels disrupt Midwest distributor networks and capture à-la-carte diagnostic demand. |
| Medical Device Compliance Qualification | Pre-validated REACH and RoHS portfolios consolidate supplier relationships with Swiss and Irish sterile equipment manufacturers. |
| Cybersecurity Retrofit Capability Buildout | Factory digitization exposes isolated pneumatic controllers to remote access vulnerabilities, creating aftermarket security demand. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this electro-pneumatic systems analysis. Conversations with plant engineers at automotive assembly facilities, procurement leads at electronics contract manufacturers, maintenance directors in food processing operations, and aftermarket service heads at distributor networks combined with bottom-up triangulation against customs data, SEC 10-K disclosures, and EU F-Gas Regulation compliance databases. Top-down validation incorporated ISO 4414 certification records and OSHA compressed air safety inspection reports.
Sensitivity analysis across the projection horizon tests demand elasticity to electric servo substitution thresholds and semiconductor input cost volatility. Segmentation dimensions modeled include product type tier, end-use industry concentration, technology maturity stage, and regional regulatory cluster intensity. CAGRs derive from installed base replacement dynamics and new automation deployment trajectories. Industry-specific forecast inputs incorporate MIIT industrial digitization directive implementation pace and METI factory automation incentive uptake rates.
Forecasts assume regulatory continuity in EU F-Gas leakage mandates, OSHA compressed air safety enforcement, and REACH chemical compliance regimes; material policy shifts would require re-modeling infrastructure upgrade timelines and material qualification cycles. Semiconductor foundry allocation disruptions, cybersecurity mandate acceleration, or electric servo cost parity breakthroughs present specific revision triggers. Revision becomes warranted when electric servo penetration in sub-4 bar applications crosses critical substitution thresholds in automotive or electronics manufacturing segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Micro Motor Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Global Cryostat Market