
 Equipment Cases Market | 2026-2036
Equipment Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Equipment Cases Market Foresight
China is reconfiguring equipment case manufacturing capacity through expanded injection molding corridors in Guangdong and Zhejiang provinces. SKB Cases leverages thermoforming expertise to dominate North American music and broadcast segments. MSA Case anchors military and first-responder channels with rotomolded durability standards. Plastic Forming Company sustains medical case leadership through ISO 13485-certified cleanroom production lines.
Equipment cases are engineered enclosures designed to protect sensitive instruments from impact, moisture, dust, and thermal shock during transit and field deployment, typically fabricated through injection molding, rotomolding, or thermoforming processes with IP ratings from IP54 to IP67. Hard cases command the largest revenue pool due to their penetration in medical device logistics and military supply chains, while custom cases capture expanding margin pools as OEMs specify foam-in-place interiors for precision instruments. Waterproof cases represent the fastest-growing product type, driven by underwater photography and marine electronics applications where salt corrosion resistance determines product lifespan.
FDA 21 CFR Part 820 quality system regulations shape medical equipment case requirements through validation protocols for sterile barrier maintenance, while REACH restricts phthalate-based plasticizers in European-sold cases and RoHS limits hazardous substances in electronics-transport applications. Stakeholders must monitor evolving battery transport regulations from IATA and DOT, as lithium-ion powered equipment reshapes case interior architecture and fire suppression specifications.
Market Dynamics
REACH compliance and the EU Green Deal are compressing polymer formulation cycles while simultaneously elevating recycled-content specifications across European supply chains. This regulatory pressure is forcing simultaneous retooling of material sourcing and manufacturing footprints.
Growth Catalysts
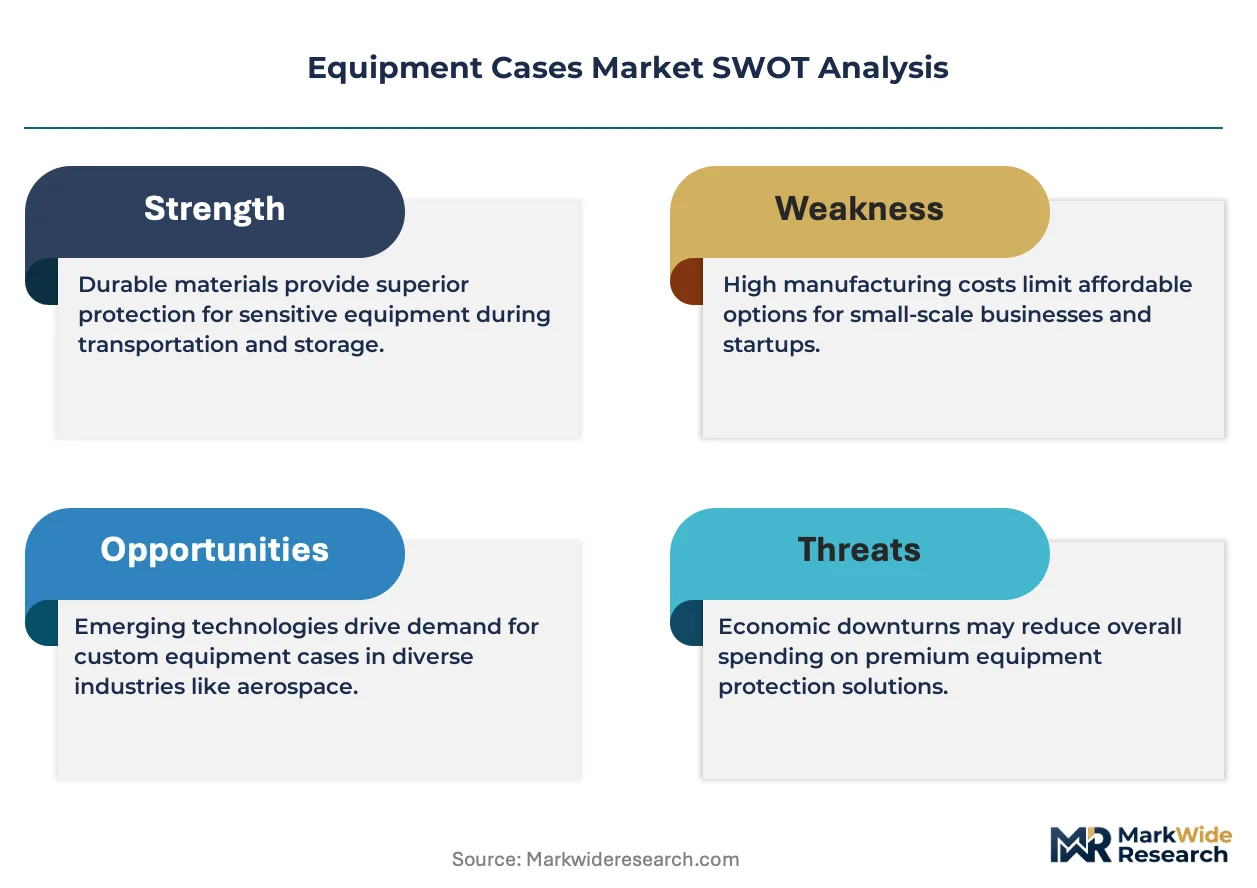
- Medical device logistics:FDA 21 CFR Part 820 validation protocols for sterile barrier maintenance are mandating purpose-built case architectures in North American healthcare distribution.
- REACH:Phthalate-based plasticizer restrictions are accelerating bio-based polymer adoption in European-sold equipment cases, creating first-mover advantages for compliant suppliers.
- Guangdong injection molding corridors:Expanded thermoplastic processing capacity is reducing lead times for custom foam-in-place interiors serving precision instrument OEMs.
Market Restraints
- Polypropylene price volatility:Feedstock cost swings tied to naphtha cracking economics compress margin stability for rotomolded case producers.
- IATA battery transport rules:Evolving lithium-ion fire suppression specifications force continuous interior architecture redesigns, extending product development timelines.
- Aluminum extrusion substitution:Metal cases retain share in military aerospace applications where electromagnetic shielding requirements exceed polymer capabilities.
Strategic Opportunities
- Underwater photography:Salt corrosion-resistant waterproof cases for marine electronics represent an expanding white space as recreational diving participation rebounds.
- EU Green Deal:Circular economy mandates for recycled content create procurement preference windows for cases meeting 30%+ post-consumer polymer thresholds.
- Direct-to-OEM digital channels:Configurator-based customization platforms are compressing distributor markups in broadcast and music equipment segments.
Industry Challenges
- ISO 13485 cleanroom certification:Medical case production requires validated particulate-controlled environments, constraining capacity expansion for mid-tier manufacturers.
- Multi-standard compliance:Simultaneous FDA, REACH, and RoHS adherence creates documentation burdens that extend commercialization timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equipment Cases Market |
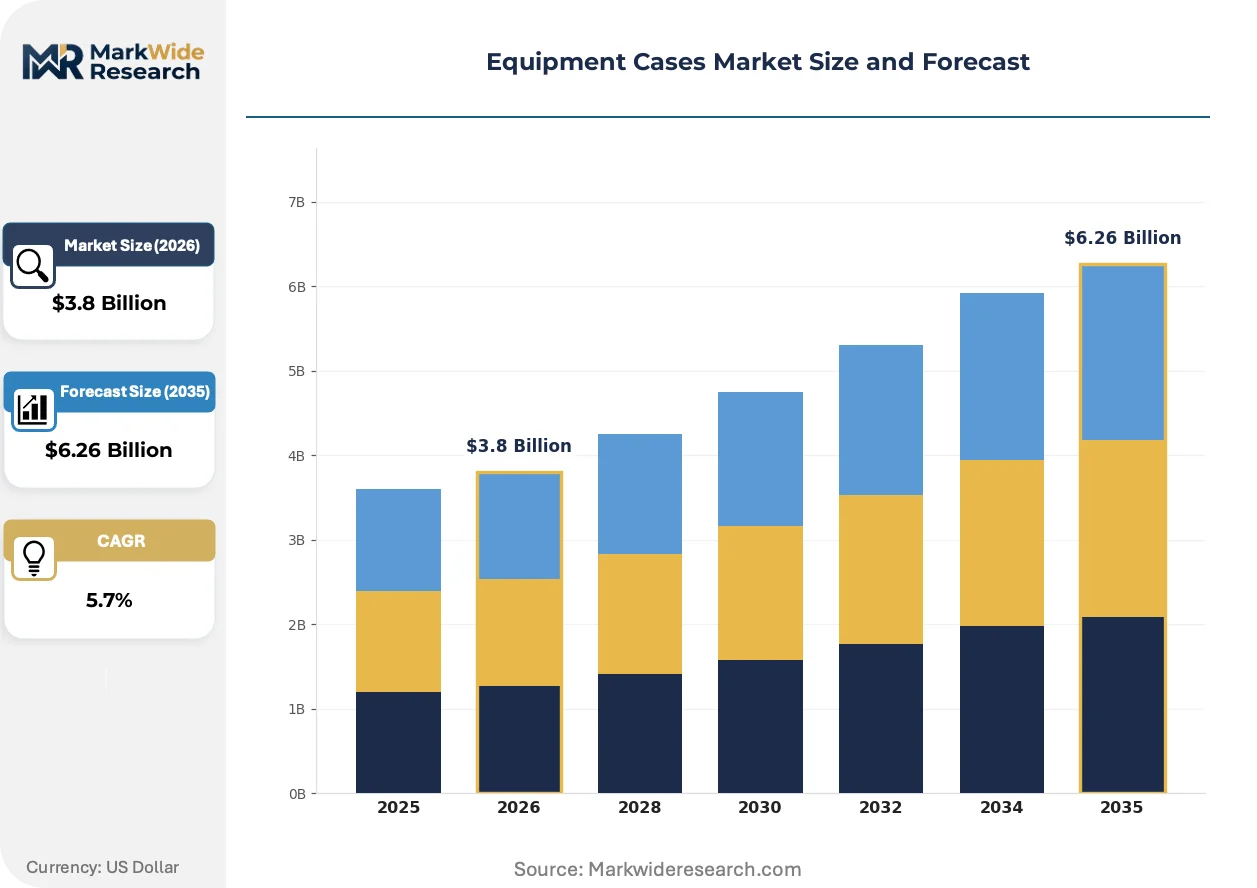
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Cases, Soft Cases, Custom Cases, Waterproof Cases Material: Plastic, Aluminum, Wood, Fabric Application: Photography, Medical Equipment, Musical Instruments, Electronics End User: Professionals, Hobbyists, Industrial Users, Retailers |
| Companies Covered | USA Case, HQC, SKB Cases, MSA Case, Sun Case, Plastic Forming Company, Lucky Case, Zero Case, Waterproof Case Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equipment Cases Market Shifts & Advancements
Material science convergence and regulatory stringency are compressing traditional manufacturing-process boundaries. Equipment case producers now face simultaneous pressure to lighten weight, elevate recycled content, and harden protective ratings.
Thermoplastic composite reinforcement is hybridizing traditional injection molding with continuous fiber integration, yielding shell structures that match aluminum stiffness at 40% lower mass. Medical device OEMs in Germany and Switzerland are piloting these hybrid cases for portable diagnostic equipment. The technology is hybridizing competitive positioning between metal and polymer case suppliers, forcing aluminum producers downstream into composite development partnerships.
RoHS hazardous substance limits are tightening electronics-transport case specifications across EU member states, with Denmark and the Netherlands enforcing stricter downstream due diligence than baseline requirements. Case manufacturers serving consumer electronics must now document full material declarations through three-tier supply chains. Medical and industrial instrumentation segments are responding by consolidating supplier bases to reduce compliance verification overhead.
Specification-led procurement is replacing catalog-based buying in enterprise accounts, with aerospace and defense contractors mandating bespoke foam-in-place interiors matched to exact equipment footprints. Traditional distributor networks in North America are losing share to direct engineering engagement models. This shift is most visible in California and Texas, where technology and energy sector procurement teams have eliminated case specification from MRO category management.
Equipment Cases Market Segmentation
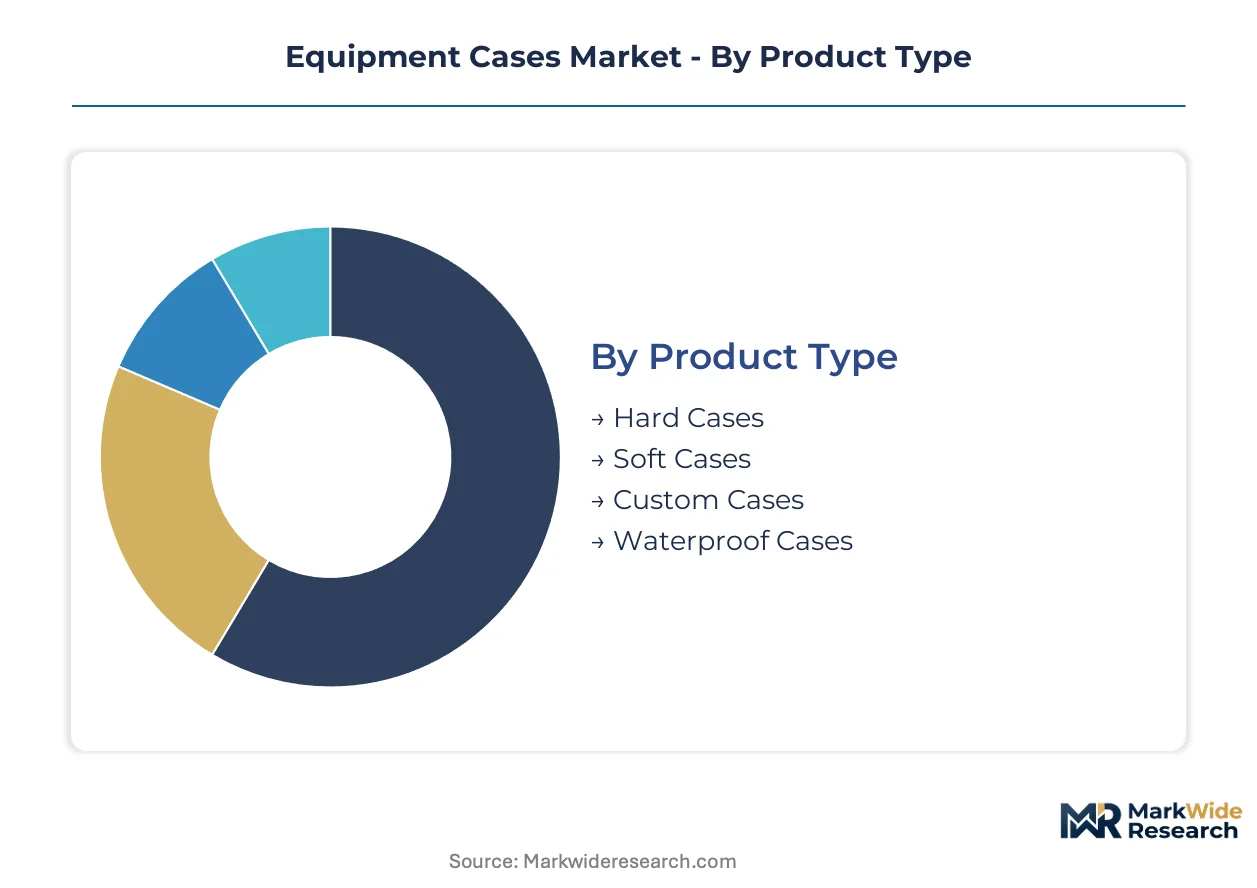
Equipment case manufacturers configure product portfolios across four intersecting dimensions. Each segmentation axis reflects distinct performance requirements, cost thresholds, and regulatory exposure that reshape competitive positioning.
Product Type:
Use-case spectrum spans from standardized transport protection to mission-critical environmental sealing.
- Hard Cases:Injection-molded polypropylene or ABS shells with foam-in-place interiors dominate medical device logistics and military supply chains. German precision engineering clusters anchor premium production for industrial instrumentation where impact resistance specifications exceed 150kg static load.
- Waterproof Cases:IP67-rated enclosures with O-ring seals and pressure equalization valves protect marine electronics and underwater photography equipment. Salt corrosion resistance determines product lifespan in recreational diving applications across Mediterranean and Caribbean coastal markets.
- Soft Cases:Padded fabric or foam constructions prioritize weight reduction for consumer electronics and basic tool transport where drop protection requirements remain moderate.
- Custom Cases:Bespoke foam-in-place interiors matched to exact equipment footprints command expanding margin pools as aerospace and defense contractors eliminate catalog-based procurement.
The dominant share belongs to hard cases, while waterproof cases are closing the gap fastest.
Material:
Cost tier stratification separates commodity feedstocks from performance-engineered substrates.
- Plastic:Polypropylene and ABS dominate through rotomolding, thermoforming, and injection molding processes. REACH phthalate restrictions and EU Green Deal recycled-content mandates are accelerating bio-based polymer adoption in European-sold cases.
- Aluminum:Extruded and fabricated metal shells retain share in military aerospace applications where electromagnetic shielding requirements exceed polymer capabilities. Swiss and German producers lead precision fabrication for portable diagnostic equipment.
- Wood:Traditional material persists in musical instrument protection where aesthetic presentation and humidity buffering properties outweigh weight penalties.
- Fabric:Nylon and polyester composites serve soft case construction with laminated waterproof membranes for consumer-grade electronics protection.
Plastic formulations command volume leadership, though aluminum maintains pricing premiums in aerospace-qualified applications.
Application:
Customer type diversity spans regulated healthcare channels to discretionary consumer segments.
- Medical Equipment:FDA 21 CFR Part 820 validation protocols for sterile barrier maintenance mandate purpose-built case architectures in North American healthcare distribution. ISO 13485 cleanroom certification constrains supplier qualification.
- Electronics:RoHS hazardous substance limits and IATA lithium-ion battery transport rules force continuous interior architecture redesigns for consumer and industrial device protection.
- Photography:Professional and amateur imaging equipment demands precision-fit foam systems with moisture control for sensor and lens protection in field deployment.
- Musical Instruments:Temperature stability and shock absorption specifications vary across orchestral, studio, and touring performance contexts.
Medical equipment applications anchor value concentration, with electronics protection expanding most quickly on battery-powered device proliferation.
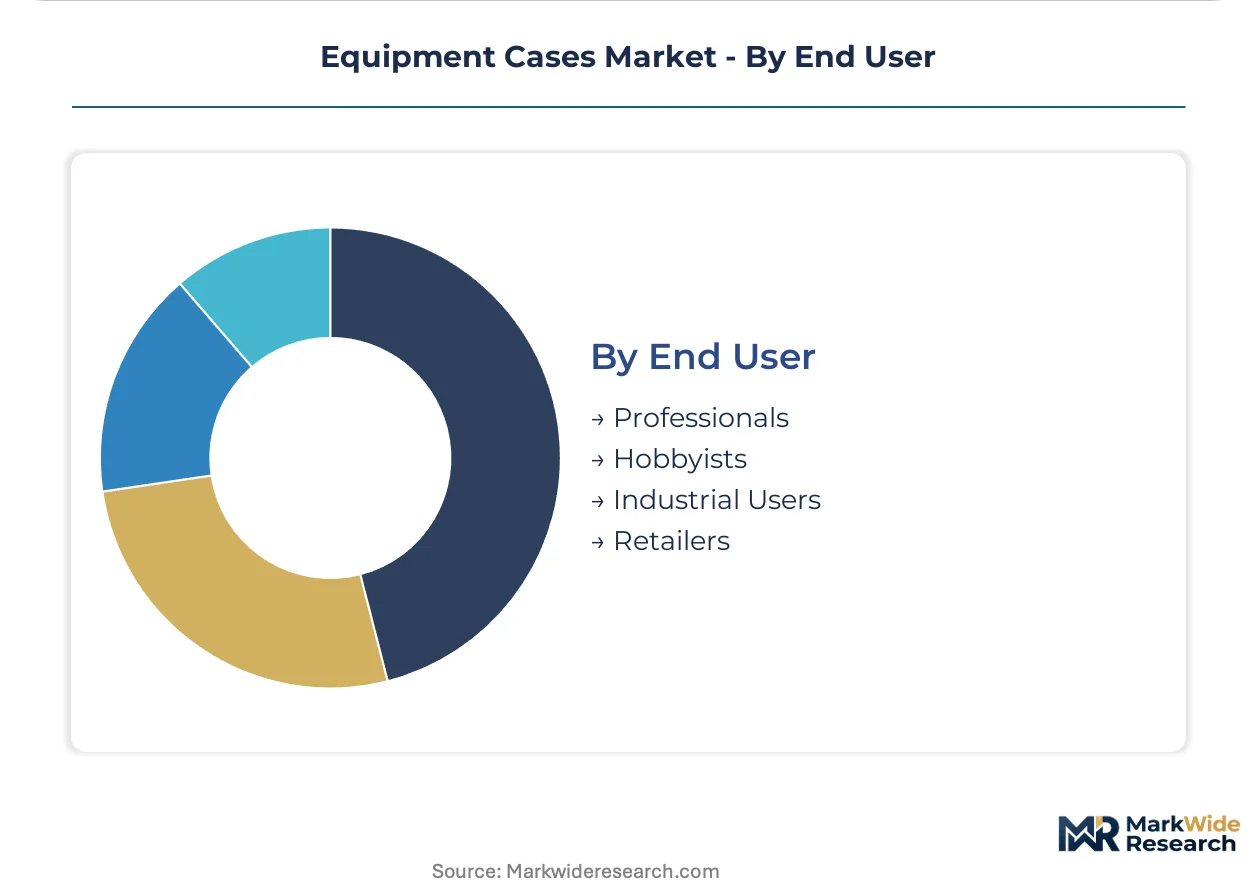
End User:
Procurement sophistication separates enterprise specification-led buying from price-sensitive retail channels.
- Professionals:Broadcast, medical, and military users mandate certified protective ratings with documented test protocols and extended warranty terms.
- Industrial Users:Energy and manufacturing sector procurement teams specify cases for instrumentation calibration equipment and field service tools.
- Hobbyists:Recreational diving, amateur photography, and home music production drive waterproof and soft case demand through direct-to-consumer digital channels.
- Retailers:Distributor and big-box electronics channels move standardized SKUs with compressed margins and high inventory velocity requirements.
Professional and industrial segments concentrate margin capture, while hobbyist channels are gaining share fastest through configurator-based customization platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment case manufacturing clusters in Germany, China, and the United States, with precision engineering hubs anchoring premium production and injection molding corridors serving volume markets. Regulatory divergence across FDA, REACH, and GB standards shapes regional product specifications. Medical device logistics and military procurement concentrate demand in specific metropolitan zones.
United States
Medical device logistics drives case demand through FDA 21 CFR Part 820 validation protocols for sterile barrier maintenance. California and Texas procurement teams have eliminated case specification from MRO category management, favoring direct engineering engagement. SKB Cases leverages thermoforming expertise to dominate music and broadcast segments from Southern California.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg anchor premium case production for industrial instrumentation where impact resistance specifications exceed 150kg static load. REACH phthalate restrictions accelerate bio-based polymer adoption in European-sold equipment cases. Stuttgart-based fabricators supply portable diagnostic equipment cases to Swiss and German medical OEMs.
China
Expanded injection molding corridors in Guangdong and Zhejiang provinces reconfigure manufacturing capacity for custom foam-in-place interiors. NMPA medical device regulations and dual carbon goals pressure polymer formulation shifts toward recycled content. Shenzhen and Dongguan thermoplastic processing clusters reduce lead times for precision instrument OEMs.
Switzerland
Swissmedic medical device standards and precision manufacturing heritage sustain demand for certified protective cases in pharmaceutical and diagnostic equipment. Geneva and Basel industrial zones host fabricators specializing in aluminum-composite hybrid enclosures for electromagnetic shielding applications. Swiss producers lead composite development partnerships with German polymer suppliers.
Japan
METI industrial standards and PMDA medical device regulations shape case specifications for domestic electronics and healthcare equipment manufacturers. Osaka and Nagoya manufacturing belts concentrate precision molding capacity for consumer electronics protection. Japanese procurement teams specify cases with documented test protocols for professional broadcast and medical applications.
Equipment Cases Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and process technology. The vendor base separates into three tiers: multinational case platforms with direct OEM channels, regional fabricators serving distributor networks, and specialized producers certified for medical or military applications. Competitive moves center on capacity expansion in Asian injection molding corridors and strategic partnerships for thermoplastic composite development.
Among US-based fabricators, SKB Cases and MSA Case exemplify divergent specialization archetypes. SKB Cases occupies a position within the music and broadcast segment tier, while MSA Case anchors military and first-responder channels with rotomolded durability standards. Plastic Forming Company represents the medical-certified archetype through ISO 13485 cleanroom production positioning.
| Leading Market Players |
|---|
| USA Case |
| HQC |
| SKB Cases |
| MSA Case |
| Sun Case |
| Plastic Forming Company |
| Lucky Case |
| Zero Case |
| Waterproof Case Company |
| Others |
Supply & Pricing Matrix
Guangdong injection molding corridors concentrate thermoplastic processing capacity, anchoring cost-competitive supply for mid-tier case producers while FDA-validated cleanroom fabrication in Germany and California commands premium pricing tiers. This geographic bifurcation creates divergent margin pools: commodity rotomolded shells compete on feedstock efficiency, while certified medical-grade enclosures extract value through sterile barrier compliance.
Pricing Analysis
FDA 21 CFR Part 820 dictates the pricing tier structure across North American medical equipment case procurement. Three-tier pricing separates ISO 13485-certified cleanroom production from standard industrial fabrication and commodity rotomolded alternatives. Certification level and customization depth drive price differentiation, with foam-in-place interiors matched to exact equipment footprints commanding substantial premiums. Cost compression in commodity polypropylene cases is intensifying because naphtha feedstock volatility erodes producer margins. Retail hobbyist channels exhibit highest price sensitivity, while aerospace and defense contractors prioritize specification compliance over unit cost.
Supply Chain Analysis
Polypropylene resin and ABS feedstock draw from petrochemical complexes in China, South Korea, and the United States. Case shell production hinges on injection molding tooling sourced from precision fabricators in Germany and Japan, with foam-in-place interior systems anchored in Guangdong and Zhejiang processing clusters. Single-source vulnerability concentrates in medical-grade polymer formulations qualified under REACH and FDA protocols. Distribution runs through direct OEM engineering engagement for enterprise accounts, while standardized SKUs move through distributor and big-box retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment case manufacturing sits at an inflection point where EU Green Deal recycled-content mandates and IATA lithium-ion fire suppression rules simultaneously reshape material science and interior architecture requirements. This regulatory-technological convergence creates asymmetric opportunities across incumbent defense, new entrant positioning, and capital deployment.
For Market Incumbents: Insulate market position by securing captive supply of bio-based polymers ahead of REACH phthalate restriction deadlines, and accelerate ISO 13485 cleanroom capacity expansion in Bavaria or Baden-Württemberg clusters to capture medical OEM consolidation. Aluminum-composite hybrid R&D partnerships with Swiss fabricators defend against electromagnetic shielding substitution threats in aerospace applications. For New Entrants and Emerging Players: Build out salt corrosion-resistant waterproof case production for Mediterranean and Caribbean recreational diving markets, where IP67-rated marine electronics protection remains underpenetrated by established suppliers. Direct-to-consumer configurator platforms targeting amateur photography and home music production segments offer lowest customer acquisition friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermoforming specialists in Southern California and rotomolded military suppliers with aging owner-operators. Five-to-ten year viability favors platforms with demonstrated FDA validation protocol expertise and established OEM direct channels. Monitor NMPA medical device regulation harmonization progress as signal for Chinese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polymer Formulation Investment | EU Green Deal 30% post-consumer thresholds create procurement preference windows for compliant suppliers. |
| ISO 13485 Cleanroom Certification | FDA sterile barrier requirements constrain qualified capacity, elevating margins for certified producers. |
| Direct-to-OEM Digital Channel Buildout | Configurator platforms compress distributor markups in broadcast and music equipment segments. |
| Thermoplastic Composite R&D Partnership | Hybrid fiber-reinforced shells match aluminum stiffness at reduced mass for portable diagnostic equipment. |
| Underwater Photography Case Line Extension | Recreational diving participation rebounds drive fastest-growing waterproof segment demand. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and aftermarket service heads provided ongoing calibration throughout the study period. Primary interviews with case manufacturer plant managers, OEM procurement leads, and distribution channel partners were cross-referenced against customs and trade data, SEC 10-K filings, and hospital procurement databases. Bottom-up segment sizing and top-down macro anchoring were reconciled through iterative triangulation.
Scenario bracketing around regulatory implementation timelines and feedstock price bands shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type hardness rating, material formulation tier, application regulatory intensity, and end-user procurement sophistication. CAGRs were derived from installed base growth rates and replacement cycle analysis, with lithium-ion battery proliferation and medical device logistics automation as primary demand drivers.
Stress conditions across polypropylene price volatility, REACH enforcement intensity, and IATA rule revision frequency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and polymer recycling technology maturation. Cross-checking against ECHA substance restriction announcements and NMPA medical device registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
CO2 Laser Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market