
 Digital Servo Press Market | 2026-2036
Digital Servo Press Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Servo Press Market Analysis
Automotive manufacturing is consolidating its position as the dominant application for digital servo presses, displacing traditional mechanical presses in EV battery tray and motor core stamping operations. Schuler Group leverages its deep ties to German OEMs to sustain leadership in large-tonnage systems. AIDA Engineering Ltd. anchors its competitive position through specialized mid-range presses for Asian tier-1 suppliers. Promess Incorporated differentiates via compact, precision benchtop units serving medical device and electronics contract manufacturers.
A digital servo press is an electromechanically driven forming machine that uses a servomotor coupled to a ball screw or crank mechanism to deliver programmable force, position, and velocity control with accuracy typically within microns. The electromechanical technology segment leads unit shipments due to superior energy efficiency and programmable motion profiles that reduce die wear. Hydraulic systems retain dominance in heavy-gauge metal forming above 1,000 kN where sustained pressure is critical. The automatic operation mode category captures the fastest growth as manufacturers integrate servo presses into Industry 4.0 lines with real-time quality feedback loops.
The EU Machinery Directive and CE marking requirements enforce safety interlocks and functional safety standards that elevate engineering costs for market entry. ISO 10218 robotics integration standards and OSHA machine guarding rules in the United States shape how OEMs configure peripheral automation around press cells. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and regional content rules for batteries and electric drivetrains redirect capital equipment procurement toward localized, certifiable press installations.
Market Dynamics
Automotive electrification is compressing the replacement cycle for traditional mechanical presses as OEMs retool stamping lines for EV battery trays and motor laminations requiring micron-level precision.
Growth Catalysts
- EU Ecodesign Directive:Tightening energy-efficiency benchmarks for industrial machinery are accelerating replacement of hydraulic systems with electromechanical servo presses across German and Italian metalworking clusters.
- EV battery tray stamping:OEM demand for precision joining in aluminum-intensive battery enclosures is pulling high-tonnage servo press installations into dedicated EV production lines.
- Ball screw advancement:Improved screw mechanisms now sustain sustained pressure profiles previously exclusive to hydraulics, expanding electromechanical addressable tonnage ranges.
Market Restraints
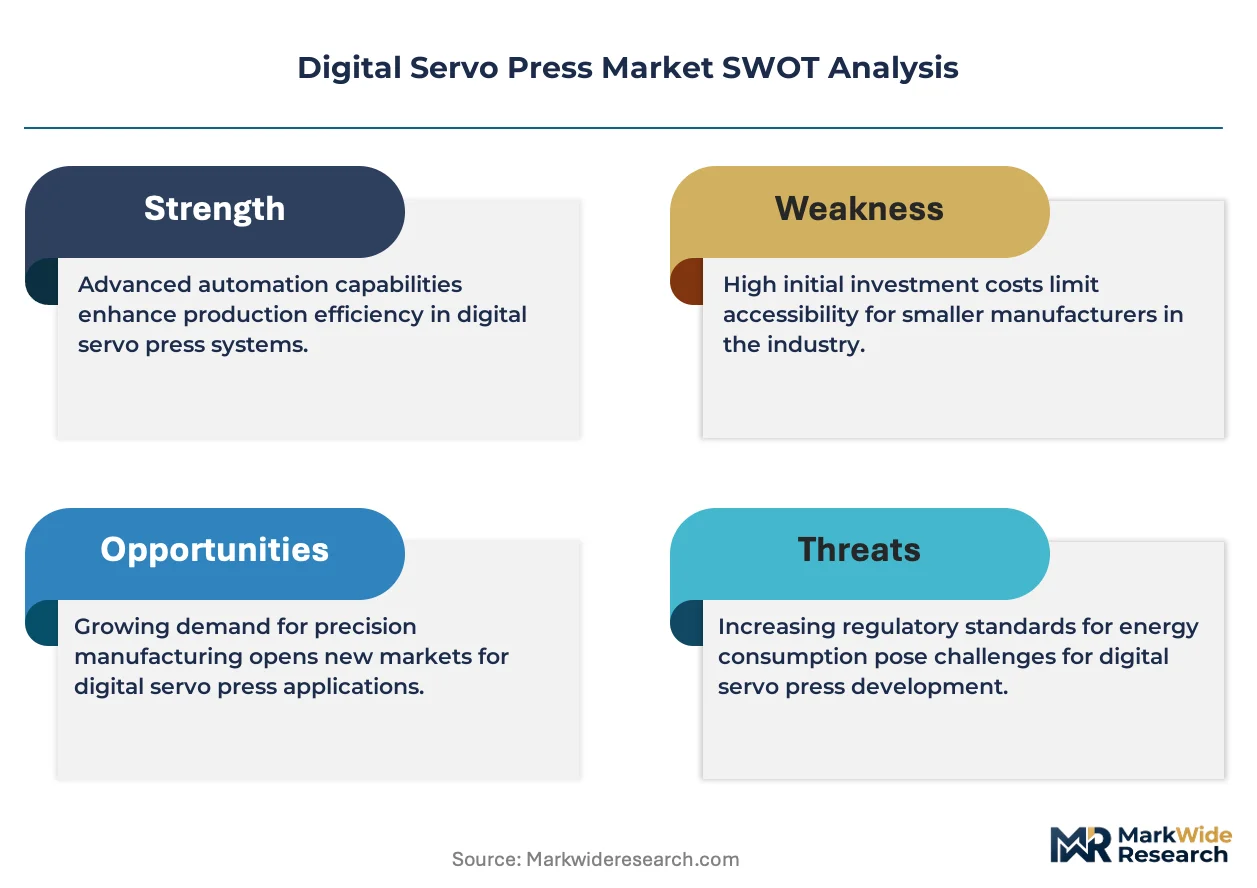
- Rare earth magnet supply concentration:Servomotor production depends on neodymium supply chains concentrated in Chinese processing facilities, creating input cost volatility and geopolitical exposure.
- CE marking compliance costs:EU Machinery Directive safety interlock requirements elevate engineering validation expenses, particularly for mid-tier suppliers lacking dedicated certification teams.
- Hydraulic legacy entrenchment:Heavy-gauge forming above 1,000 kN retains hydraulic dominance due to sustained pressure requirements that electromechanical systems struggle to match economically.
Strategic Opportunities
- Medical device miniaturization:Precision benchtop servo press demand from contract manufacturers serving orthopedic implant and catheter assembly is outpacing general industrial growth rates.
- India PLI scheme:Production-linked incentives for automotive and electronics manufacturing are redirecting capital equipment procurement toward localized, certifiable press installations in Pune and Chennai corridors.
- Digital twin integration:Convergence of servo press motion control with real-time simulation software is enabling predictive die wear modeling and remote commissioning services.
Industry Challenges
- Mechatronics skill scarcity:Servo press maintenance requires blended mechanical-electrical-software competencies that vocational training systems in mature manufacturing economies have not scaled to match deployment rates.
- ISO 10218 integration complexity:Robotics integration standards create validation bottlenecks when retrofitting legacy press cells with automated feeding and quality inspection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Servo Press Market |
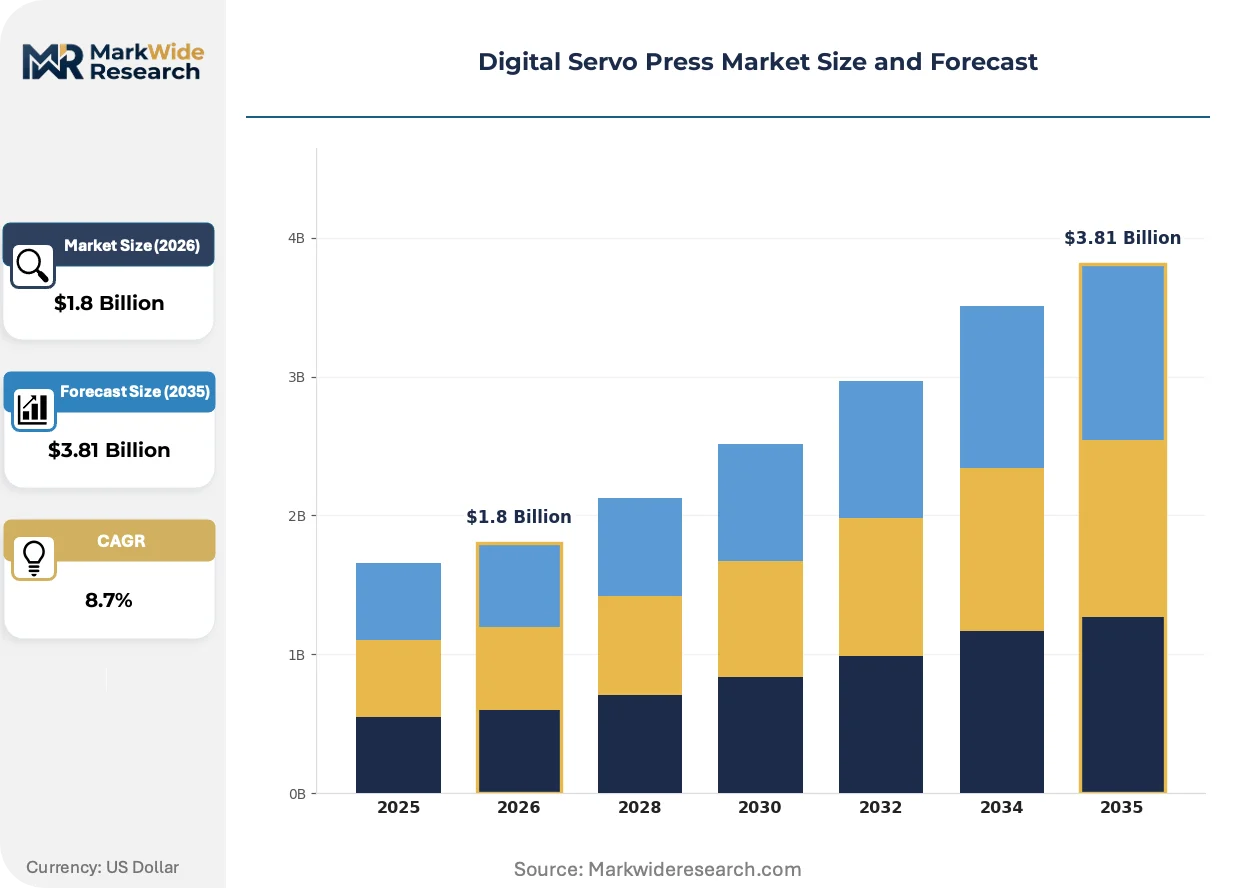
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electromechanical, Hydraulic, Pneumatic, Mechanical Application: Automotive Manufacturing, Aerospace Assembly, Electronics Production, Medical Device Fabrication End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, R&D Institutions Operation Mode: Manual, Semi-Automatic, Automatic, Remote-Controlled |
| Companies Covered | AMADA PRESS SYSTEM CO. LTD., Promess Incorporated, Schuler Group, Mitsubishi Heavy Industries, TOX PRESSOTECHNIK, AIDA Engineering Ltd., Janome Corporation, Stamtec Inc., Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Servo Press Market Emerging Trajectories
Real-time quality feedback loops and programmable motion profiles are transforming servo presses from standalone forming equipment into integrated nodes within Industry 4.0 production architectures.
Advanced torque ripple compensation algorithms are converging with high-resolution encoder feedback to deliver sub-micron positional repeatability in motor core lamination stamping. Tier-1 automotive suppliers in Germany and Japan are adopting these systems for high-speed progressive die applications. The technology is converging with cloud-based process monitoring to enable predictive maintenance contracts that displace traditional break-fix service models.
REACH restrictions on hydraulic fluid formulations are elevating total cost of ownership for conventional press systems across European manufacturing operations. The regulation is forcing OEMs to accelerate electromechanical migration timelines in stamping operations previously deemed uneconomic for servo conversion. Battery tray manufacturers in Stuttgart and Wolfsburg corridors are responding with dedicated capital allocation for large-tonnage servo installations.
Buyers are unbundling after-sales service contracts from initial equipment purchases, pressuring OEM margins while opening specialized service provider entry points. Distributors in North American and Asian markets are repositioning as lifecycle solution aggregators rather than transaction intermediaries. This pattern is most pronounced among electronics contract manufacturers in South Korea and Taiwan seeking flexible maintenance arrangements for multi-vendor press fleets.
Digital Servo Press Market Segmentation
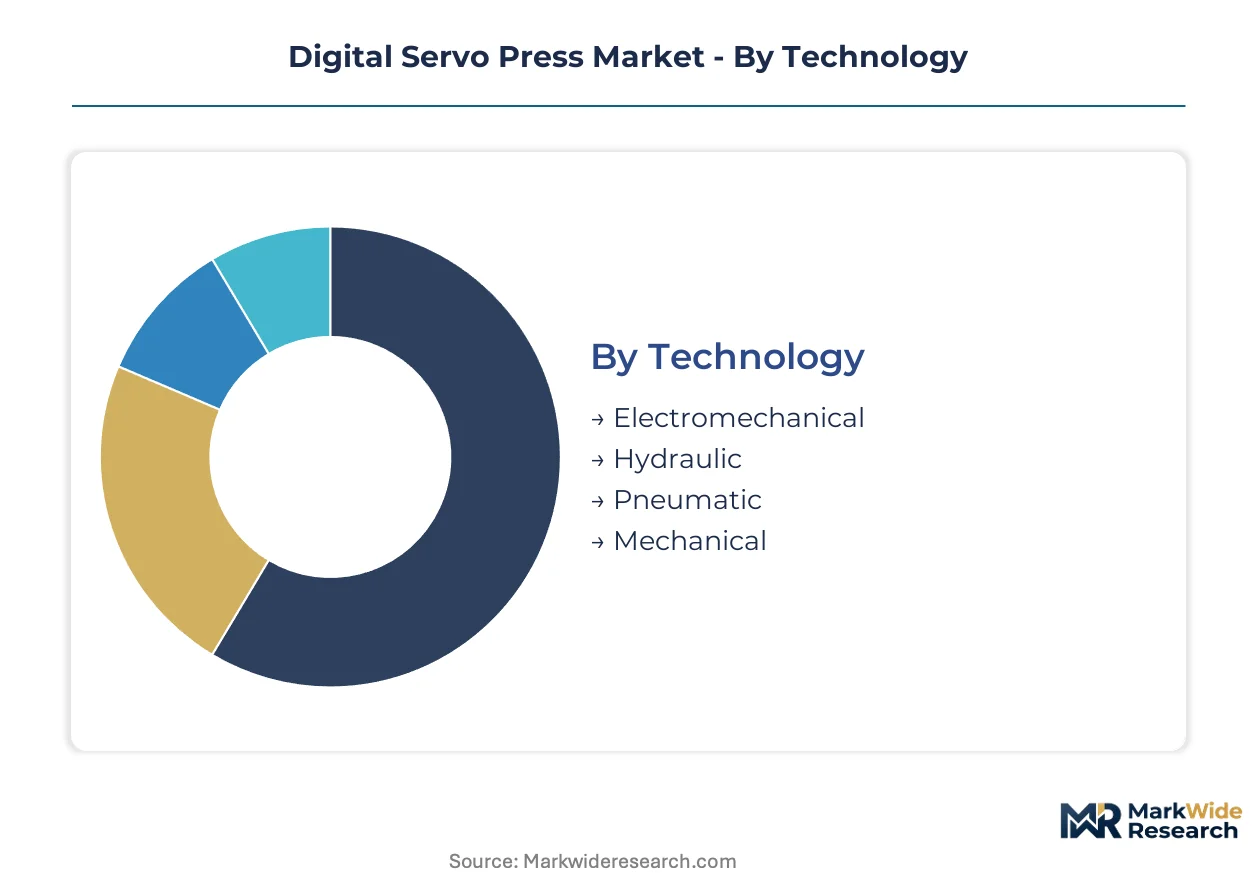
Digital servo press segmentation reveals how upgrade cycles concentrate capital allocation across incompatible technology stacks. Replacement decisions hinge on force-range requirements, precision tolerances, and integration depth with existing automation architectures.
Technology:
Replacement cycles accelerate where energy-efficiency regulations and precision demands converge, forcing trade-offs between legacy hydraulic infrastructure and electromechanical upgrade paths.
- Electromechanical:Servomotor-ball screw systems deliver programmable force-velocity-position profiles with sub-micron repeatability. Battery tray stamping operations in Germany's automotive belt favor these systems for aluminum-intensive EV enclosures where die wear reduction justifies capital outlay.
- Hydraulic:Sustained-pressure systems dominate heavy-gauge forming above 1,000 kN through oil-driven rams. REACH fluid restrictions in European operations are elevating maintenance costs and accelerating displacement timelines in operations previously deemed uneconomic for conversion.
- Pneumatic:Compressed-air drives occupy low-force assembly niches requiring rapid cycling without precision positioning.
- Mechanical:Crank-and-flywheel systems face compressed replacement cycles as OEMs retool for EV motor lamination tolerances.
Electromechanical systems sit at the top of the volume ranking, with electromechanical configurations climbing the fastest as ball screw advancements expand addressable tonnage ranges.
Application:
Cost-tier stratification separates capital-intensive automotive installations from benchtop units serving medical and electronics contract manufacturers.
- Automotive Manufacturing:High-tonnage progressive die stamping for EV battery trays and motor cores demands micron-level precision. Stuttgart and Wolfsburg corridors concentrate dedicated capital allocation for large-tonnage servo installations serving OEM electrification programs.
- Medical Device Fabrication:Compact benchtop units serve orthopedic implant and catheter assembly with force ranges below 100 kN. Contract manufacturers in precision-driven segments are outpacing general industrial growth rates for miniaturized joining operations.
- Aerospace Assembly:Titanium and composite forming requires specialized force profiles for airframe component production.
- Electronics Production:Connector and semiconductor packaging applications favor mid-range electromechanical systems with rapid cycle times.
Automotive Manufacturing commands the highest installed value, with Medical Device Fabrication gaining share fastest on precision miniaturization trends.
End User:
Customer-type fragmentation separates specification authority from procurement execution across multi-tier supply chains.
- OEMs:German automotive manufacturers specify large-tonnage systems for captive stamping operations, consolidating demand through direct vendor relationships with Schuler Group and comparable equipment builders.
- Tier-1 Suppliers:Asian component manufacturers anchor mid-range press demand through specialized configurations for motor lamination and structural battery components.
- Contract Manufacturers:Electronics and medical device assemblers favor flexible procurement arrangements for multi-vendor press fleets.
- R&D Institutions:Universities and national laboratories acquire specialized units for process development and materials characterization.
OEMs dominate capital commitment scale, with Contract Manufacturers expanding procurement fastest through unbundled service arrangements.
Operation Mode:
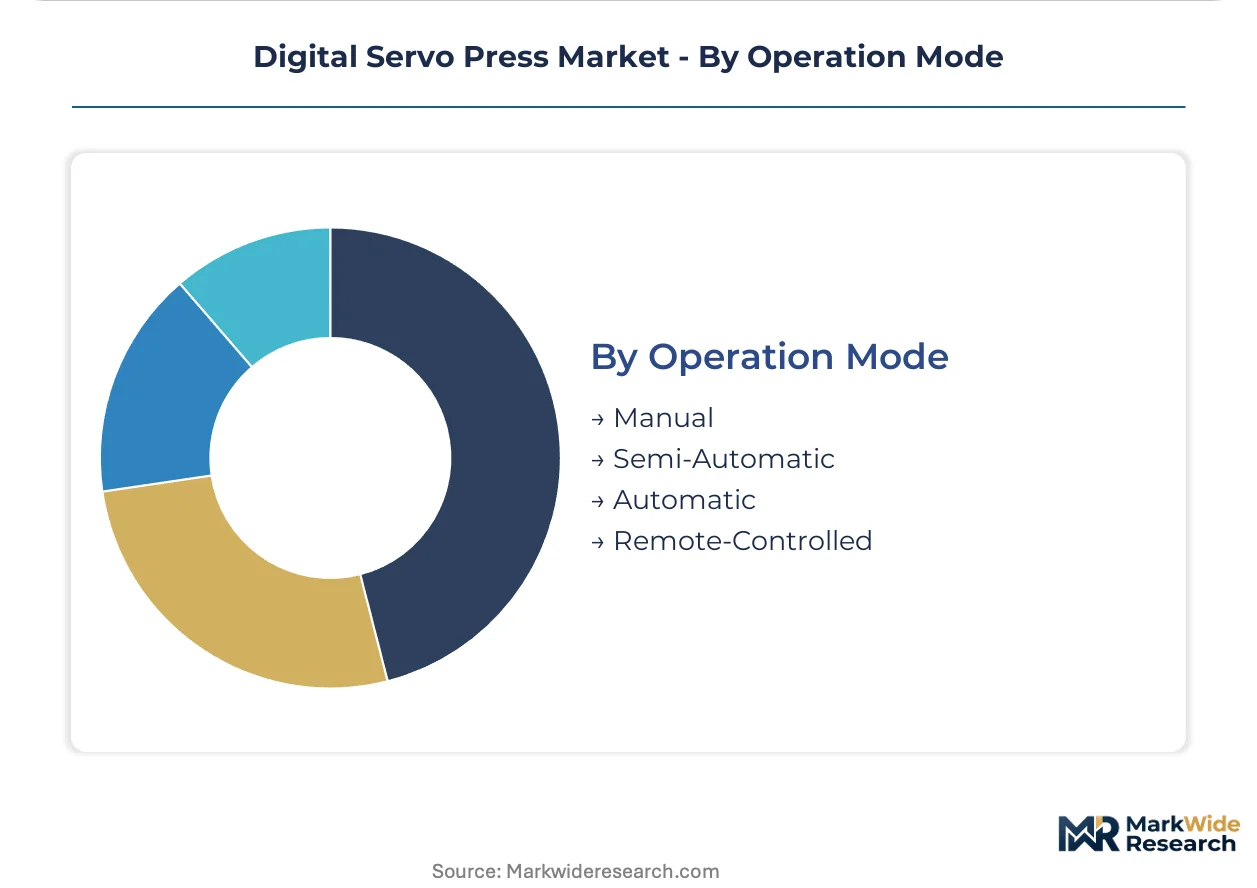
Integration depth with Industry 4.0 architectures determines mode selection, with manual and semi-automatic systems retreating to prototyping and low-volume niches.
- Automatic:Real-time quality feedback loops and predictive die wear modeling transform presses into integrated production nodes. Cloud-based process monitoring enables outcome-based maintenance contracts displacing break-fix service models.
- Remote-Controlled:Digital twin integration permits commissioning and diagnostics from off-site engineering centers, reducing travel-dependent service costs for distributed manufacturing footprints.
- Semi-Automatic:Operator-intervention systems persist in mixed-model lines requiring frequent die changeovers.
- Manual:Hand-actuated controls survive in R&D and prototype validation environments.
Automatic operation sits at the top of the volume ranking, with Remote-Controlled configurations climbing the fastest on digital twin convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing belt around Stuttgart and Wolfsburg concentrates the highest density of large-tonnage digital servo press installations. OEM electrification programs are retooling stamping lines for EV battery trays and motor laminations. Regulatory pressure from Brussels accelerates displacement of hydraulic systems across European metalworking clusters.
United States
EV battery manufacturing investments in Michigan and Ohio are pulling precision joining equipment into dedicated production lines. OSHA machine guarding rules shape how OEMs configure peripheral automation around press cells. The Southeast automotive corridor spanning Tennessee and South Carolina is seeing concentrated capital allocation for servo press installations serving transplant OEM operations.
Germany
The EU Ecodesign Directive and Machinery Directive tighten energy-efficiency benchmarks for industrial presses across Baden-Württemberg and Lower Saxony. CE marking requirements enforce safety interlocks that elevate engineering costs for market entry. Stuttgart and Wolfsburg corridors concentrate dedicated capital allocation for large-tonnage servo installations serving OEM electrification programs.
China
Dual carbon goals and MIIT industrial efficiency standards are accelerating electromechanical migration in Yangtze River Delta manufacturing zones. Rare earth magnet supply concentration creates input cost volatility for servomotor production dependent on domestic processing facilities. Shenzhen and Suzhou electronics clusters drive demand for mid-range electromechanical systems with rapid cycle times.
Japan
METI energy efficiency guidelines and JIS standards shape equipment procurement for automotive tier-1 suppliers in Aichi and Shizuoka prefectures. High-speed progressive die applications for motor core laminations demand sub-micron positional repeatability. Nagoya-area manufacturers anchor specialized mid-range press demand through configurations for structural battery components.
India
PLI scheme production-linked incentives for automotive and electronics manufacturing redirect capital equipment procurement toward localized installations. BIS certification requirements create validation bottlenecks for imported press systems. Pune and Chennai corridors concentrate contract manufacturer demand for flexible procurement arrangements serving multi-vendor press fleets.
Digital Servo Press Market Vendor Landscape
Portfolio diversification dominates the current landscape as equipment builders expand beyond traditional automotive stamping into medical device and electronics contract manufacturing. The vendor base separates into three tiers: large-tonnage system specialists serving OEM captive operations, mid-range fabricators supplying Asian tier-1 suppliers, and compact benchtop specialists targeting precision assembly niches. Consolidation pressure is mounting where energy-efficiency regulations accelerate replacement cycles. Technology licensing agreements and geographic expansion represent the dominant competitive moves as players seek access to India PLI scheme benefits and European Ecodesign compliance expertise.
Within the large-tonnage system tier, Schuler Group and AIDA Engineering Ltd. exemplify divergent geographic anchoring strategies. Schuler Group represents German-origin equipment builders with deep ties to Stuttgart and Wolfsburg OEM stamping operations. AIDA Engineering Ltd. occupies a position among Japanese-origin fabricators specializing in configurations for motor lamination and structural battery component production. Promess Incorporated sits within the compact precision tier, serving orthopedic implant and catheter assembly operations with force ranges below 100 kN.
| Leading Market Players |
|---|
| AMADA PRESS SYSTEM CO. LTD. |
| Promess Incorporated |
| Schuler Group |
| Mitsubishi Heavy Industries |
| TOX PRESSOTECHNIK |
| AIDA Engineering Ltd. |
| Janome Corporation |
| Stamtec Inc. |
| Komatsu Ltd. |
| Others |
Supply Flow & Price Mechanics
Large-tonnage electromechanical systems and compact benchtop units diverge across a certification and performance ladder that simultaneously stratifies pricing power and concentrates supply chain control among German and Japanese equipment builders serving automotive OEMs versus specialized precision fabricators.
Pricing Analysis
Neodymium magnet cost pass-through from Chinese processing facilities feeds directly into servomotor pricing, compressing margins for mid-tier electromechanical press suppliers lacking long-term rare earth supply agreements. Three-tier pricing structure across premium CE-certified installations, standard industrial configurations, and economy pneumatic alternatives reflects differentiation by precision grade and after-sales bundling. Pricing pressure stems from unbundled service contracts as buyers separate maintenance from initial equipment purchases. Contract manufacturers in electronics and medical device segments exhibit highest price sensitivity, while German automotive OEMs prioritize precision certification over unit cost.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are redirecting component sourcing toward Pune and Chennai corridor fabricators, reshaping traditional import-dependent procurement patterns. Servomotor production draws from Chinese rare earth processing, Japanese precision bearing manufacturing, and German control system engineering. Single-source vulnerability concentrates in neodymium supply chains tethered to Chinese separation and refining capacity. Distribution runs through authorized dealer networks with lifecycle service aggregation replacing transactional equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital servo press market compounds steadily as automotive electrification forces precision retooling across OEM stamping operations, creating durable replacement demand independent of cyclical capacity expansion.
For Market Incumbents: Deploy predictive maintenance software platforms to capture recurring revenue streams as buyers unbundle service contracts. Incumbent equipment builders should anchor backward integration into ball screw and encoder supply chains to offset rare earth cost volatility. Certification investment in CE marking and ISO 10218 robotics integration standards creates defensive moats against mid-tier Asian competitors lacking dedicated compliance teams. For New Entrants and Emerging Players: Enter via precision benchtop segments serving orthopedic implant and catheter assembly contract manufacturers, where incumbent coverage remains thin and price sensitivity permits competitive positioning. White-space concentration in Indian PLI scheme corridors around Pune and Chennai offers localized fabrication advantages for mid-range electromechanical systems. Go-to-market execution should leverage distributor repositioning as lifecycle solution aggregators rather than equipment-only channels. For Investors and Strategic Acquirers: Asymmetric upside sits with compact precision specialists possessing embedded software competencies and medical device regulatory pathways. Long-term viability favors acquisition targets with digital twin integration capabilities and outcome-based maintenance contract portfolios. Monitor carbon-border adjustment mechanism implementation as inflection signal for accelerated electromechanical conversion timelines in European metalworking clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ball Screw Manufacturing | Captive precision motion control supply reduces dependency on Japanese and German bearing specialists. |
| Digital Twin Platform Development | Remote commissioning and predictive die wear modeling displace travel-dependent service revenue models. |
| CE Marking and Machinery Directive Certification Investment | Regulatory compliance creates entry barriers protecting European automotive OEM relationships. |
| Medical Device Precision Benchtop Expansion | Orthopedic implant and catheter assembly demand outpaces general industrial growth rates. |
| India PLI Scheme Localized Production | Domestic fabrication qualifies automotive and electronics capital equipment for production-linked incentives. |
Methodological Framework
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs data and machinery trade associations, and technical specification analysis — were reconciled to construct segment-level demand estimates. Stakeholder consultations included maintenance directors at German automotive stamping operations, tier-1 supplier equipment planners in Japan, and contract manufacturing executives in South Korea and Taiwan. Secondary sources comprised EU Machinery Directive implementation reports, MIIT industrial efficiency disclosures, and SEC filings from listed equipment builders. Bottom-up unit demand modeling and top-down industrial capex allocation analysis were cross-validated for triangulation.
Data-stream reconciliation across technology segments, application verticals, and geographic production clusters informed analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include drive technology type, force range tier, operation mode integration depth, and end-user procurement authority. CAGRs were derived from replacement cycle compression analysis and regulatory-driven displacement timelines. Industry-specific forecast inputs incorporated EV battery tray stamping specifications and REACH hydraulic fluid restriction compliance costs.
Inputs from plant-level interviews and regulatory filing databases were available through the study window; gaps in real-time rare earth pricing transparency and unreported contract manufacturer procurement volumes introduce uncertainty bands around high-growth segment estimates. Forecasts reflect assumptions regarding PLI scheme continuation and carbon-border mechanism scope expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Electric Cartridge Heaters Market