
 Electric Cartridge Heaters Market | 2026-2036
Electric Cartridge Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Cartridge Heaters Market Insights
Buyer concentration in the plastics molding sector is consolidating as tier-one automotive suppliers merge their tooling procurement across fewer vendor relationships. Watlow leverages its vertical integration into sensor-integrated heater systems to anchor long-term contracts with medical device molders. Chromalox competes through geographic dominance in European chemical processing installations, while Tempco Electric Heater Corporation specializes in rapid-turn custom designs for North American packaging OEMs.
Electric cartridge heaters are cylindrical metal-sheathed heating elements, typically constructed from stainless steel housings with magnesium oxide insulation and nickel-chromium resistance wire cores, engineered to deliver localized heat up to 1400°F in precision industrial equipment. Their primary purpose centers on direct-contact heating in injection molds, extrusion dies, and semiconductor process chambers where uniform temperature distribution prevents material degradation. High watt density configurations command premium positioning due to severe duty cycles in aerospace component forming, while ceramic insulated technology leads durability metrics in corrosive chemical environments. Miniature cartridge heaters represent the fastest-growing product configuration as electronics assembly lines shrink tooling footprints.
ISO standards for industrial heating equipment, NEMA electrical enclosure classifications, and EU machinery directives under CE marking collectively shape product certification requirements and cross-border market access for heater manufacturers. OSHA electrical safety regulations in the United States and REACH substance restrictions in Europe further constrain material selections for insulation and sheath alloys. Stakeholders must monitor evolving semiconductor fabrication node transitions and corresponding thermal uniformity specifications that will redefine qualification thresholds for supplier inclusion.
Market Dynamics
Semiconductor fabrication node transitions below 3nm are compressing thermal uniformity tolerances to ±0.5°C, forcing heater manufacturers to redesign resistance wire geometries and sheath alloys for sub-10-second thermal response cycles.
Growth Catalysts
- EU machinery directives under CE marking:Tighter energy-efficiency mandates in Germany and Japan are accelerating replacement cycles for legacy heating systems in injection molding operations.
- High-watt-density configurations:Aerospace component forming applications command severe duty cycles that standard cartridge heaters cannot sustain, creating pull for advanced nickel-chromium core designs.
- Taiwan and South Korea:Semiconductor manufacturing fabs in these precision manufacturing clusters are expanding orders for localized heat delivery in process chambers.
Market Restraints
- Nickel price volatility:Resistance wire cores depend on nickel-chromium alloys, and London Metal Exchange price swings above 15% monthly compress margin buffers for mid-tier manufacturers.
- Magnesium oxide supply concentration:Electrical insulation material production clusters in Chinese industrial zones, creating single-source vulnerability for non-vertically integrated heater assemblers.
- REACH substance restrictions:European chemical registration requirements constrain sheath alloy selections and extend qualification timelines for new material formulations.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract assembly expansion in Noida and Sriperumbudur creates virgin demand for miniature cartridge heaters in shrunken tooling footprints.
- Sensor-integrated heater systems:Convergence of platinum resistance temperature detectors with cartridge heater housings enables closed-loop thermal control for medical device molders.
- ISO 9001:2015 quality management:Certification-driven supplier preference shifts in automotive tier-one procurement are favoring documented thermal uniformity traceability.
Industry Challenges
- Metallurgical engineering talent scarcity:Design of magnesium oxide compaction densities for 1400°F operation requires specialized expertise concentrated among retiring workforce cohorts in Midwest US manufacturing regions.
- OSHA electrical safety compliance:NEMA enclosure classification verification for wet-environment chemical processing installations extends certification timelines by 8-14 weeks.
- Legacy mold retrofits:Integration of high-watt-density units into existing tooling bore dimensions requires custom sheath machining that strains rapid-turn production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Cartridge Heaters Market |
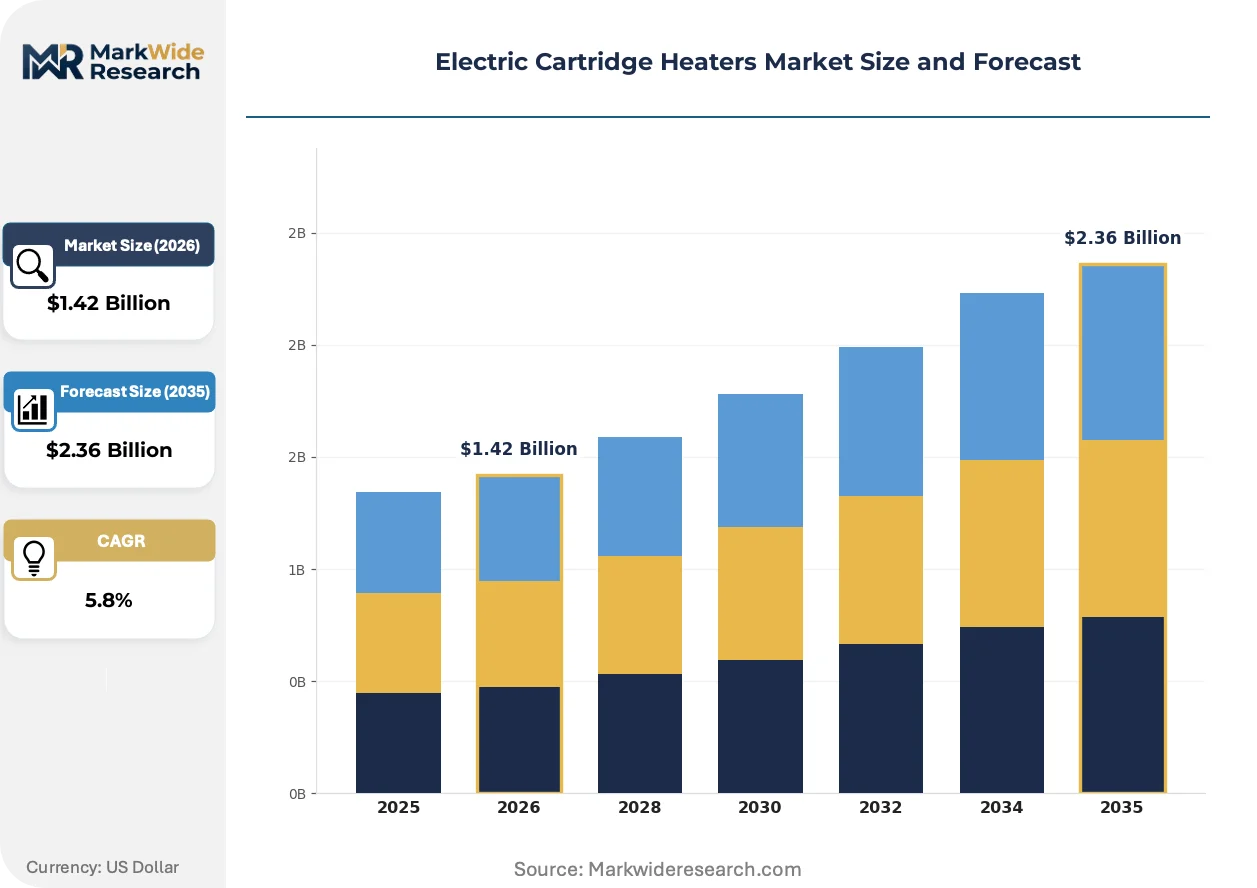
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cartridge Heaters, High Watt Density, Miniature Cartridge Heaters, Flexible Cartridge Heaters, Ceramic Cartridge Heaters Technology: Resistance Wire, Mica Insulated, Ceramic Insulated, Quartz Encapsulated, Silicone Rubber Coated Application: Packaging Equipment, Food Processing, Semiconductor Manufacturing, Plastics Molding, Laboratory Equipment End User Industry: Industrial Manufacturing, Electronics Assembly, Chemical Processing, Aerospace & Defense, Renewable Energy |
| Companies Covered | Watlow, Backer Hotwatt, Chromalox, Dalton Electric, Durex Industries, Tempco Electric Heater Corporation, Omega, Elekheat, Rama Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Cartridge Heaters Market Trends and Innovations
Ceramic-insulated cartridge technology is displacing traditional magnesium oxide cores in corrosive environments, while miniature form factors below 3mm diameter are penetrating electronics assembly lines. These shifts are compressing product lifecycles and rewiring supplier qualification protocols.
Aluminum nitride ceramic insulation is electrifying the high-temperature segment. This material delivers thermal conductivity above 170 W/m·K with dielectric strength exceeding 15 kV/mm. Semiconductor process equipment manufacturers in South Korea are adopting aluminum nitride sheaths for rapid thermal processing chambers. The technology is electrifying competitive positioning by enabling 40% faster heat-up rates than legacy oxide-filled designs.
REACH substance restrictions are tightening material disclosure requirements for sheath alloys containing cobalt or hexavalent chromium surface treatments. Industrial heating equipment manufacturers must now submit full chemical composition dossiers to ECHA for market access. European chemical processing installations are responding by sourcing alternative ferritic stainless steel grades that sacrifice some corrosion resistance for regulatory compliance.
Buyer consolidation among tier-one automotive suppliers is compressing vendor relationship counts from 12-15 heater sources to 3-4 preferred partners per tooling platform. Mold procurement teams now demand integrated thermal system warranties covering sensors, controllers, and heating elements under single-source accountability. This concentration is most visible in German automotive supply chains, where Volkswagen Group and BMW have mandated unified thermal subsystem qualification.
Electric Cartridge Heaters Market Segmentation
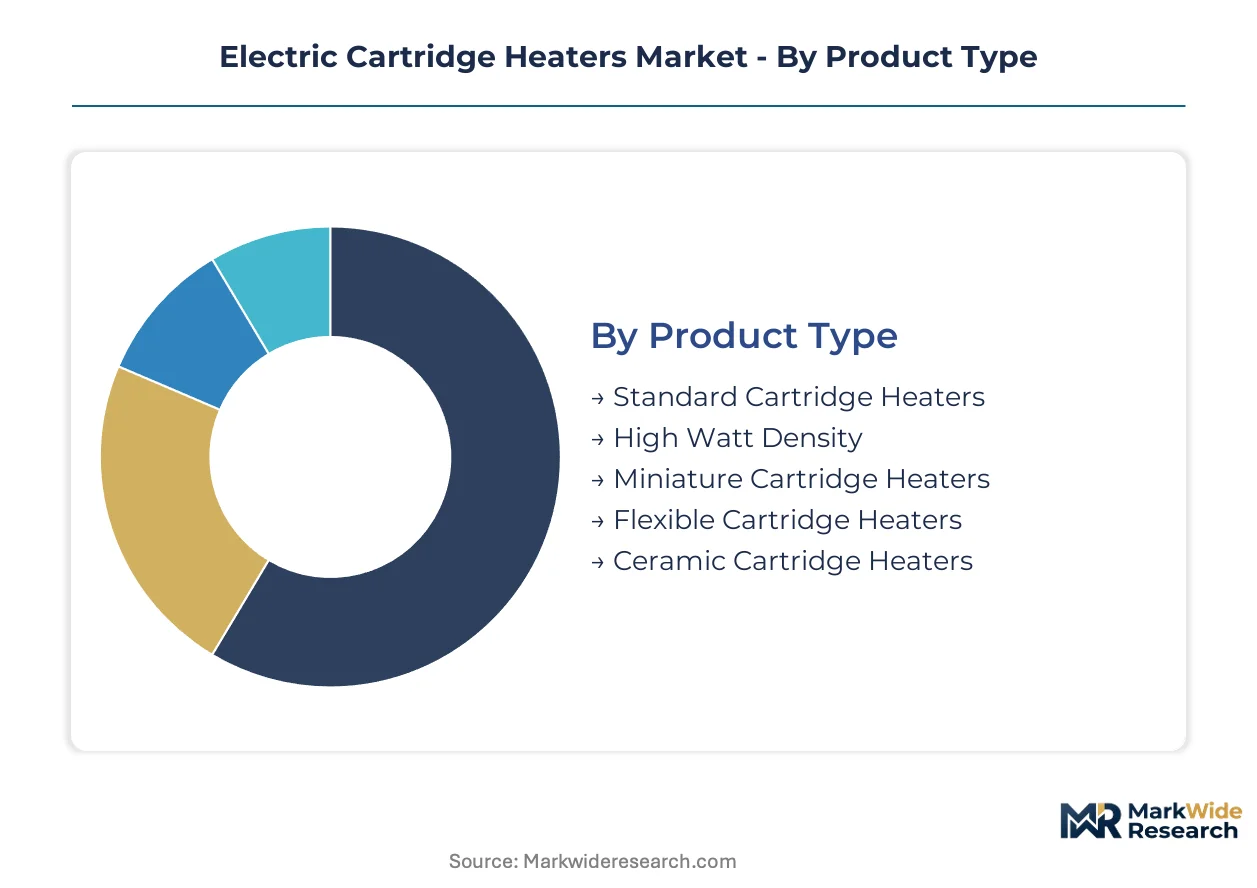
Segmentation in the electric cartridge heaters market reflects divergent thermal engineering requirements across precision manufacturing tiers. Product architecture, insulation technology, and end-use intensity create distinct procurement patterns that separate commodity replacement demand from engineered system sales.
Product Type:
Standalone cartridge heaters dominate maintenance procurement, while embedded configurations anchor new equipment specifications in semiconductor and aerospace tool builds.
- Standard Cartridge Heaters:Stainless steel sheaths with magnesium oxide insulation deliver localized heat to 800°F for general-purpose plastics molding and packaging machinery. Demand concentrates in North American automotive tier-one tooling refresh cycles as OEMs consolidate vendor relationships.
- High Watt Density:Compacted magnesium oxide cores with nickel-chromium geometries achieve 1400°F in reduced sheath diameters for aerospace component forming. Semiconductor fabrication node transitions below 3nm in Taiwan and South Korea are compressing thermal uniformity tolerances and accelerating orders for sub-10-second thermal response cycles.
- Miniature Cartridge Heaters:Sub-3mm diameters penetrate electronics assembly lines in Noida and Sriperumbudur as India's PLI scheme drives contract manufacturing expansion.
- Flexible Cartridge Heaters:Bendable stainless steel sheaths conform to curved die geometries in food processing equipment.
- Ceramic Cartridge Heaters:Aluminum nitride insulation displaces oxide cores in corrosive chemical environments.
Volume placements concentrate in standard cartridge heaters; the faster expansion belongs to miniature cartridge heaters.
Technology:
Insulation material selection determines maximum operating temperature, dielectric strength, and regulatory compliance pathways across chemical and semiconductor process environments.
- Resistance Wire:Nickel-chromium alloy cores remain the baseline construction for cost-sensitive industrial heating applications.
- Mica Insulated:Layered mica sheets provide electrical isolation in moderate-temperature packaging equipment where magnesium oxide compaction costs prove prohibitive.
- Ceramic Insulated:Aluminum nitride cores deliver thermal conductivity above 170 W/m·K with dielectric strength exceeding 15 kV/mm. South Korean semiconductor equipment manufacturers are adopting these sheaths for rapid thermal processing chambers, achieving 40% faster heat-up rates than legacy designs.
- Quartz Encapsulated:Fused silica jackets withstand thermal shock in laboratory equipment requiring optical transparency.
- Silicone Rubber Coated:Flexible outer layers protect against moisture ingress in food processing washdown environments.
Resistance wire technology retains the largest installed base; ceramic insulated configurations are climbing the fastest as semiconductor node transitions intensify.
Application:
Process temperature precision requirements separate commodity replacement demand from engineered thermal system specifications.
- Packaging Equipment:Standard watt density units seal films and form containers in high-speed lines where thermal uniformity matters less than cycle speed.
- Food Processing:Sanitary-grade sheaths with FDA-compliant surface finishes heat extrusion dies for protein and carbohydrate processing.
- Semiconductor Manufacturing:Process chambers demand ±0.5°C thermal uniformity as fabrication nodes shrink below 3nm, forcing redesign of resistance wire geometries and sheath alloys.
- Plastics Molding:Injection molds and extrusion dies represent the largest volume application, with German automotive suppliers consolidating procurement across fewer vendor relationships.
- Laboratory Equipment:Analytical instruments require miniature form factors with precise temperature control for sample preparation.
Plastics molding commands the highest shipment volumes; semiconductor manufacturing shows the steepest expansion trajectory.
End User Industry:
Customer sophistication around thermal system integration separates price-driven replacement purchasing from specification-engineered procurement.
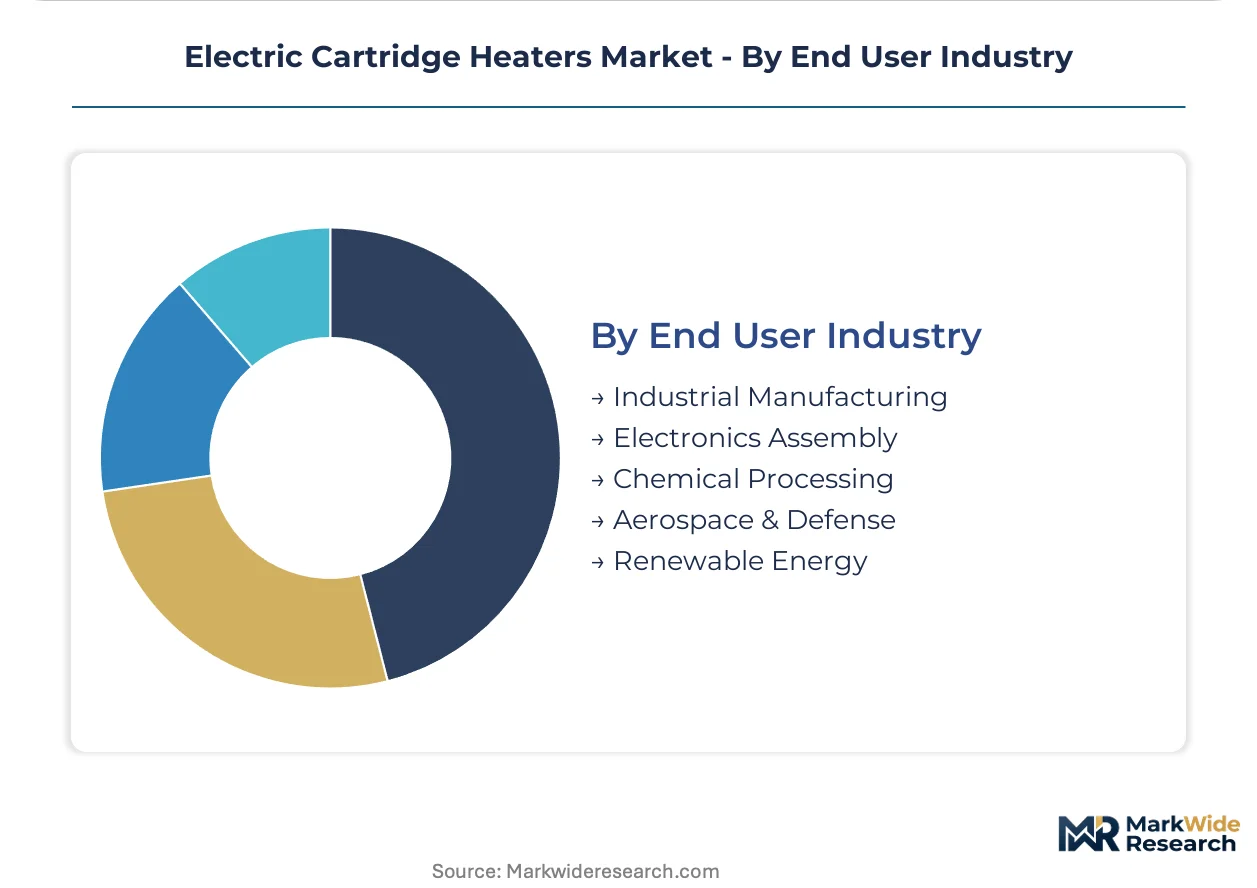
- Industrial Manufacturing:General machinery builders specify standard cartridge heaters for heating plates, sealing bars, and mold temperature control units.
- Electronics Assembly:Miniature heaters shrink tooling footprints in PCB assembly and semiconductor packaging equipment.
- Chemical Processing:Corrosive environments in European installations are driving alternative ferritic stainless steel grades as REACH substance restrictions constrain cobalt and hexavalent chromium surface treatments.
- Aerospace & Defense:Severe duty cycles in component forming command premium positioning for high watt density configurations with specialized nickel-chromium core designs.
- Renewable Energy:Battery manufacturing equipment requires precise thermal management for electrode drying and electrolyte processing.
Industrial manufacturing accounts for the broadest volume base; electronics assembly is gaining share fastest as Asian contract manufacturing clusters expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in East Asian precision manufacturing clusters where semiconductor fabrication expansion drives specialized heater procurement. German automotive supply chains and North American packaging equipment builders represent secondary volume anchors with distinct thermal system requirements.
United States
Packaging OEMs in Chicago and Milwaukee drive standard cartridge heater replacement demand for high-speed sealing lines. OSHA electrical safety regulations enforce NEMA enclosure classifications for wet-environment chemical processing installations. Midwest manufacturing regions harbor concentrated metallurgical engineering expertise for magnesium oxide compaction design.
Germany
Volkswagen Group and BMW mandate unified thermal subsystem qualification across consolidated vendor relationships. EU machinery directives under CE marking accelerate replacement cycles for legacy heating systems in injection molding operations. Bavarian automotive supply chains concentrate procurement authority among 3-4 preferred heater partners per tooling platform.
South Korea
Semiconductor equipment manufacturers adopt aluminum nitride ceramic sheaths for rapid thermal processing chambers. METI-equivalent industrial standards govern thermal uniformity specifications for sub-3nm fabrication node transitions. Seoul capital area fabs compress thermal response cycle requirements to sub-10-second specifications.
Taiwan
Foundry expansion drives orders for high-watt-density units in process chamber applications. National semiconductor development programs align supplier qualification with sub-0.5°C thermal uniformity tolerances. Hsinchu Science Park anchors precision manufacturing demand for localized heat delivery systems.
India
Electronics assembly lines in Noida and Sriperumbudur create virgin demand for miniature cartridge heaters. PLI scheme incentives for contract manufacturing expand tooling footprints in shrunken electronics packaging. National standards body BIS certification requirements shape import substitution strategies for industrial heating equipment.
Electric Cartridge Heaters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated thermal systems and ceramic insulation technologies. The vendor base stratifies across three tiers: multinational thermal system houses with captive sensor production, regional specialists in rapid-turn custom designs, and commodity assemblers dependent on Chinese magnesium oxide supply. Dominant competitive moves include backward integration into temperature sensing elements and geographic expansion through distributor network consolidation in Asian manufacturing clusters.
Among US-based thermal engineering houses, Watlow and Chromalox exemplify divergent strategic archetypes. Watlow represents the integrated-systems path, anchoring long-term medical device contracts through captive sensor production. Chromalox occupies a position emphasizing geographic density in European chemical processing installations. Tempco Electric Heater Corporation sits within the rapid-turn specialization tier, serving North American packaging OEMs with custom sheath machining capabilities.
| Leading Market Players |
|---|
| Watlow |
| Backer Hotwatt |
| Chromalox |
| Dalton Electric |
| Durex Industries |
| Tempco Electric Heater Corporation |
| Omega |
| Elekheat |
| Rama Corporation |
| Others |
Pricing and Supply Chain Analysis
Metallurgical engineering expertise concentrated in Midwest US manufacturing regions creates labor-cost differentials that widen pricing-tier spreads between commodity assemblers and precision thermal system houses. REACH substance restrictions in Europe and OSHA electrical safety regulations in the United States add compliance-cost layers that separate ISO-certified suppliers from uncertified competitors.
Pricing Analysis
Volume placements concentrate in standard cartridge heaters while margins accrue to high-watt-density and sensor-integrated configurations. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade nickel-chromium cores from general-purpose magnesium oxide units and Chinese-imported commodity heaters. Cost compression in the standard tier is intensifying because buyer consolidation among automotive suppliers compresses vendor counts. Tier-one automotive molders show least price sensitivity for thermal uniformity warranties; packaging OEMs drive hardest bargain on per-unit heater costs.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and BIS certification requirements are reshaping sourcing patterns for miniature heater assemblies in Noida and Sriperumbudur. Magnesium oxide insulation production clusters in Chinese industrial zones, with nickel-chromium wire drawing concentrated in Japan and Germany. Single-source vulnerability for electrical insulation materials threatens non-vertically integrated assemblers when logistics chokepoints emerge. Distribution runs through authorized distributor networks in Asian manufacturing clusters and direct OEM relationships in German automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions and EU machinery directives under CE marking erect compliance barriers that favor incumbent thermal system houses with established ECHA dossier capabilities. This cost-of-compliance dynamic creates sustainable moats against low-cost import competition.
For Market Incumbents: Cement sensor-integrated heater system dominance through captive platinum resistance temperature detector production. Threats from ceramic-insulated technology entrants in South Korean semiconductor equipment demand accelerated aluminum nitride sheath R&D investment. Backward integration into magnesium oxide compaction controls raw material cost volatility.
For New Entrants and Emerging Players: Distributor partnerships in India's PLI scheme electronics corridors offer lowest barrier-to-entry pathways. White-space targets include miniature cartridge heaters for Noida contract assembly lines and rapid-turn custom designs for North American packaging OEMs. Go-to-market positioning should emphasize BIS certification compliance for import substitution strategies.
For Investors and Strategic Acquirers: Re-rating potential sits with ceramic-insulated specialists given semiconductor node transition catalysts below 3nm. Long-term viability favors upstream-integrated thermal engineering houses over commodity assemblers dependent on Chinese magnesium oxide supply. Watch for thermal uniformity specification tightening in Taiwan foundry expansion announcements as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Production | Watlow anchors medical device contracts through captive platinum resistance temperature detector supply. |
| Ceramic Insulation Technology Licensing | Aluminum nitride sheath adoption by South Korean semiconductor equipment manufacturers accelerates heat-up rates. |
| Geographic Expansion through Distributor Consolidation | Asian manufacturing cluster coverage captures India's PLI scheme electronics assembly demand. |
| ISO 9001:2015 Certification Investment | Automotive tier-one procurement mandates documented thermal uniformity traceability for supplier inclusion. |
| Custom Sheath Machining Capability Buildout | Tempco Electric Heater Corporation serves rapid-turn requirements for legacy mold retrofits in packaging equipment. |
Research Methodology
Document review covered SEC filings from thermal system manufacturers, ECHA substance registration databases, and semiconductor equipment capex disclosures, complemented by interviews with plant engineers at plastics molding facilities, procurement leads at automotive tier-one suppliers, maintenance directors in chemical processing installations, and thermal system design engineers. Customs trade data for magnesium oxide and nickel-chromium alloy shipments, ISO certification registries, and OSHA enforcement records provided secondary validation. Bottom-up unit shipment estimates triangulated against top-down industry spend analysis.
Historical volume trajectories cross-referenced against expert panel input on semiconductor fabrication node transition timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, insulation technology, end-use intensity, and geographic manufacturing cluster. CAGRs derived from curve-fitting techniques applied to disclosed capacity expansion plans and replacement cycle assumptions. Industry-specific forecast inputs incorporated REACH substance restriction phase-in schedules and PLI scheme incentive disbursement patterns.
Caveats apply where nickel price volatility on the London Metal Exchange or magnesium oxide supply disruptions could materially shift the outlook for mid-tier manufacturer margin buffers. Forecasts reflect assumptions around thermal uniformity specification evolution and regulatory compliance timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Actuators Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Global Linear Bearings Market