
 Camera Tripods Market | 2026-2036
Camera Tripods Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Tripods Market Outlook
The EU REACH regulation is restructuring material sourcing priorities across the camera tripod supply chain, pushing manufacturers toward lower-toxicity coatings and recycled aluminum alloys. Manfrotto leverages its Italian manufacturing heritage and vertical control over leg-lock mechanisms to sustain premium positioning in European retail channels. Gitzo anchors the high-end carbon fiber segment through proprietary weave technologies developed in France. Benro competes aggressively on price-performance ratios, dominating volume sales across Asia-Pacific e-commerce platforms.
A camera tripod is a three-legged collapsible support device, typically constructed from aluminum tubing or carbon fiber composite layups with precision-machined leg locks, designed to stabilize imaging equipment during exposure. Load capacity ratings of 5 kg and 10 kg now capture the majority of interchangeable-lens camera users, from mirrorless hybrid shooters to cinema rig operators. Carbon fiber tripods command the highest margin pools due to their strength-to-weight ratio and thermal stability in field conditions, while aluminum variants remain the volume backbone for entry-level and education markets. Professional-grade models with integrated leveling bases and quick-release plates are seeing accelerated replacement cycles as content creators upgrade to heavier cinema cameras.
The EU REACH framework and China's GB standards for product safety jointly shape material compliance requirements and market access conditions for tripod manufacturers operating across both regions. The US Consumer Product Safety Commission monitors tip-over hazards in lightweight consumer models, particularly those marketed to mobile vloggers and travel photographers. Japan's METI energy efficiency guidelines indirectly influence motorized tripod head development through standby power regulations. Stakeholders must monitor evolving chemical substance restrictions and weight-bearing certification protocols as the primary variables determining which product architectures survive cross-border commercialization.
Market Dynamics
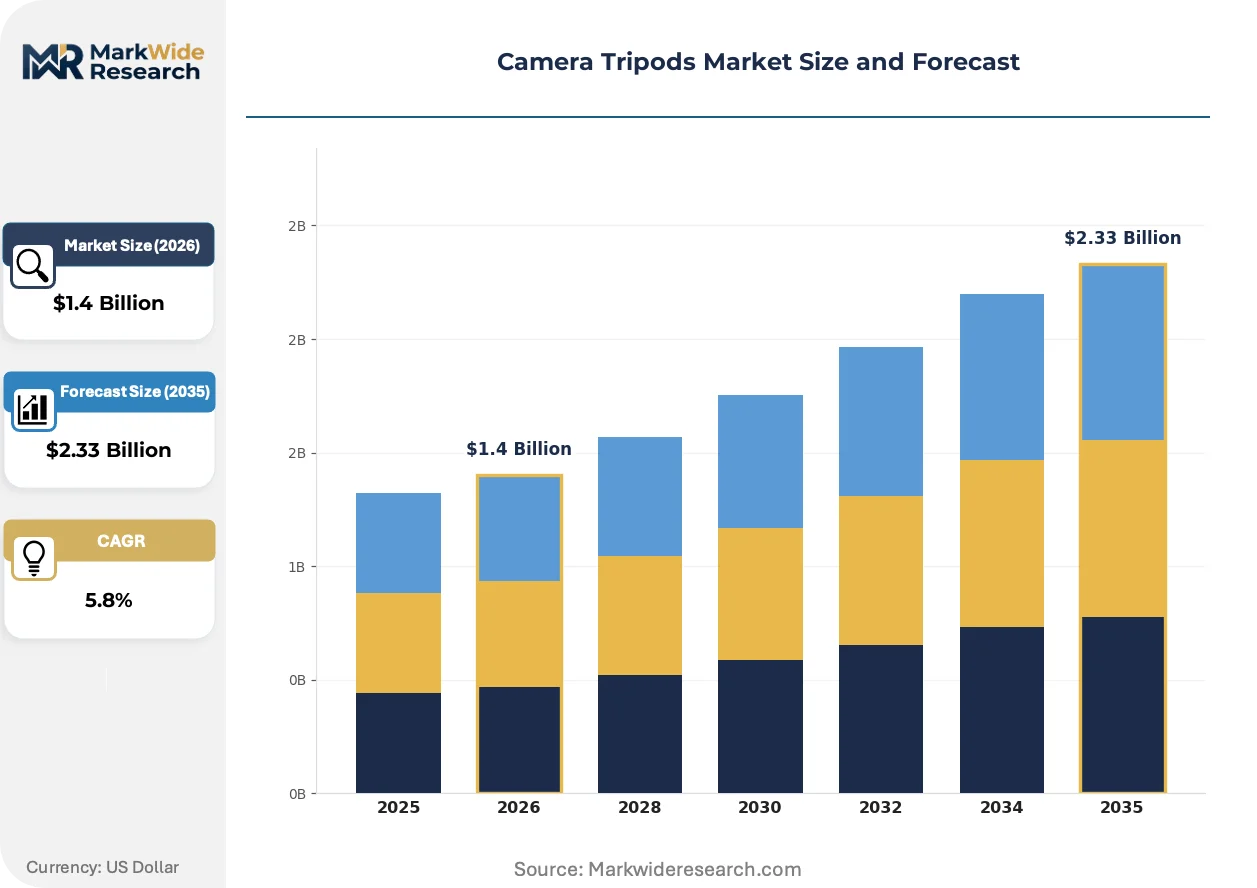
Content creator economy expansion and EU REACH chemical compliance mandates are restructuring tripod manufacturing priorities, forcing simultaneous investments in sustainable materials and creator-centric product architectures.
Growth Catalysts
- Creator Economy Expansion:Streaming and vlogging professionals are upgrading from entry-level supports to cinema-grade tripods with integrated fluid heads and quick-release systems.
- REACH Regulation:The EU's chemical substance framework is accelerating adoption of recycled aluminum alloys and water-based coatings across European manufacturing facilities.
- Carbon Fiber Proliferation:Advanced composite layup techniques are reducing weight-to-load ratios, enabling single-operator field deployment of heavy cinema rigs.
Market Restraints
- Raw Material Concentration:High-modulus carbon fiber precursor supply concentrates among Japanese and South Korean petrochemical suppliers, creating input cost volatility.
- Technical Load Ceiling:Lightweight travel tripods face inherent stability trade-offs above 8 kg payloads, limiting penetration into full cinema camera segments.
- Substitution by Gimbals:Electronic stabilization systems from DJI and Freefly are capturing mobile creator segments that previously purchased compact tripods.
Strategic Opportunities
- India Creator Infrastructure:YouTube and Instagram creator growth in Mumbai and Bangalore is outpacing local tripod supply, opening distribution partnerships for mid-tier brands.
- Live Commerce Integration:Tripod manufacturers are embedding ring lights and phone mounts directly into leg assemblies for Southeast Asian live-selling studios.
- EU Green Deal Alignment:Ecodesign requirements for repairable products are creating first-mover advantage for modular tripod architectures with replaceable leg sections.
Industry Challenges
- Precision Machining Talent:CNC programming expertise for leg-lock mechanisms concentrates in Guangdong and northern Italy, creating recruitment bottlenecks for new market entrants.
- Multi-Region Certification Lag:Simultaneous GB standard testing in China, CE marking in Europe, and FCC compliance for motorized heads extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Tripods Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Professional, Compact, Mini, Monopod Material: Aluminum, Carbon Fiber, Plastic, Wood Load Capacity: 3 kg, 5 kg, 10 kg, 15 kg Feature: Adjustable Height, Quick Release, Panorama, Leg Lock |
| Companies Covered | Manfrotto, Gitzo, Benro, Vanguard, Sirui, Joby, Neewer, Hama, Feisol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Tripods Market Strategic Shifts
Smart connectivity and sustainable material science are converging to redefine tripod functionality, while regulatory pressure on chemical inputs is forcing supply chain transparency investments.
Carbon fiber composite layups with vibration-damping resin matrices are absorbing harmonic oscillations from mirrorless camera shutters, enabling longer exposure times without motion blur. Wedding and landscape photographers are adopting these supports at accelerating rates. The technology is absorbing market share from aluminum alternatives in the 3-6 kg load category.
EU REACH substance restrictions on hexavalent chromium plating are compelling manufacturers to shift toward ceramic-coated aluminum leg sections and anodized finishes. The regulation is eliminating traditional chrome-plated steel components from European-bound product lines. Professional-grade manufacturers serving Germany and France are redesigning leg-lock interfaces to accommodate these material transitions.
Direct-to-creator sales through TikTok Shop and specialized live-streaming platforms are compressing traditional distributor margins in Asia-Pacific markets. Established retail channels in Japan and South Korea are responding with bundled service packages including on-site setup training. This channel rotation is most pronounced among Gen Z content creators in urban China.
Camera Tripods Market Segmentation
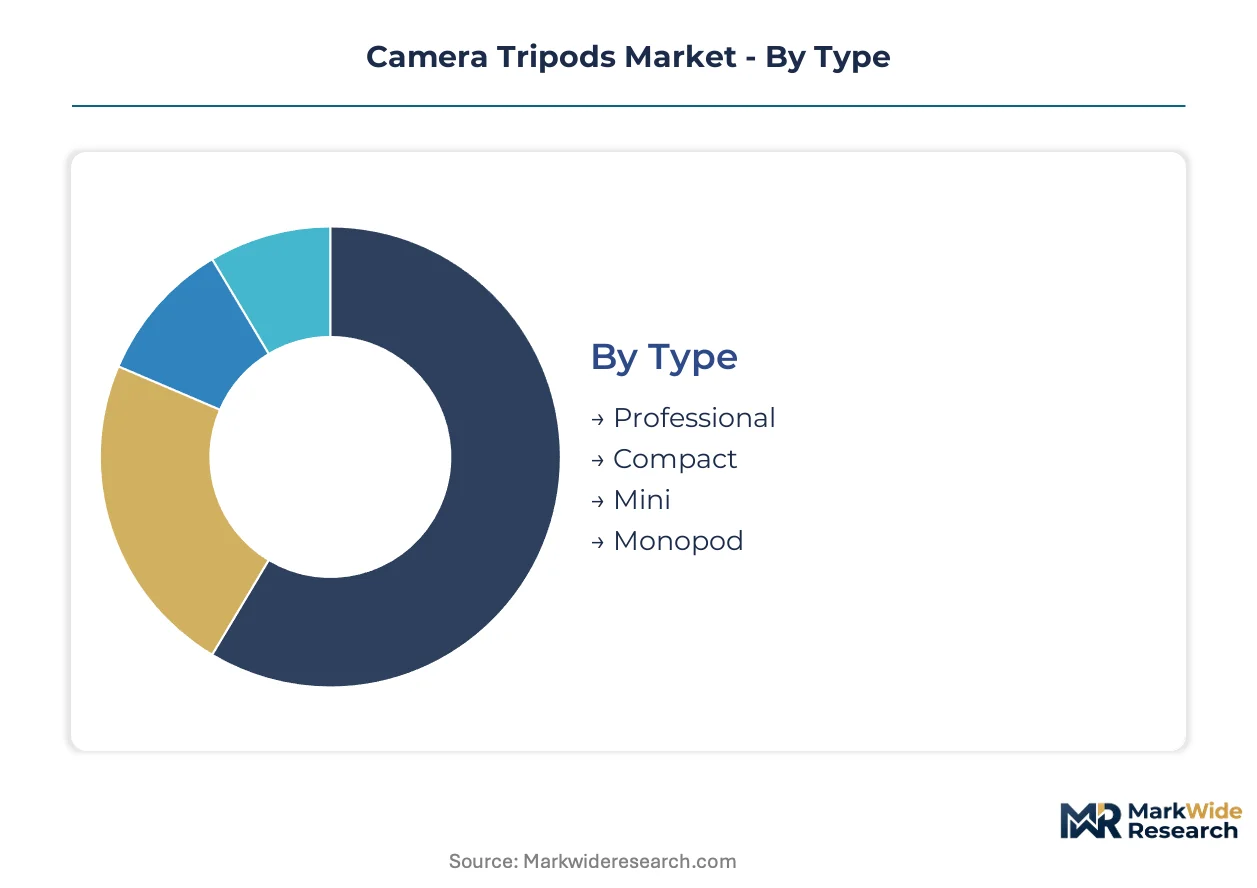
Camera tripod segmentation reveals how manufacturers balance material science against creator workflow requirements. Each dimension—type, material, load capacity, and feature—channels production investment toward distinct price-performance tiers.
Type:
Professional-grade manufacturing concentrates in Italian and Japanese facilities with captive CNC machining capabilities for precision leg locks.
- Professional:Studio and cinema configurations with integrated fluid heads and 100mm bowl bases. Broadcast operators in Germany and France are replacing aluminum models with carbon fiber variants to reduce transport weight for location shoots.
- Compact:Collapsible four-section designs with reverse-folding legs for travel photographers. Chinese manufacturers in Guangdong dominate volume output for this category, serving Southeast Asian vloggers through TikTok Shop direct sales.
- Mini:Tabletop supports with ball heads for product photography and streaming setups.
- Monopod:Single-leg stabilizers for sports and wildlife photographers requiring mobility.
Professional tripods absorb the bulk of installed capacity; compact designs are expanding most quickly.
Material:
Cost tier stratification separates premium composite sourcing from commodity metal extrusion.
- Aluminum:6061-T6 and 7075 alloys form the volume backbone through extrusion and anodizing processes. Education markets and rental houses in India specify aluminum for durability-to-cost ratios.
- Carbon Fiber:Toray T700 and T800 prepregs with proprietary resin matrices deliver strength-to-weight ratios above 5:1. Wedding photographers in Japan and landscape specialists in Norway adopt these for multi-day treks with heavy medium-format rigs.
- Plastic:Glass-reinforced nylon for entry-level consumer models and smartphone accessories.
- Wood:Traditional hardwoods for large-format view camera operators and restoration markets.
Aluminum maintains the deepest production footprint; carbon fiber commands the steepest expansion trajectory.
Load Capacity:
Application requirements dictate structural engineering investment across payload thresholds.
- 3 kg:Mirrorless hybrid systems with compact zoom lenses. Solo creators in South Korea upgrading from smartphone rigs drive replacement demand in this bracket.
- 5 kg:Full-frame DSLR and cinema camera configurations with matte boxes. Documentary filmmakers in Spain and Italy specify this rating for run-and-gun productions balancing mobility with rig weight.
- 10 kg:Heavy cinema rigs with follow focus and wireless video systems.
- 15 kg:Broadcast box lenses and telephoto wildlife configurations.
5 kg ratings anchor current manufacturing volumes; 10 kg specifications are climbing the fastest as mirrorless cinema cameras proliferate.
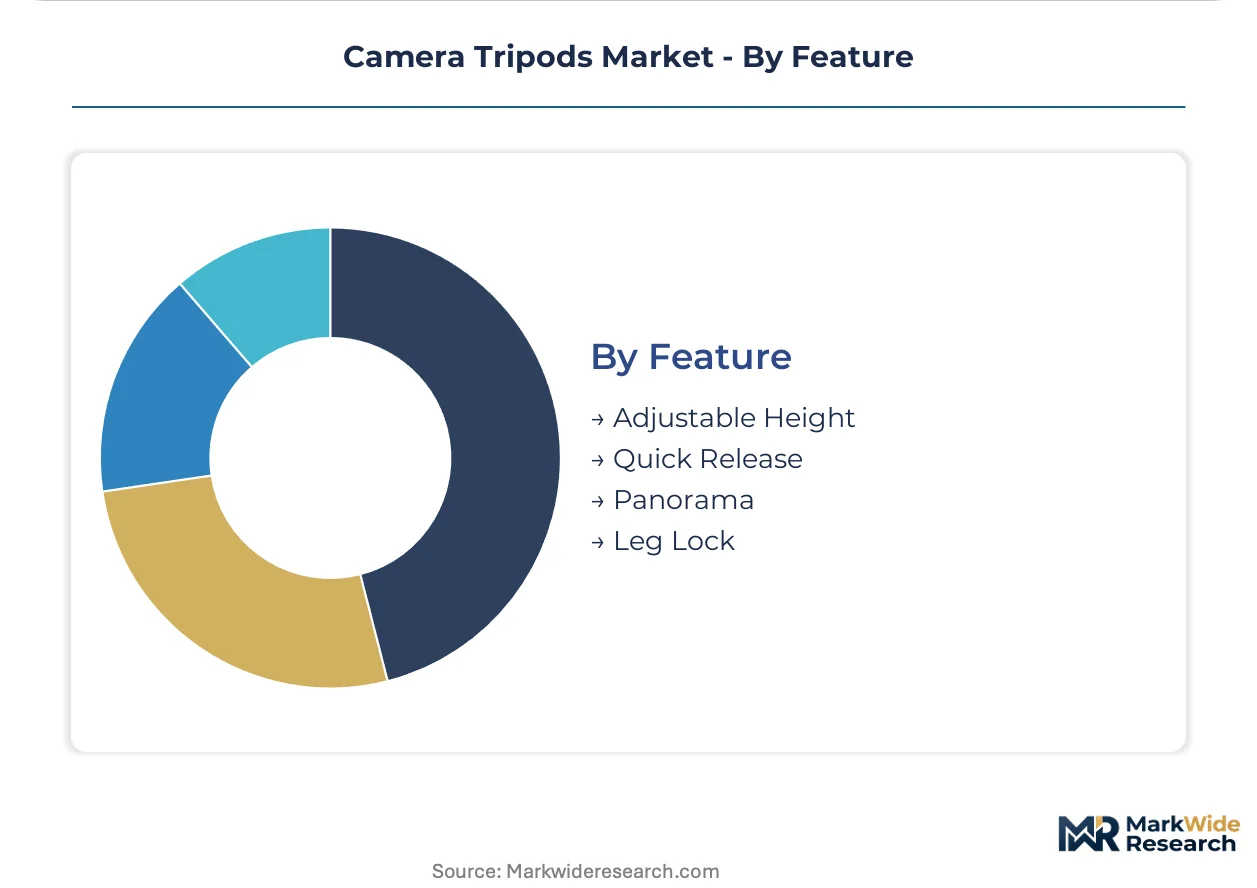
Feature:
Margin differentiation concentrates in mechanical interfaces and electronic integration points.
- Adjustable Height:Four- and five-section leg extensions with twist or flip-lock mechanisms. Rental houses in California and New York specify redundant locking systems for liability reduction.
- Quick Release:Arca-Swiss compatible plates and proprietary Manfrotto RC2 systems. YouTube studio operators in London and Berlin standardize on Arca-Swiss for cross-equipment compatibility.
- Panorama:Indexed rotation bases for multi-image stitching workflows.
- Leg Lock:Twist-grip and flip-lever mechanisms with weather sealing.
Quick release systems capture the widest accessory attachment revenue; panorama features are gaining share fastest among architectural photographers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors the global camera tripod manufacturing base, with Shenzhen and Dongguan hosting dense clusters of CNC machining facilities and carbon fiber composite workshops that supply both domestic Chinese creators and export markets.
China
Domestic content creator platforms like Douyin and Bilibili are driving 10 kg load-capacity tripod demand among independent filmmakers in Chengdu and Hangzhou. GB standards for product safety govern material compliance for all camera support equipment sold domestically. The Pearl River Delta concentration of aluminum extrusion and carbon fiber prepreg suppliers enables rapid prototype-to-production cycles for brands serving Southeast Asian e-commerce channels.
United States
YouTube studio operators in Los Angeles and Austin are upgrading to professional-grade fluid head systems as advertising revenue stabilizes for mid-tier creators. The Consumer Product Safety Commission monitors tip-over stability in lightweight travel tripods marketed to mobile vloggers. California-based rental houses specify redundant leg-lock mechanisms for liability coverage on cinema productions.
Germany
Broadcast operators in Munich and Hamburg are replacing aluminum studio tripods with carbon fiber variants to reduce transport weight for location documentary shoots. EU REACH substance restrictions on hexavalent chromium plating are eliminating chrome-plated steel components from European-bound product lines. The Bavarian industrial corridor hosts precision machining subcontractors serving Italian and French tripod brands.
Japan
Wedding photographers in Tokyo and Osaka are adopting vibration-damping carbon fiber supports for multi-day location shoots with medium-format rigs. METI energy efficiency guidelines influence standby power regulations for motorized tripod head development. The Nagoya manufacturing belt retains captive CNC programming expertise for high-precision leg-lock mechanisms.
India
YouTube and Instagram creator growth in Mumbai and Bangalore is outpacing local tripod supply, opening distribution gaps for mid-tier import brands. The Bureau of Indian Standards certifies load-bearing safety for camera support equipment entering the domestic market. Maharashtra-based equipment rental firms specify aluminum tripods for durability-to-cost ratios in education and event videography segments.
Camera Tripods Market Competitive Environment
Premium-margin players sit above commodity-margin players across material-grade and precision-engineering dimensions, with Italian and Japanese manufacturers commanding price multiples over Chinese volume producers. The vendor base stratifies into three tiers: heritage brands with captive CNC capabilities, scale-driven fabricators serving e-commerce channels, and specialist composite workshops. Strategic moves concentrate on backward integration into carbon fiber prepreg supply and modular architecture redesign for EU repairability mandates.
Within the heritage-brand tier, Manfrotto and Gitzo exemplify European precision-manufacturing archetypes with vertical control over leg-lock mechanism production. Benro occupies a position among Asia-Pacific scale players competing on price-performance ratios across e-commerce platforms. These three anchors illustrate how geographic manufacturing heritage maps to margin structure: Italian and French origins correlate with premium positioning, while Chinese base enables volume penetration.
| Leading Market Players |
|---|
| Manfrotto |
| Gitzo |
| Benro |
| Vanguard |
| Sirui |
| Joby |
| Neewer |
| Hama |
| Feisol |
| Others |
Value Chain & Pricing Dynamics
EU REACH mandates on hexavalent chromium elimination are forcing manufacturers to absorb ceramic-coating cost premiums or surrender European market access, compressing margins for non-compliant suppliers while rewarding early adopters with pricing power in Germany and France.
Pricing Analysis
Load-capacity ratings anchor value-based pricing, with 10 kg cinema-grade configurations commanding multiples over 3 kg mirrorless supports due to stability guarantees under heavy rig deployment. Three-tier pricing structure across premium carbon fiber, standard aluminum, and economy plastic tiers separates Gitzo and Manfrotto from Benro and Neewer on brand heritage and precision engineering. Cost compression in the compact travel segment intensifies as Chinese direct-to-creator channels bypass distributor markups. Education markets and rental houses in India exhibit highest price sensitivity; broadcast operators in Munich and Hamburg show lowest sensitivity when transport weight reduction justifies premium outlays.
Supply Chain Analysis
Direct-to-creator channels through TikTok Shop and specialized live-streaming platforms handle Gen Z demand in urban China, compressing traditional retail margins. Manufacturing concentrates in Guangdong Province, Japan, and Italy, with Shenzhen and Dongguan hosting CNC machining clusters and Toray T700 carbon fiber prepreg supply tethered to Japanese petrochemical suppliers. Raw material dependencies include high-modulus carbon fiber precursor, 6061-T6 aluminum extrusion stock, and vibration-damping resin matrices. Single-source vulnerability in Japanese carbon fiber precursor supply creates input cost volatility during petrochemical feedstock disruptions. Distribution runs through e-commerce platforms in Asia-Pacific and specialized retail channels in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH compliance operates as a structural moat, with substance restriction enforcement eliminating chrome-plated competitors and consolidating margin pools among ceramic-coating capable manufacturers.
For Market Incumbents: Extend modular architecture investments to capture EU Green Deal repairability premiums, redesigning leg-lock interfaces for field-replaceable sections. Backward integration into carbon fiber prepreg supply secures margin control against Toray supply volatility. DJI gimbal substitution in mobile creator segments demands fluid head feature differentiation to defend tripod relevance. For New Entrants and Emerging Players: Enter via Mumbai and Bangalore creator infrastructure gaps, where YouTube and Instagram growth outpaces local supply. Mid-tier aluminum 5 kg configurations offer the most penetrable wedge against established premium positioning. Go-to-market through Maharashtra rental house partnerships leverages durability-to-cost specification requirements in education and event videography. For Investors and Strategic Acquirers: Re-rating potential sits with Guangdong-based fabricators possessing captive CNC programming expertise and REACH-compliant coating capabilities, given EU market access catalysts. Long-term viability favors manufacturers with vertical control over leg-lock mechanisms and modular patent portfolios. Watch for carbon fiber precursor price spikes as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Prepreg | Captive Toray T700 supply secures margin control against Japanese petrochemical volatility. |
| EU Green Deal Modular Redesign | Field-replaceable leg sections capture Ecodesign repairability premiums in Germany and France. |
| Direct-to-Creator Channel Expansion | TikTok Shop penetration in Chengdu and Hangzhou bypasses traditional distributor margin extraction. |
| Ceramic Coating Compliance Investment | REACH-compliant anodized finishes eliminate chrome-plated competitors from European market access. |
| India Distribution Partnership | Maharashtra rental house relationships anchor volume penetration in outpaced creator markets. |
Study Parameters
Independent corroboration across precision manufacturing executives, content creator equipment purchasers, and EU regulatory compliance officers underwrites the qualitative findings. Primary interviews with CNC programming specialists in Guangdong and northern Italy, carbon fiber composite engineers, and rental house procurement managers in California and Maharashtra combined with secondary validation from customs trade data, SEC filings of listed precision equipment manufacturers, and ECHA substance restriction databases. Bottom-up demand modeling from creator economy platform disclosures triangulates against top-down production capacity estimates from Pearl River Delta industrial zone reports.
Rate-of-change decomposition across the analysis window separates volume expansion from price-mix effects, with CAGRs derived from segment-level load capacity adoption curves and material substitution elasticities. Segmentation dimensions modeled include tripod type, material grade, payload rating, and feature integration. Forecast inputs incorporate REACH compliance cost pass-through assumptions and carbon fiber precursor supply elasticity parameters from Japanese petrochemical supplier disclosures.
Revisions become necessary when EU substance restriction enforcement intensifies, carbon fiber supply disruptions materialize, or gimbal stabilization technology crosses payload thresholds into cinema camera segments. Forecasts reflect documented assumptions on creator economy platform growth trajectories and regulatory compliance timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Global Temperature Control Units (TCU) Market