
 Dustless Workstations Market | 2026-2036
Dustless Workstations Market Size, Share, and Industry Trends Forecast 2026-2036
Dustless Workstations Market Analytics
HEPA-negative-pressure integration with real-time particle monitoring is reshaping how dustless workstations are engineered for critical environments. BenchVent leverages proprietary airflow algorithms to sustain capture efficiency across variable load conditions. Graco Inc. anchors its position through backward integration into vacuum blower manufacturing, controlling core component supply. Air Science Technologies Ltd differentiates via modular cabinet architectures that accommodate rapid reconfiguration between pharmaceutical and electronics applications.
Dustless workstations are enclosed or partially enclosed systems combining HEPA filtration, directed airflow, and physical containment barriers to capture particulate at the generation point before dispersion into the ambient environment. These systems typically achieve 99.97% efficiency at 0.3 micron particle size through multi-stage filtration cascades, with face velocities calibrated to maintain laminar flow patterns that prevent turbulent escape. Portable units dominate contractor and workshop procurement due to deployment flexibility across multiple job sites, while integrated systems command premium positioning in semiconductor and pharmaceutical facilities where permanent infrastructure justifies capital-intensive installation. Custom solutions represent the fastest-expanding category as OEMs develop application-specific configurations for battery cell assembly and gene therapy manufacturing where standard designs prove inadequate.
OSHA enforces permissible exposure limits for respirable crystalline silica through workplace inspection protocols that directly drive replacement demand for legacy open-bench configurations. EPA oversight of hazardous air pollutant emissions shapes filtration media specifications and disposal requirements for saturated filters. ISO 14644 cleanroom standards and EU ATEX directives for explosive atmospheres create dual compliance pathways that manufacturers must navigate for cross-border equipment sales. Stakeholders must weigh capital deployment between incremental filtration upgrades and full workstation replacement as regulatory thresholds tighten without grandfathering provisions for installed base equipment.
Market Dynamics
OSHA's respirable crystalline silica enforcement is compelling manufacturers to replace open-bench configurations with enclosed HEPA-negative-pressure systems, creating immediate replacement demand across metalworking and composite fabrication facilities.
Growth Catalysts
- Semiconductor node advancement:Taiwan and South Korea fabrication facilities are expanding Class 1000-compliant cleanroom infrastructure to support sub-3nm production requirements.
- REACH filtration mandates:EU hazardous substance regulations are accelerating disposal protocols for saturated HEPA media in pharmaceutical manufacturing environments.
- Gene therapy manufacturing scale-up:Custom containment configurations for viral vector production are displacing standard pharmaceutical workstation designs in North American biomanufacturing clusters.
Market Restraints
- Specialized blower supply concentration:German and Japanese vacuum blower manufacturers control critical component availability, creating procurement bottlenecks during capacity expansion cycles.
- Filter media cost volatility:Glass microfiber and PTFE membrane prices fluctuate with petrochemical feedstock markets, compressing margin on replacement consumables.
- ATEX certification friction:EU explosive atmosphere directives impose dual compliance pathways that extend equipment validation timelines for battery cell assembly applications.
Strategic Opportunities
- India's PLI scheme for electronics:Contract manufacturers in Karnataka and Tamil Nadu are building greenfield assembly environments requiring localized dustless workstation supply.
- Real-time particle monitoring convergence:Integration of IoT sensors with HEPA filtration systems enables predictive maintenance contracts and recurring revenue streams.
- Battery cell dry room applications:Solid-state and sodium-ion production lines require ultra-low humidity containment configurations absent from standard product portfolios.
Industry Challenges
- Cleanroom certification backlog:ISO 14644-1 compliance testing capacity constraints delay facility commissioning and equipment acceptance.
- Legacy HVAC integration complexity:Retrofitting negative-pressure workstations into existing building management systems requires specialized controls engineering expertise.
- Filter disposal regulatory fragmentation:Hazardous waste classification varies across state and national jurisdictions, complicating service logistics for multinational operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dustless Workstations Market |
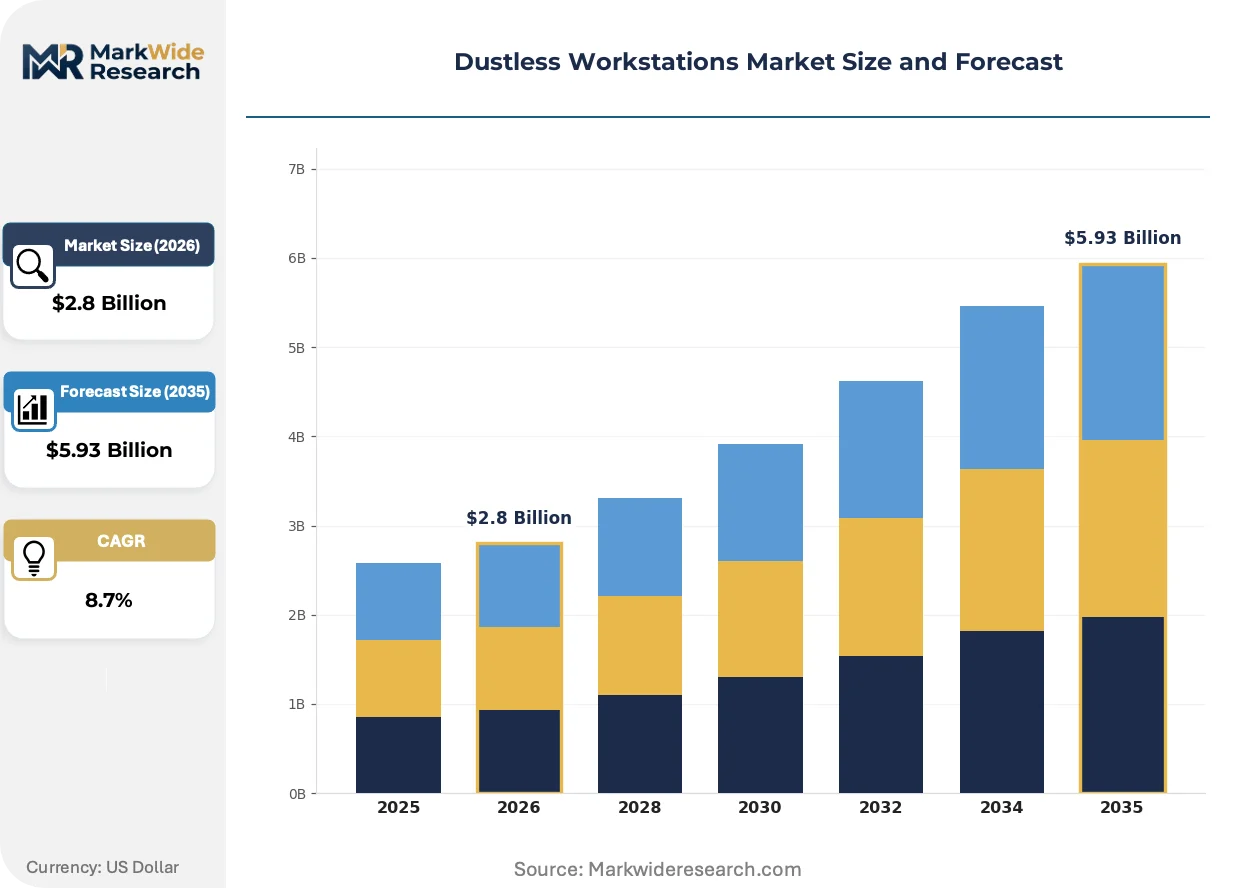
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Fixed Stations, Integrated Systems, Custom Solutions Application: Manufacturing, Construction, Automotive, Healthcare End User: Contractors, Industrial Plants, Laboratories, Workshops Technology: HEPA Filters, Vacuum Systems, Splash Guards, Airflow Management |
| Companies Covered | NARKsafe™, BenchVent, Air Science® Technologies Ltd, Graco Inc., MMLJ Inc., EcoQuip, Clemco Industries Corp., Torbo Engineering Keizers GmbH, Dustless Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dustless Workstations Market Evolving Landscape
Active airflow algorithms and modular cabinet architectures are displacing fixed-configuration designs, enabling rapid reconfiguration between pharmaceutical and electronics applications without full equipment replacement.
Ultrasonic filter loading sensors that detect particulate saturation through acoustic signature analysis are rendering obsolete scheduled replacement intervals based on operating hours. Semiconductor fabs in Hsinchu and Pyeongtaek are piloting these systems to eliminate unplanned downtime during critical production runs. The technology compresses consumables revenue predictability while shifting supplier relationships toward performance-guarantee contracts.
EPA hazardous air pollutant oversight is tightening filtration media specifications for saturated filter disposal, particularly in composite machining and stone fabrication applications. Manufacturers must now document chain-of-custody for silica-laden HEPA elements from removal through certified destruction. California and Texas metalworking clusters report the steepest compliance cost escalation as waste handlers consolidate to serve regulated disposal requirements.
Equipment-as-a-service contracting is displacing capital purchase models among mid-size contract manufacturers. German and Japanese automotive suppliers now lease dustless workstations with bundled filter replacement and certification maintenance, transferring obsolescence risk to OEMs. This restructuring concentrates procurement authority with corporate sustainability officers rather than facility engineering managers.
Dustless Workstations Market Segmentation
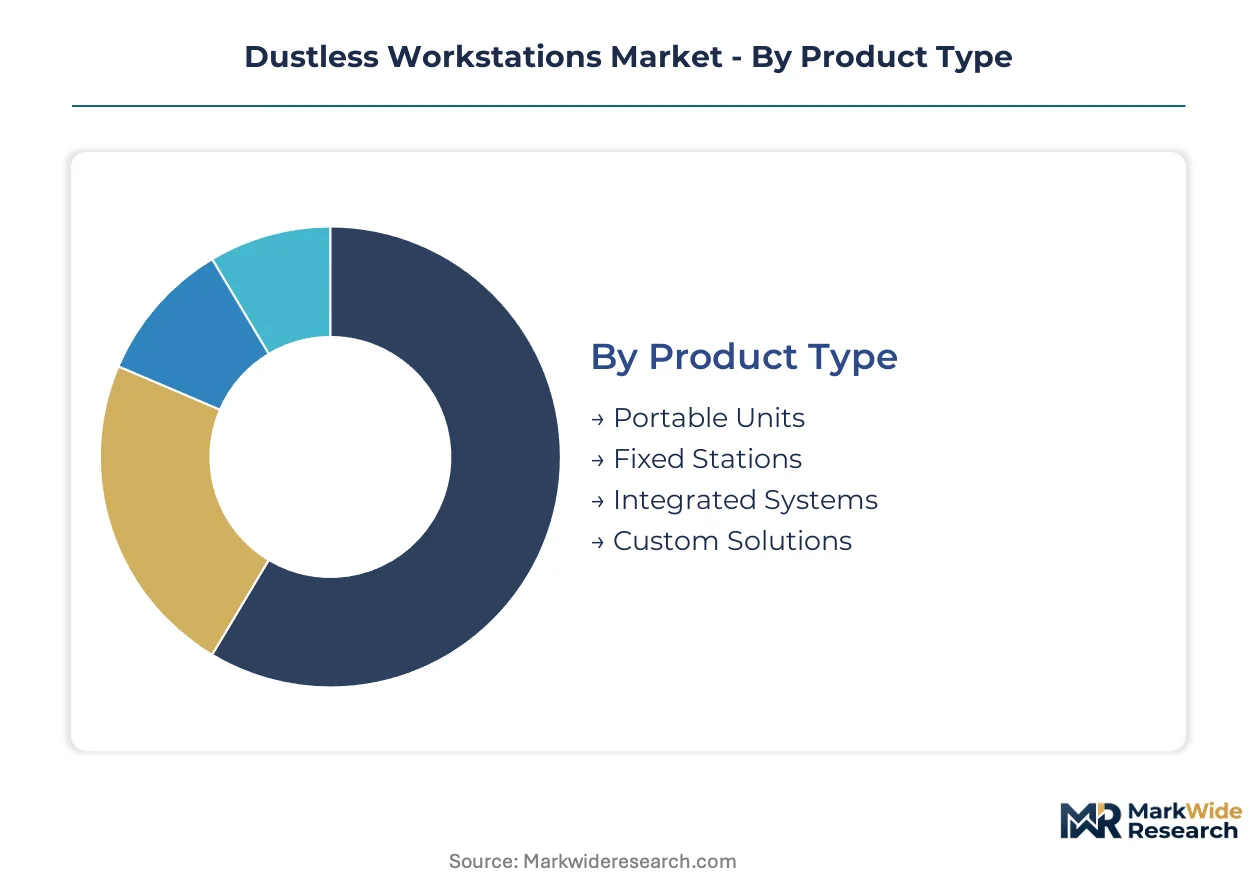
Segmentation in dustless workstations reveals distinct procurement cycles and technical requirements across product configurations and user environments. Equipment replacement intervals vary from months for portable contractor units to decades for integrated semiconductor infrastructure, shaping supplier revenue predictability and service model design.
Product Type:
Portable units turn over fastest with 18-36 month replacement cycles driven by jobsite wear, while integrated systems operate on 10-15 year capital planning horizons with mid-life filtration upgrades.
- Portable Units:Self-contained HEPA-negative-pressure enclosures mounted on casters for multi-site deployment. Demand concentrates among U.S. construction contractors facing OSHA silica enforcement in stone fabrication and concrete cutting operations.
- Fixed Stations:Permanent bench-mounted configurations with ducted exhaust integration. Metalworking shops in Germany's automotive supplier clusters favor these for dedicated grinding and finishing lines where equipment mobility adds no operational value.
- Integrated Systems:Cleanroom-embedded infrastructure with building management system connectivity. Semiconductor fabs in Taiwan and South Korea specify these for Class 1000-compliant process zones where particle control interfaces directly with facility-wide environmental monitoring.
- Custom Solutions:Application-engineered configurations for gene therapy viral vector production and solid-state battery dry room assembly. North American biomanufacturing clusters and Korean battery producers drive specification complexity as standard designs fail containment requirements.
Integrated systems anchor the volume base while custom solutions gain share at the steepest rate.
Application:
Cost tier separation runs deepest here, with semiconductor manufacturing commanding 5-8x per-station investment versus construction site deployment.
- Manufacturing:Electronics contract assembly and pharmaceutical compounding operations requiring ISO 14644-1 compliance. China's eastern coastal provinces—Jiangsu, Guangdong, Zhejiang—absorb the heaviest procurement volume as contract manufacturers build Class 1000 environments for export-bound production.
- Construction:Silica-generating activities in stone countertop fabrication and concrete surface preparation. U.S. OSHA enforcement drives replacement of open-bench grinding stations across Texas and California metalworking clusters.
- Automotive:Composite machining and battery cell assembly lines. German and Japanese OEM suppliers lease equipment-as-a-service configurations with bundled filter maintenance to transfer obsolescence risk.
- Healthcare:Hospital pharmacy compounding and pathology laboratory specimen handling. FDA oversight of sterile compounding drives HEPA-negative-pressure requirements for hazardous drug manipulation.
Manufacturing commands the revenue concentration while construction shows the most rapid expansion trajectory.
End User:
Customer type determines procurement authority location—facility engineering managers versus corporate sustainability officers—and shapes contract structure preferences.
- Contractors:Small and mid-size construction operators prioritizing deployment flexibility across multiple job sites. Equipment-as-a-service penetration remains lowest here due to capital purchase habits and irregular utilization patterns.
- Industrial Plants:Permanent manufacturing facilities with dedicated contamination control zones. These users drive demand for real-time particle monitoring integration and predictive maintenance contracts.
- Laboratories:Pharmaceutical quality control and research environments requiring documented chain-of-custody for hazardous filter disposal. REACH mandates in EU member states accelerate specification of disposal-integrated service agreements.
- Workshops:Independent metal fabricators and maker spaces with limited capital budgets. India's PLI scheme for electronics manufacturing is expanding this category into Karnataka and Tamil Nadu as contract manufacturers build supplier ecosystems.
Industrial plants dominate absolute unit demand while laboratories expand most quickly.
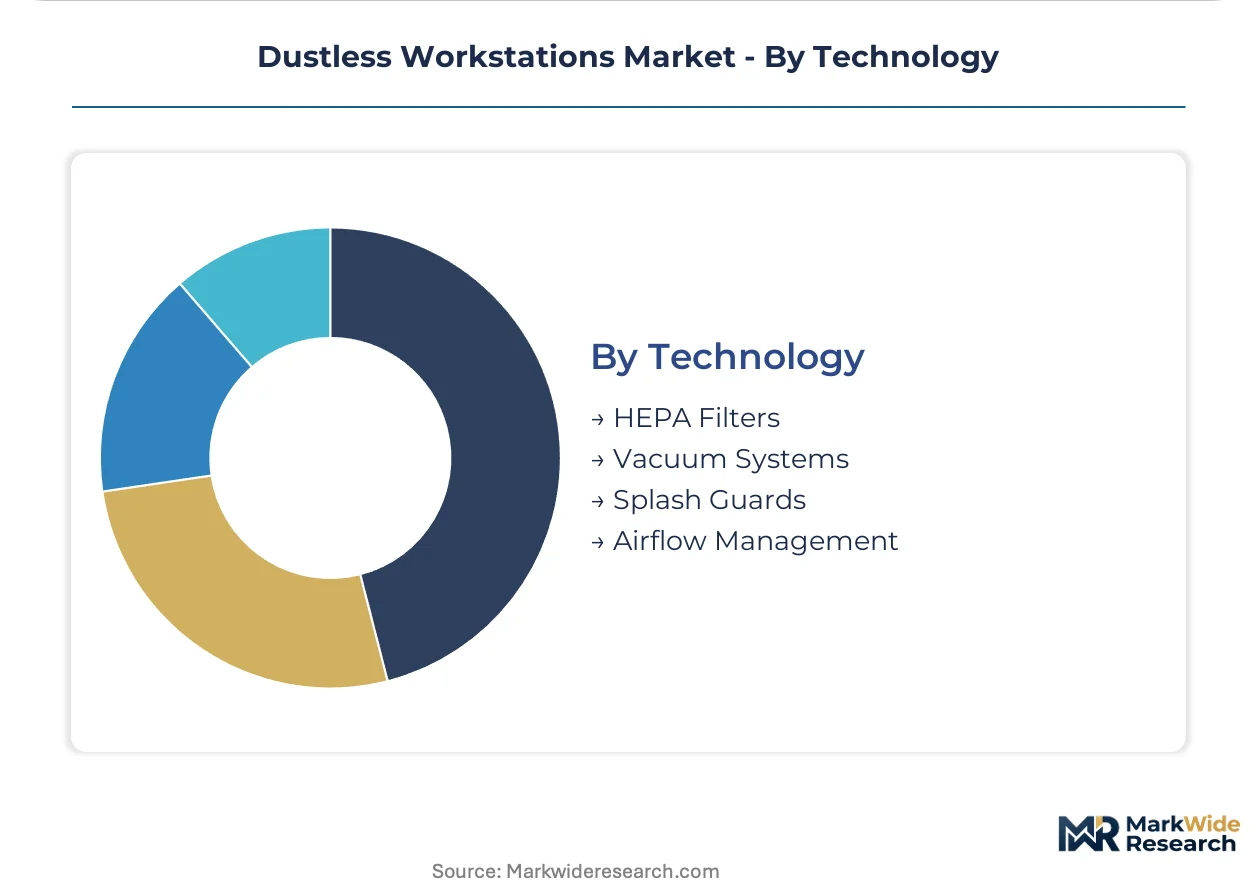
Technology:
Supply concentration for core components—German and Japanese vacuum blowers, glass microfiber media—creates margin pressure differentiation across technology tiers.
- HEPA Filters:Multi-stage filtration cascades achieving 99.97% efficiency at 0.3 micron particle size. Petrochemical feedstock price volatility for glass microfiber and PTFE membranes compresses margin on replacement consumables.
- Vacuum Systems:Negative-pressure blowers and capture hoods directing particulate away from operator breathing zones. German and Japanese component manufacturers control availability, creating procurement bottlenecks during capacity expansion cycles.
- Splash Guards:Physical containment barriers for liquid and semi-solid material handling. Pharmaceutical applications in North America and Europe drive specification for rapid-decontamination surface materials.
- Airflow Management:Active algorithms maintaining laminar flow patterns across variable load conditions. BenchVent proprietary systems and ultrasonic filter loading sensors represent the leading edge of predictive maintenance integration.
HEPA filters anchor the replacement revenue base while airflow management gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented electronics manufacturing concentrates procurement in East Asian fabrication clusters, while import-dependent markets in North America and Europe prioritize regulatory compliance retrofits over greenfield capacity. The regional landscape divides between high-volume assembly zones and enforcement-driven replacement markets.
United States
OSHA silica enforcement drives replacement of open-bench grinding stations across Texas and California metalworking clusters. EPA hazardous air pollutant oversight tightens disposal protocols for saturated HEPA filters from composite machining operations. Stone countertop fabricators in Dallas-Fort Worth and Los Angeles Basin absorb the heaviest compliance cost escalation.
China
Electronics contract manufacturers in Jiangsu, Guangdong, and Zhejiang provinces build Class 1000-compliant assembly environments for export-bound production. MIIT industrial upgrading directives accelerate domestic cleanroom equipment specification. Suzhou and Shenzhen industrial parks concentrate the fastest greenfield workstation deployment.
Germany
Automotive supplier clusters in Bavaria and Baden-Württemberg lease equipment-as-a-service configurations with bundled filter maintenance. REACH mandates accelerate disposal-integrated service agreements for pharmaceutical manufacturing. Stuttgart and Munich anchor premium-tier procurement for composite machining lines.
South Korea
Semiconductor fabs in Pyeongtaek and Hsinchu-adjacent Korean operations expand Class 1000 infrastructure for sub-3nm production nodes. MFDS pharmaceutical oversight drives containment specifications for biologics manufacturing. Battery cell producers in Ulsan require ultra-low humidity configurations for solid-state assembly lines.
India
PLI scheme incentives attract electronics contract manufacturers to Karnataka and Tamil Nadu greenfield facilities. BIS standards adoption lags behind ISO 14644 compliance requirements for export certification. Bengaluru and Chennai industrial corridors concentrate emerging demand from automotive and medical device suppliers.
Dustless Workstations Market Competitive Landscape
On the supply side, the industry is structured around three tiers: multinational filtration specialists with captive component manufacturing, regional fabricators serving construction and workshop segments, and application-engineering boutiques for pharmaceutical and battery cell containment. Strategic differentiation concentrates in airflow algorithm development, modular cabinet architectures, and service-contract bundling. Capacity expansion and backward integration into vacuum blower supply represent the dominant competitive moves.
Within the multinational tier, Graco Inc. and Air Science Technologies Ltd exemplify divergent positioning strategies. Graco anchors its market presence through in-house production of vacuum blower components, securing supply chain control during expansion cycles. Air Science Technologies Ltd occupies a position emphasizing modular cabinet architectures that accommodate rapid reconfiguration between pharmaceutical and electronics applications. Among specialized engineering boutiques, BenchVent represents the algorithm-centric archetype, with proprietary airflow management systems sustaining capture efficiency across variable load conditions.
| Leading Market Players |
|---|
| NARKsafe™ |
| BenchVent |
| Air Science® Technologies Ltd |
| Graco Inc. |
| MMLJ Inc. |
| EcoQuip |
| Clemco Industries Corp. |
| Torbo Engineering Keizers GmbH |
| Dustless Tools |
| Others |
Value Network & Pricing Analysis
German and Japanese vacuum blower manufacturers control critical component availability, concentrating upstream margin capture while downstream equipment assemblers face procurement bottlenecks during capacity expansion cycles. This supply concentration shapes pricing power distribution across the dustless workstations value chain, with captive component producers commanding premium positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pricing stratifies by certification grade—ISO 14644-1 compliance commands substantial premiums over OSHA-basic configurations—and by after-sales service bundling including predictive maintenance contracts. Cost compression in the economy tier is intensifying because petrochemical feedstock volatility for glass microfiber media compresses replacement filter margins. Contractors show highest price sensitivity due to irregular utilization patterns, while semiconductor fabs demonstrate lowest sensitivity given capital planning horizons spanning decades.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for filtration media and electronic control modules. Manufacturing concentration in Germany, Japan, and South Korea for vacuum blowers and precision airflow sensors creates single-source vulnerability during regional capacity constraints. The value chain draws from glass microfiber, PTFE membranes, and specialized aluminum extrusions as core inputs. Distribution runs through direct OEM sales for integrated systems and industrial distribution networks for portable contractor units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent capable of integrating real-time particle monitoring with predictive maintenance algorithms represents the scarcest capability in this market, separating premium-tier suppliers from commodity assemblers. The gap between algorithm-driven airflow management and static HEPA configurations defines competitive durability.
For Market Incumbents: Harden supply chain resilience through backward integration into vacuum blower manufacturing, mirroring Graco Inc.'s captive component strategy. Deepen certification investment in ATEX and ISO 14644-1 compliance to defend against emerging regional fabricators undercutting on price. Prioritize algorithm R&D to sustain capture efficiency advantages as ultrasonic filter loading sensors commoditize scheduled replacement intervals.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-driven electronics manufacturing corridor, where localized dustless workstation supply remains underdeveloped in Karnataka and Tamil Nadu greenfield facilities. Target battery cell dry room applications for solid-state and sodium-ion production, where ultra-low humidity containment configurations exceed standard product portfolios. Pursue equipment-as-a-service contracting to bypass capital purchase resistance among mid-size contract manufacturers.
For Investors and Strategic Acquirers: Capital is best deployed toward application-engineering boutiques possessing gene therapy viral vector containment expertise, as North American biomanufacturing clusters displace standard pharmaceutical designs. Long-term viability hinges on recurring revenue streams from predictive maintenance contracts rather than transactional equipment sales. Watch for ISO 14644-1 compliance testing capacity expansion as the inflection signal for facility commissioning velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Blower Manufacturing | Graco Inc.'s captive supply strategy eliminates German and Japanese component bottlenecks during expansion cycles. |
| Real-Time Particle Monitoring Integration | BenchVent's proprietary airflow algorithms enable predictive maintenance contracts with semiconductor fabs in Hsinchu. |
| Modular Cabinet Architecture Development | Air Science Technologies Ltd's rapid reconfiguration capability bridges pharmaceutical and electronics applications. |
| Equipment-as-a-Service Contracting | German automotive suppliers now lease configurations with bundled filter maintenance, transferring obsolescence risk. |
| ATEX Certification Investment | Battery cell assembly applications require dual compliance pathways that extend validation timelines for unprepared entrants. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cleanroom facility managers, pharmaceutical manufacturing engineers, semiconductor fab operations directors, and industrial distribution channel partners. Secondary validation drew from OSHA enforcement records, EPA hazardous air pollutant filings, ISO 14644-1 compliance testing databases, and SEC 10-K disclosures from listed filtration equipment manufacturers. Bottom-up unit demand estimates were triangulated against top-down capital expenditure projections across the analysis window.
Calibration against historical replacement cycles and regulatory enforcement timelines anchored the analytical framework. Segmentation dimensions modeled include product configuration type, application environment, end-user procurement authority, and technology tier. CAGRs were derived from fitted growth curves incorporating semiconductor node advancement schedules and OSHA silica exposure limit phase-in periods. Forecast inputs included cleanroom infrastructure expansion pipelines and filter media cost indices.
Stress conditions across petrochemical feedstock volatility, vacuum blower supply concentration, and ISO 14644-1 testing capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and capital expenditure timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Global Vacuum Furnaces Market