
 Europe Fans and Blowers Market | 2026-2036
Europe Fans and Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fans and Blowers Market Foresight
Permanent magnet motor integration is tilting European fan architecture toward higher efficiency tiers. ebm-papst Group leverages its Stuttgart engineering base to dominate EC motor supply for compact ventilation. FläktGroup Holding GmbH anchors large-scale HVAC projects through its Nordic manufacturing network. Systemair AB extends its reach across modular ventilation systems for commercial builds.
Fans and blowers are turbomachinery devices that generate airflow through rotational impeller action, with centrifugal designs producing pressures up to 250 mbar and axial configurations optimizing volume flow rates above 100,000 m³/h for cooling and exhaust duties. Centrifugal fans lead the product mix due to their pressure capability in industrial ducting, while variable frequency drive technology commands premium positioning as facilities prioritize load-matched energy consumption over fixed-speed operation.
The EU Ecodesign Directive and Ecodesign for Energy-related Products framework mandate minimum efficiency index thresholds that disqualify conventional AC induction motors from new installations. CE marking under the Machinery Directive enforces safety and electromagnetic compatibility standards that shape product development cycles. Stakeholders must monitor how the EU Green Deal's building renovation wave redirects procurement budgets toward heat recovery ventilation and demand-controlled systems.
Market Dynamics
Electronically commutated motor technology is compressing the installed base of AC induction units across European industrial and commercial facilities, rewiring procurement criteria toward lifetime energy cost rather than upfront capital expenditure.
Growth Catalysts
- HVAC Retrofit Mandates:Germany's building renovation wave and France's thermal regulation RT2012 are accelerating replacement cycles in aging commercial stock. Facility managers now prioritize heat recovery ventilation with demand-controlled airflow.
- EU Ecodesign Directive:Minimum efficiency index thresholds for fans between 125W and 500kW are disqualifying conventional motor architectures from new installations. Manufacturers must redesign impeller geometries and motor windings to comply.
- Automotive Electrification:Battery gigafactories across Poland, Hungary, and Germany require precision ventilation for dry room environments and electrode coating lines. This application segment demands ISO 14644 compliant air handling units.
Market Restraints
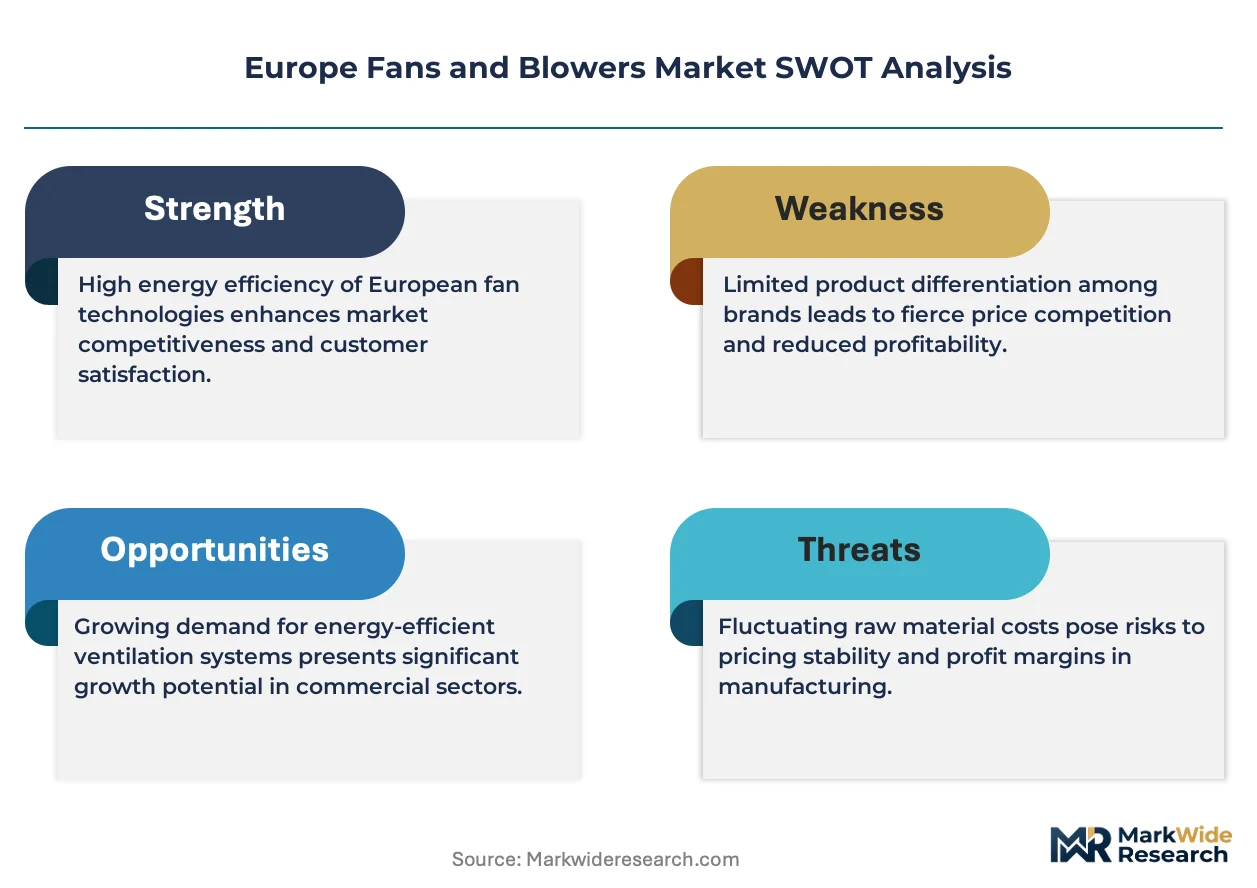
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium for permanent magnet motors concentrate in Chinese refining capacity. European motor assemblers face price volatility and strategic supply risk.
- Copper and Aluminum Input Costs:Winding materials constitute 15-25% of motor BOM cost. LME price swings compress margin predictability for tier-two manufacturers without forward hedging programs.
- Technical Limitation in High-Temperature Applications:EC motor electronics degrade above 60°C ambient. Steel mills, cement kilns, and foundries continue specifying conventional AC drives with external VFDs.
Strategic Opportunities
- Underpenetrated Nordic Markets:Sweden and Finland maintain substantial installed base of 1990s-era ventilation in pulp and paper facilities. Energy service companies are structuring performance contracting for deep retrofit.
- Data Center Liquid Cooling Convergence:Immersion and direct-to-chip cooling architectures require high-pressure blowers for dielectric fluid circulation. This emerging specification sits outside traditional HVAC vendor competence.
- EU Green Deal Building Renovation Wave:The 2024 recast Energy Performance of Buildings Directive mandates zero-emission standards for new public construction. Member states must deploy heat pumps with integrated ventilation by 2028.
Industry Challenges
- Electronics-HVAC Skill Convergence:EC motor commissioning requires technicians fluent in both power electronics and airflow balancing. Vocational training programs across Italy and Spain lag this interdisciplinary requirement.
- CE Marking Timeline Compression:The Machinery Directive's electromagnetic compatibility testing and notified body review now extends 14-18 months. Product development cycles must front-load certification risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fans and Blowers Market |
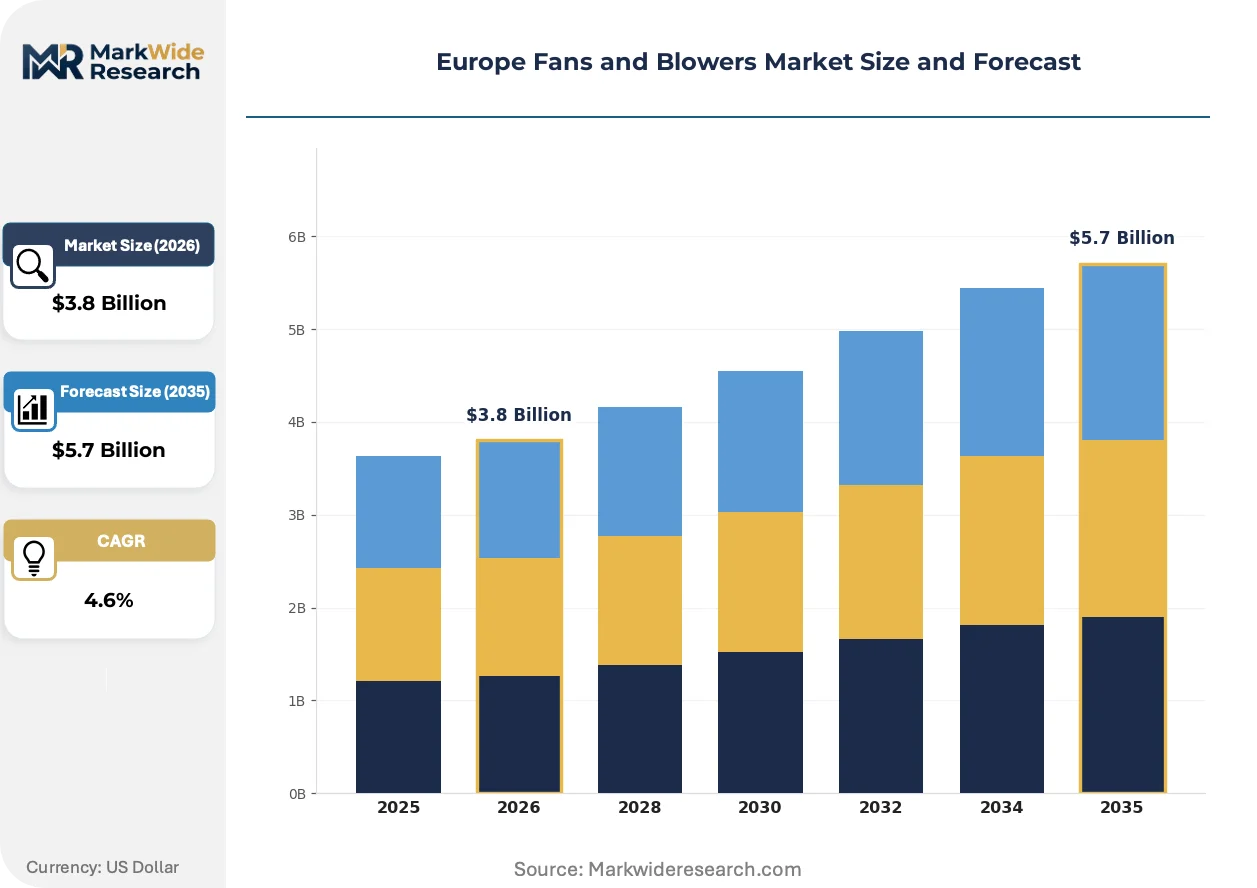
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
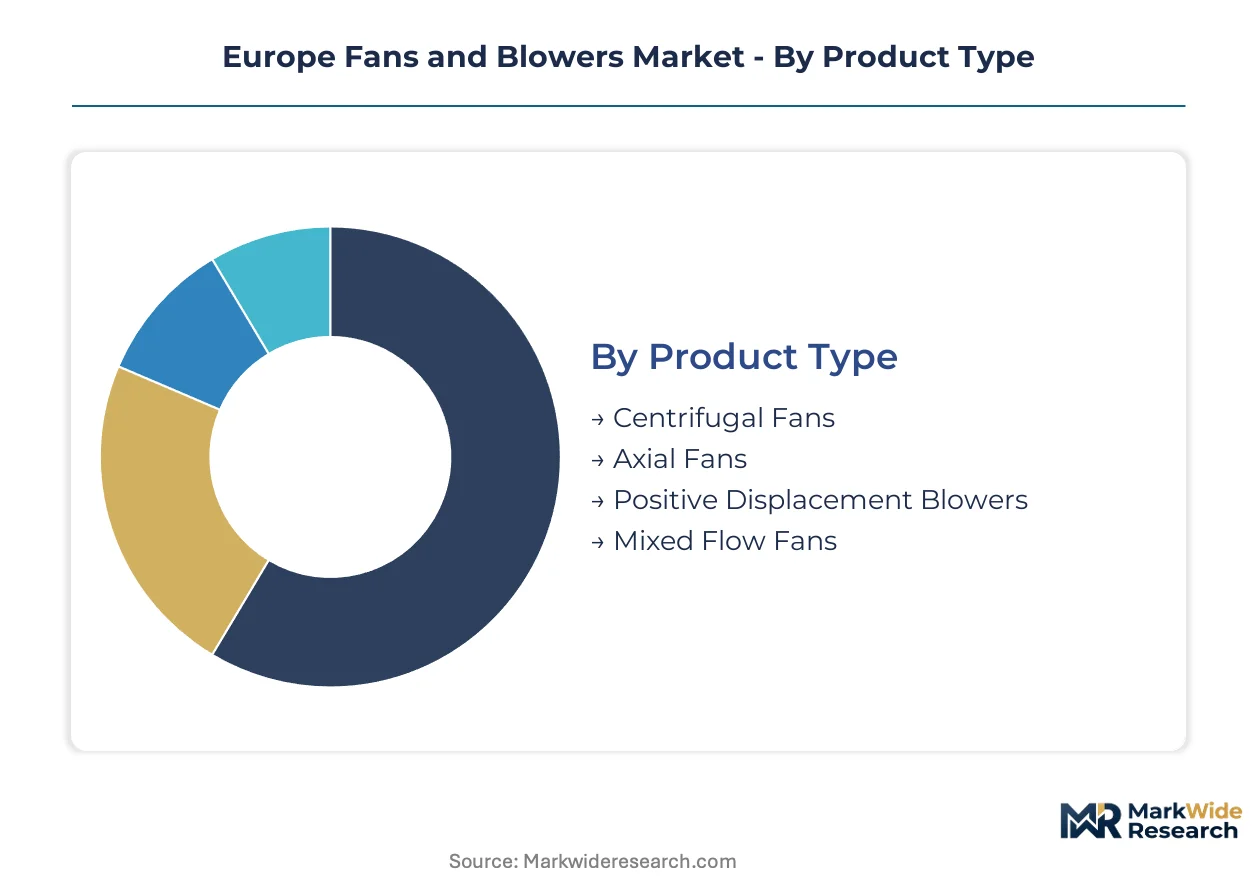
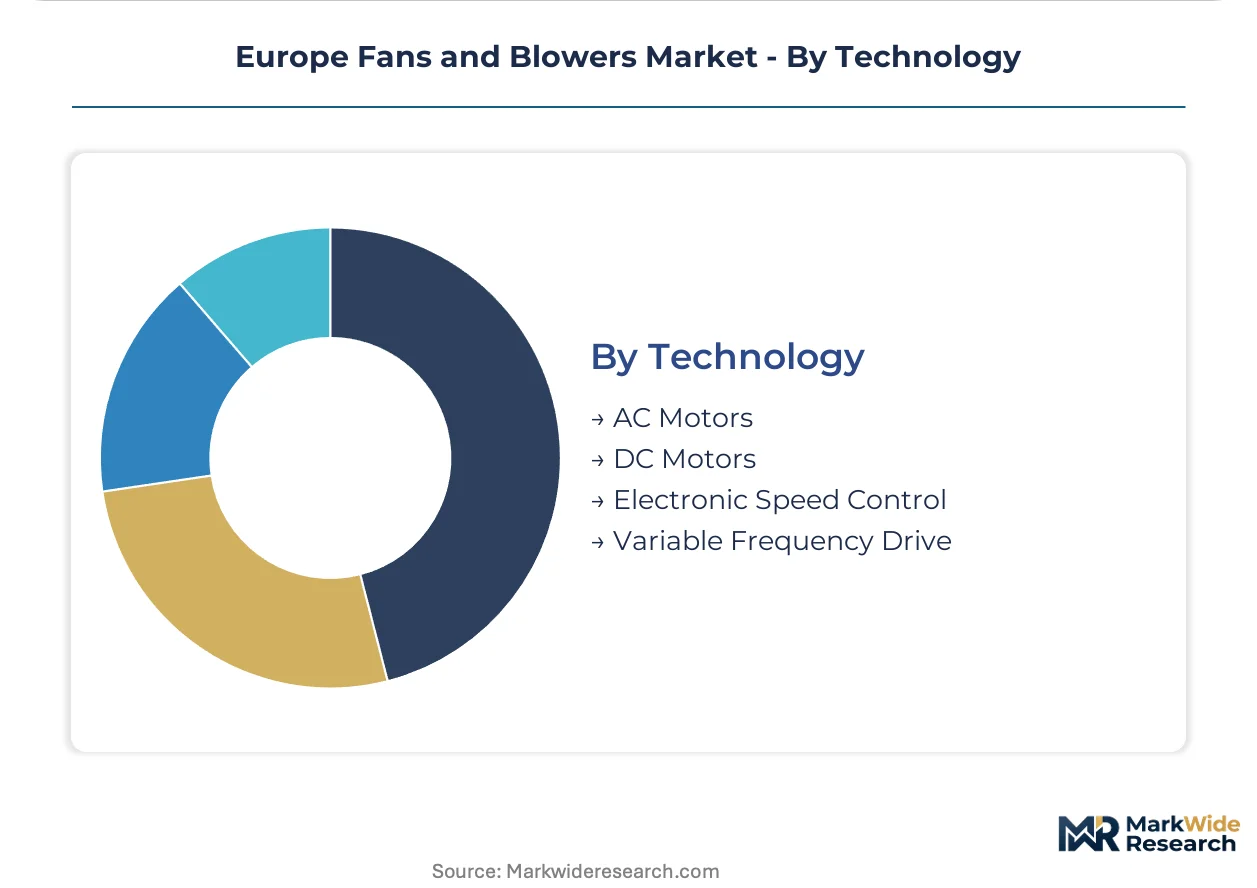
| Segmentation | Product Type: Centrifugal Fans, Axial Fans, Positive Displacement Blowers, Mixed Flow Fans Application: HVAC, Industrial Processes, Ventilation, Material Handling End User: Manufacturing, Hospitality, Residential, Automotive Technology: AC Motors, DC Motors, Electronic Speed Control, Variable Frequency Drive |
| Companies Covered | Trane Technologies plc, ebm-papst Group, Howden Group Ltd, FläktGroup Holding GmbH, Systemair AB, Greenheck Fan Corp, Halifax Fan Ltd, Continental Blower LLC, Air Control Industries Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fans and Blowers Market Shifts & Advancements
Digital twin integration and predictive maintenance algorithms are rewiring how European facilities specify, operate, and service air movement equipment. The vendor value proposition is migrating from hardware supply to guaranteed performance outcomes.
Magnet-assisted synchronous reluctance motor technology is migrating from premium HVAC toward mid-range industrial fan applications. Food processing plants in the Netherlands and pharmaceutical cleanrooms in Ireland are specifying these motors to eliminate rare earth dependency. The technology is migrating from niche positioning to mainstream specification as magnet price volatility persists.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of bearing lubricants and fan blade coatings. The restriction on PFAS-containing substances takes full effect in 2025, compelling manufacturers to validate fluorine-free alternatives for chemical resistance and UV stability. Coatings suppliers in Germany and Belgium are accelerating qualification programs to maintain CE marking continuity.
Facility operators are unbundling maintenance contracts from initial equipment procurement, compressing the traditional ten-year service bundling model. German automotive suppliers and French hospital networks now tender ventilation maintenance separately through multi-vendor framework agreements. This purchasing pattern is most visible in the Rhine-Ruhr industrial corridor and the Île-de-France healthcare cluster.
Europe Fans and Blowers Market Segmentation
European fan and blower procurement cycles vary dramatically by segment—HVAC retrofits turn over every 15-20 years while automotive production lines refresh equipment every 5-7 years. Understanding these replacement rhythms shapes inventory planning and service contract structuring across the value chain.
Product Type:
Centrifugal designs carry the longest installed base lifecycles, often exceeding two decades in industrial ducting, while axial configurations in data center cooling see accelerated refresh rates driven by thermal density upgrades.
- Centrifugal Fans:These impeller-based systems generate static pressures up to 250 mbar through radial airflow acceleration, making them essential for ducted industrial ventilation. Demand concentrates in Germany's automotive manufacturing corridor where paint booths and foundry exhaust require pressure-capable air movement.
- Axial Fans:Optimized for volume flow rates above 100,000 m³/h with minimal pressure development, these units dominate cooling tower and heat exchanger applications. France's nuclear power maintenance programs and the Netherlands' greenhouse agriculture sector specify high-efficiency axial designs for continuous operation.
- Positive Displacement Blowers:Roots-type and screw compressors deliver pulsation-free airflow for pneumatic conveying and wastewater aeration.
- Mixed Flow Fans:Combining axial throughput with centrifugal pressure characteristics, these units serve tunnel ventilation and subway systems.
Centrifugal fans dominate installed base across European heavy industry. Mixed flow configurations are where expansion concentrates as infrastructure resilience programs accelerate.
Application:
Margin structures diverge sharply across application categories—industrial process ventilation commands engineering-intensive pricing while standardized HVAC contracts compete on procurement efficiency.
- HVAC:Building climate control systems integrate fans with heat recovery and demand-controlled ventilation. The EU Energy Performance of Buildings Directive recast mandates zero-emission standards for new public construction, redirecting procurement toward integrated heat pump-ventilation systems.
- Industrial Processes:High-temperature exhaust, corrosive gas handling, and cleanroom environments require application-specific metallurgy and coatings. Battery gigafactories in Poland and Hungary specify ISO 14644 compliant air handling for dry room environments.
- Ventilation:General exhaust and fresh air supply systems serve commercial and institutional buildings.
- Material Handling:Pneumatic conveying and bulk transport applications demand abrasion-resistant impeller designs.
HVAC commands the largest addressable volume. Industrial process applications are climbing the fastest as electrification manufacturing capacity expands.
End User:
Customer sophistication ranges from residential price sensitivity to automotive specification rigor, fragmenting go-to-market approaches across the supplier base.
- Manufacturing:Automotive, steel, cement, and food processing facilities require continuous-duty ventilation with predictive maintenance integration. Germany's Rhine-Ruhr industrial cluster and northern Italy's manufacturing belt specify digitally enabled fan systems with vibration monitoring.
- Hospitality:Hotels and restaurants prioritize acoustic performance and energy efficiency certifications. France's thermal regulation RT2012 mandates heat recovery ventilation in new commercial construction.
- Residential:Single-family and multi-unit buildings specify compact, low-cost ventilation units.
- Automotive:OEM production lines and battery manufacturing require precision environmental control.
Manufacturing anchors the premium segment. Automotive is gaining share fastest as battery supply chain localization accelerates.
Technology:
Technology substitution timelines define competitive windows—EC motor retrofits displace AC induction over 10-15 year cycles while VFD upgrades occur within 3-5 year capital planning horizons.
- AC Motors:Conventional induction motors persist in high-temperature applications above 60°C ambient where EC electronics degrade. Steel mills in Belgium and cement kilns in Spain continue specifying AC drives with external variable frequency controls.
- DC Motors:Brushed and brushless DC architectures serve battery-powered and mobile equipment applications.
- Electronic Speed Control:EC motor integration with onboard power electronics enables part-load efficiency optimization.
- Variable Frequency Drive:External VFDs retrofit existing fixed-speed installations with demand-matched energy consumption.
AC motors retain substantial installed base in thermal-intensive processes. Electronic speed control is expanding most quickly as the EU Ecodesign Directive disqualifies conventional architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered EC motor fans to automotive production lines across Poland and Hungary, creating a trade corridor that channels technical standards eastward while pulling rare earth magnet supply risk westward.
Germany
Automotive electrification and battery gigafactory construction dominate demand in the Rhine-Ruhr industrial corridor and Baden-Württemberg manufacturing belt. The EU Ecodesign Directive's minimum efficiency index thresholds are disqualifying conventional AC induction motors from new installations. Stuttgart anchors EC motor engineering clusters where ebm-papst Group concentrates advanced ventilation R&D.
France
Commercial building renovation and nuclear power maintenance programs drive replacement cycles for heat recovery ventilation systems. The thermal regulation RT2012 mandates energy recovery in new construction, redirecting procurement toward demand-controlled airflow. The Île-de-France healthcare cluster and Auvergne-Rhône-Alpes industrial belt specify ISO-compliant air handling for hospital networks and pharmaceutical cleanrooms.
Poland
Battery manufacturing capacity expansion and automotive supply chain localization accelerate precision ventilation demand for dry room environments. The EU Green Deal building renovation wave channels funding toward heat pump-integrated systems in municipal construction. The Silesian manufacturing zone and Warsaw metropolitan area concentrate gigafactory investments requiring electrode coating line ventilation.
Netherlands
Greenhouse agriculture and food processing facilities prioritize continuous-duty axial fans for climate control and exhaust applications. REACH authorization requirements for PFAS substances are forcing bearing lubricant reformulation across installed equipment. The Rotterdam port industrial complex and Eindhoven high-tech corridor specify magnet-assisted synchronous reluctance motors to eliminate rare earth dependency.
Sweden
Pulp and paper facility retrofits and data center thermal management reshape procurement toward digitally enabled fan systems. The recast Energy Performance of Buildings Directive mandates zero-emission standards for new public construction by 2028. The Stockholm metropolitan region and Gothenburg industrial zone anchor energy service company performance contracting for deep ventilation retrofits.
Europe Fans and Blowers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement channels. The vendor base stratifies between full-system HVAC integrators and component-focused motor suppliers. Three archetypes dominate: Stuttgart-engineered EC motor specialists, Nordic-networked large-scale project anchors, and modular ventilation system extenders. Competitive moves concentrate on geographic expansion into battery manufacturing corridors and technology licensing for rare earth-free motor architectures.
Among Germany-based engineering specialists, ebm-papst Group and FläktGroup Holding GmbH occupy positions at opposite ends of the product complexity spectrum, with the former exemplifying compact motor integration and the latter anchoring industrial-scale air handling. Systemair AB represents the modular system archetype, extending configurable ventilation platforms across commercial construction segments. These three entities illustrate how European competitive positioning fragments between component-level efficiency leadership and integrated system project execution.
| Leading Market Players |
|---|
| Trane Technologies plc |
| ebm-papst Group |
| Howden Group Ltd |
| FläktGroup Holding GmbH |
| Systemair AB |
| Greenheck Fan Corp |
| Halifax Fan Ltd |
| Continental Blower LLC |
| Air Control Industries Ltd |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp freight corridor channels winding materials and rare earth magnets into Stuttgart engineering clusters, with container cost volatility transmitting directly into tier-two manufacturer margins and amplifying price spreads between premium EC motor systems and conventional AC units.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement between motor assemblers and winding material suppliers. Pricing stratifies across premium certified systems, standard efficiency tiers, and economy AC induction units based on CE marking tier and volume scale commitments. Cost compression in the economy tier is intensifying because Chinese rare earth export quotas constrain permanent magnet supply. Residential HVAC contractors exhibit the highest price sensitivity, while automotive battery manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Export-control restrictions on rare earth processing technology limit European access to neodymium and dysprosium refining capacity concentrated in China. Motor manufacturing draws from Chinese magnet supply, German precision engineering, and Polish assembly operations. Single-source vulnerability in rare earth refining creates structural supply risk. Distribution runs through OEM direct procurement for automotive applications and HVAC wholesaler networks for commercial building stock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEM procurement teams and framework-contracting facility managers, fragmenting the traditional ten-year bundled service model across the Rhine-Ruhr and Île-de-France clusters.
For Market Incumbents: Pre-empt rare earth-free motor technology licensing by acquiring magnet-assisted synchronous reluctance engineering capabilities before REACH PFAS restrictions eliminate conventional bearing lubricants. Anchor backward integration into copper winding supply through Polish manufacturing partnerships to defend margin position against LME volatility. Prioritize CE marking front-loading to compress 14-18 month certification timelines. For New Entrants and Emerging Players: Nordic pulp and paper facility retrofits in Sweden and Finland offer the most penetrable white-space, with energy service companies structuring performance contracting for 1990s-era ventilation replacement. Data center liquid cooling blower specifications sit outside incumbent HVAC competence, creating entry opportunity through high-pressure dielectric fluid circulation engineering. Target direct engagement with hyperscaler procurement teams bypassing traditional channel structures. For Investors and Strategic Acquirers: Component-specialist EC motor engineering boutiques with Stuttgart-region R&D clusters represent the priority acquisition archetype for technology consolidation plays. Long-term viability hinges on rare earth dependency elimination and software-enabled predictive maintenance integration. Monitor EU Green Deal building renovation wave funding disbursement velocity as inflection indicator for heat recovery ventilation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth-Free Motor Technology Licensing | Eliminates Chinese magnet supply risk while satisfying EU Ecodesign Directive efficiency thresholds. |
| CE Marking Front-Loading | Compresses Machinery Directive electromagnetic compatibility review cycles ahead of competitor product launches. |
| Energy Service Company Partnership | Captures Nordic pulp and paper retrofit demand through performance contracting rather than capital sale. |
| Data Center Liquid Cooling Engineering | Addresses hyperscaler thermal density requirements outside traditional HVAC vendor capability. |
| Polish Manufacturing Footprint Expansion | Positions assembly capacity adjacent to battery gigafactory demand in Silesia and Warsaw. |
Research Methodology
A spread of perspectives from plant engineers at automotive battery facilities, HVAC procurement managers in German hospital networks, energy service company contract specialists, and CE marking notified body reviewers converged on the working assumptions. Primary fieldwork combined with secondary validation against EU Ecodesign Directive regulatory filings, Machinery Directive technical documentation, and customs trade data for winding material flows. Bottom-up installation base modeling and top-down energy efficiency policy impact assessment provided triangulation.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across product type, application, end user, and technology dimensions. CAGRs derived from replacement cycle analysis, retrofit mandate timelines, and automotive electrification capacity buildouts. Industry-specific inputs included EU Green Deal building renovation wave funding trajectories and REACH PFAS restriction implementation schedules.
Practitioners should monitor rare earth export quota announcements, LME copper price volatility, and notified body certification backlog extensions for early signals of forecast deviation. Material shifts in EU Ecodesign Directive enforcement intensity or battery gigafactory construction delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Glass Engraving Machines Market
Industrial Equipment
Air Bearings Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Contour Measuring Machines Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Digital Servo Press Market