
 Electrode Slag Remelting (ESR) Furnace Market | 2026-2036
Electrode Slag Remelting (ESR) Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
Electrode Slag Remelting (ESR) Furnace Market Insights
Superalloy compositions incorporating higher rhenium and ruthenium content is realigning ESR furnace specifications across the specialty metals sector. ALD Vacuum Technologies leverages its vacuum metallurgy heritage to dominate high-purity aerospace remelting lines. Consarc Engineering anchors North American supply through its induction skull melting and ESR integration capabilities. INTECO Group differentiates via its Austrian engineering base and continuous remelting system expertise.
An Electrode Slag Remelting furnace consumes direct current to remelt a consumable electrode beneath a molten slag layer, typically operating at temperatures exceeding 1,600°C to refine alloy chemistry and eliminate non-metallic inclusions. The process produces ingots with superior macrostructure uniformity for critical rotating components in jet engines and industrial gas turbines. Vacuum Arc ESR systems command the premium tier due to their dual-melting purification for nickel-based superalloys, while Compact ESR units are gaining traction among specialty alloy producers seeking flexible batch sizes without full-scale infrastructure. Automated Control Systems represent the fastest-growing technology segment as foundries pursue real-time slag chemistry monitoring and electrode feed precision.
FAA airworthiness directives and EASA certification requirements for aerospace grade materials mandate documented remelting traceability, directly shaping ESR furnace procurement specifications across foundries and heavy fabrication units. ISO 9001 and AS9100 quality management frameworks further constrain supplier qualification, filtering equipment vendors by proven installation bases and service networks. Stakeholders must weigh capital deployment timing against evolving superalloy specifications and the accelerating shift toward electrified process controls.
Market Dynamics
Superalloy purity specifications for jet engine rotating components are tightening ESR furnace procurement criteria across aerospace supply chains, forcing foundries toward automated remelting systems with real-time chemistry control.
Growth Catalysts
- FAA Airworthiness Directives:Mandated traceability documentation for aerospace-grade nickel superalloys is accelerating certified ESR furnace deployment across US foundries serving turbine OEMs.
- Industrial Gas Turbine Demand:Power generation sector procurement of large-diameter superalloy ingots is expanding ESR capacity additions for heavy-frame turbine manufacturers.
- German Precision Engineering Clusters:Concentrated specialty steel production around Düsseldorf and Essen is anchoring European ESR furnace installation growth for tool steel and bearing applications.
Market Restraints
- Fluorspar Supply Concentration:China controls approximately 60% of global acid-grade fluorspar used in ESR slag formulations, exposing furnace operators to raw material price volatility and export restriction risks.
- Capital Intensity Barrier:Vacuum Arc ESR systems require 15-25 megawatt electrical infrastructure and specialized building foundations, limiting entry to well-capitalized producers.
- Electrode Quality Dependency:Defects in consumable electrode casting propagate directly into remelted ingots, forcing upstream investment in VAR or plasma cold hearth pre-melting capacity.
Strategic Opportunities
- India Defense Localization:Indigenization mandates under the country's Defense Acquisition Procedure are creating first-mover openings for ESR furnace suppliers to serve aerospace and naval propulsion programs.
- Additive Manufacturing Feedstock:Powder atomization-grade superalloy demand is opening niche ESR furnace configurations optimized for small-diameter, high-chemistry-uniformity ingot production.
- EU Green Deal Alignment:Carbon border adjustment mechanisms and scrap-based steelmaking incentives are favoring ESR remelting over primary extraction for specialty alloy circularity claims.
Industry Challenges
- Metallurgical Technician Scarcity:Retirement of experienced slag chemistry specialists is constraining furnace optimization and defect root-cause analysis capabilities across mature installations.
- AS9100 Certification Timelines:12-18 month qualification periods for aerospace supplier approval are delaying revenue realization for new ESR furnace commissioning projects.
- Legacy Control System Integration:Retrofitting automated electrode feed and slag monitoring onto 1980s-vintage furnace mechanicals requires custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrode Slag Remelting (ESR) Furnace Market |
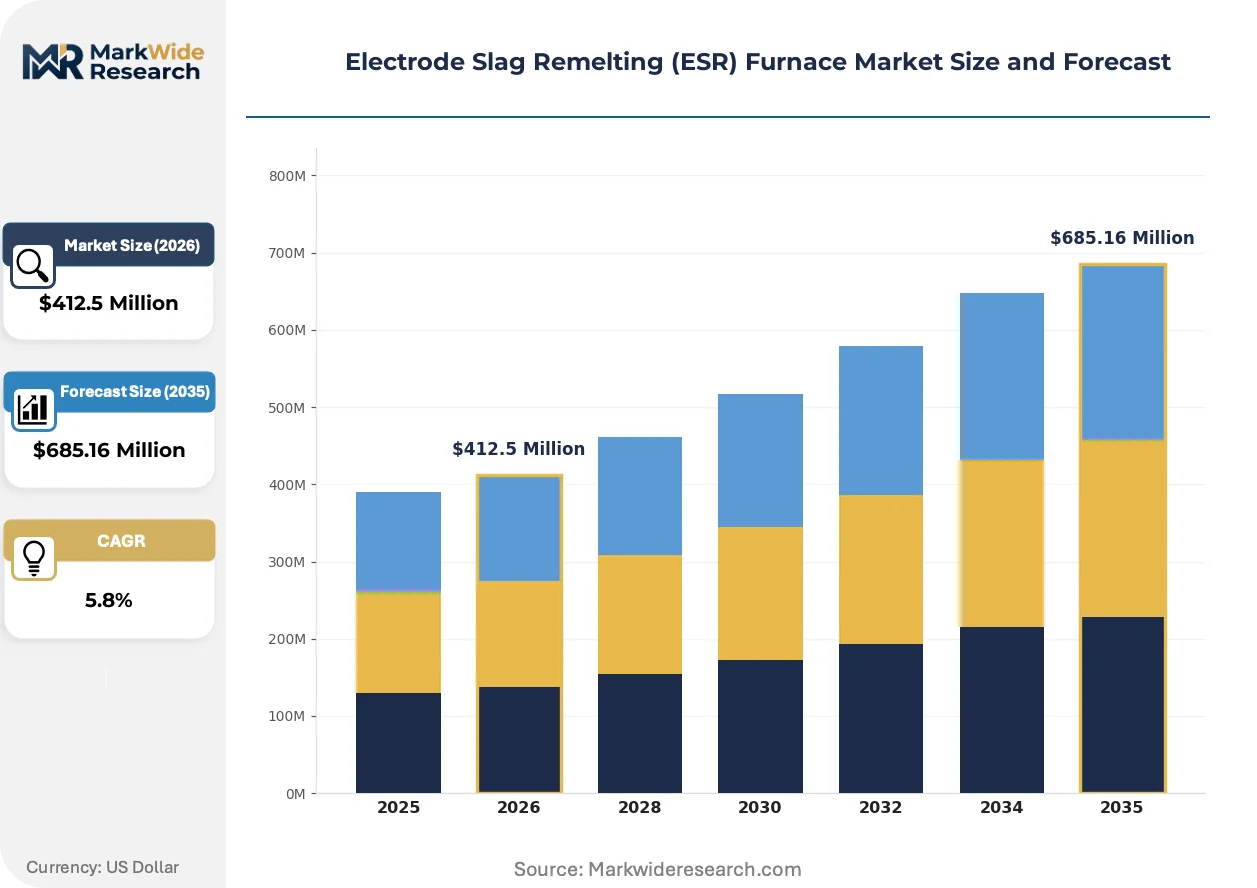
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Arc ESR, High-Frequency ESR, Direct Current ESR, Indirect Current ESR, Compact ESR Technology: Single Electrode, Multiple Electrode, Continuous Remelting, Batch Processing, Automated Control Systems Application: Aerospace Components, Power Generation Equipment, Tool Manufacturing, Industrial Machinery, Marine Engineering End User: Foundries, Heavy Fabrication Units, Specialty Alloy Producers, Metal Recycling Firms, Engineering Workshops |
| Companies Covered | Xinlanhai, LUSHOON, ALD Vacuum Technologies, Consarc Engineering, Suzhou Zhenwu, INTECO Group, Herz, Electroheat Technologies, Inductotherm Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrode Slag Remelting (ESR) Furnace Market Trends and Innovations
Real-time process instrumentation and predictive metallurgy are displacing operator-dependent ESR furnace control, compressing batch-to-batch variation and enabling lights-out remelting operations for high-volume superalloy producers.
Electromagnetic stirring technology is expanding into large-diameter ESR ingot production, where controlled melt pool convection reduces macrosegregation in 800mm+ nickel superalloy castings for industrial gas turbine disks. Siemens Energy and Mitsubishi Heavy Industries are specifying stirred-ESR material for their latest H-class turbine hardware. This capability is expanding into the premium tier of aerospace forging supply, where homogeneous chemistry reduces downstream heat treatment variability.
EASA's evolving certification requirements for engine critical rotating parts are mandating documented slag chemistry stability across entire remelt cycles, forcing furnace operators toward automated flux addition systems and continuous slag sampling. The regulation compresses allowable compositional drift windows by approximately 40% versus prior practice. German and Austrian specialty steel producers are responding fastest, integrating laser-induced breakdown spectroscopy for real-time oxide monitoring.
Power purchase agreements with renewable generators are reshaping ESR furnace operational economics, as 24/7 remelting cycles face carbon accounting pressure from aerospace OEM scope 3 reduction targets. Safran and Rolls-Royce supplier codes now require documented electricity sourcing for certified material. This behavioral shift is most visible in Sweden and Norway, where hydroelectric-backed ESR operations command sourcing preference from European turbine component forgers.
Electrode Slag Remelting (ESR) Furnace Market Segmentation
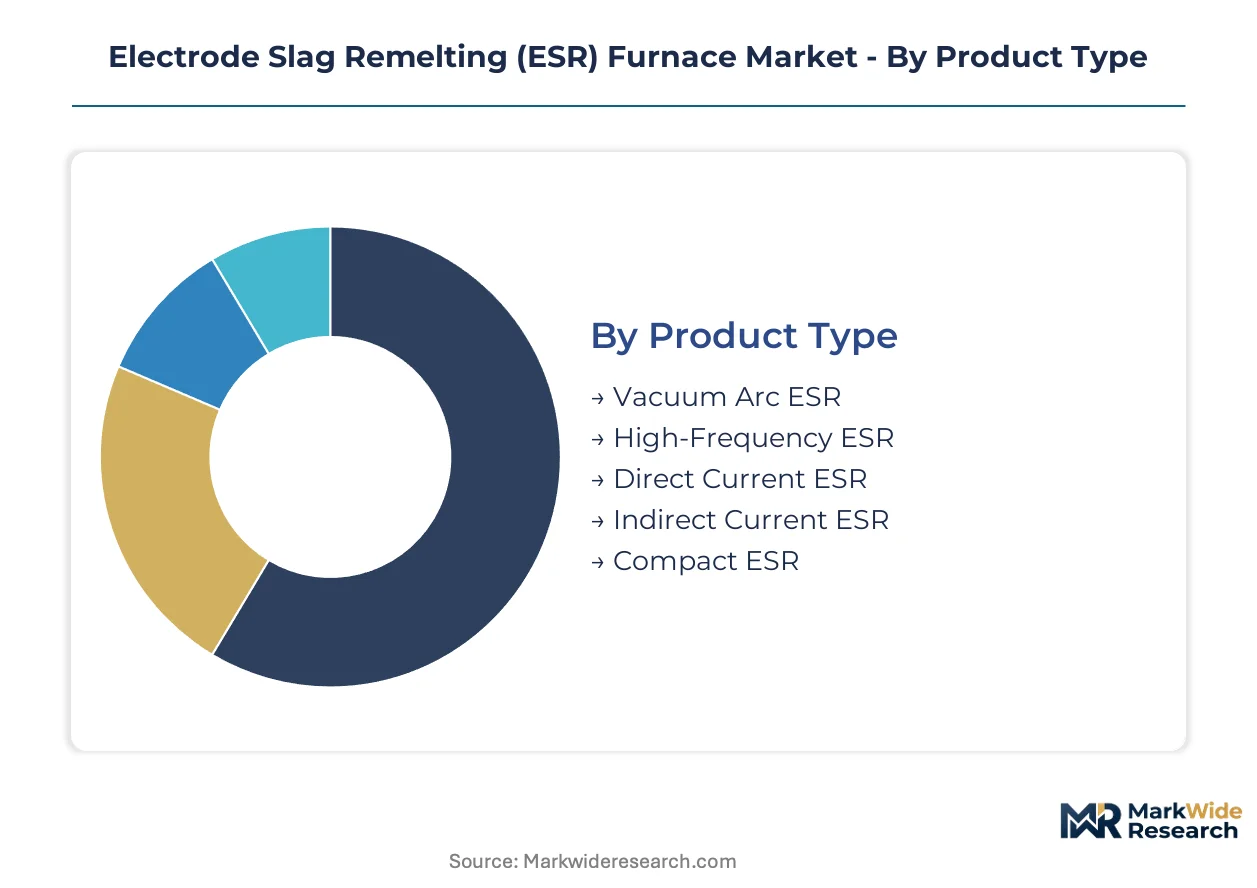
ESR furnace segmentation reveals distinct procurement patterns across melting technologies and end-use requirements. Equipment specifications diverge sharply between aerospace-certified installations and general industrial remelting operations. Understanding these segment boundaries enables targeted positioning against replacement cycles and capacity expansion timelines.
Product Type:
Upgrade cycles across ESR furnace installations track closely with evolving superalloy purity mandates and energy infrastructure constraints. Foundries face discrete decisions between premium vacuum-capable systems and conventional direct current platforms.
- Vacuum Arc ESR:Dual-melting architecture combines slag refining with vacuum arc degassing for nickel-based superalloys. Rolls-Royce and Safran supplier codes mandate this configuration for engine-critical rotating components. Demand concentrates in Germany and Sweden where hydroelectric-backed operations meet carbon accounting requirements from aerospace OEM scope 3 targets.
- Compact ESR:Reduced footprint design enables flexible batch sizes without full-scale infrastructure investment. Specialty alloy producers in India and Brazil deploy these units for defense localization programs and tool steel applications. The format suits engineering workshops seeking entry-level remelting capability.
- High-Frequency ESR:Alternating current excitation at elevated frequencies enables precise melt pool control for small-diameter ingots.
- Direct Current ESR:Conventional polarity configuration dominates established installations for standard bearing and tool steel grades.
- Indirect Current ESR:Modified electrode connection geometry reduces magnetic field interference in sensitive alloy chemistries.
Volume placements concentrate in Direct Current ESR; the faster expansion belongs to Vacuum Arc ESR.
Technology:
Automation intensity separates technology tiers, with capital deployment timing favoring systems that reduce operator dependency and batch-to-batch variation.
- Automated Control Systems:Real-time slag chemistry monitoring and precision electrode feed mechanisms enable lights-out remelting operations. German producers integrate laser-induced breakdown spectroscopy to meet EASA's compressed compositional drift windows. The segment gains share fastest among high-volume superalloy suppliers.
- Continuous Remelting:Non-stop electrode feeding and ingot extraction maximize throughput for standardized grades. Austrian engineering bases anchor European supply of these systems for tool steel and bearing applications. The format suits foundries with steady demand profiles and limited product changeover requirements.
- Single Electrode:Standard consumable electrode configuration serves conventional batch remelting requirements.
- Multiple Electrode:Parallel electrode arrangements accelerate melting rates for large-diameter ingot production.
- Batch Processing:Discrete cycle operation accommodates frequent alloy changes and custom chemistry specifications.
Procurement prioritizes Automated Control Systems for new capacity; Continuous Remelting dominates replacement demand.
Application:
Application segmentation maps directly to certification burden and metallurgical performance requirements, with aerospace specifications filtering equipment choices across supplier tiers.
- Aerospace Components:Jet engine rotating hardware demands documented remelting traceability under FAA airworthiness directives. FAA and EASA certification requirements mandate specific furnace configurations for nickel superalloy production. Siemens Energy and Mitsubishi Heavy Industries specify advanced ESR material for H-class turbine disks.
- Power Generation Equipment:Industrial gas turbine manufacturers procure large-diameter superalloy ingots for heavy-frame hardware. Heavy Fabrication Units in Germany and the US anchor demand for 800mm+ casting capabilities. Electromagnetic stirring integration reduces macrosegregation in these applications.
- Tool Manufacturing:High-speed steel and cold work die applications require consistent carbide distribution through controlled solidification.
- Industrial Machinery:General engineering grades tolerate broader chemistry windows and conventional remelting configurations.
- Marine Engineering:Naval propulsion programs in India drive localized ESR capacity under defense indigenization mandates.
Revenue concentration sits with Aerospace Components; Power Generation Equipment shows the steepest capacity expansion trajectory.
End User:
End user categories reflect vertical integration depth and raw material access, with foundry networks consolidating around certified remelting capacity.
- Foundries:Dedicated remelting operations serve aerospace and power generation supply chains with AS9100-qualified installations. 12-18 month certification timelines filter vendor selection toward established equipment bases. German precision engineering clusters anchor European foundry ESR deployment.
- Specialty Alloy Producers:Integrated producers control electrode quality through captive VAR or plasma cold hearth pre-melting capacity. Fluorspar supply concentration from China exposes these operators to raw material price volatility. EU Green Deal alignment favors ESR remelting over primary extraction for circularity claims.
- Heavy Fabrication Units:Large component manufacturers maintain in-house remelting for proprietary alloy development.
- Metal Recycling Firms:Scrap-based feedstock operations align with carbon border adjustment mechanisms in European markets.
- Engineering Workshops:Small-batch producers serve niche tooling and research applications with compact system configurations.
Foundries represent the largest installed base; Specialty Alloy Producers are expanding capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates ESR furnace demand through precision engineering clusters serving aerospace and specialty steel applications. Regulatory pressure from EASA certification requirements shapes procurement specifications across European foundries. Industrial deployment patterns track closely with superalloy purity mandates and carbon accounting frameworks.
United States
FAA airworthiness directives mandate documented remelting traceability for nickel superalloys used in jet engine rotating components. Defense procurement programs under the Defense Acquisition Procedure accelerate certified ESR furnace deployment across domestic foundries. Heavy fabrication units in Texas and Ohio anchor demand for large-diameter ingot capabilities serving industrial gas turbine manufacturers.
Germany
Specialty steel producers around Düsseldorf and Essen drive European ESR furnace installation growth for tool steel and bearing applications. EU Green Deal alignment favors ESR remelting over primary extraction for circularity claims in carbon border adjustment mechanisms. Precision engineering clusters integrate automated slag chemistry monitoring to meet compressed compositional drift windows from EASA.
India
Defense indigenization mandates under the Defense Acquisition Procedure create first-mover openings for ESR furnace suppliers to aerospace and naval propulsion programs. Bureau of Indian Standards certification requirements shape equipment specifications for domestic foundry networks. Compact ESR units gain traction among engineering workshops in Maharashtra and Gujarat seeking entry-level remelting capability.
Sweden
Hydroelectric-backed ESR operations command sourcing preference from European turbine component forgers pursuing scope 3 reduction targets. Power purchase agreements with renewable generators reshape operational economics for 24/7 remelting cycles. Specialty alloy producers integrate electromagnetic stirring technology for large-diameter nickel superalloy castings.
China
Domestic fluorspar supply concentration exposes furnace operators to raw material price volatility in slag formulations. Ministry of Ecology and Environment regulations on industrial emissions constrain conventional remelting configurations. Regional producers in Jiangsu and Shandong expand vacuum metallurgy capabilities for aerospace-grade material qualification.
Electrode Slag Remelting (ESR) Furnace Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier vacuum systems consolidating around established metallurgy heritage while compact formats fragment among regional fabricators. The vendor base clusters into three archetypes: vacuum technology specialists leveraging dual-melting architectures, induction equipment integrators offering ESR as process-line extensions, and regional engineering firms serving cost-sensitive entry-level demand. Capacity expansion and automated control system licensing represent the dominant competitive moves as foundries pursue lights-out remelting operations.
Within the vacuum technology tier, ALD Vacuum Technologies and INTECO Group occupy positions shaped by European engineering heritage and continuous remelting system expertise respectively. Consarc Engineering anchors North American supply through its induction skull melting integration capabilities. Among Asian fabricators, Suzhou Zhenwu and Xinlanhai represent regional archetypes addressing defense localization and compact system demand across emerging markets.
| Leading Market Players |
|---|
| Xinlanhai |
| LUSHOON |
| ALD Vacuum Technologies |
| Consarc Engineering |
| Suzhou Zhenwu |
| INTECO Group |
| Herz |
| Electroheat Technologies |
| Inductotherm Group |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive electrode production anchors both supply security and pricing power for ESR furnace operators, as foundries that control consumable quality command premiums from aerospace OEMs while insulating margins from VAR pre-melting cost volatility. This structural choice separates certified aerospace suppliers from commodity remelting operations.
Pricing Analysis
High-volume contract placements concentrate in standard DC configurations while margins accrue to vacuum-capable systems with automated chemistry control. Pricing stratifies across aerospace-certified, industrial-grade, and compact entry-level tiers, with certification burden from FAA and EASA directives compressing price elasticity at the premium end. Cost compression in conventional remelting is intensifying because Chinese fluorspar export restrictions are elevating slag formulation expenses. Specialty alloy producers show least price sensitivity due to pass-through mechanisms with turbine OEMs, whereas Indian engineering workshops exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Electrode refurbishment and remanufacturing flows from decommissioned aerospace components are emerging as secondary feedstock channels for specialty alloy circularity claims. Primary supply concentrates in Germany, Austria, and Sweden, where precision engineering clusters and hydroelectric infrastructure anchor European furnace manufacturing. The chain draws from Chinese acid-grade fluorspar, Swedish specialty steel scrap, and German automation components. Single-source vulnerability in fluorspar exposes operators to export license unpredictability from Beijing. Distribution runs through foundry networks with AS9100 certification, bypassing open-market spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ESR furnace supply is structurally constrained by 12-18 month AS9100 certification timelines, a capacity bottleneck that props pricing power for qualified installations serving aerospace and power generation OEMs.
For Market Incumbents: Anchor defensive positioning through electromagnetic stirring technology licensing and captive fluorspar stockpiling against Chinese export restriction risks. Secure long-term power purchase agreements with Nordic hydroelectric generators to meet Rolls-Royce and Safran scope 3 carbon accounting requirements. Deepen backward integration into VAR electrode pre-melting capacity to eliminate quality propagation defects from upstream suppliers. For New Entrants and Emerging Players: Automated slag chemistry monitoring systems offer a technology-first wedge into the retrofit market for 1980s-vintage furnace mechanicals. Target Indian defense localization programs under Bureau of Indian Standards certification pathways, where first-mover advantages exist in naval propulsion and aerospace indigenization. Pursue joint development partnerships with Maharashtra-based engineering workshops seeking compact ESR entry points without full-scale infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by vacuum metallurgy specialists seeking automated control system capabilities. Long-term viability hinges on positioning against electrified process controls and superalloy specification evolution rather than commodity remelting cycles. Monitor EASA compositional drift window compression and FAA airworthiness directive expansion as inflection indicators for premium-tier capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Pre-melting | Captive VAR capacity eliminates defect propagation risks from upstream casting operations. |
| Automated Slag Chemistry Monitoring Deployment | Laser-induced breakdown spectroscopy meets EASA's compressed compositional drift requirements. |
| Renewable Power Purchase Agreement Execution | Hydroelectric-backed operations command sourcing preference from European turbine forgers. |
| Electromagnetic Stirring Technology Licensing | Controlled melt pool convection reduces macrosegregation in 800mm+ nickel superalloy castings. |
| AS9100 Certification Timeline Acceleration | Compressed qualification periods unlock faster revenue realization for new furnace commissioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with furnace operations managers, aerospace procurement leads at turbine OEMs, specialty alloy metallurgists, and slag chemistry specialists. FAA airworthiness directives, EASA certification requirements, and Bureau of Indian Standards specifications provided regulatory boundary conditions. Bottom-up installation tracking across German precision engineering clusters and top-down superalloy demand modeling from power generation and aerospace sectors enabled cross-validation.
Granularity-level modeling distinguished vacuum-capable from conventional DC configurations, automated control intensity tiers, and certification-grade versus industrial-grade end-use applications across the projection horizon. CAGRs derived from segmented demand elasticity analysis against superalloy purity specification evolution and carbon accounting framework adoption. Forecast inputs incorporated defense indigenization mandate timelines, fluorspar supply concentration risk weightings, and electromagnetic stirring technology penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese fluorspar export restriction escalation or accelerated EASA compositional drift compression. Practitioners should monitor FAA airworthiness directive expansion scope and Nordic renewable power purchase agreement pricing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Laser Marking Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Pneumatic Strippers Market
Industrial Equipment
Microwave Equipment Market