
 Bellows Vacuum Suction Cup Market | 2026-2036
Bellows Vacuum Suction Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Bellows Vacuum Suction Cup Market Insights
German pneumatic component manufacturing is shifting toward higher-cycle bellows designs for cleanroom electronics handling. Schmalz leverages its Stuttgart engineering base to dominate European automotive OEM specifications. Piab sustains technology leadership through its proprietary COAX vacuum ejector integration with multi-bellows configurations. SMC anchors Asia-Pacific supply with localized production networks spanning its Japanese headquarters and Chinese subsidiary manufacturing.
Bellows vacuum suction cups are elastomeric gripping devices featuring pleated, compressible sidewalls that conform to curved or irregular surfaces while maintaining vacuum seal integrity; typical specifications include shore hardness ratings from 40 to 70 A and operating temperatures ranging from minus 40 to plus 200 degrees Celsius depending on material compound. These components serve primarily as end-of-arm tooling in automated material handling systems where gentle part transfer and positional repeatability prove critical. Silicone variants command premium positioning in food processing and pharmaceutical cleanroom applications due to FDA compliance and thermal stability, while nitrile rubber occupies high-volume packaging automation where cost sensitivity dominates procurement. Medium diameter formats represent the mature revenue core, though small diameter segments for microelectronics assembly exhibit the fastest growth trajectory driven by semiconductor packaging miniaturization.
FDA food contact regulations and EU Machinery Directive safety standards govern material selection and operational validation across North American and European installations. ISO 9409-1 robot mechanical interface specifications further constrain dimensional compatibility for systems integrators specifying end-of-arm tooling. China's GB standards and Japan's JIS frameworks add parallel compliance layers for equipment deployed in East Asian manufacturing bases. Stakeholders must monitor evolving PFAS restrictions in elastomer formulations and accelerating regional content requirements in automation equipment procurement policies.
Market Dynamics
Semiconductor packaging miniaturization is compressing bellows diameter specifications while simultaneously elevating cleanliness requirements, forcing simultaneous investment in precision molding and contamination-controlled manufacturing environments.
Growth Catalysts
- EU Machinery Directive compliance mandates:Automated handling equipment in German automotive plants must meet EN ISO 13849-1 safety integrity levels, driving replacement cycles for certified suction cup assemblies.
- Silicone thermal stability:Food processing lines in North America specify FDA 21 CFR 177.2600 compliant compounds for high-temperature sterilization cycles, expanding addressable applications.
- South Korean semiconductor clusters:Pyeongtaek and Hwaseong packaging facilities deploy sub-20mm diameter bellows for die-handling automation at scale.
Market Restraints
- Fluoropolymer feedstock volatility:PFAS restriction proposals under ECHA's REACH restriction roadmap threaten supply continuity for specialized sealing compounds.
- Regional concentration risk:Japanese precision elastomer compounders control critical shore-hardness formulation IP, creating single-source dependencies for high-cycle variants.
- Mechanical substitution pressure:Electroadhesive grippers from Swiss automation specialists eliminate vacuum infrastructure requirements in cleanroom electronics handling.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO's tightening GMP enforcement drives demand for FDA-validated handling components in injectables manufacturing.
- Carbon-neutral production incentives:EU Green Deal industrial transition funding subsidizes energy-efficient vacuum ejector retrofits in automotive stamping lines.
- Collaborative robot integration:ISO/TS 15066 safety requirements for human-robot collaboration is unifying force-torque sensing with compliant bellows geometries.
Industry Challenges
- Multi-standard certification timelines:Simultaneous UL, CE, and KOSHA approvals for robot interface components extend product launch cycles by 8-14 months.
- Legacy pneumatic infrastructure incompatibility:Brownfield automotive facilities in Michigan and Ohio require custom manifold adapters for next-generation multi-bellows configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bellows Vacuum Suction Cup Market |
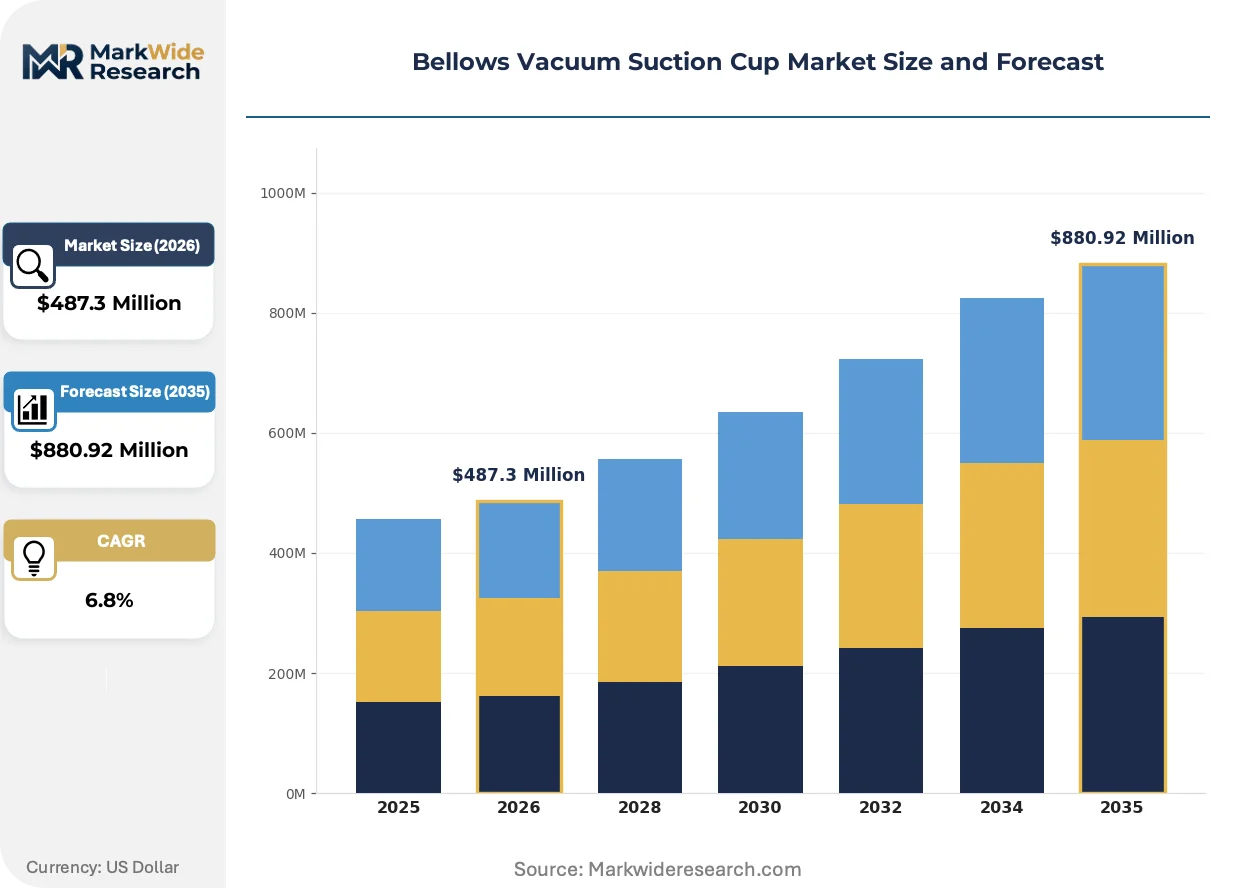
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Nitrile Rubber, Silicone, Polyurethane, Neoprene, EPDM, Thermoplastic Elastomer Size: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter Application: Electronics Assembly, Packaging Automation, Automotive Manufacturing, Food Processing End User: Robotic Systems Integrators, Material Handling Companies, Pharmaceutical Manufacturers, Consumer Goods Producers |
| Companies Covered | Schmalz, Piab, SMC, Coval, FIPA, VacMotion, ANVER, AIRBEST, VUOTOTECNICA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bellows Vacuum Suction Cup Market Trends and Innovations
Material science advances and regulatory stringency are compressing product development cycles while expanding the performance envelope of elastomeric gripping systems across precision manufacturing verticals.
Multi-material co-molding technology is unifying rigid structural ribs with compliant sealing lips in single-shot processing, eliminating secondary bonding operations. Medical device manufacturers in Massachusetts and Minnesota are qualifying these hybrid constructions for catheter handling automation. The convergence is compressing unit costs for high-integrity pharmaceutical applications while extending fatigue life beyond ten million cycles.
REACH Annex XVII PFAS restrictions are compelling compound reformulation across European supply chains, with ECHA's 2023 restriction proposal targeting perfluoroelastomers used in aggressive chemical environments. Automotive painting operations in Stuttgart and Wolfsburg are accelerating validation of hydrogenated nitrile alternatives. The transition is elevating qualification costs while creating first-mover advantages for compounders with pre-validated material portfolios.
Specification consolidation among tier-one automotive OEMs is compressing supplier bases for end-of-arm tooling, with BMW and Mercedes-Benz centralizing suction cup procurement through approved system integrator frameworks. Direct manufacturer relationships are displacing distributor-centric purchasing in high-volume German and Austrian stamping plants. The concentration is visible most acutely in powertrain component handling, where single-source agreements now cover multi-year model cycles.
Bellows Vacuum Suction Cup Market Segmentation
Bellows vacuum suction cup procurement patterns diverge sharply between high-volume commodity purchasing and precision-specified engineered components. Material selection and diameter specifications function as the primary commercial levers, with application-specific certification requirements creating distinct margin tiers across end-use verticals.
Material:
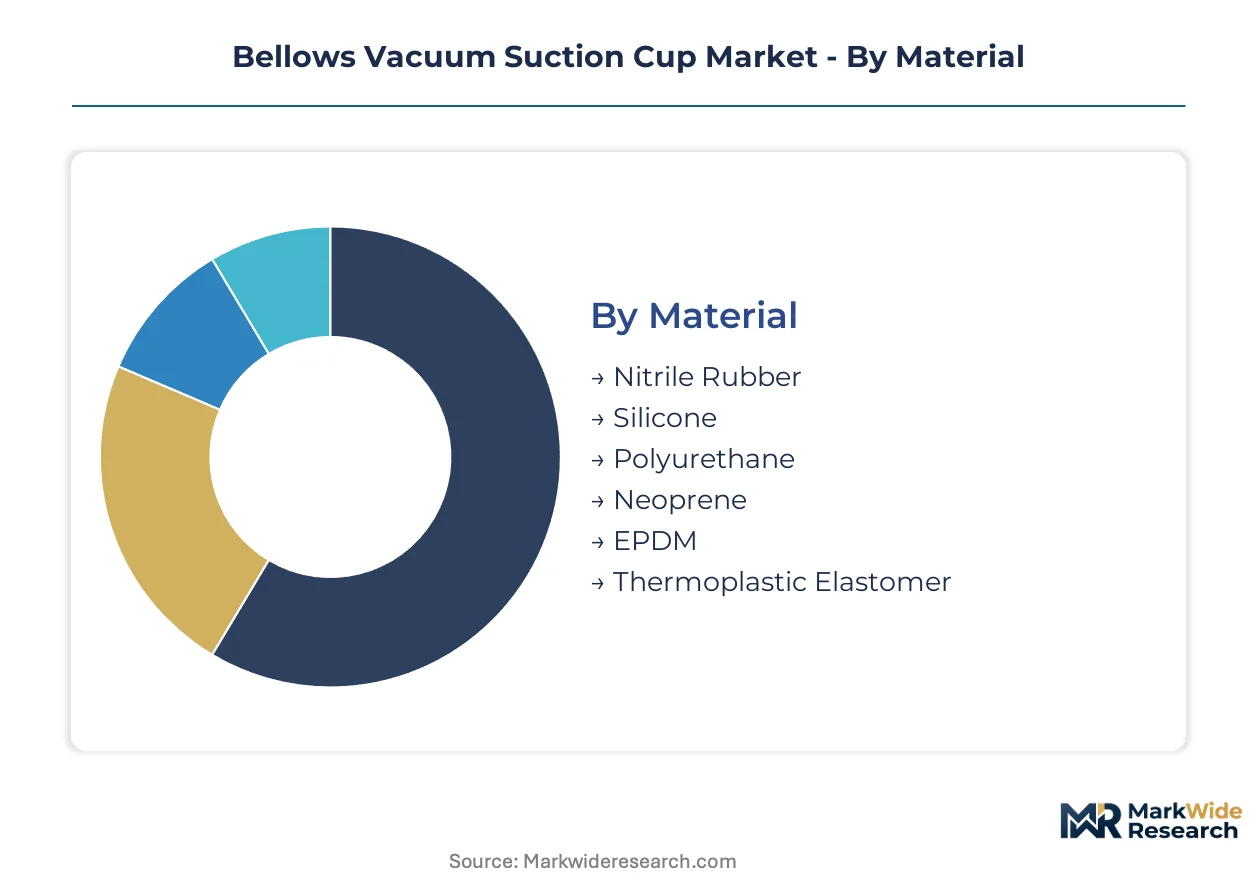
Silicone commands premium positioning against nitrile rubber's volume dominance, with specialized compounds occupying niche performance tiers.
- Silicone:FDA 21 CFR 177.2600 compliance and thermal stability from minus 40 to plus 200 degrees Celsius enable food processing and pharmaceutical cleanroom deployment. South Korean semiconductor packaging facilities in Pyeongtaek and Hwaseong specify silicone variants for high-temperature sterilization cycles in die-handling automation.
- Nitrile Rubber:Shore hardness ratings from 40 to 70 A deliver cost-effective sealing for high-cycle packaging lines where procurement sensitivity outweighs thermal performance requirements. German automotive stamping plants in Stuttgart and Wolfsburg standardize on nitrile for powertrain component handling at scale.
- Polyurethane:Abrasion resistance extends service life in abrasive material handling environments.
- Neoprene:Balanced oil and weather resistance suits general industrial automation without premium certification overhead.
- EPDM:Steam and chemical resistance targets specialized pharmaceutical processing equipment.
- Thermoplastic Elastomer:Recyclability and processing efficiency align with EU Green Deal circular economy mandates.
Today's leader: Nitrile Rubber. Tomorrow's challenger: Silicone.
Size:
Medium diameter formats anchor current revenue, though semiconductor miniaturization is compressing specifications toward smaller formats.
- Small Diameter:Sub-20mm specifications serve semiconductor die-handling and microelectronics assembly where positional repeatability below 0.1mm proves critical. Japanese precision elastomer compounders control critical shore-hardness formulation IP for high-cycle variants in this segment.
- Medium Diameter:Mature revenue core spanning 20-60mm formats dominates automotive and general packaging automation. BMW and Mercedes-Benz centralize procurement of medium-diameter assemblies through approved system integrator frameworks covering multi-year model cycles.
- Large Diameter:Heavy-panel handling in construction material automation and appliance manufacturing.
- Extra Large Diameter:Sheet metal and glass panel transfer in automotive body-in-white operations.
Medium Diameter generates the dominant revenue share. Small Diameter is climbing the fastest.
Application:
Electronics assembly and automotive manufacturing concentrate specification complexity, while packaging automation and food processing split between premium and commodity tiers.
- Electronics Assembly:Cleanroom ISO Class 5-7 compatibility and ionic contamination controls dominate procurement criteria. Massachusetts and Minnesota medical device manufacturers are qualifying hybrid multi-material constructions for catheter handling automation.
- Automotive Manufacturing:EN ISO 13849-1 safety integrity levels mandated by EU Machinery Directive drive replacement cycles for certified suction cup assemblies in German OEM plants.
- Packaging Automation:High-volume, low-variation specifications prioritize unit cost over performance envelope.
- Food Processing:FDA validation and thermal sterilization compatibility create premium positioning for compliant material compounds.
Automotive Manufacturing anchors current specification investment. Electronics Assembly is gaining share fastest.
End User:
Robotic systems integrators function as specification gatekeepers, while material handling companies and pharmaceutical manufacturers occupy opposite ends of the certification-complexity spectrum.
- Robotic Systems Integrators:ISO 9409-1 robot mechanical interface specifications constrain dimensional compatibility for end-of-arm tooling design. Schmalz leverages its Stuttgart engineering base to dominate European automotive OEM specifications through direct integrator relationships.
- Pharmaceutical Manufacturers:CDSCO's tightening GMP enforcement in India drives demand for FDA-validated handling components in injectables manufacturing.
- Material Handling Companies:Cost-optimized procurement for brownfield pneumatic infrastructure dominates replacement purchasing.
- Consumer Goods Producers:Volume-scale automation with standardized handling requirements across packaging lines.
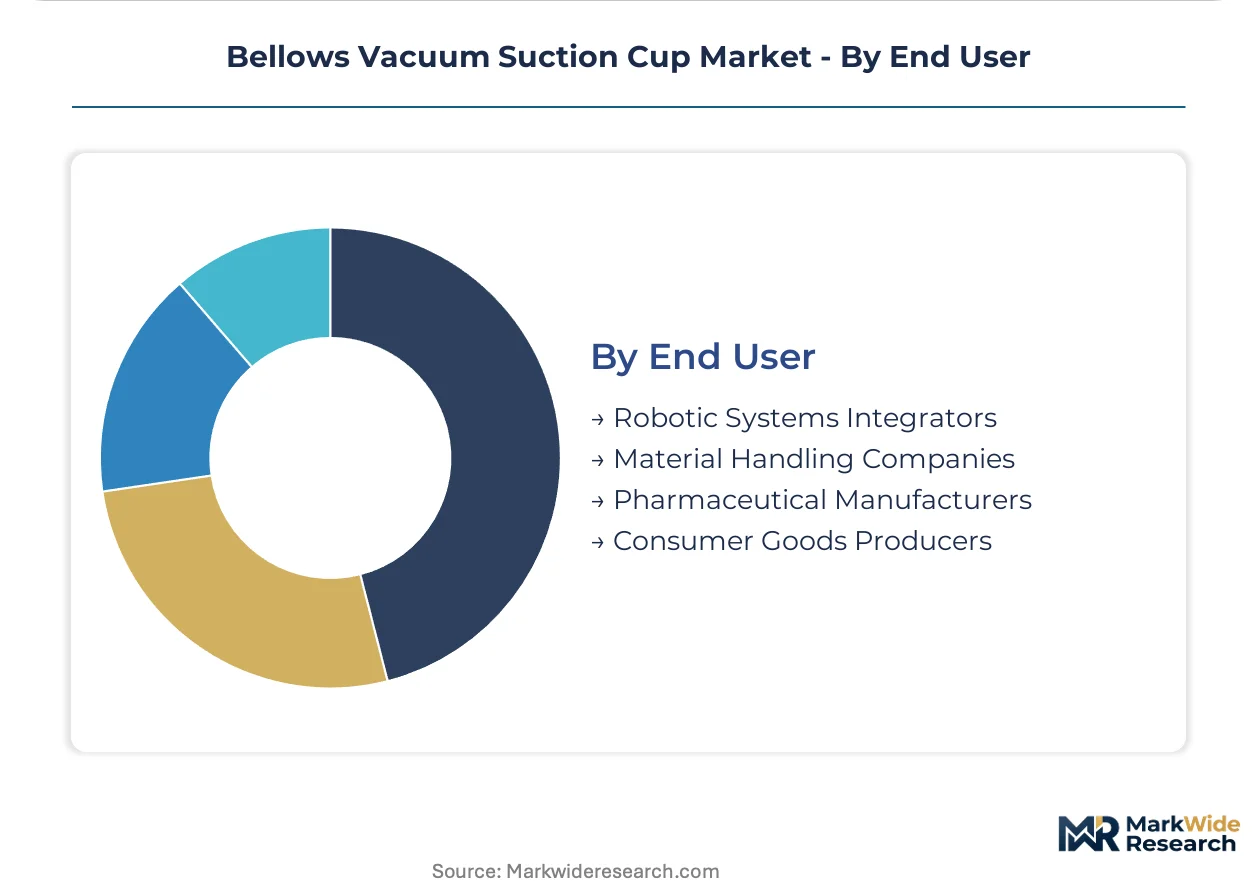
Robotic Systems Integrators control specification flow. Pharmaceutical Manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive stamping lines demand higher-cycle bellows specifications than Japanese electronics cleanrooms, while South Korean semiconductor packaging compresses diameter tolerances most aggressively.
Germany
Stuttgart and Wolfsburg automotive OEMs specify EN ISO 13849-1 certified suction cup assemblies for powertrain component handling. The EU Machinery Directive mandates safety integrity levels that accelerate replacement cycles in brownfield stamping plants. BMW and Mercedes-Benz centralize procurement through approved system integrator frameworks covering multi-year model cycles.
Japan
Tokyo and Nagoya precision elastomer compounders control critical shore-hardness formulation IP for high-cycle bellows variants. METI industrial automation standards constrain dimensional compatibility for robot interface components. Japanese headquarters anchor Asia-Pacific supply networks with localized subsidiary manufacturing across Chinese industrial clusters.
South Korea
Pyeongtaek and Hwaseong semiconductor packaging facilities deploy sub-20mm diameter bellows for die-handling automation at scale. MFDS pharmaceutical GMP enforcement drives FDA-validated component demand in injectables manufacturing. Korean electronics assembly clusters concentrate specification complexity for microelectronics miniaturization.
United States
Massachusetts and Minnesota medical device manufacturers qualify hybrid multi-material constructions for catheter handling automation. FDA 21 CFR 177.2600 compliance requirements govern silicone compound selection for food processing sterilization cycles. Michigan and Ohio brownfield automotive facilities require custom manifold adapters for next-generation multi-bellows configurations.
India
Maharashtra and Gujarat pharmaceutical packaging lines face CDSCO tightening GMP enforcement for FDA-validated handling components. The country's national pharmaceutical regulator elevates qualification barriers for elastomeric gripping systems in sterile manufacturing. Indian injectables manufacturing expansion creates demand concentration for premium silicone variants.
Bellows Vacuum Suction Cup Market Competitive Landscape
German engineering-centric producers anchor one tier; Japanese precision manufacturers hold specialized high-cycle positions. The vendor base clusters around three strategic archetypes: Stuttgart-based system integrator partners, Tokyo-Nagoya precision compounders, and diversified pneumatic component conglomerates with captive suction cup portfolios. Consolidation pressure concentrates among tier-one automotive OEM procurement frameworks, while technology licensing agreements distribute COAX vacuum ejector integration across second-tier specialists.
Among Germany-based engineering houses, Schmalz GmbH exemplifies the direct OEM relationship archetype through its Stuttgart engineering base. Piab AB occupies a position bridging Swedish vacuum technology heritage with multi-bellows configuration specialization. SMC Corporation anchors the diversified conglomerate tier with Japanese headquarters and Chinese subsidiary manufacturing networks. These three represent distinct competitive vectors: engineering proximity to automotive OEMs, proprietary ejector integration, and scale-driven Asia-Pacific supply chain density.
| Leading Market Players |
|---|
| Schmalz |
| Piab |
| SMC |
| Coval |
| FIPA |
| VacMotion |
| ANVER |
| AIRBEST |
| VUOTOTECNICA |
| Others |
Pricing and Supply Chain Analysis
Silicone rubber commodity indices cascade through three distinct pricing tiers as raw material volatility separates FDA-validated pharmaceutical grades from general industrial nitrile variants. Japanese precision compounders translate shore-hardness formulation IP into premium positioning for semiconductor cleanroom specifications, while German automotive OEM procurement frameworks compress distributor margins through direct system integrator relationships.
Pricing Analysis
Distributor margin layers have compressed from fifteen to eight percentage points as BMW and Mercedes-Benz centralize procurement through approved system integrator frameworks covering multi-year model cycles. Three-tier pricing structure across premium silicone for pharmaceutical cleanrooms, standard nitrile for automotive powertrain handling, and economy EPDM for general packaging automation reflects certification grade and volume scale differentiation. Cost compression in medium-diameter commodity tiers intensifies because Chinese subsidiary manufacturing networks compete on cycle time rather than technical specification. Material handling companies exhibit highest price sensitivity due to brownfield pneumatic infrastructure replacement cycles, while pharmaceutical manufacturers accept premium positioning for FDA 21 CFR 177.2600 validated compounds.
Supply Chain Analysis
Single-source vulnerability sits with Japanese precision elastomer compounders in Tokyo and Nagoya who control critical shore-hardness formulation IP for high-cycle bellows variants. Manufacturing concentrates in Germany for automotive OEM proximity, Japan for precision compound technology, and China for volume-scale subsidiary production networks. Raw material dependencies encompass silicone feedstocks from specialty chemical producers, nitrile rubber from petrochemical derivatives, and fluoropolymer compounds threatened by ECHA REACH Annex XVII PFAS restriction proposals. Tariff exposure runs through EU-China automation equipment trade corridors where regional content requirements in procurement policies elevate qualification costs. Distribution runs through robotic systems integrators who function as specification gatekeepers for end-of-arm tooling procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal industrial transition funding subsidizes energy-efficient vacuum ejector retrofits in German automotive stamping lines while Indian pharmaceutical packaging lines absorb premium silicone pricing under CDSCO tightening GMP enforcement without equivalent subsidy support.
For Market Incumbents: Anticipate electroadhesive gripper substitution pressure from Swiss automation specialists by accelerating COAX vacuum ejector integration with multi-bellows configurations for cleanroom electronics handling. Backward integration into captive silicone compounding capacity insulates margin position against ECHA PFAS restriction timeline uncertainty. Certification investment in simultaneous UL, CE, and KOSHA approvals defends specification control against emerging Asia-Pacific competitors. For New Entrants and Emerging Players: Begin with Indian pharmaceutical packaging lines in Maharashtra and Gujarat where CDSCO enforcement gaps create temporary qualification windows for FDA-validated handling components in injectables manufacturing. Target collaborative robot integration segments where ISO/TS 15066 safety requirements for human-robot collaboration unify force-torque sensing with compliant bellows geometries. Pursue direct relationships with Massachusetts and Minnesota medical device manufacturers qualifying hybrid multi-material constructions for catheter handling automation. For Investors and Strategic Acquirers: Consolidation pressure builds where tier-one automotive OEM procurement frameworks displace distributor-centric purchasing in high-volume German and Austrian stamping plants. Five-to-ten year viability hinges on compound reformulation capabilities as REACH Annex XVII restrictions compel hydrogenated nitrile alternatives validation. Acquisition target archetype: precision elastomer compounders with pre-validated material portfolios and existing ECHA regulatory submission track records. Monitor ECHA restriction proposal implementation timeline as inflection indicator for specialty fluoropolymer replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Co-Molding Capacity Expansion | Massachusetts medical device manufacturers compress unit costs for catheter handling automation through single-shot processing elimination of secondary bonding. |
| Backward Integration into Silicone Compounding | Stuttgart-based engineering houses secure FDA 21 CFR 177.2600 validated feedstock supply continuity against ECHA PFAS restriction uncertainty. |
| Collaborative Robot Safety Certification Pathway | ISO/TS 15066 compliance unifies force-torque sensing with compliant bellows geometries for human-robot interaction deployment. |
| Long-Term Supply Agreement with Semiconductor Clusters | Pyeongtaek and Hwaseong packaging facilities lock in sub-20mm diameter bellows supply for die-handling miniaturization at scale. |
| Geographic Manufacturing Footprint in India | Maharashtra and Gujarat pharmaceutical packaging lines access CDSCO enforcement-driven demand for FDA-validated injectables handling components. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with robotic systems integrators, automotive OEM procurement teams, pharmaceutical manufacturing engineers, and precision elastomer compounders with secondary validation against SEC filings, customs and trade data, EU Machinery Directive implementation records, and FDA 510(k) submission databases. Bottom-up demand modeling across end-use verticals triangulated against top-down macroeconomic indicators for industrial automation capital expenditure.
Historical reference periods anchored the projection horizon to documented replacement cycles in German automotive stamping lines and South Korean semiconductor packaging facility expansions. Segmentation dimensions encompassed material compound, diameter specification, application vertical, and end-user archetype, with CAGRs derived from regression analysis of installed base growth and technology substitution rates. Industry-specific forecast inputs incorporated ECHA PFAS restriction proposal timeline scenarios and METI industrial automation standard revision schedules.
Caveats apply where ECHA regulatory implementation delays or accelerated electroadhesive gripper adoption in cleanroom electronics handling could materially shift the outlook for vacuum-based gripping system demand. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Machine Mounts Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Anti-Vibration Mounts Market
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Electron Beam Welding Systems Market