
 Fusion Splicer Market | 2026-2036
Fusion Splicer Market Size, Share, and Industry Trends Forecast 2026-2036
Fusion Splicer Market Intelligence
The bundling of extended warranties and technician training with new equipment purchases is hardening the preference for single-vendor solutions among system integrators. Fujikura Ltd. leverages its extensive service network to support these bundled offerings in developed markets. Sumitomo Electric Industries, Ltd. competes on the basis of its core alignment technology and manufacturing scale. Meanwhile, INNO Instrument Inc. differentiates through cost-effective models targeting emerging economies.
A fusion splicer is a device that utilizes a localized electric arc to precisely melt and join two optical fibers, creating a continuous connection. Its primary function is to achieve a splice with minimal optical loss, often below 0.02 decibels, ensuring signal integrity in long-haul communication lines. Core alignment splicers represent the dominant product type, valued for their precision in telecommunication networks. The data center application segment is expanding rapidly, requiring high-density splicing capabilities from ribbon fiber splicers.
Government-led broadband initiatives, such as those guided by the US Federal Communications Commission (FCC) and the EU's Digital Decade policy, directly influence deployment schedules and equipment demand. Equipment must also adhere to technical specifications set by bodies like the IEC globally and JIS standards in Japan to ensure interoperability. Network operators must continually evaluate the trade-off between capital investment in advanced automatic splicers and the operational costs of training field technicians.
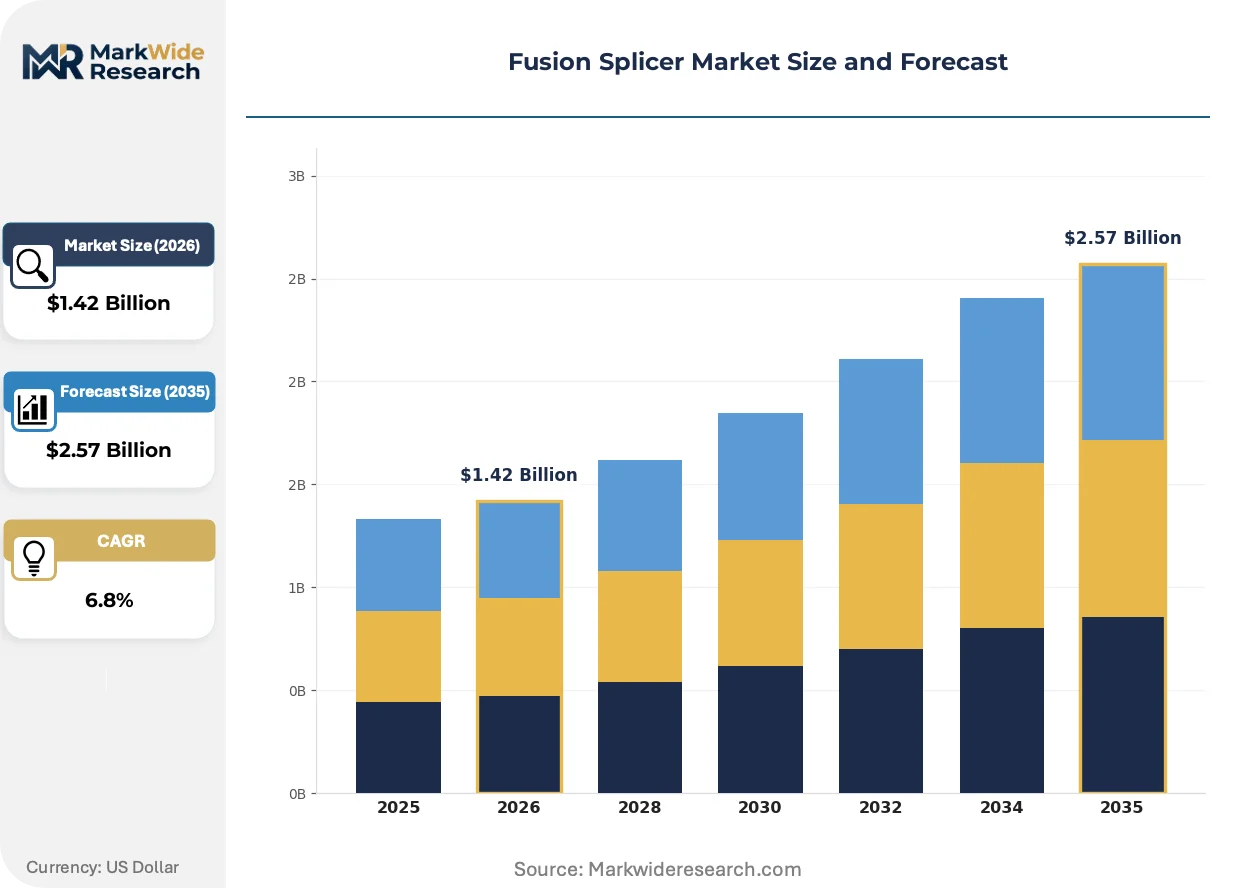
Market Dynamics
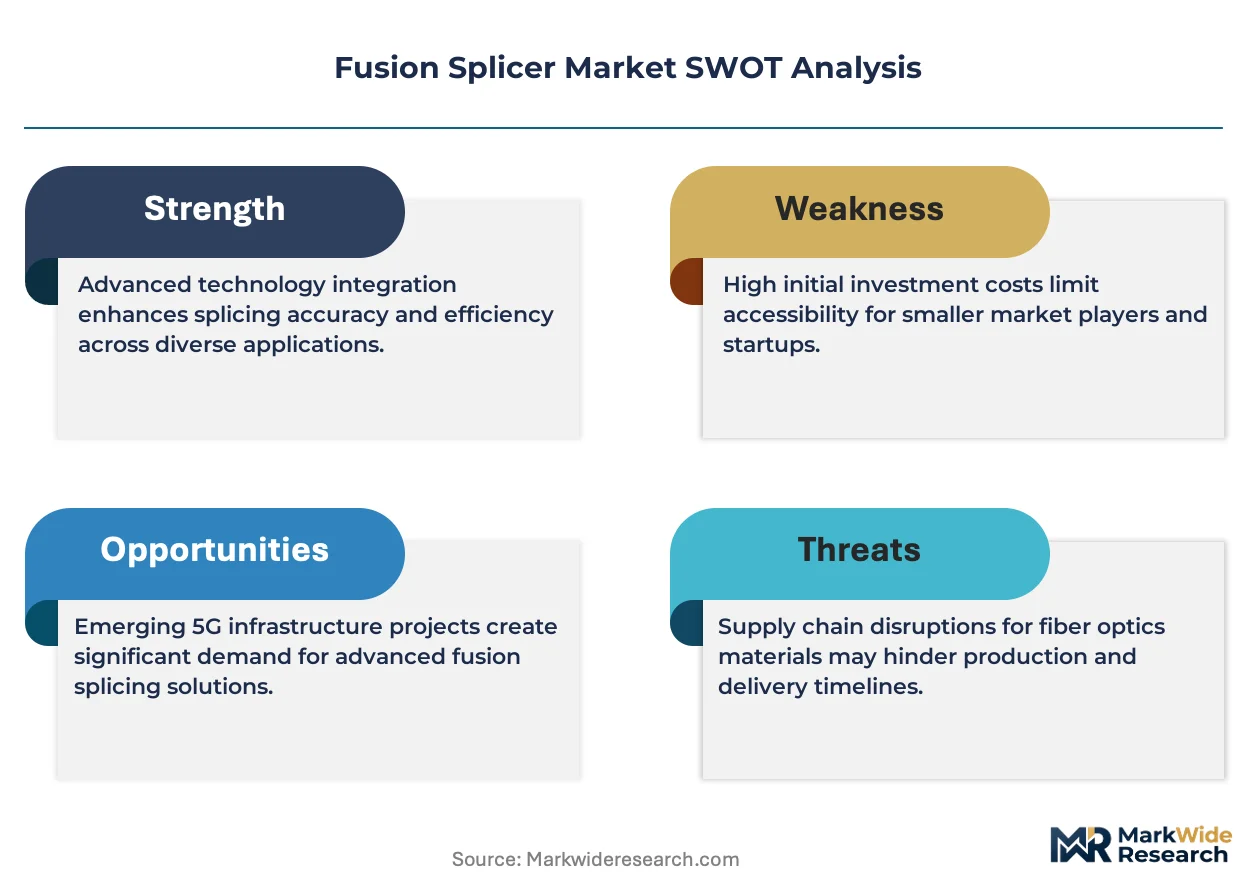
The expansion of global telecommunication infrastructure, particularly for 5G backhaul and fiber-to-the-home networks, provides the central demand driver for fusion splicers. Government-led broadband initiatives create predictable deployment schedules, while data center construction necessitates high-density splicing capabilities.
Growth Catalysts
- Government Broadband Mandates:National policies, including the EU's Digital Decade targets and programs guided by the US Federal Communications Commission (FCC), directly fund and accelerate the build-out of fiber optic networks, requiring extensive splicing equipment.
- 5G Network Densification:The deployment of 5G technology requires a dense mesh of fiber optic cable to connect small cell sites, significantly increasing the volume of splices needed for backhaul and fronthaul connectivity.
- Data Center Interconnectivity:The proliferation of hyperscale data centers creates intense demand for ribbon fiber splicers capable of performing rapid, high-density connections to manage internal data traffic and external network links.
Market Restraints
- High Capital Expenditure:The significant upfront cost of high-precision core alignment splicers remains a substantial barrier for smaller telecommunication contractors, independent installers, and operators in emerging markets.
- Field Condition Sensitivity:Splicing performance is susceptible to environmental contaminants like dust and moisture, necessitating the use of more expensive, environmentally sealed units for reliable outdoor field deployment.
- Viability of Mechanical Splices:In non-critical, last-mile, or temporary repair applications, lower-cost and simpler mechanical splices present a functional alternative, capping the market for fusion splicers in certain segments.
Strategic Opportunities
- Emerging Market Infrastructure:Rapid digital infrastructure development in Southeast Asian nations, particularly Vietnam and Indonesia, presents significant greenfield opportunities for splicer sales as national fiber backbones are established.
- Specialized Industrial Applications:Niche applications in sectors like aerospace, medical sensing, and subsea communications require specialized splicers for non-standard fiber types, offering a high-margin opportunity beyond telecommunications.
- Integrated Test and Measurement:The development of devices that combine fusion splicing with diagnostic capabilities, such as an Optical Time-Domain Reflectometer (OTDR), addresses operator demand for workflow consolidation and improved field efficiency.
Industry Challenges
- Technician Skill Gap:A persistent shortage of technicians with the training to properly operate fusion splicers and accurately interpret splice quality data creates operational bottlenecks for network deployment projects.
- Compliance with Multiple Standards:Equipment manufacturers must navigate and adhere to a complex web of technical specifications, including global IEC standards and country-specific regulations like Japan's JIS standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fusion Splicer Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Alignment Splicer, Bare Fiber Splicer, Ribbon Fiber Splicer, Portable Splicer Technology: Manual Fusion, Automatic Fusion, Semi-Automatic Fusion, Mechanical Splicing Application: Telecommunication Networks, Data Centers, Broadcast Networks, Military Communications End User: Network Operators, System Integrators, Equipment Manufacturers, Service Providers |
| Companies Covered | INNO Instrument Inc., Nanjing Jilong Optical Communication Co., Ltd., Fujikura Ltd., Shinho Fiber Communication Co., Ltd, Signal Fire Technology Co., Ltd., Sumitomo Electric Industries, Ltd., Ilsintech Co., Ltd., Darkhorsechina (Beijing) Telecom. Tech. Co., Ltd., Furukawa Electric Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fusion Splicer Market Strategic Shifts & Innovations
The evolution of fusion splicing technology focuses on embedding intelligence and automation into the equipment. This drive seeks to minimize the impact of technician skill variability and increase the speed and reliability of large-scale fiber optic deployments.
AI-powered image analysis improves the accuracy of fiber core alignment before an electric arc is applied. Network operators and system integrators are adopting these automated systems to lower splice failure rates and shorten technician training cycles. This automated alignment functionality is converging with cloud-based fleet management platforms, enabling remote monitoring of splice quality and equipment status across geographically dispersed teams.
The US Federal Communications Commission (FCC) establishes specific performance metrics for projects funded through its various broadband deployment initiatives. This regulatory pressure effectively mandates the use of low-loss splicing techniques, strengthening the case for high-performance equipment over lower-cost alternatives. The telecommunications segment in North America is therefore standardizing on advanced core alignment splicers to ensure compliance and secure federal funding.
A shift from one-time equipment sales to comprehensive service and support bundles is altering procurement patterns among major network operators. These agreements package the splicer with extended warranties, technician training, and consumable resupply, replacing the traditional transactional purchasing model. This trend is most pronounced in developed markets where operators prioritize long-term operational reliability and predictable total cost of ownership over initial capital outlay.
Fusion Splicer Market Segmentation
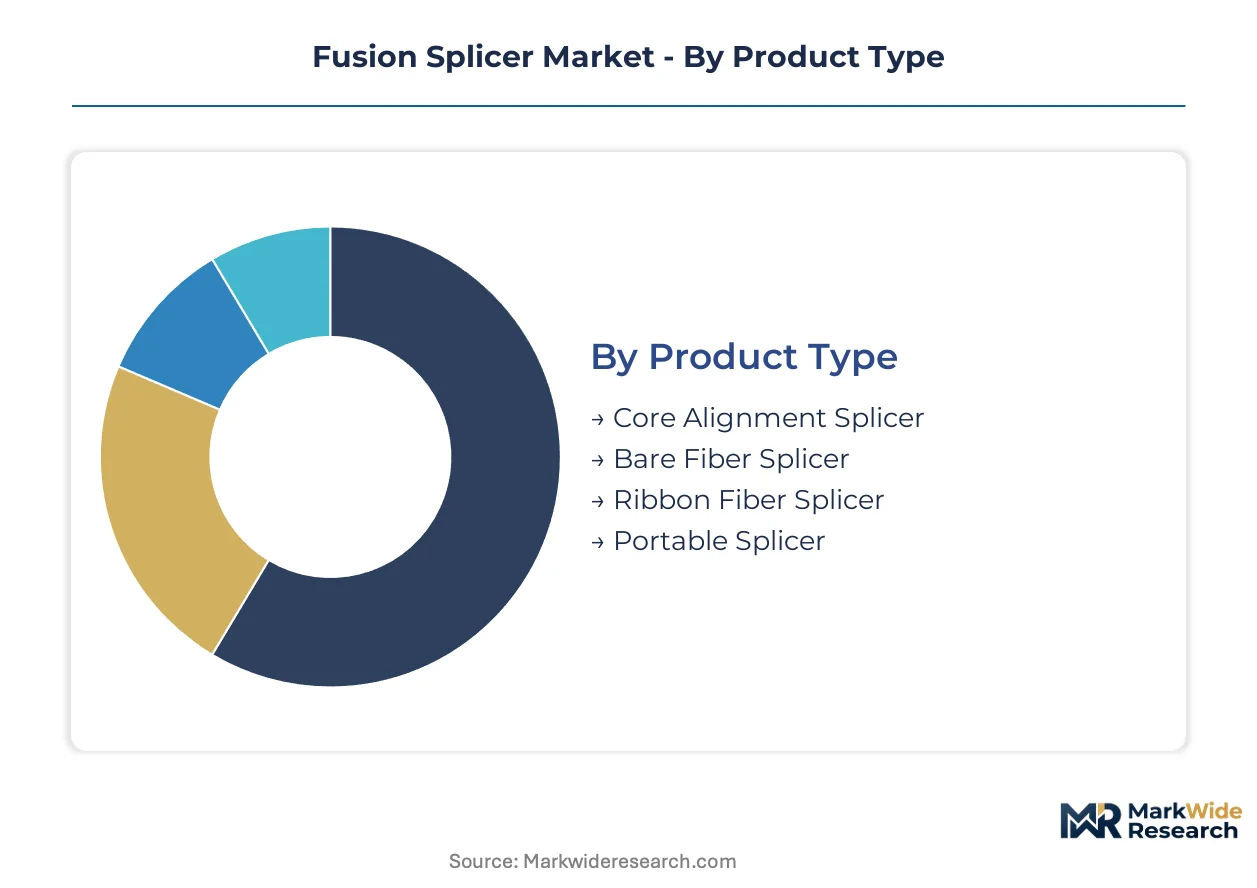
The Fusion Splicer Market is segmented to provide a granular understanding of product type, technological advancements, diverse application areas, and the varied end-user ecosystem. This segmentation highlights how different market facets contribute to the overall industry dynamics and growth trajectory.
Product Type:
Product type segmentation in the fusion splicer market highlights the balance between high-precision instruments and portable, field-ready solutions. This differentiation addresses varying operational demands and investment capacities across diverse deployment scenarios.
- Core Alignment Splicer:These devices precisely align fiber cores using advanced image processing, minimizing optical loss to below 0.02 decibels for critical connections. Demand concentrates in long-haul telecommunication networks, where signal integrity is paramount for high-bandwidth data transmission.
- Bare Fiber Splicer:These splicers are optimized for handling fibers without protective coatings, often used in laboratory settings or for specific component integration.
- Ribbon Fiber Splicer:Designed to splice multiple fibers simultaneously, these units are essential for high-density cabling, particularly ribbon fiber configurations. Data center application expansion requires these splicers for rapid deployment and efficient management of internal network traffic.
- Portable Splicer:Compact and battery-operated, portable splicers are designed for field deployment, enhancing technician mobility for last-mile fiber-to-the-home installations.
Mature deployment sits with Core Alignment Splicers. Newer deployment is concentrated in Ribbon Fiber Splicers due to data center expansion.
Technology:
Technology segmentation reflects the trade-offs between initial capital outlay, operational efficiency, and required skill levels for fiber optic connections.
- Manual Fusion:Requires significant operator skill for precise fiber alignment and arc discharge control, typically used for specialized or low-volume applications.
- Automatic Fusion:This technology integrates automated fiber preparation, alignment, and splicing processes, reducing operator intervention and skill dependency. Network operators prioritize automatic fusion to lower splice failure rates and accelerate large-scale fiber optic deployments.
- Semi-Automatic Fusion:Offers some automated features like fiber clamping, balancing operator control with enhanced efficiency compared to fully manual methods.
- Mechanical Splicing:A simpler, non-fusion method that physically aligns and clamps fibers, offering a quick and less expensive alternative to fusion. Mechanical splices find application in non-critical, last-mile connections or temporary repair scenarios, capping fusion splicer demand.
Automatic Fusion technology is gaining market share due to reduced skill requirements. Mechanical splicing maintains relevance for temporary or non-critical applications.
Application:
Application segments are driven by specific network architectures and performance requirements, influencing the type and volume of fusion splicers deployed.
- Telecommunication Networks:These applications involve extensive fiber optic infrastructure for backhaul, fronthaul, and fiber-to-the-home deployments, requiring robust and low-loss splicing. Government-led broadband initiatives, such as those guided by the US Federal Communications Commission (FCC), directly influence deployment schedules and equipment demand.
- Data Centers:Hyperscale data centers require high-density splicing capabilities for internal interconnections and external network links. The proliferation of these facilities drives demand for ribbon fiber splicers capable of rapid, high-volume connections.
- Broadcast Networks:Require high-performance fusion splicers for reliable signal transmission in media production and distribution infrastructure.
- Military Communications:Demands ruggedized and secure splicing equipment for field deployment in harsh environments, ensuring robust communication links.
Telecommunication Networks continue to anchor demand, while the data center application segment is expanding most quickly.
End User:
End-user categories highlight distinct procurement patterns and service expectations within the fiber optic infrastructure ecosystem.
- Network Operators:These entities deploy and manage large-scale fiber optic networks, procuring splicers based on operational reliability, total cost of ownership, and bundled service agreements. Major operators prioritize advanced automatic splicers to ensure compliance with performance metrics like those set by the US Federal Communications Commission (FCC).
- System Integrators:Responsible for designing and implementing complex network solutions, system integrators often prefer single-vendor solutions that bundle equipment with extended warranties and technician training. Fujikura Ltd. leverages its service network to support these offerings.
- Equipment Manufacturers:Utilize fusion splicers for internal production processes, testing, and quality control of fiber optic components and assemblies.
- Service Providers:Offer installation, maintenance, and repair services for fiber optic networks, requiring a versatile fleet of splicing equipment for diverse field conditions.
Network Operators prioritize long-term reliability and bundled services. System Integrators focus on efficiency and multi-vendor interoperability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global fusion splicer market exhibits a clear divide between established manufacturing hubs and rapidly expanding consumption centers. Production capabilities are concentrated in developed economies, while significant demand emerges from nations undertaking extensive digital infrastructure projects. This dynamic shapes regional investment and deployment strategies.
United States
Demand for fusion splicers in the United States is driven by aggressive 5G deployments and fiber-to-the-home initiatives. The US Federal Communications Commission (FCC) mandates performance metrics for federally funded broadband projects, favoring advanced splicing technology. Major data center clusters in Virginia and Texas require high-density ribbon fiber splicers for internal and external connectivity.
China
China's vast telecommunication network expansion and hyperscale data center build-outs create substantial demand for fusion splicers. The Ministry of Industry and Information Technology (MIIT) guides national 5G and fiber optic infrastructure plans, accelerating equipment procurement. Large manufacturing hubs like the Yangtze River Delta integrate advanced splicers into their fiber optic component production.
India
India's ambitious Digital India program and rapid 5G rollout necessitate extensive fiber optic splicing equipment. The Telecom Regulatory Authority of India (TRAI) supports policies promoting widespread broadband access, boosting equipment purchases. Infrastructure development in cities such as Bengaluru and Hyderabad fuels demand for both core alignment and ribbon fiber splicers.
Germany
European Union Digital Decade policy targets drive fusion splicer demand across Germany for enhanced broadband connectivity. Compliance with IEC standards is paramount for equipment deployed in critical infrastructure, emphasizing precision. Industrial clusters in Bavaria and North Rhine-Westphalia integrate specialized splicers for advanced manufacturing and research applications.
Vietnam
Rapid digital infrastructure development in Vietnam generates significant greenfield opportunities for fusion splicer sales. Government initiatives prioritize national fiber backbone establishment and rural broadband access, influencing procurement. Ho Chi Minh City and Hanoi are central to new network deployments, requiring substantial splicing capabilities.
Fusion Splicer Market Key Industry Players
The competitive structure tilts toward a tiered ecosystem, featuring established global manufacturers alongside specialized regional players catering to diverse market needs. Strategic archetypes include high-precision technology leaders focusing on advanced performance, cost-effective solution providers targeting emerging economies, and integrated service-bundle vendors offering comprehensive support. Dominant competitive moves involve strategic partnerships to expand market reach and continuous portfolio diversification to address evolving application requirements.
Within the high-precision technology leadership tier, Fujikura Ltd. (a Japanese firm) and Sumitomo Electric Industries, Ltd. (another Japanese entity) exemplify companies leveraging extensive manufacturing scale and advanced core alignment technologies. INNO Instrument Inc., a South Korean company, occupies a position among cost-effective solution providers, targeting emerging economies with accessible models. These companies anchor different segments of the market by offering distinct value propositions.
| Leading Market Players |
|---|
| INNO Instrument Inc. |
| Nanjing Jilong Optical Communication Co., Ltd. |
| Fujikura Ltd. |
| Shinho Fiber Communication Co., Ltd |
| Signal Fire Technology Co., Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Ilsintech Co., Ltd. |
| Darkhorsechina (Beijing) Telecom. Tech. Co., Ltd. |
| Furukawa Electric Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The US Federal Communications Commission's (FCC) performance metrics for federally funded broadband projects directly influence procurement patterns for fusion splicers. This demand-side pressure forces manufacturers to prioritize advanced features, impacting pricing strategies across the market.
Pricing Analysis
Margin tightening in the cost-effective segment reflects intense competition from mechanical splices and local manufacturers. The dominant pricing model remains per-unit transactional, though bundled service agreements are gaining traction in developed markets. Price differentiation stems from core alignment precision and after-sales support. Smaller telecommunication contractors in emerging economies exhibit higher price sensitivity compared to major network operators prioritizing long-term reliability.
Supply Chain Analysis
Logistics costs significantly impact the final price of high-precision fusion splicers, especially for units shipped to remote deployment sites. Geographic supply concentration centers in Japan, South Korea, and China, which house key manufacturers. The supply chain draws from specialized optical components and precision mechanical parts. Single-source vulnerability for advanced laser components represents a structural risk. Downstream sales channels utilize a mix of direct sales and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently supply-constrained, primarily due to a persistent shortage of skilled field technicians capable of operating advanced fusion splicers. This capacity bottleneck props up pricing for comprehensive training and automated equipment.
For Market Incumbents: Anticipate the need for continuous investment in AI-powered automation to mitigate the technician skill gap and reduce operational costs. Fujikura Ltd. and Sumitomo Electric Industries, Ltd. should expand their bundled service offerings, including extended warranties and technician training, to counter the threat from lower-cost alternatives. Focusing R&D on integrated test and measurement capabilities will reinforce their market position against niche competitors.
For New Entrants and Emerging Players: Underserved independent installers in rapidly expanding Southeast Asian markets present a significant opportunity for market entry. These regions, particularly Vietnam and Indonesia, require cost-effective yet reliable solutions for national fiber backbones. A go-to-market angle focusing on accessible, semi-automatic models combined with localized training programs can capture initial market share.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented regional distribution networks. Long-term viability is strong, driven by global digital infrastructure build-outs over the next decade. Acquisition targets should include specialized providers of ribbon fiber splicers or companies with strong service networks in emerging economies. A signal to watch is the acceleration of government-led broadband initiatives in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Service Network | Fujikura Ltd. can enhance customer loyalty and support bundled offerings in developed markets. |
| Invest in AI-Powered Automation | Manufacturers can reduce technician skill dependency and improve splice reliability for network operators. |
| Develop Integrated Test Solutions | Operators gain workflow consolidation and improved field efficiency by combining splicing with diagnostics. |
| Target Emerging Market Distribution | INNO Instrument Inc. can capture greenfield opportunities in nations like Vietnam and Indonesia. |
| Acquire Niche Technology Provider | Strategic acquirers can gain specialized capabilities for ribbon fiber or industrial applications. |
Research Approach
Independent corroboration across network operator procurement records, equipment manufacturer specifications, and government broadband initiative reports underwrites the qualitative findings. Primary interviews were conducted with telecommunications engineers, system integrators, and field service managers. Secondary data sources included FCC filings, MIIT guidelines, and IEC standards documentation. This approach enabled bottom-up and top-down triangulation.
The rate-of-change decomposition framework was applied to project market dynamics across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and key geographic regions. Compound annual growth rates were derived from historical trends and projected infrastructure spending. Forecast inputs incorporated planned 5G rollout schedules and fiber-to-the-home penetration rates.
Revisions become necessary when shifts in government broadband funding or unforeseen technological disruptions materialize. Forecasts reflect assumptions regarding telecommunication infrastructure investment and regulatory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Actuators Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Electric Actuator Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Battery Spot Welder Market