
 Cleanroom Equipment Market | 2026-2036
Cleanroom Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cleanroom Equipment Market Analytics
Polytetrafluoroethylene (PTFE) membrane media is decoupling from traditional fiberglass in HEPA filter construction, reducing pressure drop penalties while maintaining EN 1822 compliance. Exyte Group leverages its turnkey cleanroom infrastructure capability to anchor large-scale semiconductor fab projects across Asia. DuPont sustains polymer science leadership through fluoropolymer barrier fabrics that dominate pharmaceutical garment specifications. Camfil competes on filter testing and certification depth, operating accredited laboratories that validate performance claims to ISO 12500 protocols.
Cleanroom equipment encompasses engineered enclosures, air filtration systems, personnel decontamination apparatus, and specialized furniture designed to maintain defined particulate and microbial cleanliness levels per ISO 14644-1 classifications, with HEPA filtration achieving 99.97% efficiency at 0.3 micron particle size and laminar airflow systems delivering 0.3-0.5 m/s face velocity to protect sensitive processes. HEPA Filters command the largest product type revenue pool due to replacement cycle economics and escalating filtration efficiency requirements in gene therapy manufacturing, while Modular Cleanrooms represent the fastest-growing technology segment as pharmaceutical companies prioritize reconfigurable production lines to accommodate multi-product biologics suites. Softwall Cleanrooms retain share in research and quality control applications where capital constraints and temporary deployment needs predominate.
The US FDA enforces current Good Manufacturing Practice (cGMP) regulations under 21 CFR Parts 210 and 211, mandating environmental monitoring and contamination control that directly specifies cleanroom classification requirements for sterile drug production. The European Medicines Agency (EMA) implements EU GMP Annex 1 revisions that strengthen barrier technology and isolator requirements, while China's National Medical Products Administration (NMPA) aligns domestic biologics manufacturing standards with PIC/S guidelines to facilitate export market access. Stakeholders must monitor evolving ISO 14644-2 monitoring standard drafts and assess whether continuous particle monitoring investments will become mandatory rather than discretionary across regulated jurisdictions.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are forcing ISO Class 1-3 upgrades across HEPA filtration supply chains as EUV lithography nodes tighten particulate tolerances below 0.1 microns.
Growth Catalysts
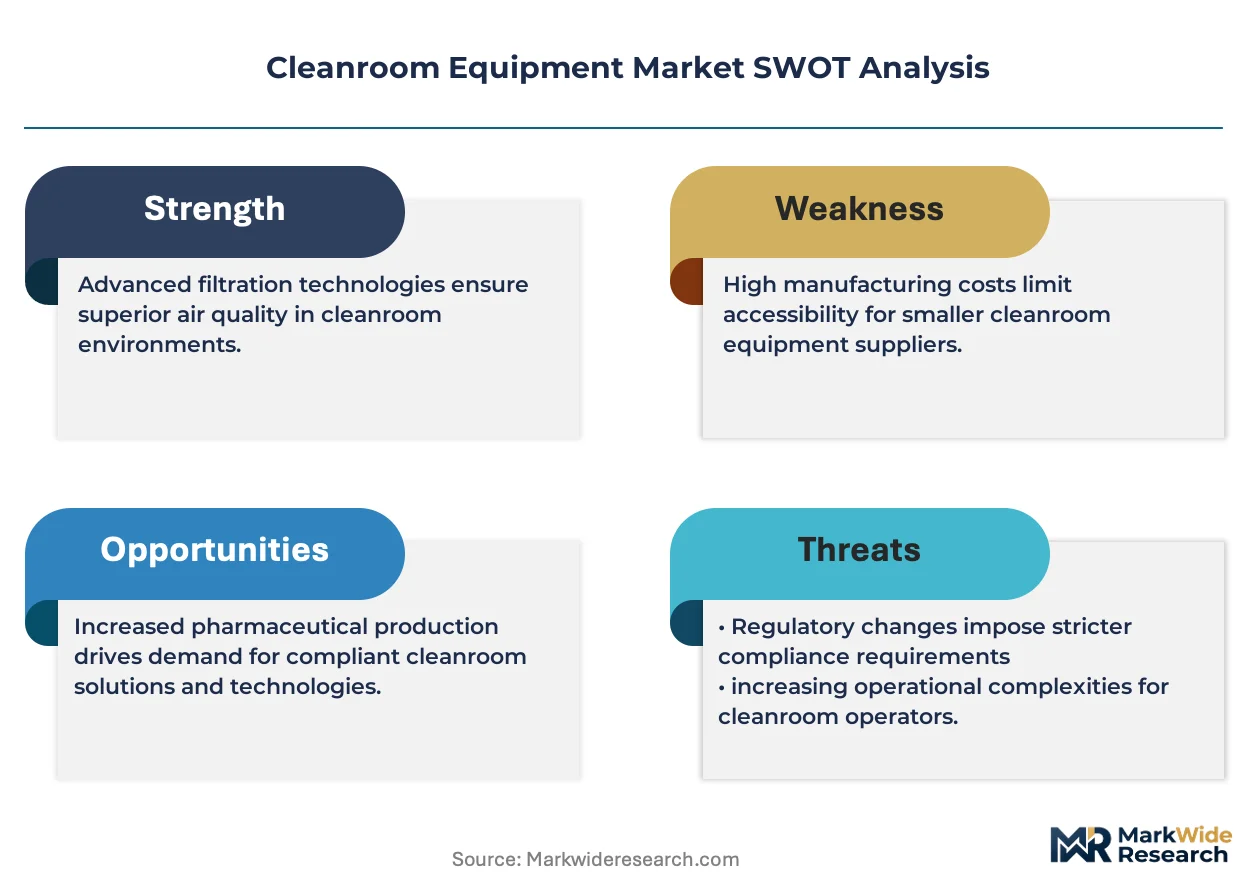
- EU GMP Annex 1 revisions:The EMA's updated sterile manufacturing guidance mandates barrier isolator technology in aseptic processing, accelerating cleanroom infrastructure replacement cycles across European pharmaceutical facilities.
- Gene therapy manufacturing:Viral vector production requires ISO 5-7 environments with continuous monitoring, expanding demand for modular cleanroom suites that accommodate multi-product biologics campaigns.
- PTFE membrane media:Fluoropolymer filter construction reduces pressure drop penalties while maintaining EN 1822 compliance, enabling energy recovery in high-volume HVAC systems serving 24/7 semiconductor operations.
Market Restraints
- High-purity aluminum supply concentration:Cleanroom ceiling grid and framing systems depend on specialty extruded aluminum where Chinese smelter capacity dominates raw material availability.
- Filter media cost volatility:Microglass fiber and PTFE resin prices fluctuate with fluorochemical feedstock markets, compressing margins for HEPA filter manufacturers on fixed-price municipal contracts.
- Extended validation timelines:FDA 21 CFR Part 11 electronic records compliance adds 6-18 months to cleanroom commissioning schedules, delaying revenue recognition for turnkey installation providers.
Strategic Opportunities
- India pharmaceutical expansion:CDSCO's alignment with PIC/S guidelines and PLI scheme incentives for active pharmaceutical ingredient manufacturing create demand for Grade A/B filling isolators in Hyderabad and Ahmedabad clusters.
- Cell and gene therapy CDMO buildout:Contract development organizations require rapidly deployable softwall cleanrooms for clinical-scale production, favoring rental and lease financing models over capital purchase.
- Continuous particle monitoring mandates:Draft ISO 14644-2 revisions signal regulatory migration from periodic to real-time environmental monitoring, opening retrofit markets for integrated sensor networks in existing pharmaceutical suites.
Industry Challenges
- Qualified cleanroom technician scarcity:Certification programs for ISO 14644-1 testing and HEPA filter installation lag demand, constraining deployment velocity for large-scale semiconductor fab projects.
- Legacy HVAC integration complexity:Pharmaceutical facilities built to 2005-era specifications require extensive ductwork modification to accommodate modern laminar airflow requirements and redundant filtration banks.
- Cross-contamination protocol standardization:Multi-product biologics suites demand rapid changeover procedures that lack harmonized industry guidance, forcing facility-specific validation approaches that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleanroom Equipment Market |
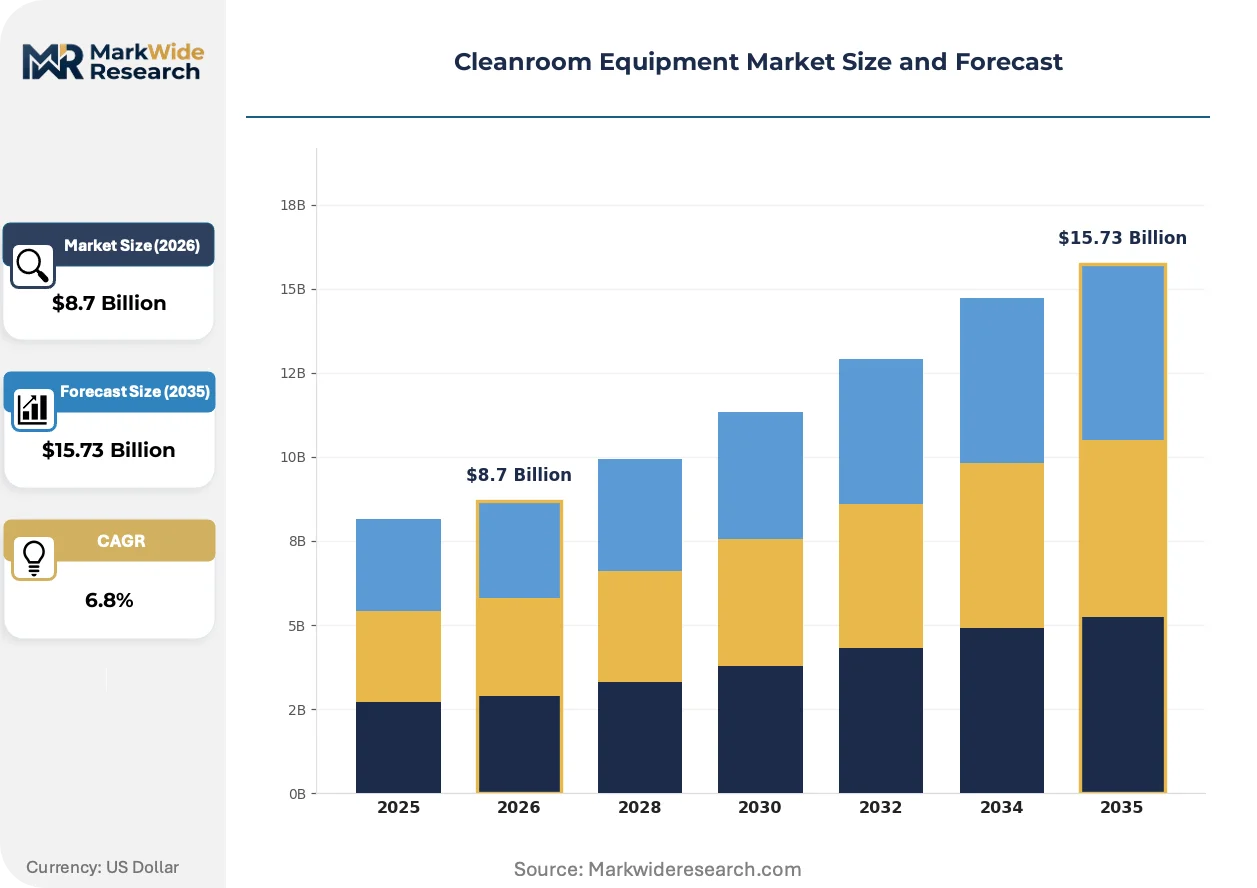
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Showers, Cleanroom Gowns, HEPA Filters, Cleanroom Furniture End User: Pharmaceutical, Biotechnology, Electronics, Healthcare Technology: Modular Cleanrooms, Softwall Cleanrooms, Hardwall Cleanrooms, Pass-Through Chambers Application: Manufacturing, Research, Quality Control, Laboratory |
| Companies Covered | Exyte Group, DuPont, Illinois Tool Works, Thermo Fisher Scientific, AAF International, Camfil, Ansell, Terra Universal, Angstrom Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleanroom Equipment Market Evolving Landscape
Active materials substitution, regulatory monitoring intensification, and procurement model restructuring are compressing equipment lifecycles while expanding service-attachment opportunities across installation bases.
PTFE membrane media is overtaking traditional fiberglass in HEPA filter construction for pharmaceutical and semiconductor applications. The fluoropolymer substrate achieves equivalent EN 1822 H13-H14 efficiency ratings at 15-20% lower pressure drop, reducing fan energy consumption in continuous-operation facilities. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement specifications now prioritize PTFE-based filters for EUV lithography bays, compressing demand for legacy microglass designs.
China's NMPA has aligned domestic biologics manufacturing standards with PIC/S guidelines through revised Good Manufacturing Practice annexes effective 2023. The regulatory convergence requires foreign-market-oriented Chinese facilities to upgrade from Grade C/D environmental classifications to Grade A/B isolator-based processing for sterile injectables. Domestic cleanroom engineering firms in Suzhou and Beijing are capturing retrofit contracts previously awarded to European turnkey providers.
Equipment-as-a-service contracting is displacing capital purchase for modular cleanroom deployments in mid-scale pharmaceutical operations. CDMOs and emerging biotechs favor 36-60 month operational leases bundling installation, certification, and filter replacement to preserve balance sheet capacity for R&D investment. This model concentrates most visibly in the Boston-Cambridge and Research Triangle Park clusters where venture-funded companies prioritize cash flow timing over total cost of ownership.
Cleanroom Equipment Market Segmentation
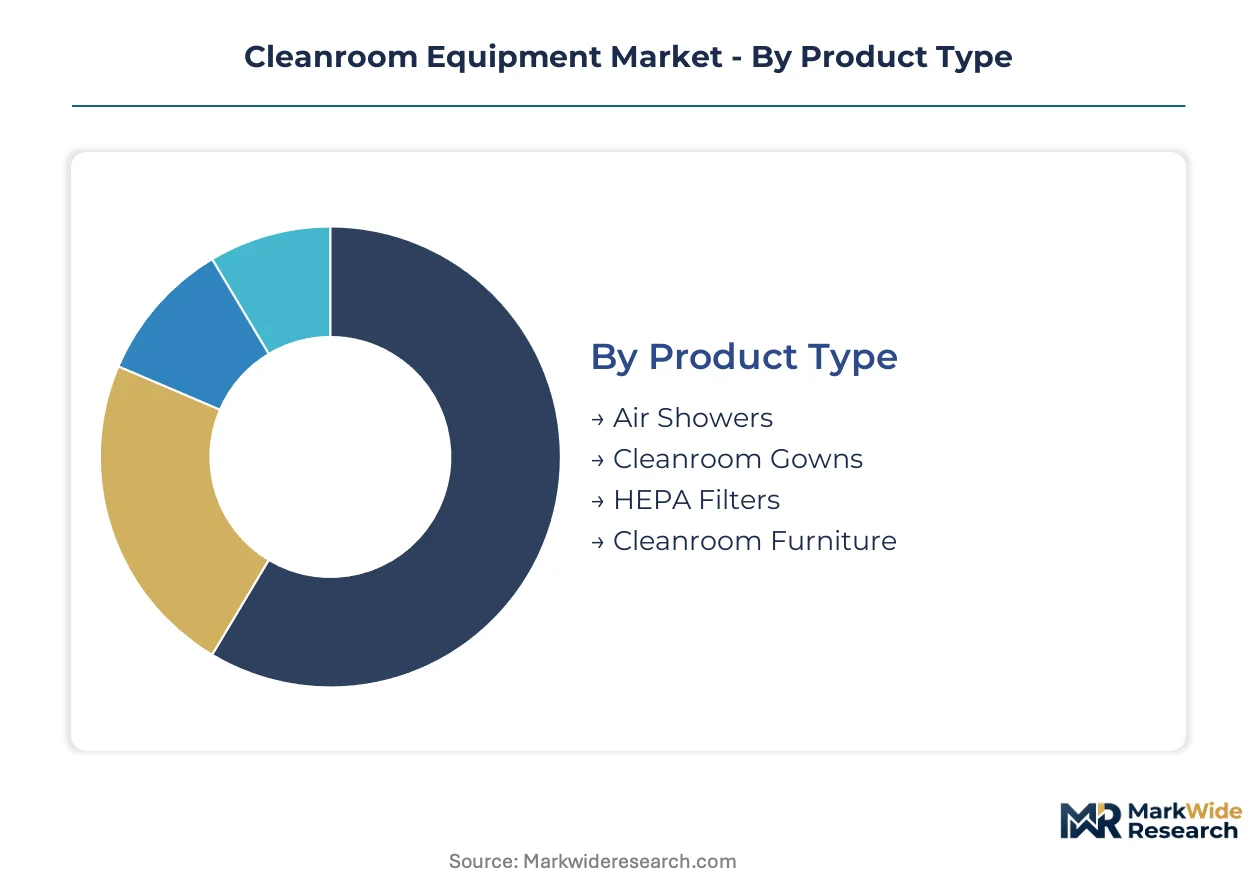
Cleanroom equipment segmentation reveals distinct procurement patterns across integration depths, from standalone filtration units to fully integrated enclosure systems. Equipment specification varies sharply by end-use sterility requirements and operational tempo, driving divergent technology preferences across semiconductor fabrication and pharmaceutical manufacturing.
Product Type:
Standalone filtration and personnel decontamination systems operate independently of enclosure infrastructure, while furniture and garment systems embed within broader cleanroom architectures.
- HEPA Filters:Constructed from PTFE membrane or microglass fiber media achieving 99.97% efficiency at 0.3 micron particle size. Semiconductor fabs in Taiwan and South Korea dominate procurement as EUV lithography nodes mandate ISO Class 1-3 environments with sub-0.1 micron particulate control.
- Cleanroom Gowns:Barrier fabrics manufactured from fluoropolymer composites or spunbond-meltblown-spunbond polypropylene laminates. Pharmaceutical operations in Germany and the United States drive specification tightening as EU GMP Annex 1 revisions mandate enhanced personnel contamination control.
- Air Showers:High-velocity decontamination entry systems deploying HEPA-filtered air jets at 20-25 m/s. Biotechnology facilities deploy these at suite boundaries.
- Cleanroom Furniture:Stainless steel and phenolic resin work surfaces designed for minimal particle shedding and chemical resistance. Research laboratories favor configurable modular designs.
Volume placements concentrate in HEPA Filters; the faster expansion belongs to Cleanroom Gowns as barrier fabric specifications intensify.
End User:
Cost tier stratification separates capital-intensive semiconductor infrastructure from mid-scale pharmaceutical deployments and constrained research budgets.
- Pharmaceutical:Aseptic processing and sterile injectable manufacturing requiring ISO 5-8 classifications with continuous environmental monitoring. FDA 21 CFR Parts 210-211 and EMA Annex 1 compliance drive isolator-based Grade A/B processing upgrades across facilities in India and the United States.
- Electronics:Semiconductor wafer fabrication and flat-panel display manufacturing demanding ISO Class 1-3 environments. Taiwan and South Korea anchor procurement volume as foundries expand EUV lithography capacity.
- Biotechnology:Viral vector and cell therapy production requiring rapid suite reconfiguration for multi-product campaigns. CDMOs favor modular cleanroom leasing over capital purchase.
- Healthcare:Hospital pharmacies and compounding facilities with intermediate cleanliness requirements. Regulatory enforcement varies by national healthcare system.
Electronics commands the dominant spend tier; Biotechnology posts the steepest expansion trajectory as gene therapy manufacturing scales.
Technology:
Application maturity separates established hardwall construction from emerging modular and rental-enabled softwall alternatives.
- Modular Cleanrooms:Prefabricated panel systems with rapid deployment and reconfiguration capabilities. Pharmaceutical companies in Boston-Cambridge and Research Triangle Park clusters prioritize these for multi-product biologics suites.
- Hardwall Cleanrooms:Permanent gypsum wall or insulated metal panel construction with integrated HVAC and filtration. Semiconductor fabs require these for ISO Class 1-3 stability.
- Softwall Cleanrooms:Flexible PVC curtain enclosures with aluminum framing for temporary or low-classification deployment. Research and quality control applications favor capital-light configurations.
- Pass-Through Chambers:Material transfer airlocks maintaining pressure differentials and particulate isolation. All regulated manufacturing segments require these at cleanroom boundaries.
Hardwall systems retain the largest installed base; Modular Cleanrooms are climbing the fastest as pharmaceutical flexibility demands intensify.
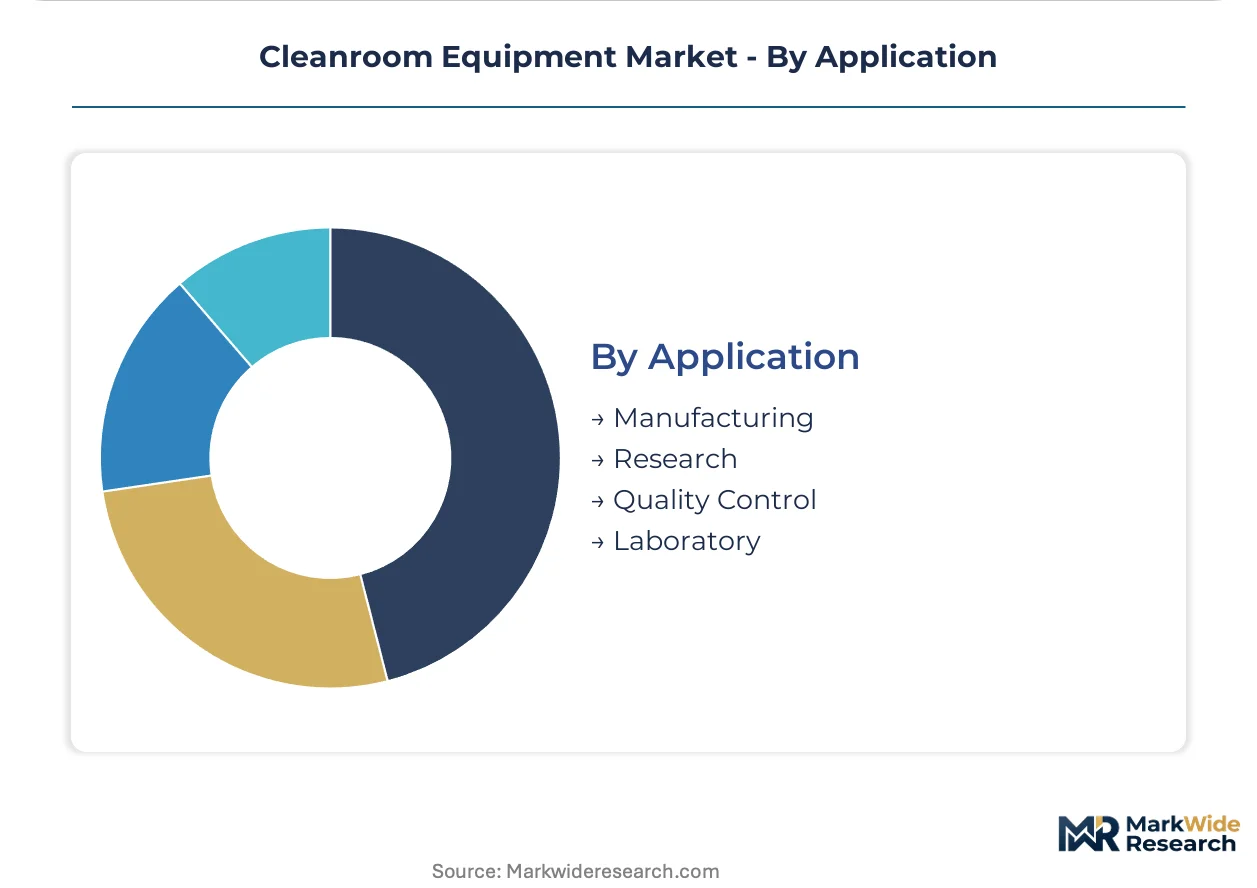
Application:
Customer workflow integration distinguishes continuous manufacturing operations from intermittent research and validation activities.
- Manufacturing:24/7 production environments with validated cleaning protocols and batch record integration. Semiconductor and pharmaceutical GMP operations dominate equipment specification intensity.
- Research:Exploratory development with variable cleanliness requirements and rapid protocol changes. Academic and government laboratories prioritize reconfigurable softwall systems.
- Quality Control:Analytical testing and release verification with intermediate environmental stringency. Microbiological testing requires ISO 7-8 environments.
- Laboratory:General analytical and preparatory work with standard cleanliness protocols. Contract testing organizations drive mid-tier equipment demand.
Manufacturing absorbs the predominant equipment volume; Research is gaining share fastest as cell and gene therapy discovery activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication and pharmaceutical manufacturing concentrate cleanroom equipment procurement in Taiwan, South Korea, Germany, the United States, and India, with regulatory convergence around ISO 14644-1 classifications and EU GMP Annex 1 standards reshaping investment patterns across these markets.
Taiwan
TSMC and United Microelectronics Corporation are expanding EUV lithography capacity that demands ISO Class 1-3 environments with sub-0.1 micron particulate control. The National Development Council's chip industry incentives accelerate fab construction timelines in Hsinchu and Tainan Science Parks. HEPA filter suppliers are localizing PTFE membrane production to meet procurement specifications from foundry operators.
South Korea
Samsung Foundry and SK Hynix are driving HEPA filtration upgrades for 3nm process nodes that exceed legacy microglass performance thresholds. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative subsidizes cleanroom infrastructure in Pyeongtaek and Yongin clusters. Domestic engineering firms are capturing turnkey installation contracts previously awarded to European providers.
Germany
Boehringer Ingelheim and Merck KGaA are retrofitting aseptic processing lines to comply with EMA's revised EU GMP Annex 1 barrier isolator mandates. The country's national pharmaceutical regulator enforces Grade A/B processing standards for sterile injectables that exceed prior environmental classifications. Baden-Württemberg and Bavaria host the densest concentration of modular cleanroom engineering specialists serving European biologics manufacturers.
United States
Gene therapy CDMOs in Boston-Cambridge and Research Triangle Park are leasing modular cleanroom suites to preserve capital for clinical pipeline investment. FDA 21 CFR Parts 210-211 cGMP regulations mandate continuous environmental monitoring for viral vector production facilities. The Southeast cluster around North Carolina's Research Triangle is posting the fastest deployment velocity for softwall cleanroom rentals.
India
Dr. Reddy's Laboratories and Biocon are expanding Grade A/B filling capacity for export-oriented biologics manufacturing. CDSCO's alignment with PIC/S guidelines and the PLI scheme for active pharmaceutical ingredients create procurement incentives for isolator technology in Hyderabad and Ahmedabad. Domestic cleanroom fabricators in these clusters are displacing European turnkey providers on mid-scale pharmaceutical projects.
Cleanroom Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with filtration media and modular enclosure markets consolidating around polymer science leaders while turnkey installation remains fragmented across regional engineering firms. Three archetypes dominate competitive positioning: integrated infrastructure providers bundling design-build-validate services, component specialists commanding premium pricing through certification depth, and regional fabricators competing on deployment velocity and lease financing flexibility. M&A activity concentrates among filtration media producers seeking backward integration into PTFE resin supply, while capacity expansion dominates among Asian turnkey providers building local installation teams.
Within the integrated infrastructure tier, Exyte Group anchors large-scale semiconductor fab projects through turnkey delivery capability. DuPont occupies a position in fluoropolymer barrier fabrics that dominate pharmaceutical garment specifications. Camfil exemplifies the certification-depth archetype, operating accredited laboratories that validate HEPA performance claims to ISO 12500 protocols. These three companies represent distinct competitive vectors: project-scale execution, materials science leadership, and testing authority.
| Leading Market Players |
|---|
| Exyte Group |
| DuPont |
| Illinois Tool Works |
| Thermo Fisher Scientific |
| AAF International |
| Camfil |
| Ansell |
| Terra Universal |
| Angstrom Technology |
| Others |
Value Network & Pricing Analysis
ISO 14644-1 certified technician pools in Germany and Taiwan create labor-cost differentials that widen pricing spreads between premium EN 1822-validated HEPA systems and standard-grade alternatives. The scarcity of qualified cleanroom commissioning engineers in South Korea and the United States concentrates pricing power with turnkey providers bundling installation and validation services.
Pricing Analysis
Volume placements of standard HEPA filters run on thin margins while premium PTFE membrane systems and validated isolator suites capture expanded spreads. Three-tier pricing structure across premium, standard, and economy levels separates EN 1822-certified pharmaceutical-grade filtration from industrial microglass designs and unvalidated research-grade alternatives. Cost compression in standard HEPA tiers is intensifying because Chinese domestic fabricators are displacing European suppliers on fixed-price municipal contracts. CDMOs and emerging biotechs in Boston-Cambridge exhibit highest price sensitivity through equipment-as-a-service leasing preferences, while semiconductor foundries in Taiwan show lowest sensitivity due to zero-failure tolerance specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fab demand from TSMC and Samsung Foundry, while distributor networks serve mid-scale pharmaceutical installations. Geographic supply concentration centers on China for high-purity aluminum ceiling grid extrusions, South Korea for specialty fluoropolymer resin production, and Germany for precision HVAC component fabrication. Raw material dependencies rest on PTFE resin feedstocks, microglass fiber media, and specialty aluminum alloys. Single-source vulnerability in Chinese smelter capacity for pharmaceutical-grade aluminum framing creates structural exposure to export restriction risks. Distribution runs through regional engineering firms for turnkey installation and accredited filter laboratories for certification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cleanroom technician scarcity across Taiwan, South Korea, and Germany props pricing for bundled installation-validation services. This capacity bottleneck sustains margin premiums for integrated infrastructure providers against component specialists.
For Market Incumbents: Lock in backward integration into PTFE resin supply to secure fluoropolymer filter media margins against feedstock volatility. Capture capacity addition in India through Hyderabad and Ahmedabad installation teams before domestic fabricators consolidate. Certification investment in ISO 12500 testing protocols defends position against emerging entrants lacking accredited laboratory infrastructure. For New Entrants and Emerging Players: Launch via equipment-as-a-service leasing models targeting venture-funded biotechs in Research Triangle Park with cash-flow-sensitive procurement preferences. White-space targets include softwall cleanroom rentals for cell therapy CDMOs and continuous particle monitoring retrofit sensors for legacy pharmaceutical suites. The most penetrable segment is mid-scale Grade A/B isolator installations where European turnkey providers face displacement pressure from domestic Indian engineering firms. For Investors and Strategic Acquirers: Re-rating potential sits with fluoropolymer materials specialists given PTFE membrane substitution acceleration in EUV lithography filtration. Long-term viability over the next decade favors targets with captive resin supply and EN 1822 certification depth rather than pure-play installation contractors. The signal to watch is foundry procurement specification shifts toward sub-0.1 micron PTFE-based filters as 2nm process nodes approach.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTFE Resin Supply | Secures fluoropolymer filter margins against volatile feedstock markets in China and South Korea. |
| ISO 12500 Testing Laboratory Accreditation | Validates HEPA performance claims for pharmaceutical and semiconductor procurement specifications. |
| Equipment-as-a-Service Leasing Model | Captures CDMO demand in Boston-Cambridge and Research Triangle Park clusters. |
| Continuous Particle Monitoring Sensor Networks | Addresses draft ISO 14644-2 revisions signaling real-time environmental monitoring mandates. |
| India Domestic Installation Capacity Buildout | Captures PLI scheme-driven pharmaceutical cleanroom demand in Hyderabad and Ahmedabad. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cleanroom engineering directors, pharmaceutical facility managers, semiconductor fab procurement leads, and HEPA filter certification specialists combined with secondary validation from FDA 21 CFR filings, EMA Annex 1 guidance documents, NMPA GMP revisions, and ISO 14644-1/2 draft standards. Bottom-up equipment shipment tracking and top-down facility investment analysis provided triangulation across the analysis window.
Data-stream reconciliation across equipment vendor shipment reports, fab construction timelines from Taiwan and South Korea, and pharmaceutical facility expansion announcements in India and Germany enabled segmentation modeling. Dimensions include product type, end user, technology, application, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, capacity expansion schedules, and regulatory compliance deadlines. Industry-specific inputs encompass EUV lithography node transitions, gene therapy manufacturing scale-up, and PIC/S guideline convergence.
Raw material supply disruptions, regulatory timeline acceleration, and qualified technician availability are the dominant revision risks for forecast outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Pin Insertion Machine Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Laser Drilling Market