
 Europe Fusion Splicer Market | 2026-2036
Europe Fusion Splicer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fusion Splicer Market Intelligence
The EU Green Deal is decoupling energy-efficient network infrastructure from legacy deployment economics across Europe. Fujikura leverages its R&D intensity in core alignment architectures to sustain premium positioning in German and French backbone projects. Sumitomo Electric anchors its European presence through specialized ribbon fiber splicing systems for dense metropolitan builds. Nexans competes by controlling regional distribution channels and localized technical service capabilities.
A fusion splicer is a precision instrument that thermally joins optical fibers by melting their glass cores and cladding under controlled electric arc discharge, typically achieving splice losses below 0.05 dB for single mode fibers. The device serves the fundamental commercial purpose of creating low-loss, high-mechanical-strength connections in fiber optic networks where connector-based termination proves insufficient or cost-prohibitive. Core alignment systems command the dominant share of European procurement for long-haul and FTTH backbone work due to their superior accuracy with single mode fibers. Ribbon fiber technology represents the fastest-growing configuration as France, Italy, and Spain accelerate multi-fiber cable deployments in urban corridors. Manual splicers occupy a shrinking but persistent niche in developing Eastern European markets where labor costs offset automation premiums.
CE marking under the EU Radio Equipment Directive and REACH compliance for electronic component materials shape product design and market access requirements for all suppliers distributing within the European Economic Area. ECHA substance restrictions and national spectrum regulators in Germany and France further constrain material choices and electromagnetic emission profiles. Stakeholders must monitor the interplay between EU Green Deal procurement mandates and evolving F-Gas Regulation interpretations affecting thermal management systems in field-portable splicer designs.
Market Dynamics
The EU Green Deal's binding digital infrastructure targets are forcing telecommunication operators across Germany and France to accelerate fiber-to-the-home deployments, creating sustained procurement pressure for precision splicing equipment in backbone network construction.
Growth Catalysts
- EU Green Deal procurement mandates:Binding digital infrastructure targets require energy-efficient fiber networks, directing capital toward low-loss splicing systems that minimize signal regeneration needs.
- Ribbon fiber cable technology:Multi-fiber ribbon configurations reduce deployment labor by enabling simultaneous splicing of 4-12 fibers, accelerating metropolitan corridor builds in France and Italy.
- German backbone expansion:Deutsche Telekom and regional carriers are replacing copper with single-mode fiber trunk lines, generating concentrated demand for core alignment splicers.
Market Restraints
- Precision electrode supply concentration:Tungsten-rhenium electrodes for arc discharge systems depend on limited Central European foundry capacity, creating input cost volatility.
- F-Gas Regulation thermal management constraints:Interpretations affecting cooling systems in portable field units restrict design flexibility and extend certification timelines.
- Skilled technician scarcity:Specialized fiber preparation and splice protection skills remain concentrated in Western European labor pools, constraining deployment velocity in Eastern Europe.
Strategic Opportunities
- Polish and Romanian FTTH underpenetration:Eastern European markets show fiber penetration gaps of 40-60 percentage points versus Western benchmarks, creating whitespace for equipment vendors.
- EU AI Act network infrastructure provisions:Emerging requirements for low-latency data transmission infrastructure favor high-performance splicing in edge computing backbone links.
- Rental and service-subscription models:Project-based contractors in Spain and Portugal increasingly prefer operational expenditure structures over capital equipment purchases.
Industry Challenges
- REACH substance compliance complexity:ECHA restrictions on electronic component materials require continuous reformulation of circuit boards and housing polymers.
- CE marking timeline under RED:EU Radio Equipment Directive certification for electromagnetic emission profiles adds 4-6 months to product launch schedules.
- Legacy copper technician retraining:Workforce transition from electrical to optical fiber installation creates productivity gaps during skill acquisition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fusion Splicer Market |
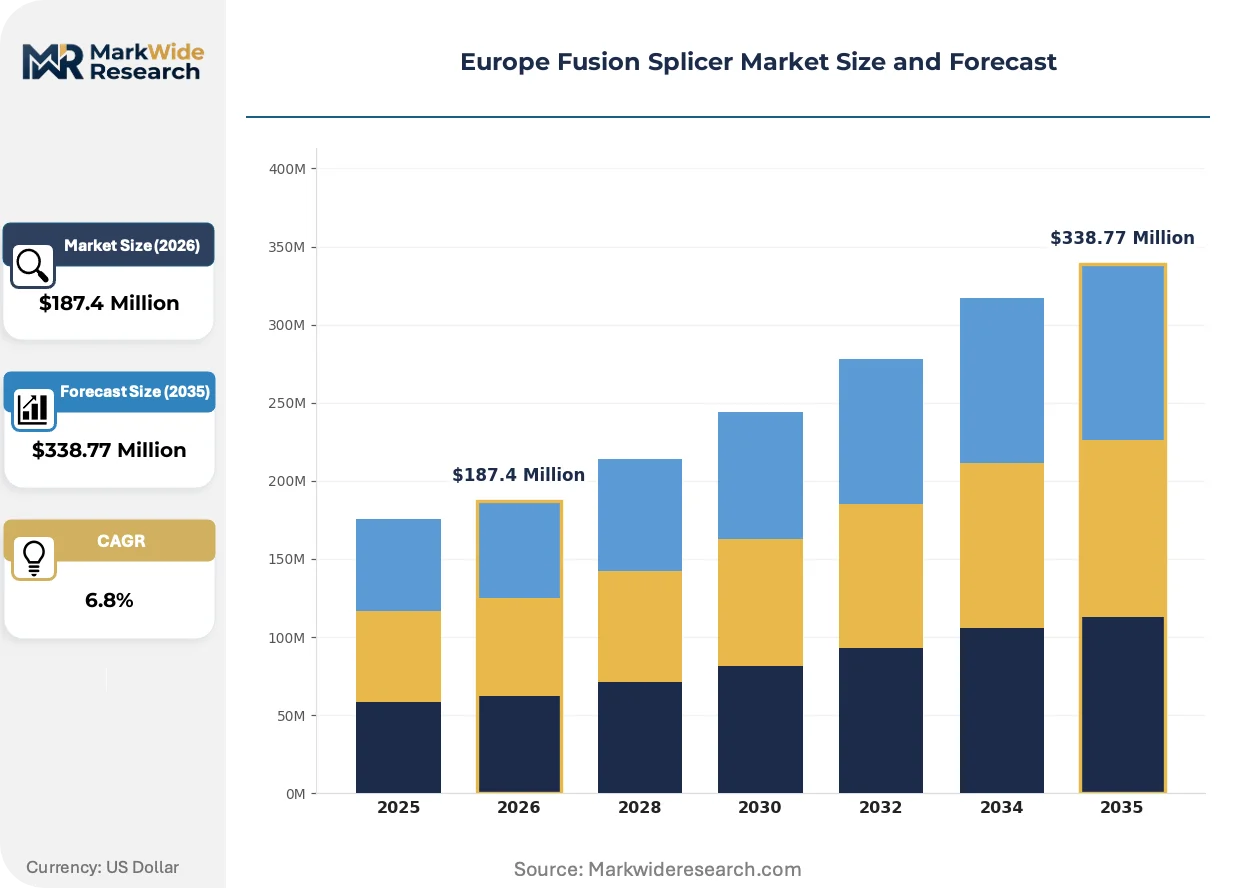
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Alignment, Cladding Alignment, Automated, Manual End User: Telecommunication, Cable TV, Government, Educational Institutions Technology: Single Mode, Multi Mode, Specialty Fiber, Ribbon Fiber Application: Fiber Optic Installation, Maintenance, Testing, Networking |
| Companies Covered | Fujikura, Sumitomo Electric, Furukawa Electric, Nexans, Nokia, Optotec, Ilsintech, INNO Instrument, Darkhorsechina, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fusion Splicer Market Strategic Shifts & Innovations
Active alignment algorithms and automated fiber recognition are compressing splice cycle times while reducing operator skill dependencies. Equipment vendors are embedding predictive maintenance capabilities through onboard diagnostics.
Active cladding alignment systems are expanding into metropolitan access networks previously served by manual or fixed v-groove equipment. French and Italian contractors deploying dense urban fiber are adopting these systems to maintain splice quality with less experienced field technicians. The technology is expanding into mid-tier procurement categories, eroding the traditional premium-standard equipment boundary.
REACH substance restrictions under ECHA oversight are forcing material transitions in electronic housings and thermal management components. Manufacturers must reformulate polymers and cooling fluids to maintain market access. German and French national regulators are enforcing these constraints with particular rigor, delaying product launches for non-compliant suppliers.
Spanish and Portuguese contractors are unbundling after-sales service from equipment purchase, preferring third-party calibration and maintenance providers. Traditional vendor-captive service models are losing share to independent technical service networks. This pattern is most visible in Iberian markets where project-based procurement dominates over operator fleet ownership.
Europe Fusion Splicer Market Segmentation
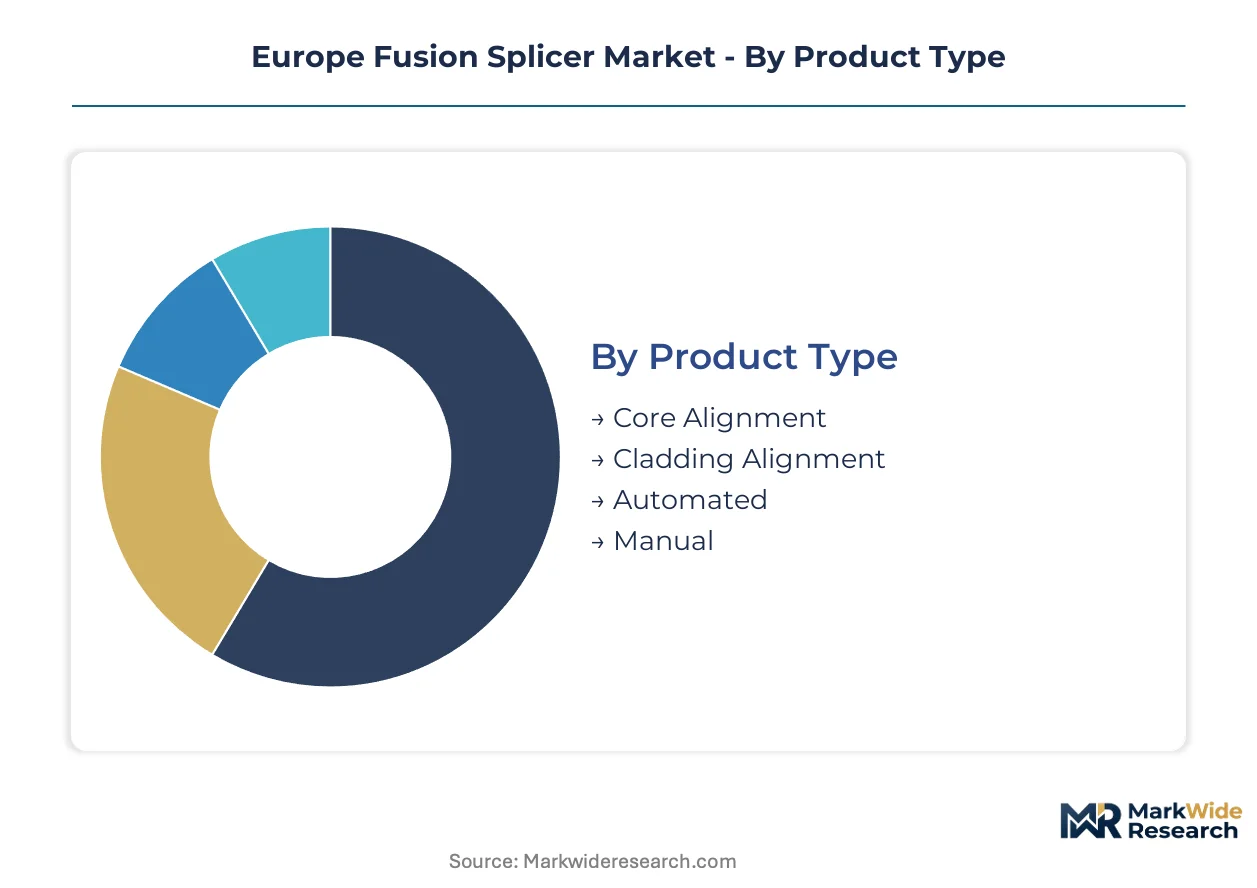
Equipment configuration choices in the European fusion splicer market carry substantial capital implications, with precision alignment systems commanding premium procurement budgets while manual units serve cost-constrained deployment scenarios. Network operators balance splice accuracy requirements against total cost of ownership across diverse infrastructure build-outs.
Product Type:
Capital intensity varies sharply across alignment architectures, with automated core alignment systems requiring the highest upfront investment but delivering lowest per-splice operational costs at scale.
- Core Alignment:Electro-mechanical systems position fiber cores using microscopic imaging and piezoelectric actuators, achieving splice losses below 0.05 dB. Deutsche Telekom and Orange SA specify these units for backbone trunk lines where signal regeneration costs dominate lifecycle economics.
- Cladding Alignment:Fixed v-groove mechanisms align outer cladding surfaces rather than cores, trading accuracy for speed and cost. French metropolitan contractors deploy these for last-mile drops where splice loss tolerance exceeds 0.1 dB.
- Automated:Self-contained units with embedded processors eliminate operator judgment from fiber positioning and arc timing. German network integrators favor these for standardized crew performance across dispersed project sites.
- Manual:Operator-dependent systems with minimal automation suit Eastern European markets where labor rates offset equipment premiums and deployment volumes remain modest.
Most installed capacity flows through Core Alignment. Expansion is steepest in Automated.
End User:
Customer type determines procurement scale and service attachment rates, with national operators buying fleet quantities while institutional users purchase single units with extended warranty terms.
- Telecommunication:Incumbent carriers and alternative network operators constitute the dominant demand pool, purchasing core alignment systems in volume for FTTH backbone construction mandated under EU Green Deal timelines.
- Cable TV:Hybrid fiber-coaxial upgrade programs in Spain and Portugal generate concentrated demand for ribbon fiber capable units serving multi-dwelling connection density.
- Government:Defense and transport infrastructure agencies specify ruggedized portable units with extended calibration intervals for field maintenance operations.
- Educational Institutions:Technical universities and vocational training centers purchase entry-level cladding alignment systems for fiber optics curriculum delivery.
Telecommunication operators deploy the greatest equipment volume. Government procurement is climbing the fastest as sovereign network infrastructure programs accelerate.
Technology:
Fiber geometry specifications dictate splicer optical configuration and electrode design, with single mode systems requiring precision core alignment while multi mode tolerates simpler cladding-based positioning.
- Single Mode:Small core diameter (8-10 micron) fibers demand sub-micron alignment accuracy for long-haul and high-speed data transmission. German backbone expansion programs concentrate demand for these precision systems.
- Multi Mode:Larger core diameter (50-62.5 micron) fibers suit shorter-reach enterprise and data center interconnects where alignment tolerance relaxes and splicing speed takes priority.
- Specialty Fiber:Polarization-maintaining, erbium-doped, and other non-standard geometries require customized arc parameters and specialized electrode profiles for research and sensing applications.
- Ribbon Fiber:Multi-fiber flat ribbons enable simultaneous splicing of 4-12 fibers, reducing labor hours in dense French and Italian urban corridor deployments.
Single Mode systems account for the largest installed base. Ribbon Fiber is gaining share fastest as metropolitan density requirements intensify.
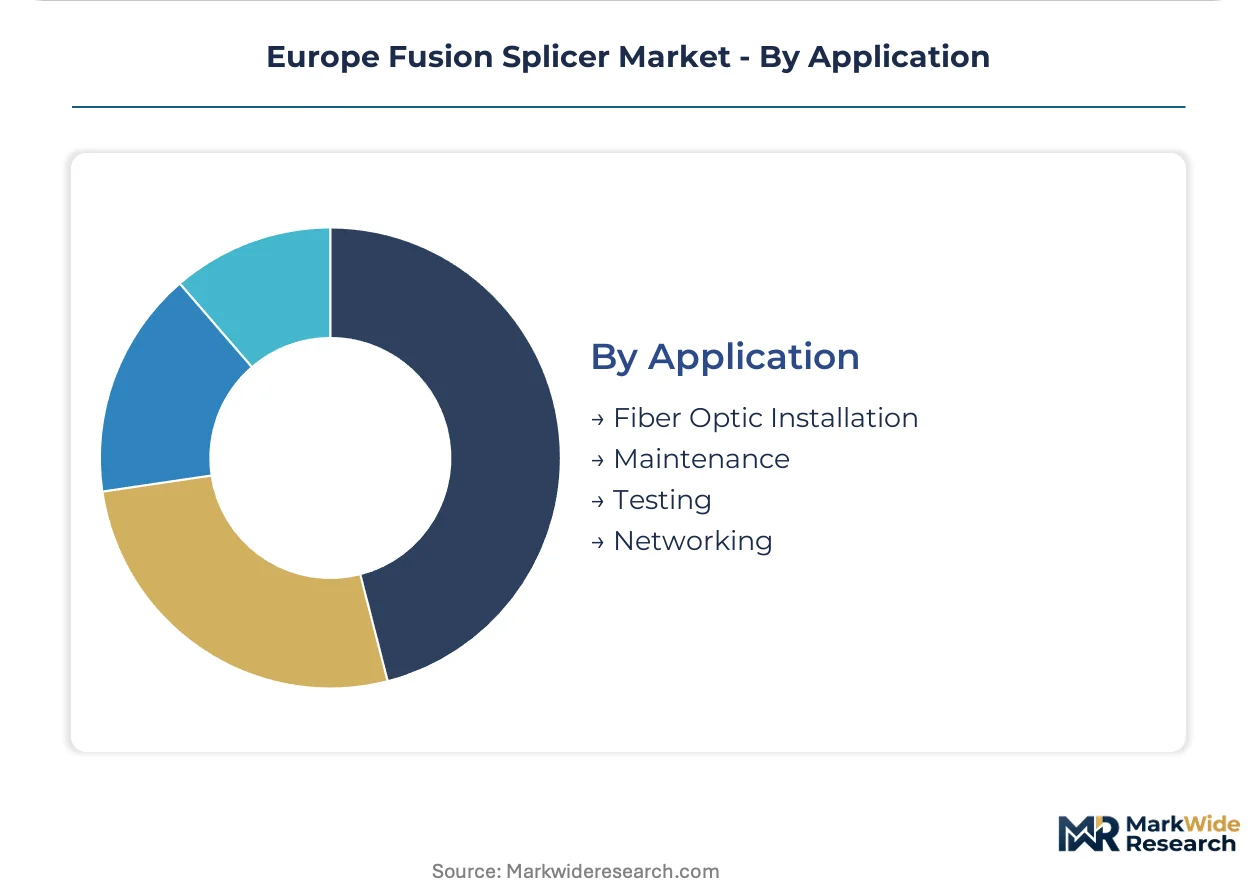
Application:
Use case determines equipment mobility requirements and environmental hardening, with installation crews needing field-portable units while testing applications prioritize bench-top precision.
- Fiber Optic Installation:Greenfield deployment drives the core equipment market, with French and German contractors specifying dust-resistant portable units for trench and aerial installation environments.
- Maintenance:Repair and restoration operations require rapid-deployment systems with pre-stored splice programs for common fiber types, prioritizing reliability over cutting-edge features.
- Testing:Laboratory and certification applications demand highest-precision core alignment with integrated loss measurement and documentation capabilities for quality assurance protocols.
- Networking:Enterprise and data center interconnect work favors compact units with short heat-shrink ovens for confined rack-space splicing operations.
Installation consumes the majority of equipment shipments. Networking applications show the steepest expansion trajectory as edge computing infrastructure multiplies interconnection points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled fiber optic technicians concentrate in Western European labor pools, creating deployment velocity gaps as Eastern European FTTH expansion accelerates. This talent asymmetry shapes procurement patterns and service model preferences across national markets.
Germany
Deutsche Telekom and regional carriers are replacing copper trunk lines with single-mode fiber backbone networks under EU Green Deal timelines. The Federal Network Agency enforces strict electromagnetic compatibility standards through CE marking requirements under the EU Radio Equipment Directive. Bavaria and North Rhine-Westphalia host the densest concentrations of network construction activity, with Munich-based contractors specifying core alignment systems for standardized crew deployment.
France
Orange SA and alternative network operators are accelerating metropolitan corridor builds using ribbon fiber cable technology for multi-dwelling unit density. ANSM and national spectrum regulators enforce REACH compliance and electromagnetic emission constraints with particular rigor on imported equipment. The Île-de-France region around Paris and the Provence-Alpes-Côte d'Azur corridor show the steepest equipment procurement growth as urban fiber penetration targets tighten.
Italy
Open Fiber and infrastructure investors are deploying dense urban fiber networks requiring simultaneous multi-fiber splicing capabilities. ECHA substance restrictions under REACH compliance frameworks delay product launches for non-compliant housing polymers and cooling fluids. Northern industrial clusters in Lombardy and Emilia-Romagna concentrate procurement activity, with Milan-based contractors driving adoption of automated alignment systems for less experienced field crews.
Spain
Project-based contractors in Madrid and Barcelona are unbundling after-sales service from equipment purchase, preferring third-party calibration providers over vendor-captive models. The Spanish national regulator enforces CE marking timelines that add certification months to product launch schedules. Catalonia and the Madrid metropolitan area show the strongest shift toward operational expenditure structures and rental-subscription procurement models.
Poland
Fiber penetration gaps of 40-60 percentage points versus Western benchmarks create whitespace for equipment vendors targeting underpenetrated regional markets. Polish national procurement regulations align with EU Green Deal mandates but apply less stringent electromagnetic emission enforcement than German or French counterparts. The Warsaw metropolitan area and Silesian industrial corridor concentrate emerging demand as state-backed broadband programs accelerate trenching and aerial installation contracts.
Europe Fusion Splicer Market Key Industry Players
The competitive structure tilts toward precision alignment specialists with established technical service networks. Japanese and European incumbents anchor premium-tier positioning through core alignment R&D intensity and localized calibration capabilities. Three archetypes dominate: integrated fiber infrastructure conglomerates with captive splicer distribution, specialized precision equipment manufacturers with regional service subsidiaries, and emerging Asian fabricators competing on cost-adjusted feature sets. Dominant competitive moves include strategic partnerships with national operators for fleet standardization and geographic expansion through third-party technical service networks.
Among Japanese precision equipment specialists, Fujikura and Sumitomo Electric exemplify the R&D-intensive archetype with sustained positioning in German and French backbone projects. Nexans occupies a distinct position as a European-integrated cable and connectivity conglomerate with controlled regional distribution channels. These three anchors demonstrate how technical service proximity and regulatory compliance familiarity create defensive positioning against cost-focused entrants.
| Leading Market Players |
|---|
| Fujikura |
| Sumitomo Electric |
| Furukawa Electric |
| Nexans |
| Nokia |
| Optotec |
| Ilsintech |
| INNO Instrument |
| Darkhorsechina |
| Others |
Cost & Logistics Intelligence
Tungsten-rhenium electrode spot prices in Central European foundry markets cascade through fusion splicer manufacturing tiers, compressing margins on cladding alignment systems while insulating core alignment premiums through precision-grade scarcity.
Pricing Analysis
The bundled-vs-unbundled service split stratifies procurement economics across European markets. Core alignment systems with vendor-captive calibration contracts command premium positioning against unbundled equipment sales to Iberian contractors. Price differentiation hinges on CE marking tier and after-sales service attachment rates. Cost compression in manual and cladding alignment tiers intensifies as Asian fabricators expand distribution through independent technical service networks. Eastern European contractors exhibit highest price sensitivity due to project-based procurement structures, while German backbone operators prioritize lifecycle cost over upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with tungsten-rhenium electrode foundries concentrated in Germany and Austria. Precision arc discharge components draw from limited Central European metallurgical capacity, with ceramic ferrule and piezoelectric actuator supply anchored in Japan and South Korea. Regulatory restriction through REACH substance compliance and F-Gas thermal management constraints constrains alternative sourcing. Distribution runs through manufacturer-direct fleet sales to national operators, supplemented by specialized distributors serving project-based contractors in Southern and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe fusion splicer market functions as a stable compounder, with EU Green Deal infrastructure mandates generating predictable procurement cycles across national operator fleets.
For Market Incumbents: Cement defensive positioning through backward integration into electrode supply and captive calibration service networks. Threats from cost-optimized Asian entrants intensify in manual and cladding alignment tiers; counter through CE marking acceleration and localized technical service density in German and French backbone corridors. For New Entrants and Emerging Players: Automated fiber recognition algorithms offer a technology-first wedge into mid-tier metropolitan access networks previously served by fixed v-groove equipment. Polish and Romanian FTTH whitespace presents the most penetrable geography; enter through rental-subscription models aligned with project-based contractor preferences. For Investors and Strategic Acquirers: Asymmetric upside sits with precision equipment specialists possessing regional service subsidiaries and regulatory compliance familiarity. Long-term viability favors core alignment R&D intensity over commodity manual fabrication; watch for inflection in Eastern European skilled technician training program enrollment as capacity expansion signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Subsidiary Expansion | Proximity calibration capabilities lock in German and French operator fleet standardization decisions. |
| Automated Alignment Algorithm Development | Active cladding systems erode premium-standard boundary in dense urban corridor deployments. |
| REACH-Compliant Material Reformulation | ECHA substance restrictions delay non-compliant competitors across German and Italian launches. |
| Rental-Subscription Model Launch | Operational expenditure structures capture Spanish and Portuguese project-based contractor demand. |
| Third-Party Technical Service Partnership | Independent calibration networks unbundle after-sales revenue from equipment sales in Iberia. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured network construction directors at Deutsche Telekom and Orange SA, procurement leads at Polish alternative network operators, fiber installation contractors across French metropolitan corridors, and calibration service technicians in Spanish distribution networks. Secondary validation drew from EU Radio Equipment Directive certification databases, ECHA REACH substance restriction filings, national spectrum regulator emission standards, and operator capex disclosure filings. Bottom-up equipment shipment estimates and top-down infrastructure investment flows were triangulated against vendor-reported regional revenue allocations.
Segment-weighting approaches distributed total market value across alignment architecture tiers, end-user categories, fiber geometry specifications, and application use cases. The analytical framework modeled unit economics and replacement cycles across the projection horizon. CAGRs were derived from infrastructure investment trajectories under EU Green Deal timelines and fiber penetration gap closure assumptions in Eastern European markets. Forecast inputs incorporated skilled technician labor pool growth rates and ribbon fiber cable deployment acceleration in dense urban corridors.
The model holds under stable EU regulatory enforcement and continued operator capex commitment to FTTH targets; deviation in REACH substance restriction scope or F-Gas thermal management interpretations would shift equipment certification timelines and geographic launch sequencing. Forecasts reflect documented assumptions on infrastructure investment continuity and supply chain input cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Asia-Pacific Electro Hydraulic Servo Valve Market
Industrial Equipment
Precision Machine Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Precision Positioning Equipment Market