
 Air Preparation Equipment (FRL) Market | 2026-2036
Air Preparation Equipment (FRL) Market Size, Share, and Industry Trends Forecast 2026-2036
Air Preparation Equipment (FRL) Market Insights
Multi-source procurement for precision pneumatic components is repositioning how tier-one automation suppliers manage supply risk. SMC Corporation leverages its integrated manufacturing footprint across Asia to sustain cost-competitive output of combination FRL units. Festo anchors European demand through deep channel control in German automotive OEM supply chains. Parker Hannifin differentiates via technology leadership in electro-pneumatic monitoring interfaces that extend service intervals and reduce unplanned downtime.
Air preparation equipment (FRL) comprises filter-regulator-lubricator assemblies and ancillary conditioning modules engineered to remove particulate contamination, stabilize operating pressure, and inject atomized oil into compressed air systems serving pneumatic actuators and control valves. Typical filtration ratings span five to forty microns with operating pressures from zero to sixteen bar, depending on industrial duty cycle requirements. Combination units dominate volume shipments due to space-constrained installations in manufacturing plants, while digital monitoring technology captures the fastest expansion as IoT-enabled pressure and flow sensors enable predictive maintenance protocols. Electro-pneumatic interfaces command premium positioning where pharmaceutical manufacturers and electronics assemblers require real-time air quality validation for cleanroom compliance.
ISO 8573 air quality classes, OSHA compressed air safety standards, and REACH substance restrictions collectively shape FRL material selection, filtration performance claims, and market access requirements for suppliers serving regulated industries. FDA validation protocols for pharmaceutical manufacturing air systems further tighten specification windows for filter media and lubricant chemistries in North American supply chains. Stakeholders must monitor evolving energy-efficiency mandates and digital certification requirements as compressed air system optimization becomes embedded in broader factory sustainability targets.
Market Dynamics
Automotive OEMs in Germany are forcing compressed air system upgrades across tier-one supplier networks as electric vehicle assembly lines demand tighter pneumatic precision for battery module handling and lightweight body-in-white joining operations.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are compelling manufacturers to redesign FRL seals and diaphragms with low-permeability elastomers compatible with synthetic ester lubricants.
- Electronics assemblers:Semiconductor fabrication facilities in South Korea and Taiwan are specifying ISO 8573-1 Class 1.2.1 air quality, driving demand for ultrafine filtration and activated carbon adsorption stages.
- IoT-enabled predictive maintenance:Pressure differential sensors with Modbus TCP/IP connectivity are capturing fastest expansion as plant engineers seek to eliminate unplanned downtime in continuous-process industries.
Market Restraints
- Aluminum die-cast body costs:Raw material volatility in primary aluminum ingot pricing compresses margin structures for mid-tier combination FRL manufacturers lacking backward integration into casting operations.
- Filter media supply concentration:Borosilicate glass microfiber production for sub-five-micron ratings clusters among a narrow set of German and Japanese specialty paper converters, creating single-source vulnerability.
- Compressed air system substitution:Electric linear actuators with integrated servo drives are displacing pneumatic cylinders in precision positioning applications below 500mm stroke lengths.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for industrial machinery are attracting FRL suppliers to establish local assembly for textile and food processing automation clusters in Gujarat and Tamil Nadu.
- Pharmaceutical aseptic filling:Steam-sterilizable FRL units with 316L stainless steel construction are opening premium positioning as biologics manufacturing expands in Switzerland and Singapore.
- Digital twin convergence:Integration of FRL sensor data with Siemens MindSphere and Rockwell FactoryTalk platforms is enabling outcome-based compressed air efficiency contracts.
Industry Challenges
- Cross-functional commissioning expertise:Deployment of electro-pneumatic FRL units requires technicians fluent in both pneumatic hardware and industrial Ethernet protocols, a skill combination scarce in Midwest US manufacturing regions.
- FDA validation timelines:Pharmaceutical air system qualification under 21 CFR Part 211 extends procurement cycles to 18-24 months, straining working capital for project-driven FRL suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Preparation Equipment (FRL) Market |
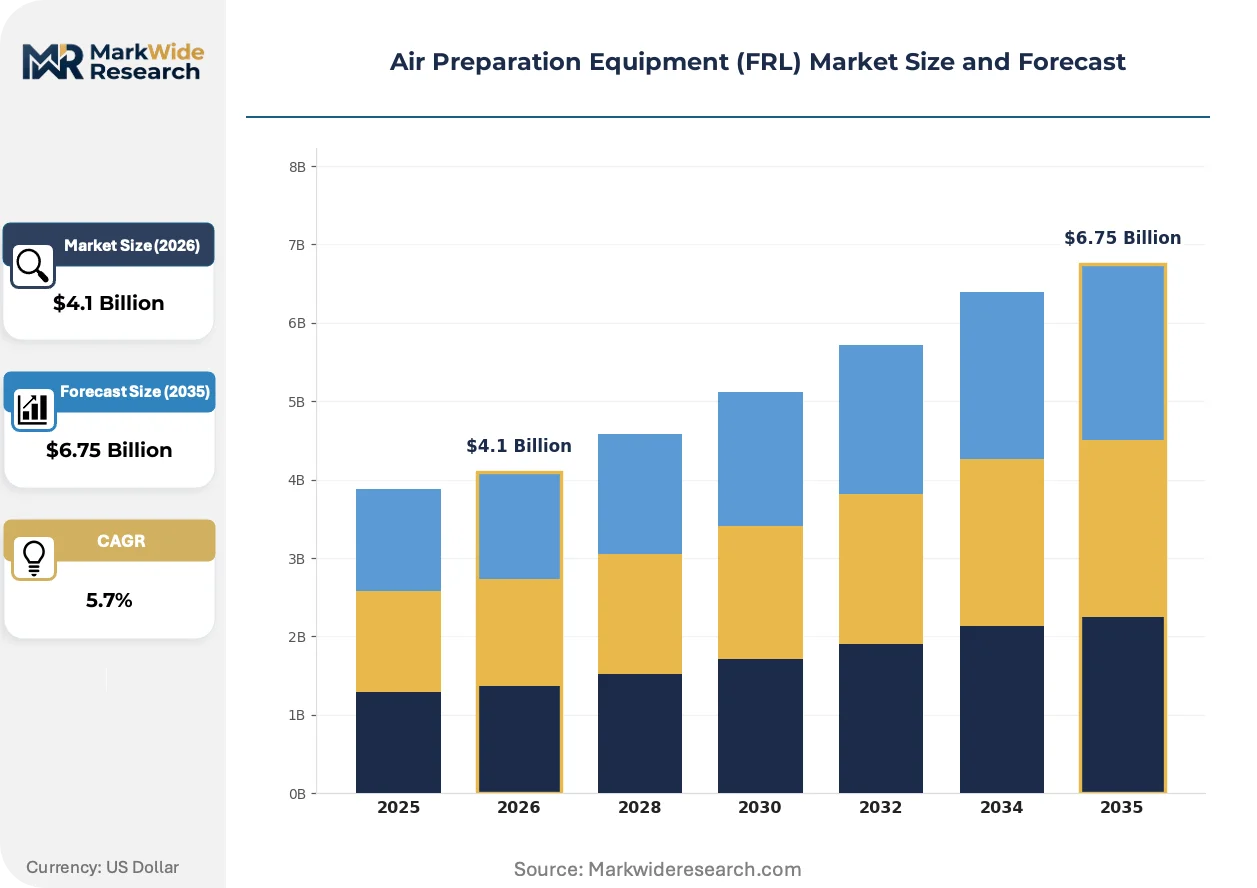
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.75 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filters, Regulators, Lubricators, Combination Units, Air Dryers Technology: Pneumatic Control, Electro-Pneumatic, Mechanical, Digital Monitoring Application: Manufacturing Plants, Packaging Systems, Material Handling, Laboratory Equipment, Food Processing End User Industry: Automotive OEMs, Electronics Assemblers, Pharmaceutical Manufacturers, Chemical Producers, Textile Fabricators |
| Companies Covered | Emerson, Norgren, SMC Corporation, CKD Corporation, CEJN AB, Atlas Copco, Festo, HAFNER Pneumatik, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Preparation Equipment (FRL) Market Trends and Innovations
Pneumatic conditioning hardware is absorbing digital intelligence at the component level, transforming standalone FRL units into networked edge devices that feed factory-wide energy management platforms.
Membrane air drying technology is absorbing moisture removal duties traditionally assigned to refrigerated dryers in point-of-use applications. Food packaging OEMs in the Netherlands and Denmark are specifying hollow-fiber membrane modules for their compact footprint and zero electrical consumption. This absorption is compressing the addressable market for desiccant dryer suppliers in sub-50-scfm installations.
REACH substance restrictions on polycyclic aromatic hydrocarbons are forcing reformulation of nitrile rubber seals and diaphragms used in FRL pressure regulators. Compounders serving the pneumatics industry are accelerating validation of hydrogenated nitrile butadiene rubber alternatives. German automotive OEM supply chains are experiencing the tightest specification windows as they reconcile material compliance with extended temperature range requirements.
Buyers are consolidating pneumatic component procurement under single-source framework agreements with integrated automation distributors. Machine builders in Northern Italy are abandoning spot purchasing through traditional wholesale channels in favor of vendor-managed inventory programs with annual spend commitments. This concentration is most pronounced among mid-size OEMs serving the packaging machinery sector.
Air Preparation Equipment (FRL) Market Segmentation
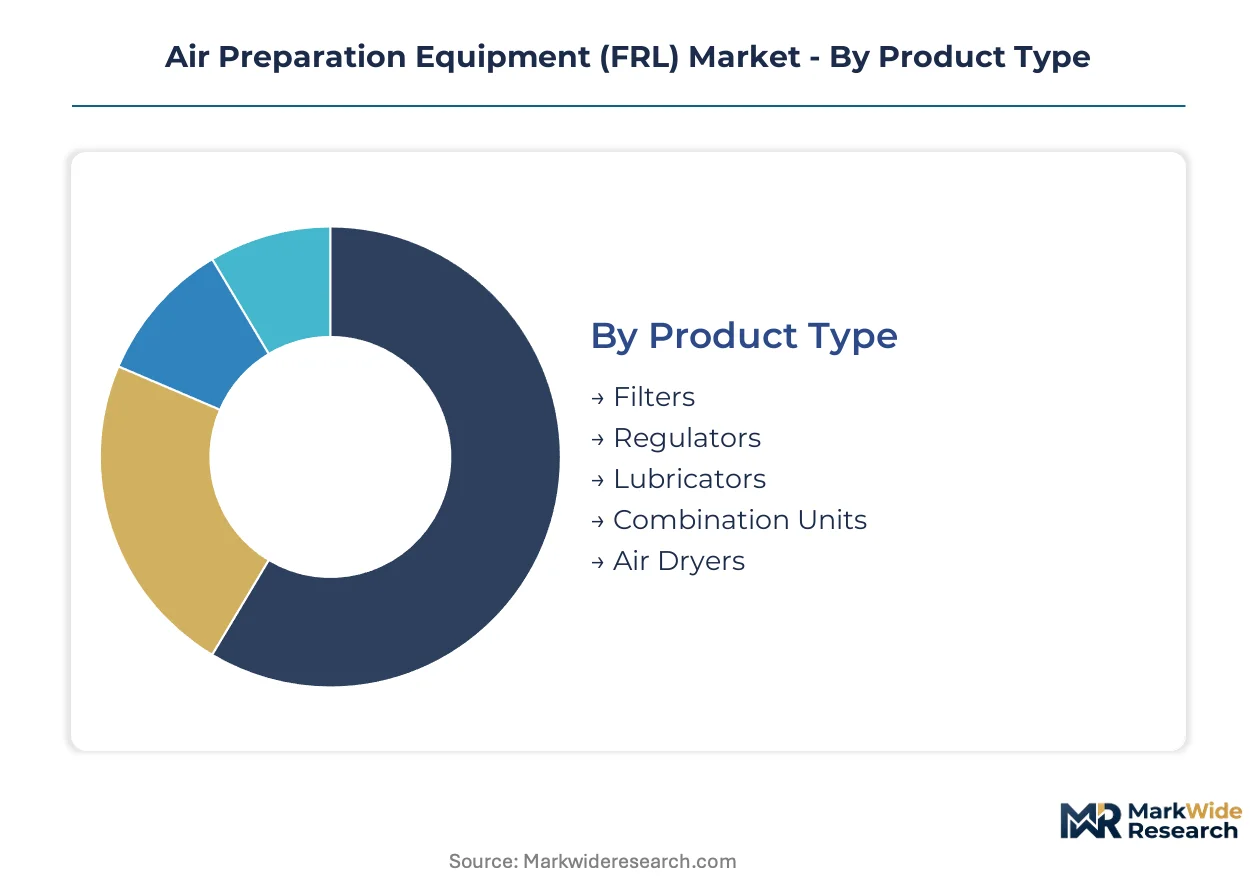
Segmentation in the Air Preparation Equipment (FRL) Market reflects divergent technical requirements across pneumatic duty cycles, from heavy industrial automation to precision cleanroom environments. Specification mismatches between product types and end-use applications create distinct procurement patterns that suppliers must navigate.
Product Type:
Filtration ratings and pressure stabilization architectures define the specification axis across FRL product categories.
- Combination Units:Integrated filter-regulator-lubricator assemblies consolidate three conditioning functions into space-optimized housings. Automotive OEMs in Germany specify these units for robotic welding cells where cabinet footprint constraints dominate equipment selection.
- Filters:Borosilicate glass microfiber media removes particulate contamination across five to forty micron ratings. Electronics assemblers in Taiwan demand sub-five-micron absolute ratings for semiconductor wafer handling systems.
- Regulators:Diaphragm-operated pressure control valves stabilize downstream pressure against inlet fluctuations. Chemical producers specify stainless steel construction for corrosive process environments.
- Lubricators:Venturi-effect oil injection systems atomize lubricant into compressed air streams. Textile fabricators in India deploy these for high-speed pneumatic looms requiring continuous tool lubrication.
- Air Dryers:Refrigerated and membrane technologies remove moisture to prevent actuator corrosion. Food packaging OEMs in the Netherlands specify hollow-fiber membrane modules for zero electrical consumption.
Combination Units lead on scale; Digital Monitoring within Technology leads on momentum.
Technology:
Control architectures span purely pneumatic actuation through fully networked electro-pneumatic interfaces, with cost tiers stratifying adoption.
- Digital Monitoring:IoT-enabled pressure differential sensors with Modbus TCP/IP connectivity feed predictive maintenance platforms. Pharmaceutical manufacturers in Switzerland specify these for real-time air quality validation in aseptic filling lines.
- Electro-Pneumatic:Solenoid-integrated FRL units enable remote pressure adjustment and flow profiling. Battery module handling systems in South Korean EV plants require this precision for lightweight component joining.
- Pneumatic Control:Traditional pilot-operated designs without electrical interfaces dominate legacy installations. Midwest US manufacturing regions maintain this base due to technician skill availability.
- Mechanical:Spring-loaded regulators and gravity-fed lubricators serve cost-sensitive applications. Textile clusters in Gujarat procure these for basic pneumatic tool circuits.
Pneumatic Control anchors volume; Digital Monitoring commands the steepest expansion trajectory.
Application:
Installation environments impose distinct air quality classes, flow rate demands, and maintenance access requirements.
- Manufacturing Plants:Continuous-process industries require FRL units with extended service intervals and redundant filtration stages. German machinery exporters specify premium combination units for export equipment reliability.
- Packaging Systems:High-cycle pneumatic actuation demands lubricated air with precise pressure control. Northern Italian OEMs consolidate procurement under vendor-managed inventory programs.
- Material Handling:Conveyor and pick-and-place systems prioritize compact FRL footprints. Singapore biologics facilities specify 316L stainless steel for steam-sterilizable installations.
- Laboratory Equipment:Analytical instrumentation requires ultra-clean air meeting ISO 8573-1 Class 1.2.1 specifications. Swiss pharmaceutical research centers drive demand for activated carbon adsorption stages.
- Food Processing:Direct and indirect food contact applications mandate FDA-compliant lubricants and filter media. Danish packaging OEMs specify membrane dryers to eliminate electrical ignition risks.
Manufacturing Plants dominate installed base; Laboratory Equipment exhibits the most rapid specification tightening.
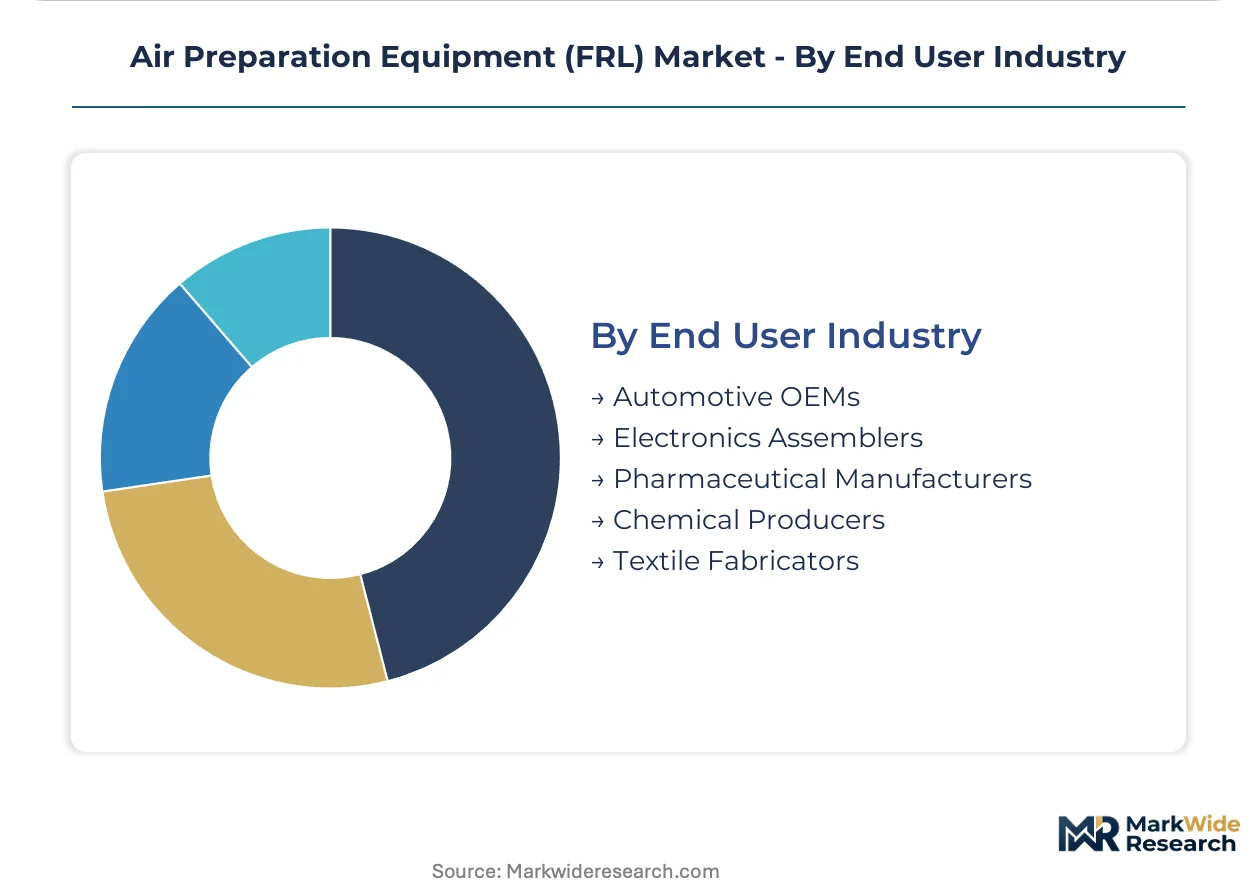
End User Industry:
Customer concentration patterns and procurement sophistication levels create divergent margin structures across verticals.
- Automotive OEMs:Tier-one supplier networks face forced compressed air upgrades for electric vehicle assembly precision. German OEMs enforce REACH-compliant seal specifications across their supply chains.
- Pharmaceutical Manufacturers:21 CFR Part 211 validation protocols extend procurement cycles to 18-24 months. Swiss and Singapore biologics expansion drives premium stainless steel FRL demand.
- Electronics Assemblers:Semiconductor fabrication requires Class 1.2.1 air quality with sub-micron filtration. South Korean and Taiwanese facilities specify the tightest contamination control.
- Chemical Producers:Corrosive process environments demand specialty elastomers and coated aluminum housings. EU F-Gas Regulation compliance redirects seal material selection toward synthetic ester compatibility.
- Textile Fabricators:High-speed loom automation in India benefits from PLI scheme machinery incentives. Gujarat and Tamil Nadu clusters attract local FRL assembly operations.
Automotive OEMs concentrate procurement volume; Pharmaceutical Manufacturers generate the highest unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEM supply chains command the highest specification density for precision FRL assemblies, with machinery export volumes sustaining premium equipment procurement across multiple continents.
Germany
Automotive OEMs in Stuttgart and Munich are forcing compressed air system upgrades across tier-one supplier networks for electric vehicle assembly precision. EU F-Gas Regulation phase-down schedules compel manufacturers to redesign seals with low-permeability elastomers compatible with synthetic ester lubricants. Baden-Württemberg machinery exporters specify REACH-compliant combination FRL units for battery module handling systems.
United States
Midwest manufacturing regions maintain substantial legacy pneumatic installations despite technician scarcity for electro-pneumatic commissioning. FDA validation protocols under 21 CFR Part 211 extend pharmaceutical air system procurement cycles to 18-24 months. Chicago-area packaging OEMs are consolidating component procurement under vendor-managed inventory programs with annual spend commitments.
China
Dual carbon goals and industrial energy-efficiency mandates are accelerating compressed air system optimization in Yangtze River Delta manufacturing clusters. GB standards for air quality classes shape filter media specifications for domestic semiconductor fabrication facilities. Shenzhen electronics assemblers specify ISO 8573-1 Class 1.2.1 compliance for wafer handling automation.
India
PLI scheme production-linked incentives for industrial machinery are attracting FRL suppliers to establish local assembly operations. BIS certification requirements govern filter performance claims in textile and food processing automation. Gujarat and Tamil Nadu clusters benefit from machinery incentives for high-speed pneumatic loom installations.
South Korea
Semiconductor fabrication facilities in Suwon and Pyeongtaek specify ISO 8573-1 Class 1.2.1 air quality with sub-micron filtration ratings. MFDS pharmaceutical manufacturing standards drive demand for steam-sterilizable stainless steel FRL construction. Battery module handling systems in Gyeonggi Province require electro-pneumatic precision for lightweight component joining operations.
Air Preparation Equipment (FRL) Market Competitive Landscape
Global majors compete with regional champions across technology integration and channel control dimensions. The vendor base stratifies into three tiers: integrated automation distributors with captive manufacturing, precision pneumatic specialists with deep vertical expertise, and regional fabricators serving cost-sensitive machinery builders. Dominant competitive moves include backward integration into aluminum die-casting operations and strategic partnerships for IoT platform integration.
Within the integrated automation tier, SMC Corporation and Festo occupy positions reflecting distinct geographic anchoring strategies. Parker Hannifin exemplifies technology-led differentiation through electro-pneumatic monitoring interfaces. Norgren represents European precision engineering heritage in filter-regulator-lubricator assemblies. Emerson and Atlas Copco sit within diversified industrial conglomerate structures that cross-sell compressed air solutions through existing energy and automation channels. CKD Corporation and CEJN AB exemplify specialist positioning in precision pneumatic connectivity and conditioning modules.
| Leading Market Players |
|---|
| Emerson |
| Norgren |
| SMC Corporation |
| CKD Corporation |
| CEJN AB |
| Atlas Copco |
| Festo |
| HAFNER Pneumatik |
| Parker Hannifin |
| Others |
Pricing and Supply Chain Analysis
Commissioning technicians fluent in both pneumatic hardware and industrial Ethernet protocols cluster in Germany's Baden-Württemberg region, creating labor-cost differentials that widen pricing spreads between electro-pneumatic premium tiers and mechanical economy units.
Pricing Analysis
Primary aluminum ingot volatility passes through directly to combination FRL unit pricing, compressing margins for mid-tier manufacturers lacking captive die-casting operations. Pricing stratifies across premium, standard, and economy tiers based on certification grade—ISO 8573-1 Class 1.2.1 compliance commands substantial premiums—and volume scale from framework agreements. Cost compression in the standard tier is intensifying because of raw material volatility and electric actuator substitution. Textile fabricators in Gujarat exhibit the highest price sensitivity, while pharmaceutical manufacturers in Switzerland show minimal elasticity due to FDA validation requirements.
Supply Chain Analysis
Container freight rate fluctuations from Asia to Europe and North America directly impact landed costs for combination FRL assemblies manufactured in Japan and China. Manufacturing concentrates in Germany, Japan, and China, with borosilicate glass microfiber for sub-five-micron filtration drawing from German and Japanese specialty paper converters. Supply chain risk centers on single-source vulnerability for filter media production. Distribution runs through integrated automation distributors with vendor-managed inventory programs replacing traditional wholesale channels in Northern Italy and the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as electric vehicle assembly precision forces tier-one automotive suppliers toward ISO 8573-1 Class 1.2.1 specification upgrades regardless of near-term capital constraints.
For Market Incumbents: Cement channel control in German automotive OEM supply chains through REACH-compliant seal certification investments that emerging competitors cannot replicate quickly. Deepen backward integration into aluminum die-casting to defend margin position against primary ingot volatility. Prioritize electro-pneumatic R&D to offset electric linear actuator substitution threats in sub-500mm stroke applications. For New Entrants and Emerging Players: Launch via vendor-managed inventory partnerships with mid-size packaging machinery OEMs in Northern Italy, where incumbent concentration has created service gaps. Target India's Gujarat and Tamil Nadu textile clusters benefiting from PLI scheme machinery incentives as the most penetrable geography. Pursue steam-sterilizable stainless steel FRL specialization for biologics manufacturing in Switzerland and Singapore, where FDA validation timelines deter established players from rapid response. For Investors and Strategic Acquirers: Diversified industrial conglomerates with existing energy and automation channels are the most active acquirers in this space, seeking pneumatic conditioning capabilities to cross-sell through installed base relationships. Over a five-to-ten-year horizon, acquisition value concentrates in precision pneumatic specialists with deep vertical expertise in pharmaceutical or semiconductor cleanroom applications. Monitor membrane air drying adoption rates in food packaging as the critical signal—accelerating absorption of point-of-use moisture removal duties indicates structural compression for refrigerated dryer-dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Die-Casting | Captive supply of primary housings insulates margin structures from LME volatility. |
| IoT Platform Partnership | Siemens MindSphere integration enables outcome-based compressed air efficiency contracts. |
| REACH-Compliant Seal Validation | Hydrogenated nitrile butadiene rubber certification opens German automotive OEM access. |
| Membrane Air Drying Module Development | Zero electrical consumption positioning targets Dutch and Danish food packaging OEMs. |
| Local Assembly in India | PLI scheme qualification reduces landed costs for Gujarat textile automation clusters. |
Research Methodology
Bottom-up pneumatic duty cycle modeling reconciled against top-down compressed air system installation tracking forms the analytical core of this study. Primary interviews with maintenance directors at continuous-process manufacturers, OEM procurement teams in automotive and electronics assembly, aftermarket service heads at integrated distributors, and plant engineers in pharmaceutical facilities combined with secondary validation from SEC filings, customs and trade data, ISO certification registries, and EU F-Gas Regulation compliance disclosures. Triangulation across these sources ensures demand-side estimates align with supply-side production capacity.
Input-output matrices map FRL unit shipments across product type, technology architecture, application environment, and end-user industry through the projection horizon. Segmentation dimensions include filtration rating tiers, control interface sophistication, installation environment air quality class, and regional regulatory cluster. CAGRs derive from fitted growth curves against historical penetration rates and projected replacement cycles. Forecast inputs incorporate semiconductor fabrication capacity expansion in South Korea and Taiwan, plus electric vehicle assembly line commissioning schedules in Germany and China.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated electric actuator substitution or prolonged FDA validation timeline extensions. Forecasts reflect assumptions about regulatory enforcement consistency, raw material price stabilization, and technician skill availability for electro-pneumatic commissioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Micro Motor Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Dustless Workstations Market