
 Commercial Refrigeration System Market | 2026-2036
Commercial Refrigeration System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Refrigeration System Market Analysis
The US EPA SNAP program is rebalancing procurement criteria across North American food retail chains. Daikin leverages its compressor manufacturing scale to supply CO2-based systems for European supermarket retrofits. Johnson Controls sustains technology leadership in building automation integration for refrigerated facilities. Carrier anchors its position through geographic dominance in North American service networks.
Commercial refrigeration systems are engineered assemblies that maintain controlled low-temperature environments for perishable goods, typically operating between -40°C and 15°C using refrigerant cycles, insulated enclosures, and precision control systems. These systems preserve food safety, pharmaceutical efficacy, and product quality across supply chain nodes. Walk-in coolers occupy the largest installed base due to universal deployment across restaurants and warehouses, though display cases command premium margins through glass-door efficiency engineering and merchandising integration. Vapor compression technology dominates current installations, while absorption refrigeration gains traction in facilities with waste-heat recovery potential.
The US EPA, the EU F-Gas Regulation, and Japan's METI collectively tighten refrigerant phase-down schedules and energy performance standards, forcing equipment replacement cycles and redesign of system architectures. Compliance timelines now shape capital expenditure planning for multi-site food retailers and cold-chain logistics operators. Stakeholders must monitor refrigerant quota allocation mechanisms and regional certification harmonization to align procurement strategies with evolving access requirements.
Market Dynamics
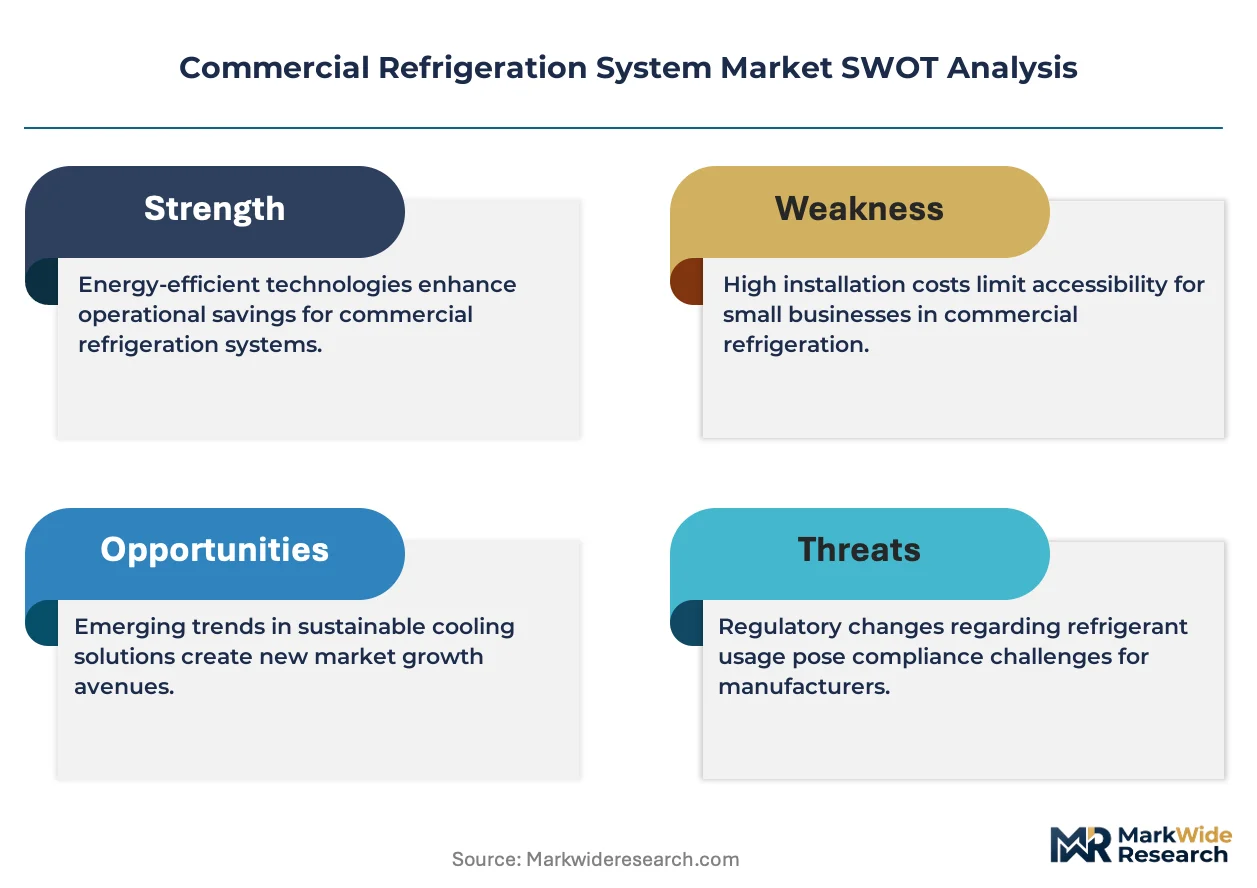
Refrigerant phase-down mandates are compressing equipment replacement cycles across food retail and cold-chain logistics, forcing capital redeployment toward lower-GWP architectures before legacy system depreciation completes.
Growth Catalysts
- EU F-Gas Regulation:Quota mechanisms accelerate supermarket retrofit timelines, pulling forward demand for CO2 transcritical systems in Germany and France.
- Cold-chain logistics:Pharmaceutical distribution networks expand temperature-controlled warehouse footprints to support biologics supply chains.
- Natural refrigerants:Ammonia and propane systems gain traction in industrial freezing applications where charge size regulations permit deployment.
Market Restraints
- Copper and aluminum volatility:Heat exchanger materials expose OEMs to commodity price swings that compress margin visibility on fixed-price contracts.
- Compressor supply concentration:European and Japanese manufacturers control critical component output, creating bottleneck risk for system integrators.
- Charge size limitations:IEC safety standards restrict hydrocarbon refrigerant quantities in urban retail installations, constraining architecture options.
Strategic Opportunities
- India cold-chain deficit:Post-harvest losses exceeding 15% create addressable infrastructure gaps in Maharashtra and Gujarat agricultural corridors.
- Waste-heat recovery:Absorption refrigeration convergence with industrial process plants opens food processing and chemical manufacturing adjacencies.
- US IRA clean energy credits:Tax incentives for energy-efficient equipment reduce payback periods for independent grocers considering system upgrades.
Industry Challenges
- Refrigerant handling certification:EPA Section 608 technician shortages delay installation timelines and inflate labor costs for retrofit projects.
- Legacy control integration:BACnet and Modbus protocol mismatches complicate building automation upgrades in multi-site retail portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Refrigeration System Market |
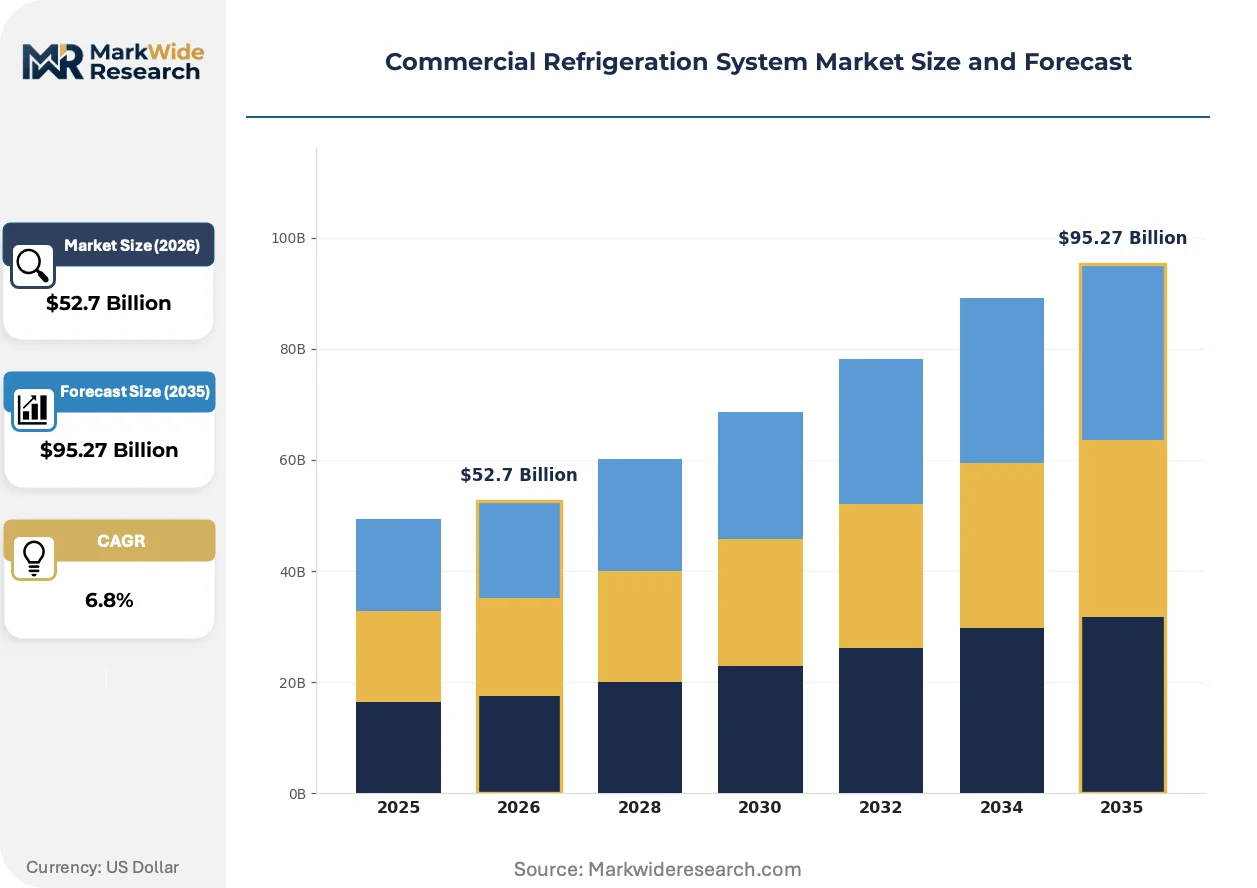
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-In Coolers, Reach-In Refrigerators, Display Cases, Ice Machines End User: Supermarkets, Convenience Stores, Restaurants, Warehouses Application: Food Storage, Beverage Cooling, Pharmaceutical Storage, Floral Preservation Technology: Vapor Compression, Absorption Refrigeration, Thermoelectric, Cascade System |
| Companies Covered | Daikin, Johnson Controls, Carrier, Dover, Hussmann, Danfoss, Haier, Emerson Electric, Welbilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Refrigeration System Market Emerging Trajectories
Equipment architectures are pivoting from centralized direct-expansion systems toward distributed approaches that reduce refrigerant inventory and simplify leak detection protocols.
CO2 transcritical booster systems are rewriting efficiency benchmarks for supermarket applications in moderate climates. Scandinavian retailers deployed these configurations a decade ago; German and French chains now replicate the model. The technology is compressing the performance gap between natural and synthetic refrigerants in regions previously deemed unsuitable.
The US EPA SNAP program continues expanding approved refrigerant lists while accelerating phase-out schedules for high-GWP alternatives. Equipment manufacturers must maintain dual certification tracks for transitional and next-generation chemistries. Food retail chains with 500-plus locations face compressed procurement windows as state-level regulations outpace federal timelines.
Service contract unbundling is fragmenting the traditional OEM-captive maintenance model. Third-party service aggregators now compete for multi-site retail accounts using predictive analytics platforms. This shift concentrates in the United Kingdom and Netherlands where independent contractors hold stronger market presence.
Commercial Refrigeration System Market Segmentation
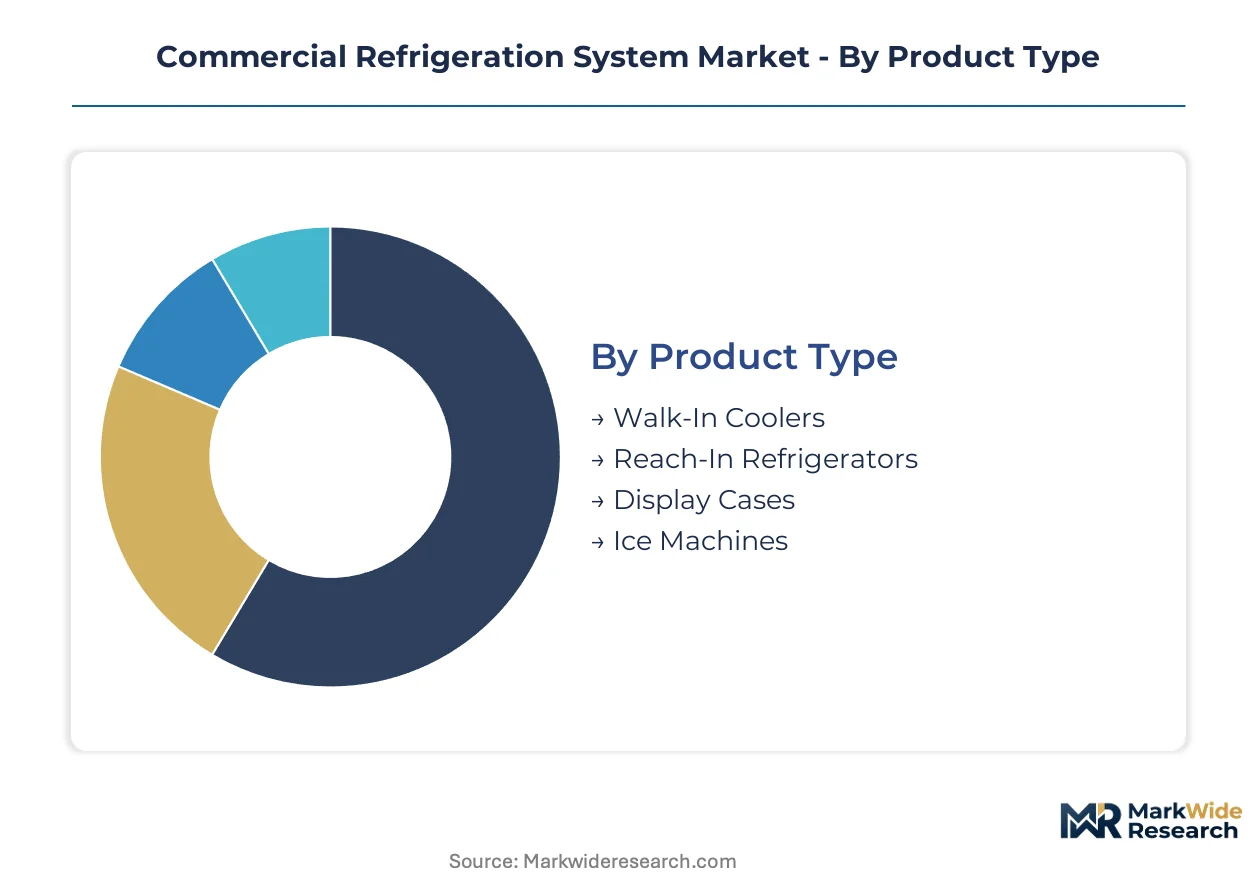
Equipment segmentation in commercial refrigeration tracks divergent capital deployment patterns across temperature ranges, enclosure formats, and refrigerant architectures. Procurement decisions cluster around energy compliance timelines and facility retrofit cycles rather than uniform replacement schedules.
Product Type:
Capital intensity varies sharply across enclosure formats, with field-assembled systems demanding substantially higher installation labor and site preparation than self-contained units.
- Walk-In Coolers:Modular insulated panels assembled on-site create controlled environments from -18°C to 4°C for bulk inventory storage. Restaurant chains and third-party logistics providers in Germany and France are retrofitting these systems with CO2 transcritical architectures ahead of EU F-Gas quota reductions.
- Display Cases:Glass-door merchandising units integrate LED lighting, anti-fog coatings, and precision airflow management to maintain product visibility while minimizing thermal load. Convenience store operators in Japan prioritize these units for grab-and-go beverage sections where METI efficiency standards drive replacement urgency.
- Reach-In Refrigerators:Self-contained vertical cabinets with hinged or sliding doors serve back-of-house food preparation zones in independent restaurants.
- Ice Machines:Batch or continuous production systems for cube, flake, and nugget formats deploy across hospitality and healthcare settings.
Walk-in coolers absorb the bulk of installed capacity; display cases are expanding most quickly.
End User:
Facility scale determines system architecture complexity, with multi-site operators favoring centralized monitoring platforms over standalone controls.
- Supermarkets:Full-format food retailers operate integrated refrigeration plants serving display cases, walk-in coolers, and preparation areas through distributed or centralized architectures. Chains across Scandinavia pioneered CO2 transcritical adoption; German and French operators now replicate these configurations under EU F-Gas compliance pressure.
- Restaurants:Independent and chain foodservice operations deploy reach-in units and under-counter systems for ingredient storage and preparation workflows. Quick-service operators in India's Maharashtra corridor are installing basic cold storage to reduce post-harvest losses in supply chains.
- Convenience Stores:Small-footprint retailers prioritize grab-and-go beverage coolers and frozen food merchandisers with minimal maintenance requirements.
- Warehouses:Cold-chain logistics operators construct temperature-controlled distribution centers supporting pharmaceutical and food product integrity.
Supermarkets command the highest equipment spend per location; warehouses are climbing the fastest as biologics distribution networks expand.
Application:
Temperature precision requirements stratify equipment specifications, with pharmaceutical applications demanding validation protocols absent in food retail.
- Food Storage:Temperature maintenance between -25°C and 4°C preserves raw ingredients and prepared products across supply chain nodes. Cold-chain infrastructure gaps in India's Gujarat agricultural belt are driving warehouse construction for produce consolidation.
- Pharmaceutical Storage:Validated cold rooms and reach-in units maintain 2°C to 8°C for vaccines and biologics with continuous monitoring and alarm systems. Distribution networks in Germany and France are expanding capacity to support mRNA vaccine cold chains.
- Beverage Cooling:Rapid chilling systems for retail merchandising and draft dispensing prioritize energy efficiency in high-ambient environments.
- Floral Preservation:Humidity-controlled coolers extend shelf life for cut flowers through ethylene management and precise temperature maintenance.
Food storage dominates installed base; pharmaceutical storage is gaining share fastest on biologics distribution investments.
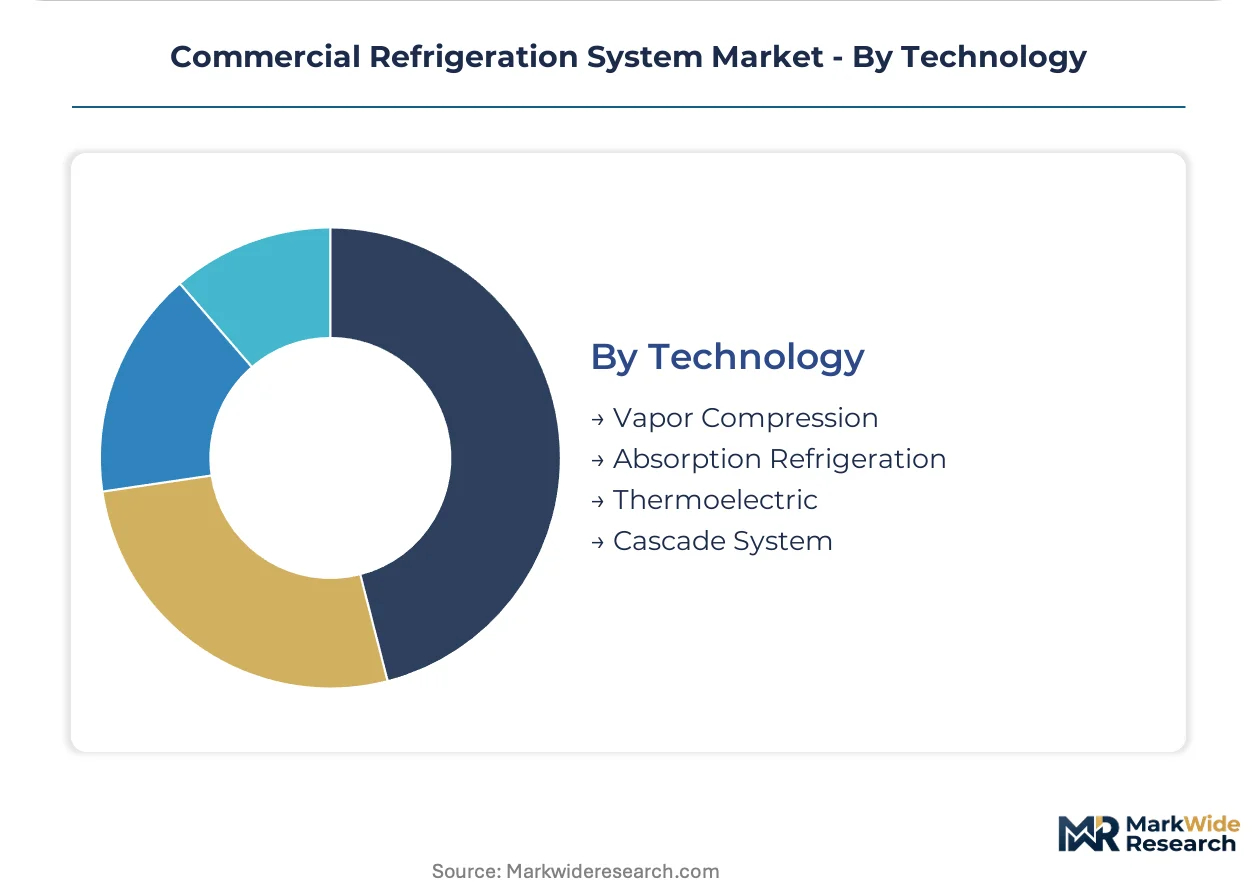
Technology:
Refrigerant selection and thermodynamic cycle choice determine regulatory compliance trajectory and energy performance benchmarks.
- Vapor Compression:Mechanical refrigeration cycles using electric-driven compressors dominate current installations across all product categories. System integrators are transitioning these architectures toward lower-GWP refrigerants under US EPA SNAP and EU F-Gas phase-down schedules.
- Absorption Refrigeration:Heat-activated systems using ammonia-water or lithium bromide pairs eliminate electric compressor demand. Industrial food processors with waste-heat recovery potential in Germany are piloting these configurations for freezing applications.
- Thermoelectric:Solid-state Peltier devices provide precise temperature control for small-volume pharmaceutical and laboratory applications.
- Cascade System:Staged refrigeration cycles combining CO2 and hydrocarbon or HFO refrigerants achieve ultra-low temperatures for industrial freezing.
Vapor compression holds the overwhelming share of operating units; absorption refrigeration is expanding most quickly where waste-heat integration proves viable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany, Japan, and the United States while consumption accelerates across China's eastern corridor and India's agricultural belts. Regulatory divergence between EPA SNAP timelines and EU F-Gas quotas fragments procurement strategies. Cold-chain infrastructure gaps in emerging economies pull investment toward warehouse construction and retrofit demand.
United States
Food retail consolidation drives multi-site retrofit programs across Kroger and Albertsons networks. EPA SNAP approval schedules for R-454B and R-455A compress equipment procurement windows. Texas and California cold-storage construction accelerates to support pharmaceutical distribution from Dallas-Fort Worth and Inland Empire logistics clusters.
Germany
Discounter chains Aldi and Lidl mandate CO2 transcritical architectures for new-build supermarkets. EU F-Gas quota reductions force refrigerant inventory management across Bavarian and North Rhine-Westphalian retail portfolios. Industrial absorption refrigeration pilots leverage waste-heat recovery from chemical processing complexes in Ludwigshafen.
China
Eastern coastal provinces Jiangsu and Zhejiang deploy display case upgrades for Hema and 7Fresh fresh-format stores. SAMR energy efficiency labeling tightens compressor performance thresholds. Yangtze River Delta cold-chain hubs expand pharmaceutical storage capacity to serve domestic biologics distribution.
India
Post-harvest losses exceeding fifteen percent drive warehouse construction in Maharashtra and Gujarat agricultural corridors. FSSAI cold-chain compliance mandates reshape procurement for organized retail expansion. Bangalore and Hyderabad pharmaceutical manufacturers validate temperature-controlled distribution networks for export markets.
Japan
Convenience store operators Lawson and 7-Eleven prioritize grab-and-go beverage cooler efficiency under METI standards. Aging supermarket refrigeration plants in Osaka and Nagoya face compressed replacement cycles. Thermoelectric precision cooling gains traction for laboratory and pharmaceutical applications in Kanto research clusters.
Commercial Refrigeration System Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive compressor manufacturing and building automation integration. Tier-one positions consolidate around HVAC-to-refrigeration portfolio breadth rather than pure-play specialization. Strategic archetypes include full-system integrators, component-scale suppliers, and service-network anchors. Dominant competitive moves center on geographic service density expansion and natural refrigerant architecture certification.
Among diversified industrial conglomerates, Daikin Industries, Ltd. and Carrier Global Corporation exemplify scale-driven positions anchored by compressor manufacturing depth and North American service network density. Johnson Controls International plc occupies the building automation convergence tier, representing integration between refrigerated facility controls and enterprise energy management. These three entities illustrate how competitive positioning stratifies across manufacturing scale, service reach, and control system integration rather than product-line breadth alone.
| Leading Market Players |
|---|
| Daikin |
| Johnson Controls |
| Carrier |
| Dover |
| Hussmann |
| Danfoss |
| Haier |
| Emerson Electric |
| Welbilt |
| Others |
Supply Flow & Price Mechanics
The US EPA SNAP refrigerant phase-down mandates gate qualified supply and premium-tier pricing access for CO2 transcritical system architectures. Food retail chains with multi-site portfolios face compressed procurement windows as state-level regulations outpace federal timelines, concentrating pricing power with OEMs holding dual-certification tracks for transitional and next-generation chemistries.
Pricing Analysis
Value-based pricing anchored to energy efficiency outcomes and compliance uptime dominates supermarket and cold-chain logistics procurement. Three-tier pricing structure across premium, standard, and economy levels separates CO2 transcritical systems with full building automation integration from basic HFO retrofits and legacy HFC maintenance contracts. Cost compression in economy-tier vapor compression equipment is intensifying because copper and aluminum commodity volatility exposes OEMs to margin erosion on fixed-price contracts. Independent grocers and small-format convenience operators exhibit highest price sensitivity, while pharmaceutical distribution networks prioritize validated cold-chain uptime over capital expenditure minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Kroger and Albertsons networks, while independent contractors and third-party service aggregators serve fragmented restaurant and convenience store accounts. Manufacturing concentrates in Germany, Japan, and the United States for compressor and control system production, drawing from specialty steel alloys, refrigerant gases, and precision electronics inputs. Single-source vulnerability in European and Japanese compressor output creates bottleneck risk for system integrators facing EU F-Gas quota deadlines. Distribution runs through captive OEM service networks in North America, independent contractor ecosystems in the United Kingdom and Netherlands, and emerging third-party platforms deploying predictive analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial refrigeration system market sits in a technology-transition phase as CO2 transcritical architectures displace legacy HFC vapor compression systems under regulatory pressure.
For Market Incumbents: Hedge refrigerant technology exposure by maintaining parallel certification tracks for HFO blends and natural refrigerant architectures until EPA SNAP and EU F-Gas quota clarity stabilizes. Deepen backward integration into compressor manufacturing to offset supply concentration risk from European and Japanese component suppliers. Prioritize building automation integration capabilities to defend against third-party service aggregators unbundling maintenance contracts. For New Entrants and Emerging Players: Begin with India's Maharashtra and Gujarat agricultural corridors where post-harvest loss reduction mandates create cold-chain infrastructure gaps underserved by incumbent OEM service networks. Target warehouse construction for pharmaceutical biologics distribution as the most penetrable segment given validation protocol requirements that favor specialized regional players over generalist contractors. Pursue joint venture structures with local construction firms to navigate FSSAI compliance mandates and accelerate field deployment. For Investors and Strategic Acquirers: EPA Section 608 technician certification bottlenecks delaying installation timelines is the leading indicator that labor-constrained markets will consolidate around service-network density. The five-to-ten year viability window favors acquisition of regional service aggregators with predictive analytics platforms over pure-play equipment manufacturers lacking aftermarket recurring revenue. Monitor state-level refrigerant regulations outpacing federal SNAP schedules as the signal for accelerated capital redeployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Certification Investment | Dual-track EPA SNAP and EU F-Gas compliance opens supermarket retrofit access in Germany and France. |
| Backward Integration into Compressor Manufacturing | In-house production of critical components reduces exposure to Japanese and European supply bottlenecks. |
| Predictive Analytics Platform Deployment | Third-party service aggregators in the United Kingdom and Netherlands challenge OEM-captive maintenance models. |
| India Cold-Chain Joint Venture Formation | Local construction partnerships navigate FSSAI mandates in Maharashtra and Gujarat agricultural corridors. |
| Building Automation Convergence | Johnson Controls-type integration between refrigerated controls and enterprise energy management commands premium positioning. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with food retail procurement directors, cold-chain logistics operators, EPA-certified refrigeration technicians, and OEM product managers combined with bottom-up and top-down triangulation. Secondary sources included US EPA SNAP approval databases, EU F-Gas quota registry filings, AHRI certification directories, and import-export records from Germany, Japan, and China customs authorities.
Reconciliation of equipment shipment data, refrigerant consumption reports, and capital expenditure disclosures from publicly traded food retail chains shaped the analytical framework. Segmentation dimensions modeled encompass product type, end-user facility scale, temperature application range, refrigerant architecture, and regional regulatory cluster across the projection horizon. CAGRs derived from slope-log analysis of historical replacement cycles projected against compliance deadline clustering. Industry-specific forecast inputs included EU F-Gas quota allocation trajectories and US IRA clean energy credit uptake rates among independent grocers.
Underlying measurement precision varies by segment; walk-in cooler and display case categories carry tighter precision than emerging absorption refrigeration and thermoelectric applications. Forecasts reflect assumptions regarding refrigerant phase-down schedule adherence, commodity price stability for copper and aluminum, and technician certification pipeline expansion. Regulatory acceleration beyond modeled EPA SNAP timelines, trade policy shifts affecting compressor component flows, or breakthroughs in solid-state cooling could materially revise trajectory projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Global Fans and Blowers Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Resistance Spot Welding Machines Market