
 United States Contract Lifecycle Management Software Market | 2026-2036
United States Contract Lifecycle Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
United States Contract Lifecycle Management Software Market Intelligence
Subscription-based financing and asset-light SaaS procurement models is rewriting competitive dynamics for mid-market buyers. Icertis, Inc. leverages enterprise-grade AI extraction to anchor complex multi-party negotiations. DocuSign, Inc. sustains broad electronic-signature integration that extends into downstream contract execution workflows. Zycus Inc. specializes in procurement-linked CLM for Fortune 500 manufacturing clients.
United States Contract Lifecycle Management Software comprises digital platforms that automate authoring, negotiation, execution, and renewal of legally binding agreements through clause libraries, AI-powered risk scoring, and automated approval routing. Cloud-based deployment dominates new implementations as organizations prioritize remote accessibility and reduced infrastructure overhead. The user segment splits sharply between enterprises seeking ERP-integrated governance and SMBs adopting self-service subscription tiers. API-driven integration levels are gaining traction where Salesforce and SAP ecosystems require real-time contract data synchronization.
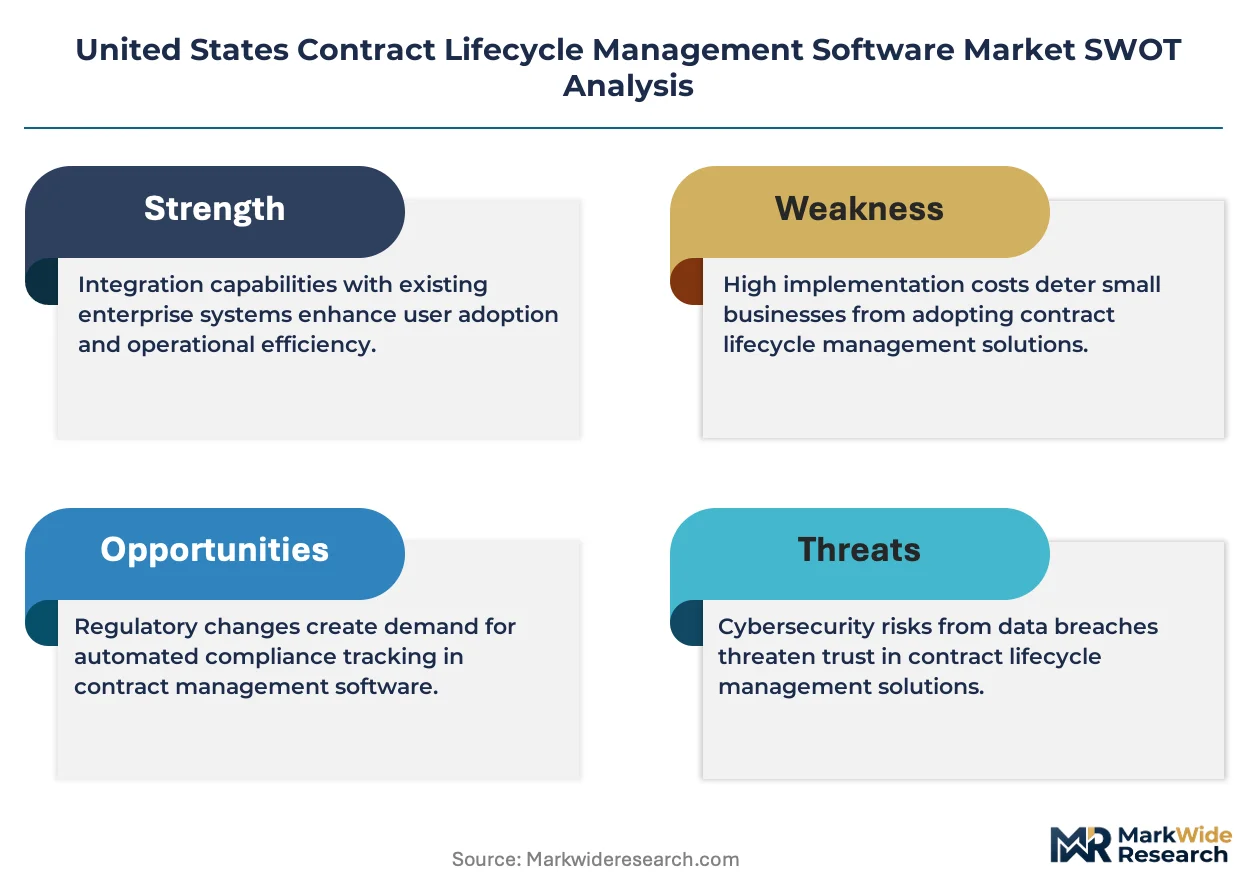
The SEC mandates detailed contract disclosure under Regulation S-K, while HIPAA governs healthcare data handling within CLM systems storing patient-related agreements. State-level procurement regulations in California and New York impose additional compliance layers on government-facing vendors. Stakeholders must evaluate whether their platform architecture can absorb emerging AI audit requirements without fragmenting existing workflow automation.
Market Dynamics
The SEC's enhanced disclosure mandates under Regulation S-K are compressing procurement cycles and forcing enterprise buyers toward AI-native contract governance platforms that automate material contract identification and filing workflows.
Growth Catalysts
- Healthcare compliance mandates:HIPAA requirements for patient data handling in supplier agreements are driving hospital networks toward CLM platforms with built-in privacy clause libraries and automated risk scoring for business associate contracts.
- California procurement centralization:State-level vendor management reforms are standardizing contract templates across California's public health systems, creating procurement volume for integrated CLM suites.
- AI extraction capabilities:Natural language processing engines trained on legal corpora are reducing contract review cycles from weeks to hours for Fortune 500 legal departments managing thousands of active agreements.
Market Restraints
- Cloud infrastructure concentration:Dependence on hyperscale providers for CLM hosting creates single-point-of-failure exposure for financial services firms requiring contractual uptime guarantees above standard SLAs.
- Data residency fragmentation:Divergent state-level data sovereignty interpretations between California and New York impose architectural complexity on multi-jurisdictional deployments for national enterprises.
- Legacy ERP integration costs:Custom API development for SAP and Oracle systems consumes implementation budgets that midsize firms cannot absorb without financing arrangements.
Strategic Opportunities
- Mid-market self-service tiers:Subscription models priced below enterprise thresholds are penetrating professional services firms and regional healthcare systems previously excluded from CLM automation.
- SEC climate disclosure convergence:Emerging sustainability-linked contract clauses are creating demand for platforms that track carbon performance obligations alongside traditional commercial terms.
- API-first ecosystem positioning:Real-time synchronization with Salesforce and Workday environments represents whitespace for vendors capturing workflow-native contract data flows.
Industry Challenges
- Legal engineering talent scarcity:Firms struggle to hire professionals who bridge contract law expertise with platform configuration and AI training data curation.
- Multi-system integration complexity:Synchronizing clause libraries across disparate procurement, finance, and CRM environments requires sustained IT investment that delays value realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Contract Lifecycle Management Software Market |
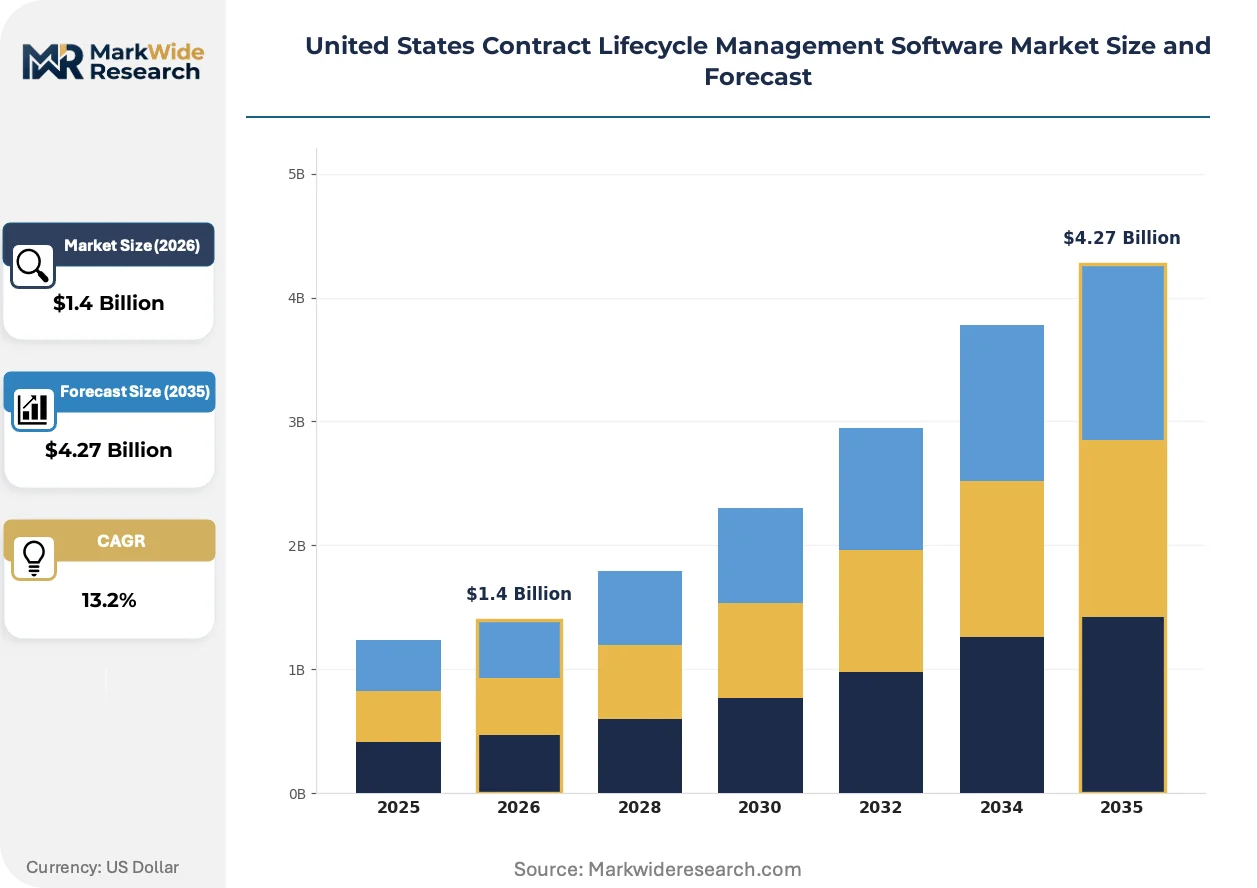
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.27 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: On-Premise, Cloud-Based, Hybrid, DIY User Segment: SMBs, Enterprises, Government, Non-Profits Deployment Model: Managed Services, Professional Services, Self-Service, Subscription Integration Level: Standalone, ERP Integration, CRM Integration, API-Driven |
| Companies Covered | Icertis, Inc., Agiloft Inc., DocuSign, Inc., Coupa Software Inc., Zycus Inc., Apttus Corp., Onit Inc., Evisort Inc., Concord Worldwide, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Contract Lifecycle Management Software Market Strategic Shifts & Innovations
Generative AI is compressing document generation timelines while regulatory pressure on contract transparency is reshaping platform architecture priorities for compliance automation.
Large language models trained on legal corpora are digitizing contract drafting workflows by auto-generating first-pass agreements from intake questionnaires. Mid-market legal departments are adopting these tools at accelerating rates to offset flat headcount budgets. The technology is digitizing the traditional associate attorney role in routine document preparation, reallocating human review toward exception handling and negotiation strategy.
The SEC's material contract disclosure requirements under Regulation S-K Item 601 are mandating systematic contract metadata extraction for accelerated filing deadlines. Public companies must now maintain searchable repositories of agreements triggering disclosure obligations. Healthcare and technology sectors are responding fastest, deploying AI classification engines to flag contracts exceeding quantitative materiality thresholds.
Enterprise buying patterns are consolidating vendor relationships as procurement teams prioritize platforms offering adjacent capabilities—e-signature, spend analytics, supplier risk monitoring—within unified suites. Single-vendor CLM strategies are displacing best-of-breed point solutions in Fortune 500 technology and financial services verticals. This consolidation is most visible in New York's banking sector, where vendor management offices are reducing supplier counts to streamline security reviews and contract administration overhead.
United States Contract Lifecycle Management Software Market Segmentation
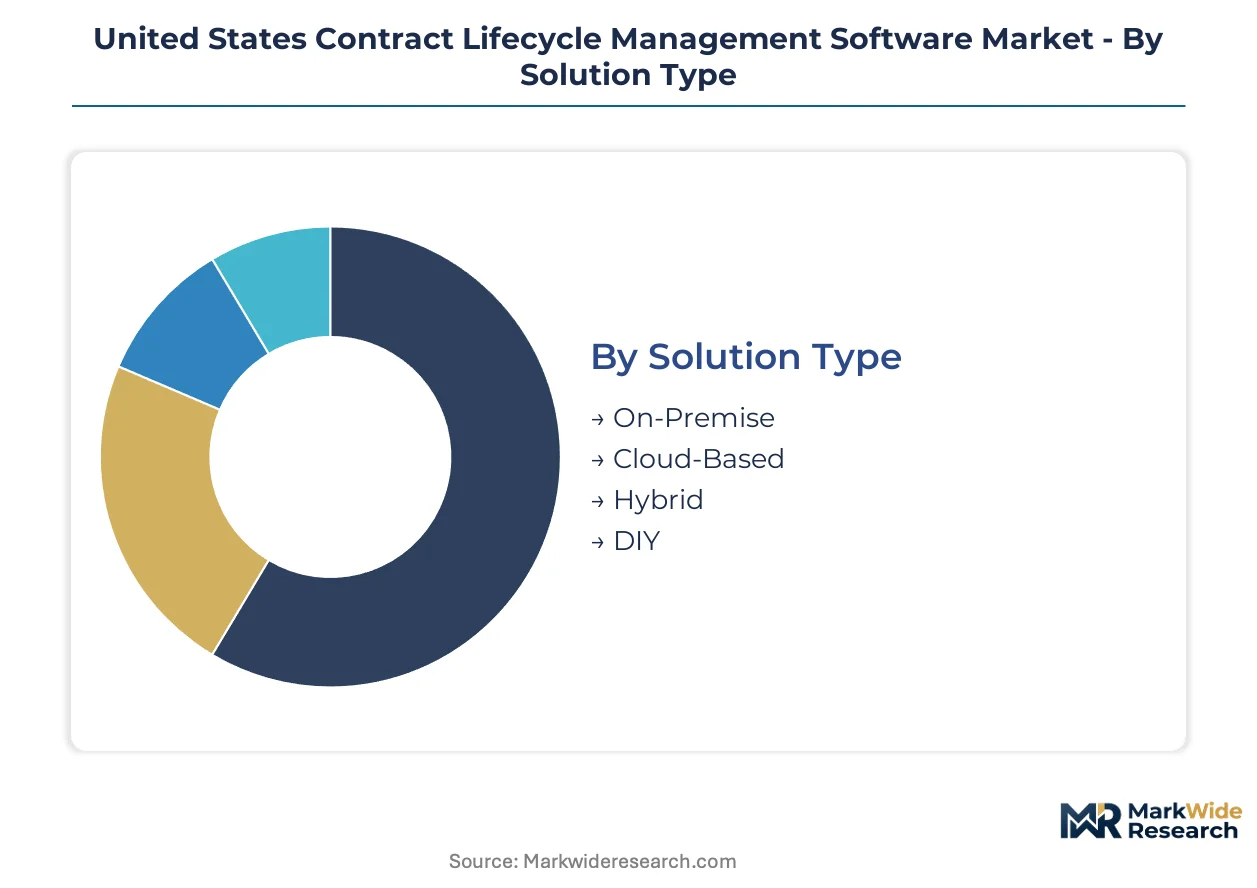
CLM procurement patterns diverge sharply across customer scale and technical architecture preferences. Solution type and integration requirements reshape vendor selection criteria for healthcare networks, financial services firms, and public sector buyers navigating SEC disclosure mandates and HIPAA compliance obligations.
Solution Type:
Cost tier structures the procurement calculus as organizations weigh infrastructure control against operational agility and capital deployment flexibility.
- Cloud-Based:Multi-tenant SaaS architectures deliver remote accessibility and automatic security patching without on-site hardware investment. Hospital networks in California and New York are migrating supplier agreement repositories to cloud-native platforms to satisfy HIPAA business associate contract automation requirements while eliminating data center overhead.
- On-Premise:Single-tenant deployments behind corporate firewalls preserve complete data sovereignty and custom security policy enforcement. Financial services firms in Manhattan require on-premise CLM hosting to meet contractual uptime guarantees exceeding standard cloud SLAs for derivatives trading documentation.
- Hybrid:Split architectures isolate sensitive contract data on-premise while routing routine workflows through cloud interfaces. Federal contractors handling CUI (Controlled Unclassified Information) leverage hybrid models to compartmentalize classified supplier agreements.
- DIY:Open-source or self-assembled configurations using generic document management tools with custom clause libraries. Cash-constrained municipal governments in secondary markets occasionally pursue DIY approaches before compliance audit failures force platform migration.
Cloud-based deployments command the established base. The steepest expansion runs through hybrid configurations serving regulated industries with compartmentalized security requirements.
User Segment:
Customer type determines feature depth, pricing tolerance, and implementation complexity as procurement maturity varies across organizational scale.
- Enterprises:Fortune 500 legal departments require AI-powered extraction, multi-jurisdictional clause libraries, and ERP-integrated approval routing for thousands of active agreements. Technology and financial services corporations in California's Bay Area and New York's financial corridor represent the revenue concentration for premium CLM suites.
- SMBs:Professional services firms and regional healthcare systems adopt self-service subscription tiers with templated workflows and limited customization. Flat legal headcount budgets at mid-market professional services firms in Texas and Florida are accelerating SMB CLM adoption for routine document preparation.
- Government:Federal, state, and municipal procurement offices require FedRAMP authorization and standardized contract templates. California's public health system centralization is standardizing CLM procurement across county-level vendor management offices.
- Non-Profits:Grant-funded organizations prioritize donor agreement tracking and restricted fund compliance over commercial contract complexity. University research institutions managing federal grant subcontracts represent a niche but stable demand pool.
Enterprises anchor vendor revenue. SMB self-service tiers are climbing fastest as subscription pricing penetrates previously excluded market strata.
Deployment Model:
Service intensity shapes implementation timelines and ongoing operational burden for internal legal operations teams.
- Subscription:Recurring SaaS licenses with tiered feature access and usage-based scaling. Asset-light procurement models are rewriting competitive dynamics for mid-market buyers seeking predictable OpEx structures.
- Managed Services:Vendor-operated platform administration including clause library maintenance and user support. Healthcare systems lacking legal engineering talent are outsourcing CLM operations to managed service providers.
- Professional Services:Implementation-heavy engagements with custom configuration, legacy system migration, and training. SAP and Oracle ERP integration projects for Fortune 500 manufacturers consume substantial professional services budgets.
- Self-Service:Low-touch onboarding with pre-configured templates and minimal vendor intervention. Rapid deployment requirements at fast-growing technology startups are favoring self-service CLM adoption.
Subscription pricing commands the established base. Managed services are expanding most quickly as talent scarcity drives outsourcing decisions.
Integration Level:
System connectivity requirements determine architectural complexity and data synchronization demands across enterprise software ecosystems.
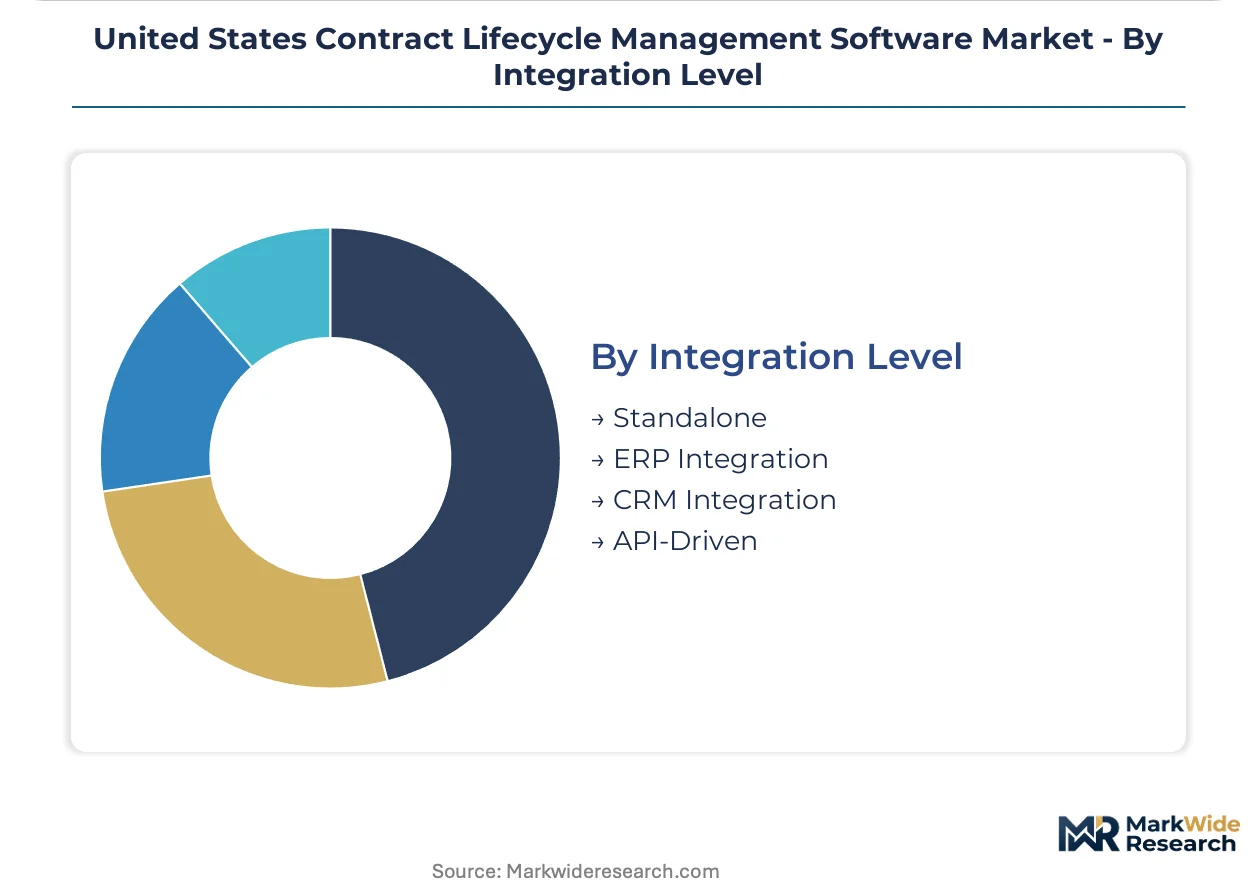
- API-Driven:Real-time bi-directional data flows with Salesforce, Workday, and SAP environments enabling workflow-native contract visibility. API-first positioning represents whitespace for vendors capturing real-time synchronization requirements in technology sector procurement.
- ERP Integration:Deep coupling with SAP, Oracle, or Microsoft Dynamics for procurement-to-payment workflow continuity. Manufacturing enterprises in the Midwest require ERP-integrated CLM to synchronize supplier agreements with purchase order generation.
- CRM Integration:Connection to Salesforce or HubSpot for customer contract visibility within sales workflows. Technology sector revenue operations teams demand CRM-integrated CLM for subscription renewal management.
- Standalone:Isolated platforms operating without external system connectivity, suitable for simple contract storage and basic approval routing. Smaller professional services firms occasionally accept standalone deployments before ecosystem consolidation pressures force integration upgrades.
ERP integration commands the established base. API-driven architectures are gaining share fastest as real-time data synchronization becomes a procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's technology corridor and New York's financial services hub, while secondary markets absorb cost-pressured implementations through self-service tiers and managed service outsourcing.
California
Healthcare networks and technology enterprises drive cloud-native CLM procurement for HIPAA-compliant supplier management and SEC disclosure automation. State-level procurement centralization mandates standardized contract templates across county public health systems. Silicon Valley legal departments deploy AI extraction engines to compress material contract review cycles ahead of quarterly filing deadlines.
New York
Financial services firms demand on-premise and hybrid architectures to meet contractual uptime guarantees exceeding standard cloud SLAs for derivatives documentation. The SEC's Regulation S-K enforcement pressures Manhattan-based public companies toward automated governance platforms. Wall Street vendor management offices consolidate supplier relationships to streamline security reviews and contract administration overhead.
Texas
Mid-market professional services firms adopt self-service subscription tiers to offset flat legal headcount budgets for routine document preparation. State procurement regulations impose compliance layers on government-facing CLM vendors serving municipal clients. Dallas-Fort Worth energy sector legal teams prioritize ERP-integrated platforms for supplier agreement synchronization with purchase order generation.
Illinois
Fortune 500 manufacturers in the Midwest require deep SAP and Oracle coupling for procurement-to-payment workflow continuity. Legacy ERP integration costs consume implementation budgets that regional enterprises absorb through financing arrangements. Chicago-based hospital networks migrate supplier repositories to cloud platforms to eliminate data center overhead while satisfying business associate contract automation requirements.
Florida
Regional healthcare systems and fast-growing technology startups favor rapid-deployment self-service CLM adoption with pre-configured templates. Talent scarcity drives outsourcing decisions to managed service providers for platform administration and clause library maintenance. Miami professional services firms represent accelerating SMB penetration as subscription pricing penetrates previously excluded market strata.
United States Contract Lifecycle Management Software Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrow workflow automation tools. The vendor base organizes around three strategic archetypes: enterprise-grade AI-native suites, e-signature-anchored workflow extenders, and procurement-linked governance platforms. Consolidation pressures favor unified suites over best-of-breed point solutions. Dominant competitive moves include adjacent capability integration and API-first ecosystem positioning for real-time data synchronization.
Within the enterprise AI-native tier, Icertis, Inc. and Evisort Inc. exemplify platforms leveraging legal corpus-trained extraction engines for complex multi-party negotiations. DocuSign, Inc. anchors the e-signature-anchored archetype, extending electronic signature infrastructure into downstream contract execution workflows. Zycus Inc. occupies a position within procurement-linked specialization, serving manufacturing clients with spend analytics-adjacent governance capabilities. These three company structures represent the strategic positioning spectrum visible across the competitive landscape.
| Leading Market Players |
|---|
| Icertis, Inc. |
| Agiloft Inc. |
| DocuSign, Inc. |
| Coupa Software Inc. |
| Zycus Inc. |
| Apttus Corp. |
| Onit Inc. |
| Evisort Inc. |
| Concord Worldwide, Inc. |
| Others |
Cost & Logistics Intelligence
Silicon Valley's hyperscale cloud infrastructure concentration shapes downstream pricing power for CLM vendors, as compute and storage costs from California's technology corridor cascade through SaaS subscription tiers and managed service margins.
Pricing Analysis
The customization-premium spread separates enterprise-configured deployments from self-service subscription tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by AI extraction depth and ERP integration complexity. Pricing pressure stems from mid-market buyers demanding asset-light OpEx models that compress implementation margins. SMB professional services firms exhibit highest price sensitivity, while Fortune 500 legal departments prioritize capability depth over cost minimization.
Supply Chain Analysis
Export-control regime restrictions on advanced AI training hardware and encryption technologies limit component flows into CLM platform development. Supply concentrates in the United States for core software engineering, with specialized NLP model training drawing from cloud compute clusters in Virginia and Oregon. Raw material dependencies center on semiconductor access, data center real estate, and legal corpus training datasets. Single-source vulnerability runs through hyperscale cloud hosting for financial services uptime requirements. Distribution runs through direct enterprise sales teams and channel partners serving regional healthcare systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as SEC disclosure mandates and HIPAA compliance requirements create specialized niches for AI-native governance platforms serving regulated verticals.
For Market Incumbents: Pre-empt mid-market consolidation by acquiring self-service CLM specialists before subscription pricing erodes enterprise deal flow. Deepen API-first ecosystem positioning to capture real-time Salesforce and Workday synchronization requirements. Defend against procurement-linked suite expansion from adjacent spend analytics vendors by embedding clause libraries directly into ERP workflows. For New Entrants and Emerging Players: Florida's regional healthcare systems and Texas professional services corridors represent underpenetrated whitespace for rapid-deployment self-service tiers. Target hospital networks lacking legal engineering talent with managed service packaging that outsources platform administration. Lead with pre-configured HIPAA compliance templates to accelerate procurement cycles against incumbent implementation timelines. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-automation play because regulatory disclosure mandates are structurally expanding contract governance addressable spend. Acquisition targets should display AI extraction capabilities trained on legal corpora with proven hospital network or public company deployments. Watch for SEC enforcement patterns around material contract identification as the inflection signal for platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Real-time ERP synchronization with SAP and Oracle environments compresses procurement-to-payment cycles for manufacturing clients. |
| AI Extraction Enhancement | Legal corpus-trained NLP engines reduce material contract review timelines ahead of SEC quarterly filing deadlines. |
| Geographic Expansion | Mid-market penetration in Texas and Florida professional services accelerates subscription revenue without enterprise sales overhead. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure ensure HIPAA-compliant hosting infrastructure for hospital network deployments. |
| Acquisition of Specialist Firm | Self-service CLM specialists add rapid-deployment capabilities that offset legacy integration project delays. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with legal operations directors, healthcare procurement officers, CLM platform engineers, and enterprise software channel partners. Secondary validation drew from SEC Regulation S-K filings, HIPAA enforcement actions, hyperscaler capex disclosures, and hospital system procurement databases. Bottom-up sizing of deployment volumes triangulated against top-down segment spending estimates across the analysis window.
Calibration against historical adoption curves and regulatory implementation timelines anchored projection models. Segmentation dimensions spanned deployment architecture, organization scale, vertical industry, integration complexity, and regional compliance environment. CAGRs were derived from fitted growth curves applied to base-year estimates, with inputs including legal department headcount trends, SEC filing volume growth, and cloud infrastructure expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native entrants or hyperscaler platform bundling would shift outcomes. Material shifts in SEC disclosure enforcement intensity or state-level data sovereignty rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Tech Support Services Market
Software & Services
Global OEE Software Market
Software & Services
Quality Management Software Market
Software & Services
Global Translation Software Market
Software & Services
Global Script Writing Software Market
Software & Services
Data Visualization Software Market
Software & Services
Lending Software Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Artwork Management Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Global Desktop As a Service Market
Software & Services
OCR Scanning Software Market