
 Collaborative Whiteboard Software Market | 2026-2036
Collaborative Whiteboard Software Market Size, Share, and Industry Trends Forecast 2026-2036
Collaborative Whiteboard Software Market Analysis
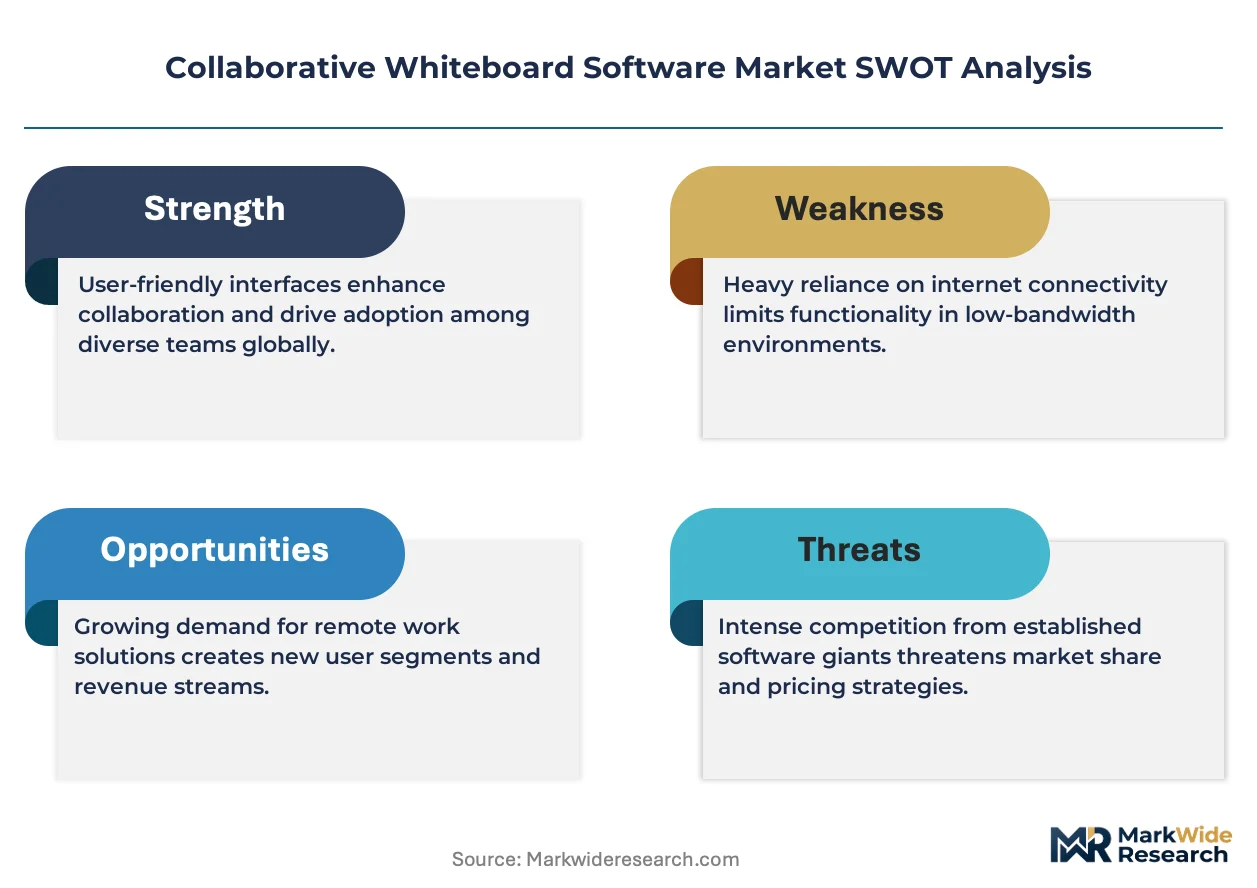
ISO 27001 information security certification is reorganizing the competitive landscape for collaborative whiteboard software vendors, as enterprise procurement teams mandate audited data protection frameworks before contract approval. Microsoft Corporation leverages its Azure cloud infrastructure to anchor security credentials across government and healthcare segments. Miro competes through deep integration partnerships with Atlassian and Slack, extending workflow connectivity for distributed product teams. Cisco Systems, Inc. dominates in regulated industries where Webex ecosystem lock-in controls enterprise purchasing decisions.
Collaborative whiteboard software comprises digital canvas platforms that enable synchronous visual communication through vector-based rendering engines, WebRTC data channels, and conflict-free replicated data types for real-time state synchronization. Cloud-based deployment leads segment value generation due to zero-install scalability and automatic security patching, while on-premise alternatives occupy niche demand from defense contractors and financial institutions with air-gapped infrastructure requirements. The education sector represents the fastest-growing end-user category as K-12 districts and universities replace physical smart boards with browser-accessible alternatives.
FCC guidelines on data transmission integrity intersect with GDPR cross-border data transfer rules to shape where vendors locate processing infrastructure and how consent mechanisms function within shared workspaces. ETSI cybersecurity standards for cloud services are gaining traction among European enterprise buyers evaluating vendor risk profiles. Procurement teams must monitor evolving AI Act provisions on automated content generation within collaborative tools, as real-time suggestion features trigger forthcoming transparency obligations.
Market Dynamics
ISO 27001 certification mandates are restructuring vendor qualification workflows as enterprise procurement teams reject unaudited cloud platforms. This security framework requirement is concentrating contract awards toward infrastructure providers with established compliance architectures.
Growth Catalysts
- Hybrid Work Persistence:Enterprise corporate teams maintain distributed collaboration requirements as physical office footprints shrink. Browser-accessible canvas tools replace conference room hardware.
- GDPR Cross-Border Transfer Rules:European data localization requirements push vendors to deploy EU-based processing infrastructure. This creates procurement preference for regional cloud presence.
- K-12 Digital Transformation:School districts accelerate smart board replacement with software-based alternatives. Education budgets redirect capital expenditure toward recurring SaaS licenses.
Market Restraints
- Air-Gapped Infrastructure Requirements:Defense contractors and financial institutions mandate on-premise deployment. Cloud-native architectures face exclusion from sensitive segments.
- WebRTC Bandwidth Dependency:Real-time synchronization requires stable high-throughput connections. Connectivity volatility degrades user experience in emerging market deployments.
- Atlassian-Slack Ecosystem Lock-In:Deep workflow integration with dominant productivity suites creates switching friction. Standalone whiteboard vendors struggle against bundled offerings.
Strategic Opportunities
- AI Act Transparency Obligations:Automated content generation features trigger forthcoming disclosure requirements. First-mover compliance creates competitive differentiation in European public sector procurement.
- Healthcare HIPAA Alignment:Protected health information handling demands specialized audit trails. Purpose-built clinical collaboration tools command premium pricing against generalist platforms.
- Vector-Based Rendering Convergence:Integration with CAD and design software extends addressable market. Engineering teams adopt whiteboard tools for technical diagramming workflows.
Industry Challenges
- Conflict-Free Replicated Data Type Engineering:Real-time state synchronization requires specialized distributed systems expertise. Talent scarcity constrains product development velocity for mid-tier vendors.
- FCC Data Transmission Integrity Certification:Telecommunications-grade reliability standards demand extended validation timelines. Compliance delays compress competitive windows for feature releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaborative Whiteboard Software Market |
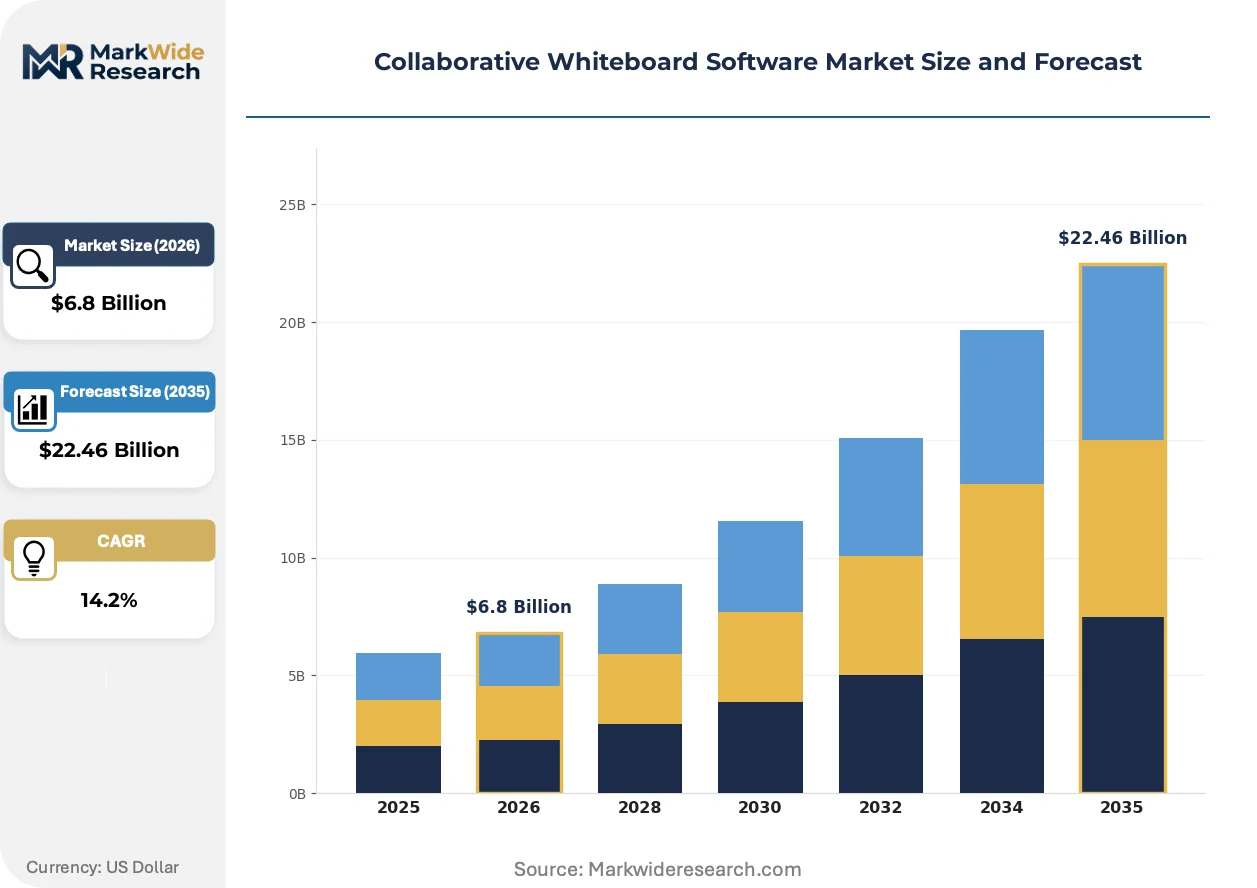
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Canvas, Sticky Notes, Drawing Tools, Templates Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Education Sector, Corporate Teams, Freelancers, Nonprofits Feature: Real-Time Collaboration, User Permissions, Integrations, Offline Access |
| Companies Covered | Miro, Microsoft Corporation, Google LLC, Cisco Systems, Inc., InVisionApp Inc., Mural, Stormboard, Conceptboard, Lucid Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaborative Whiteboard Software Market Emerging Trajectories
WebRTC data channel architectures are displacing proprietary synchronization protocols as the foundation for real-time collaboration. This shift compresses development barriers while elevating infrastructure performance expectations.
Vector-based rendering engines with WebAssembly acceleration are displacing raster-based canvas implementations. Product teams at software companies adopt these tools for interactive prototyping. The displacement is compressing hardware requirements while enabling mobile-first deployment strategies.
EU AI Act provisions on automated decision transparency are reshaping feature development roadmaps. Real-time suggestion engines face forthcoming disclosure and audit obligations. Healthcare and financial services segments in Germany and France are prioritizing vendors with explainable AI architectures.
Enterprise buying committees now mandate ISO 27001 evidence before pilot program approval. Security questionnaires have displaced functional demos as the primary vendor evaluation gate. United States federal contractors and German automotive suppliers exhibit the strictest documentation requirements.
Collaborative Whiteboard Software Market Segmentation
Segmentation in collaborative whiteboard software reveals how substitution pressures from adjacent productivity tools reshape competitive boundaries across product architectures and customer workflows. Understanding these divides exposes where vendors defend against bundled offerings versus where specialist capabilities command premium positioning.
Product Type:
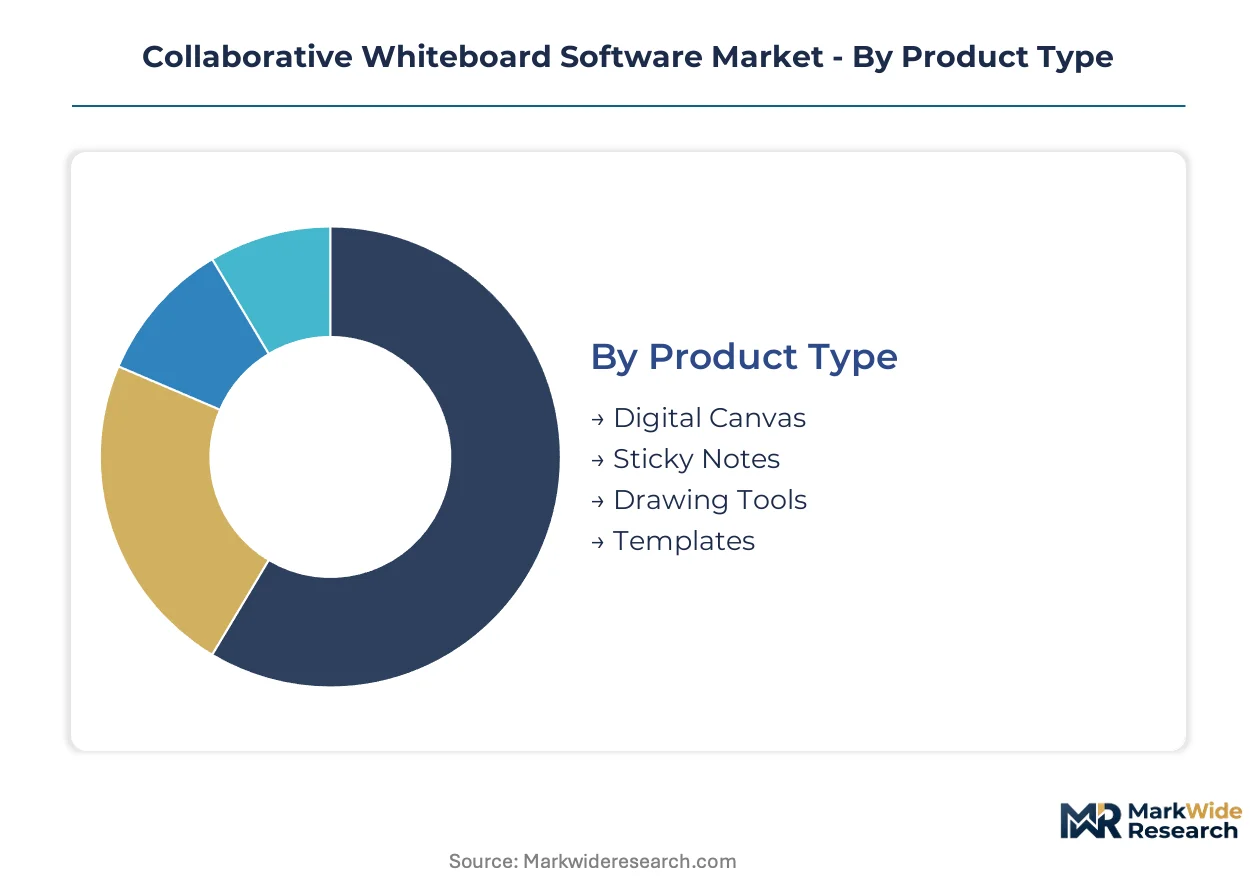
Digital canvas platforms face intense substitution from generalist design software, while template libraries create stickier retention through workflow-specific IP.
- Digital Canvas:Vector-based infinite zoom surfaces with WebGL rendering engines anchor enterprise deployments. United States corporate teams drive demand as physical whiteboard replacement accelerates in hybrid office configurations.
- Sticky Notes:Lightweight ideation objects with persistent state synchronization across sessions. Education sector procurement in Germany favors these for classroom brainstorming where device heterogeneity complicates full canvas adoption.
- Drawing Tools:Precision annotation capabilities with pressure-sensitive input support.
- Templates:Pre-structured canvases for Agile ceremonies and design sprints.
Digital Canvas anchors the volume base while Templates gains share at the steepest rate.
Deployment:
Deployment architecture determines compliance eligibility and total cost of ownership trajectories across customer maturity stages.
- Cloud-Based:Browser-delivered platforms with automatic security patching and zero-install onboarding. Japanese enterprise buyers prioritize these for rapid subsidiary rollout without IT infrastructure investment.
- On-Premise:Air-gapped server installations with localized data residency controls. Defense contractors in the United States mandate these for classified project collaboration, excluding cloud-native vendors from sensitive procurement.
- Hybrid:Split architectures with cloud orchestration and on-premise data storage.
- SaaS:Subscription-metered access with tiered feature entitlements.
Cloud-Based deployment captures the majority revenue position while Hybrid architectures expand most quickly among regulated mid-market buyers.
End User:
Customer type segmentation maps pricing power against procurement sophistication and switching cost profiles.
- Education Sector:K-12 districts and universities replacing physical smart boards with browser-accessible alternatives. Budget constraints in United States public school systems favor freemium conversion models over upfront licensing.
- Corporate Teams:Distributed product and engineering groups requiring real-time synchronization. German automotive suppliers exhibit the strictest ISO 27001 documentation requirements before pilot approval.
- Freelancers:Individual practitioners with low collaboration volume and high price sensitivity.
- Nonprofits:Grant-funded organizations with irregular procurement cycles and volunteer-driven adoption.
Corporate Teams dominate current revenue while Education Sector climbs the fastest as digital transformation budgets redirect from hardware to software.
Feature:
Capability segmentation tracks where engineering investment converts to competitive differentiation versus table-stakes parity.
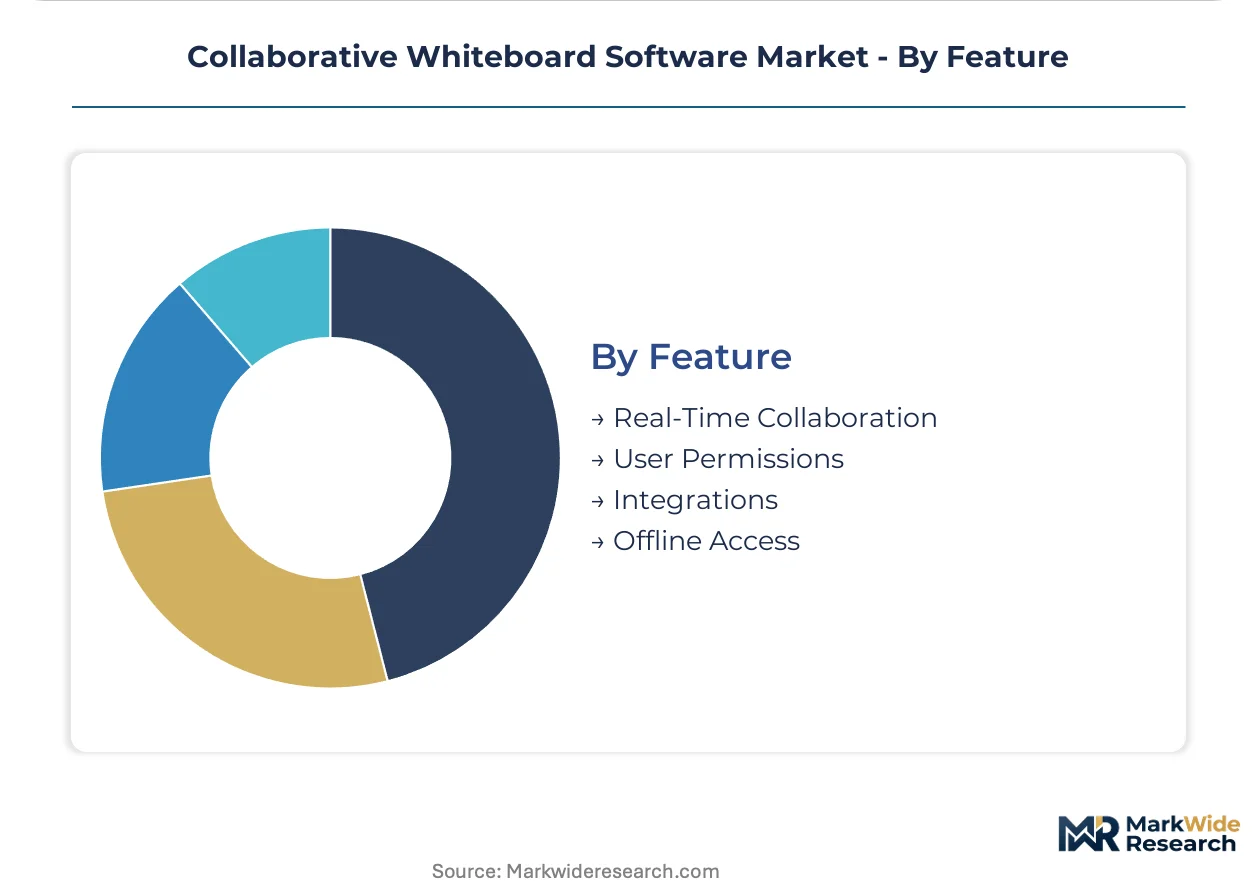
- Real-Time Collaboration:WebRTC data channel implementations with conflict-free replicated data types for state synchronization. Product teams at software companies in Japan adopt these for interactive prototyping workflows that compress hardware requirements.
- Integrations:API connectivity with dominant productivity suites including Atlassian and Slack ecosystems. Deep workflow integration creates switching friction that standalone vendors struggle to overcome.
- User Permissions:Role-based access controls with audit logging for compliance documentation.
- Offline Access:Local-first architectures with deferred synchronization for connectivity-volatile environments.
Real-Time Collaboration underpins category definition while Integrations demonstrates the steepest expansion trajectory as ecosystem connectivity becomes a primary evaluation criterion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government cloud-first mandates and data localization statutes are steering procurement decisions toward vendors with certified regional infrastructure. ISO 27001 documentation requirements now gate contract eligibility across public sector and regulated industries.
United States
Federal contractors drive demand for FedRAMP-authorized platforms with air-gapped deployment options. FCC data transmission integrity guidelines shape vendor qualification timelines for telecommunications-grade reliability. Austin and Seattle tech clusters host product teams advancing WebRTC synchronization for distributed software engineering workflows.
Germany
Automotive suppliers mandate ETSI cybersecurity standards and ISO 27001 evidence before pilot approvals for collaborative tools. GDPR cross-border transfer rules push vendors toward Frankfurt and Munich data centers for EU processing residency. Stuttgart engineering clusters adopt whiteboard platforms for CAD-integrated technical diagramming.
Japan
METI digital transformation subsidies accelerate enterprise SaaS adoption for hybrid work infrastructure. JIS standards compliance governs procurement evaluation for cloud service security. Tokyo and Osaka corporate headquarters prioritize browser-accessible canvas tools for rapid subsidiary rollout without capital expenditure.
United Kingdom
NCSC cloud security principles guide public sector whiteboard procurement for education and healthcare segments. Post-Brexit data adequacy negotiations influence vendor infrastructure location decisions. London financial services firms evaluate specialized audit trail capabilities for compliance documentation.
India
MeitY data localization requirements under the Digital Personal Data Protection Act steer vendor server deployment toward Mumbai and Bangalore regions. PLI scheme incentives for IT hardware manufacturing indirectly support adjacent software adoption. Hyderabad and Pune IT services clusters integrate whiteboard tools into client delivery workflows.
Collaborative Whiteboard Software Market Vendor Landscape
Player mix skews toward cloud-native specialists with deep ecosystem integration partnerships. Market structure exhibits tiered consolidation around infrastructure-backed incumbents and workflow-embedded challengers. Three archetypes dominate: hyperscale platform extenders, standalone collaboration specialists, and verticalized industry solutions. Competitive moves concentrate on strategic partnerships with dominant productivity suites and geographic data center expansion for compliance localization.
Within the ecosystem-embedded tier, Microsoft Corporation and Cisco Systems, Inc. anchor positions through infrastructure lock-in and Webex integration respectively. Miro occupies a specialist position exemplifying deep Atlassian and Slack connectivity for distributed product teams. These three represent contrasting defensive strategies against bundled platform substitution.
| Leading Market Players |
|---|
| Miro |
| Microsoft Corporation |
| Google LLC |
| Cisco Systems, Inc. |
| InVisionApp Inc. |
| Mural |
| Stormboard |
| Conceptboard |
| Lucid Software Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day provisioning cycles for ISO 27001 audit documentation compress competitive windows for SaaS vendors while amplifying pricing power for pre-certified infrastructure providers. Cloud-native architectures with established compliance frameworks command subscription premiums against mid-tier challengers facing extended qualification timelines.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 27001 evidence gating enterprise procurement at the high end. Three-tier pricing structure across premium, standard, and economy levels segments by audit depth, data residency controls, and integration complexity. Cost compression in the standard tier intensifies because hyperscale platform bundling erodes standalone vendor margins. Education sector buyers exhibit highest price sensitivity due to capital-to-operating-expense conversion pressures, while defense contractors demonstrate lowest sensitivity given air-gapped deployment mandates.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes strain hardware provisioning for hybrid deployment customers requiring localized server infrastructure. Cloud processing capacity concentrates in the United States, Germany, and Japan, with secondary nodes expanding in India and the United Kingdom under data localization statutes. Vector rendering engines and WebRTC data channel implementations rest on specialized distributed systems talent pools concentrated in Austin, Seattle, and Tokyo engineering clusters. Single-source vulnerability sits with hyperscale infrastructure providers controlling regional availability zones. Distribution runs through direct enterprise sales teams supplemented by channel partners for education and mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collaborative whiteboard software functions as a defensive-moat market where switching costs lock enterprise workflows into ecosystem-embedded platforms. Regulatory entrenchment through ISO 27001 and sector-specific compliance deepens incumbent advantages against unbundled challengers.
For Market Incumbents: Fortify ecosystem lock-in through deeper Atlassian and Slack integration partnerships that elevate switching costs for distributed product teams. Expand Frankfurt and Mumbai data center footprints to preempt GDPR and MeitY localization requirements before contract eligibility gates tighten. Prioritize WebRTC engineering talent acquisition as conflict-free replicated data type expertise constrains mid-tier competitor velocity. For New Entrants and Emerging Players: Differentiate on clinical workflow specialization for HIPAA-aligned healthcare segments where generalist platforms lack purpose-built audit trails. Target K-12 education districts in the United States where freemium conversion models and hardware replacement budgets create accessible entry points. Pursue white-label partnerships with learning management system providers to bypass direct sales cost structures. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-entrenchment play because ISO 27001 certification requirements concentrate procurement toward pre-audited vendors with established government and healthcare segment presence. Acquisition targets should display vertical workflow IP in regulated industries rather than horizontal feature parity. Watch for AI Act transparency obligation enforcement in Germany and France as an inflection signal for explainable AI architecture premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Atlassian and Slack connectivity elevates switching costs for enterprise product teams. |
| Geographic Expansion | Frankfurt and Mumbai data centers satisfy GDPR and MeitY localization mandates. |
| Acquisition of Specialist Firm | Clinical workflow IP commands premium pricing in HIPAA-regulated healthcare segments. |
| Product Launch | AI-transparent suggestion engines align with forthcoming EU AI Act disclosure obligations. |
| Strategic Partnership | LMS provider alliances bypass direct sales friction in budget-constrained education procurement. |
Methodological Framework
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and integration specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie usage data, and ETSI cybersecurity standard documentation. Bottom-up deployment model sizing triangulated against top-down enterprise SaaS spend estimates across the analysis window.
Sensitivity analysis tested forecast robustness across alternative hybrid work persistence scenarios and regulatory enforcement timelines. Segmentation dimensions modeled include deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from installed base growth rates multiplied by average revenue per account trajectories, with WebRTC bandwidth penetration and ISO 27001 certification velocity as key forecast inputs.
Material uncertainties — AI Act enforcement timing, air-gapped infrastructure procurement shifts, and education budget reallocations — sit outside the modeled envelope. Forecasts reflect documented assumptions about hybrid work persistence and compliance framework adoption. Recalibration cycles align with material shifts in regulatory enforcement, hyperscaler bundling strategies, and distributed systems talent availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
Japan IT Services Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Global Automation Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Federal Government Software Market
Software & Services
Customs Declaration Software Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Public Financial Management Software Market
Software & Services
Automotive Operating Systems Market