
 Global Storm Tracking Apps Market | 2026-2036
Global Storm Tracking Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Storm Tracking Apps Market Foresight
Market Context
Emergency responders is bifurcating the buyer base away from casual consumers as institutional procurement replaces individual downloads. AccuWeather, Inc. leverages its radar network density to dominate enterprise contracts with state emergency management departments. DTN LLC anchors its position through exclusive aviation safety integrations that filter storm corridors for flight path optimization.
Technical Definition and Segment Structure
Storm tracking apps are software platforms that ingest meteorological sensor data, satellite imagery, and Doppler radar feeds to calculate precipitation intensity, storm trajectory, and arrival timing with geographic precision. These systems serve commercial and institutional users who require sub-minute alerting to protect personnel, crops, infrastructure, or passenger safety. The Application dimension shows Disaster Management commanding the largest deployment base while Aviation Safety generates the highest per-seat pricing due to FAA-mandated weather minimums for commercial operators. Platform segmentation reveals iOS and Android capturing consumer volume, yet Windows and Web deployments sustain margin pools through government and meteorological laboratory contracts that demand desktop-grade visualization.
Regulatory Frame
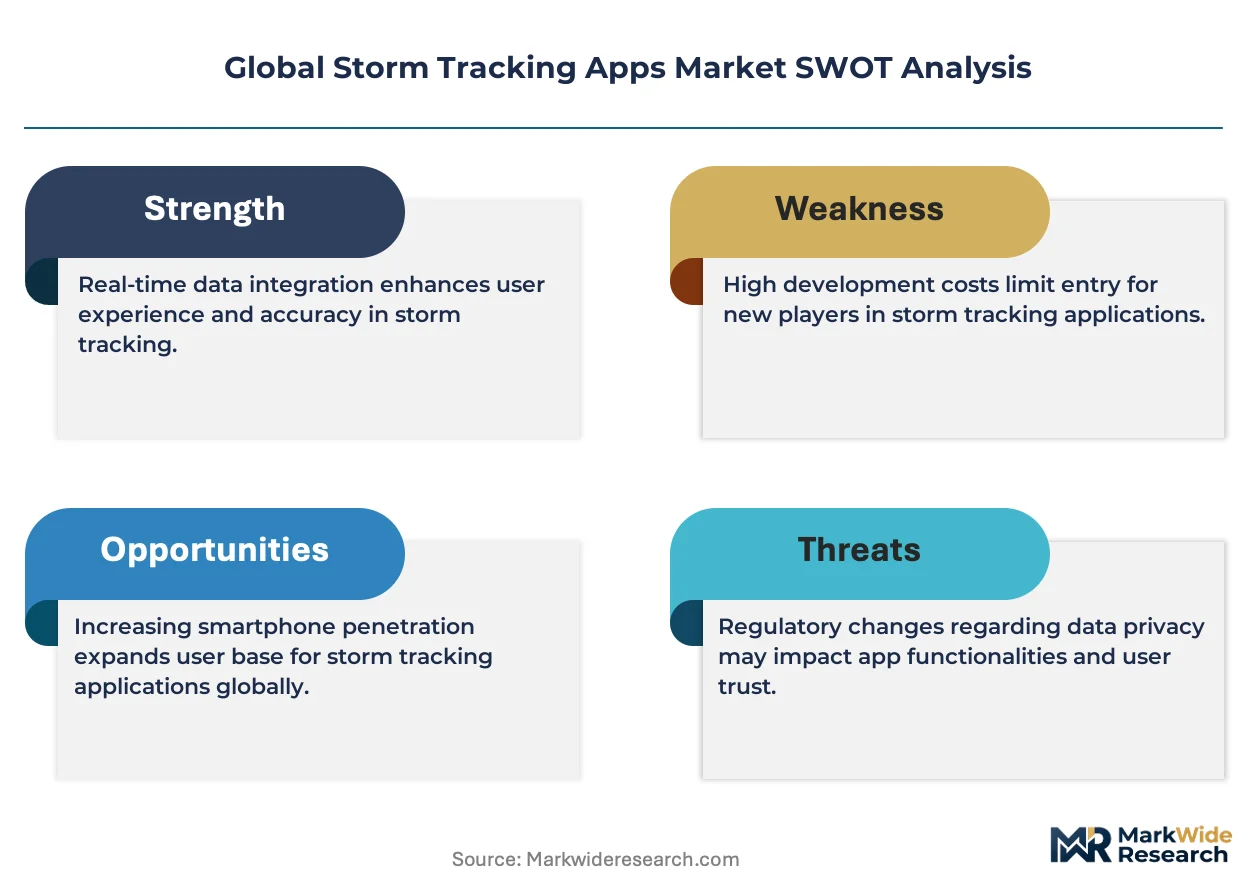
FAA regulations govern weather data sourcing for flight operations, while FEMA guidelines shape emergency alert distribution protocols that storm tracking vendors must embed to qualify for federal procurement. The EU AI Act and GDPR impose algorithmic transparency and location data handling requirements on apps serving European users, complicating cross-border data pipeline architectures. Stakeholders must monitor whether national meteorological services tighten data licensing terms or mandate open-standard APIs that could erode proprietary feed advantages.
Market Dynamics
Satellite-to-mobile data pipelines are compressing alert latency from minutes to seconds, forcing vendors to rebuild their ingestion architectures around real-time edge processing rather than batch radar cycles. This infrastructure shift is bifurcating the competitive landscape between legacy providers and cloud-native entrants.
Growth Catalysts
- FEMA Procurement Standards:Federal emergency management protocols now mandate sub-minute alerting capabilities, creating institutional demand pull for enterprise-grade storm tracking platforms in the United States.
- Synthetic Aperture Radar Satellites:Commercial SAR constellations are delivering all-weather precipitation monitoring, eliminating the data gaps that previously plagued optical satellite-dependent apps during nighttime or cloud-covered events.
- Aviation Weather Minimums:FAA regulations governing commercial flight operations require continuous storm corridor monitoring, generating premium-priced subscription demand from airlines and charter operators.
Market Restraints
- Proprietary Data Licensing:National meteorological services in Germany, Japan, and the United Kingdom impose per-query fees on commercial app developers, inflating variable cost structures for real-time feed integration.
- Silicon Supply Concentration:Edge processing chipsets for mobile radar computation depend heavily on Taiwan-based fabrication capacity, exposing vendors to geopolitical supply disruption risk.
- Algorithmic Transparency Mandates:The EU AI Act requires explainable precipitation prediction models, forcing developers to abandon black-box neural networks in favor of interpretable physics-based simulations with higher computational overhead.
Strategic Opportunities
- Brazil Agricultural Corridor:Soybean and sugarcane cooperatives in Mato Grosso and São Paulo states lack precision storm alerting, presenting white-space demand for Portuguese-language platforms with crop-loss modeling.
- 5G Network Slicing:Telecom operators in South Korea and the United States are offering guaranteed-latency slices for emergency services, enabling storm tracking apps to monetize quality-of-service guarantees to fire and police departments.
- Parametric Insurance Integration:Weather-indexed crop and property insurers in India and Kenya require verified storm intensity data for automated payout triggers, opening B2B2C distribution channels through insurance partnerships.
Industry Challenges
- Atmospheric Data Science Talent:The intersection of meteorology, machine learning, and mobile software engineering commands premium compensation, constraining vendor hiring pipelines in competitive labor markets.
- Legacy Radar Integration:Government meteorological laboratories in France, Australia, and Canada operate decades-old Doppler systems with incompatible data formats, forcing costly middleware development for feed standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Storm Tracking Apps Market |
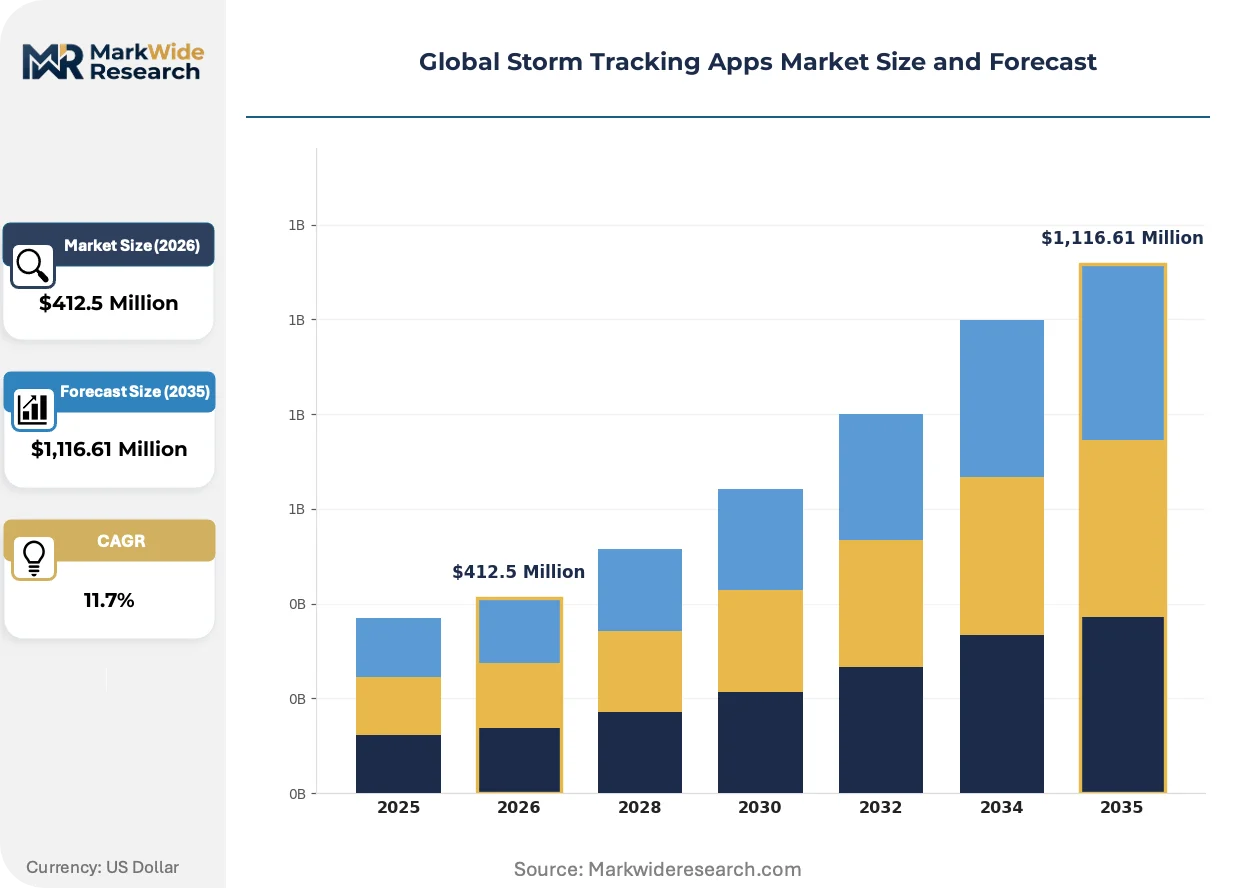
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,116.61 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: iOS, Android, Web, Windows, macOS Application: Disaster Management, Agriculture Planning, Aviation Safety, Event Coordination, Research Analysis End User: Government Agencies, Meteorologists, Emergency Responders, Media Outlets, Outdoor Enthusiasts Subscription Model: Free, Freemium, Monthly, Annual, Pay-per-Use |
| Companies Covered | AccuWeather, Inc., The Weather Company, DTN LLC, WeatherBug, ACME AtronOmatic, Radarscope LLC, CARROT Weather, Apalon LLC, The Scripps Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Storm Tracking Apps Market Shifts & Advancements
Edge-native computation is displacing cloud-centric processing architectures across the storm tracking value chain. Vendors are racing to deploy lightweight precipitation models directly onto smartphones and vehicle infotainment systems, reducing dependency on continuous connectivity.
Neural network precipitation nowcasting is fragmenting the competitive moat of established radar network operators. Startups in Israel and Singapore are training generative models on open satellite datasets to predict storm trajectories 30-60 minutes ahead without proprietary ground-based sensor infrastructure. Agricultural cooperatives in Argentina and drought-response agencies in Spain are piloting these platforms, drawn by subscription pricing 40-60% below legacy providers. The technology is fragmenting market share concentration and eroding the data exclusivity that historically protected incumbent vendors.
REACH chemical compliance and the EU AI Act are jointly reshaping hardware deployment strategies for European markets. Storm tracking wearables and vehicle-integrated alert systems must now document supply chain provenance for lithium batteries and rare-earth magnets while providing algorithmic audit trails for automated warning triggers. Automotive OEMs in Germany and fleet operators in the Netherlands are demanding pre-certified modules, pushing component vendors to front-load compliance documentation rather than retrofit post-launch.
Subscription unbundling is disrupting the traditional all-you-can-eat pricing model that dominated consumer storm app monetization. Freemium platforms in the United States and United Kingdom are now selling hyperlocal street-level alerts, lightning proximity notifications, and historical storm reconstruction as separate microtransactions. Casual users in Florida and Texas coastal counties are gravitating toward event-based purchasing during hurricane season rather than annual commitments, compressing vendor revenue recognition cycles and forcing cash flow management adaptations.
Global Storm Tracking Apps Market Segmentation
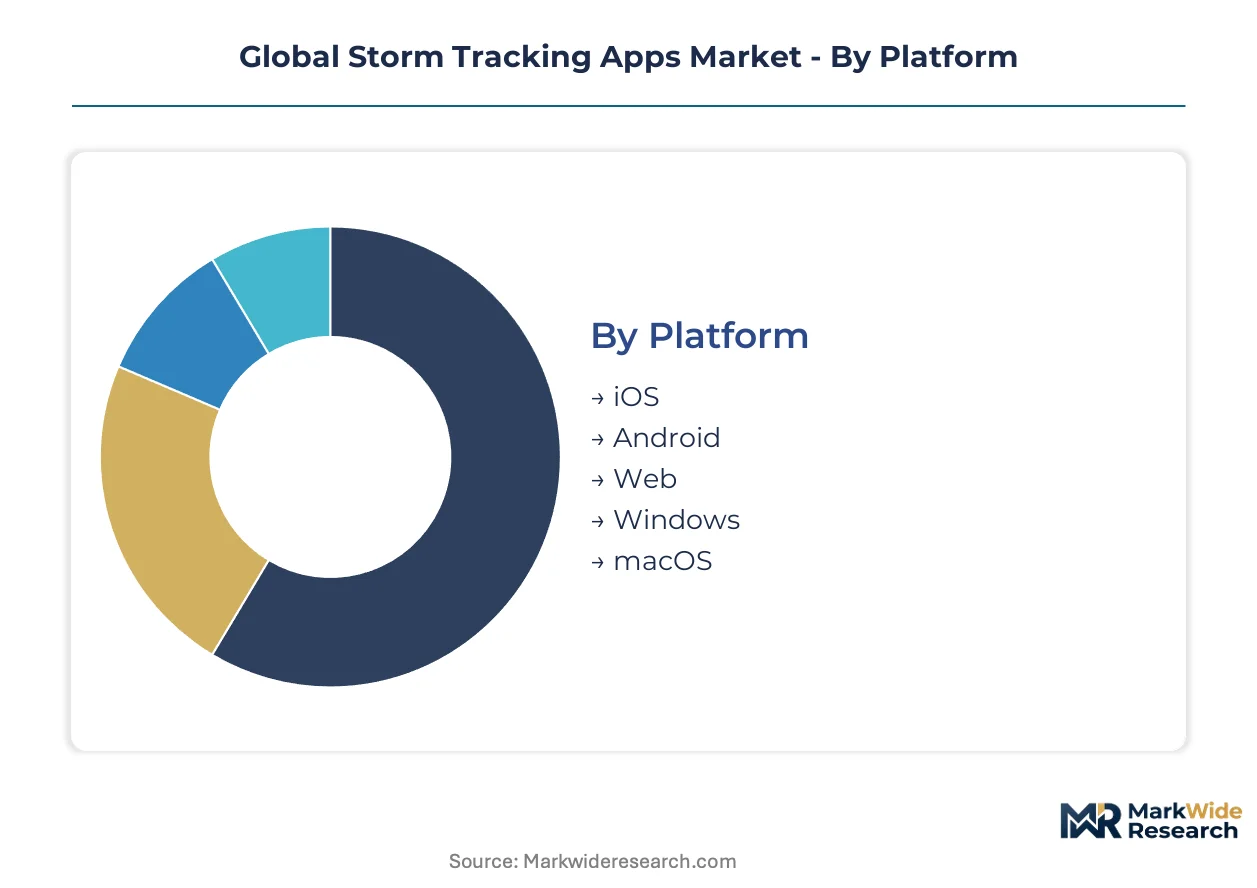
Storm tracking apps serve radically different performance requirements across consumer handhelds, enterprise workstations, and embedded aviation systems. Platform choice determines latency tolerance, visualization depth, and procurement authority, while application focus shapes data feed complexity and pricing architecture.
Platform:
iOS and Android deployments concentrate in domestic consumer markets where individual users download weather alerts for personal safety. Web and Windows platforms anchor export-led institutional contracts requiring desktop-grade radar visualization and multi-user dashboard access.
- iOS:Premium hardware sensors enable barometric pressure calibration and precise GPS storm proximity alerts. Demand clusters in coastal United States counties where hurricane evacuation orders trigger mass downloads during seasonal peaks.
- Android:Fragmented device ecosystem forces developers to optimize for lowest-common-denominator processing power, compressing margin through extended QA cycles. Volume leadership in India and Brazil stems from price-sensitive smartphone penetration.
- Web:Browser-based platforms bypass app store commission structures while delivering full-resolution radar loops to emergency operations centers. Procurement runs through municipal IT departments in Germany and Japan.
- Windows:Legacy government meteorological laboratories in France and Australia standardize on desktop Windows deployments for radar data ingestion and archival storm reconstruction.
- macOS:Niche scientific workstation segment serves university atmospheric research departments with specialized visualization plugins for dissertation-grade storm analysis.
iOS holds the largest share; momentum sits with Web deployments as municipalities consolidate vendor relationships.
Application:
Cost tier stratification separates life-safety mandates from discretionary planning tools. Aviation and disaster management command premium subscription tiers with regulatory compliance overhead, while agriculture and event coordination compete on per-acre or per-ticket economics.
- Disaster Management:Real-time situational awareness platforms integrate FEMA alert protocols and multi-agency coordination dashboards. Procurement concentrates in United States state emergency management departments with federal grant funding.
- Aviation Safety:FAA-mandated weather minimums require continuous storm corridor monitoring with documented data provenance for flight plan liability. Airlines and charter operators in the United States and United Kingdom absorb the highest per-seat pricing in the market.
- Agriculture Planning:Crop-loss modeling algorithms predict hail damage and soil saturation windows for planting decisions. Soybean cooperatives in Mato Grosso, Brazil present white-space demand for Portuguese-language platforms.
- Event Coordination:Lightning proximity alerts and precipitation timing drive outdoor concert and sporting venue decisions. Music festival promoters in Tennessee and Texas purchase event-based microtransactions rather than annual commitments.
- Research Analysis:Archival storm reconstruction and climate trend modeling serve university atmospheric science departments with grant-funded procurement cycles.
Disaster Management holds the largest share; Aviation Safety climbs the fastest as post-pandemic flight operations normalize.
End User:
Customer type determines contract structure, with government agencies demanding multi-year enterprise licenses and outdoor enthusiasts driving freemium conversion rates through seasonal surge behavior.
- Government Agencies:Federal, state, and municipal emergency management departments mandate sub-minute alerting with 99.999% uptime SLAs. FEMA procurement standards in the United States filter vendor eligibility through documented disaster response integration.
- Meteorologists:Professional atmospheric scientists require raw radar feed access and custom algorithm development environments. National meteorological services in Japan and Germany impose per-query data licensing fees that inflate platform costs.
- Emergency Responders:Fire departments and police units deploy vehicle-integrated alert systems with guaranteed-latency 5G network slicing. South Korean telecom operators pioneered quality-of-service monetization for this segment.
- Media Outlets:Television stations and digital publishers license storm tracking visualizations for broadcast weather segments with co-branded radar attribution.
- Outdoor Enthusiasts:Hikers, boaters, and amateur storm chasers represent the most price-sensitive segment with high churn and hurricane-season usage spikes.
Government Agencies hold the largest share; Emergency Responders gain share fastest as institutional procurement replaces consumer downloads.
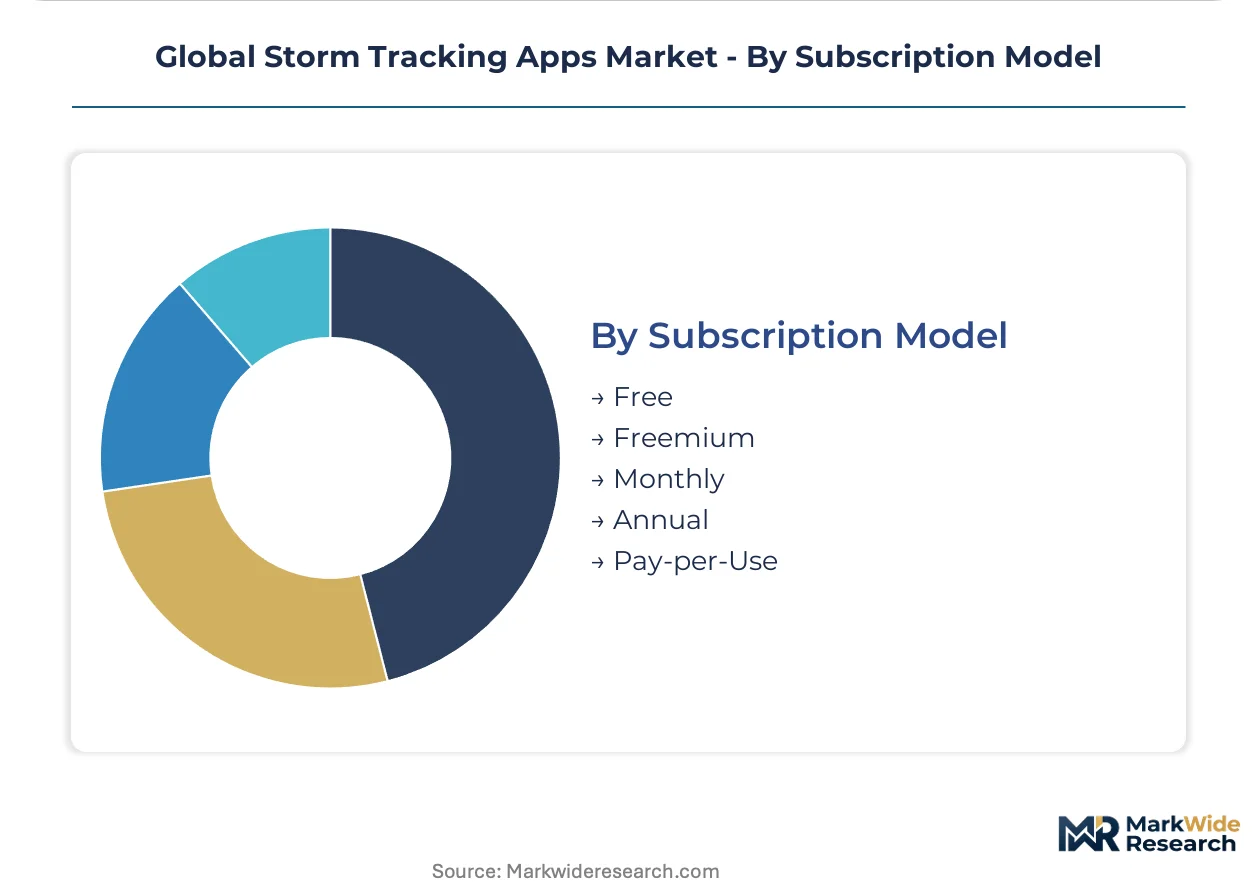
Subscription Model:
Revenue recognition cycles compress as seasonal users abandon annual commitments. Maturity gradients separate experimental freemium platforms from established annual-recurrence vendors with embedded enterprise workflows.
- Free:Ad-supported tier drives user acquisition for hurricane season surges but monetizes poorly outside coastal United States markets.
- Freemium:Base radar access with hyperlocal street-level alerts and lightning proximity sold as microtransactions. Florida and Texas coastal users prefer event-based purchasing.
- Monthly:Flexible commitment tier captures agricultural planners with crop-cycle timing and event coordinators with seasonal venue contracts.
- Annual:Enterprise standard for government agencies and aviation operators with budget predictability requirements and multi-user license management.
- Pay-per-Use:Verified storm intensity data triggers for parametric crop and property insurers in India and Kenya, opening B2B2C distribution through automated payout integration.
Annual holds the largest share; Freemium expands most quickly as vendors unbundle all-you-can-eat pricing into microtransaction architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States NOAA satellite ground station network and FEMA procurement pipelines anchor institutional demand for sub-minute alerting platforms. European meteorological data licensing regimes and Asian aviation corridor density shape divergent deployment economics across major markets.
United States
FEMA procurement standards mandate sub-minute alerting capabilities for state emergency management departments. FAA regulations govern weather data sourcing for commercial flight operations, creating premium subscription demand from airlines. Coastal counties in Florida and Texas drive seasonal consumer surges during hurricane evacuation periods.
Germany
REACH chemical compliance and the EU AI Act jointly reshape hardware deployment strategies for storm tracking wearables. The country's national meteorological service imposes per-query data licensing fees on commercial developers. Automotive OEMs in Stuttgart demand pre-certified modules with algorithmic audit trails for vehicle-integrated alert systems.
Japan
Commercial SAR constellations deliver all-weather precipitation monitoring for aviation safety applications. METI standards influence edge processing chipset procurement for mobile radar computation. Tokyo-based telecom operators pilot 5G network slicing for guaranteed-latency emergency services alerts.
Brazil
Soybean and sugarcane cooperatives in Mato Grosso and São Paulo states present white-space demand for Portuguese-language platforms. ANVISA compliance requirements shape data handling protocols for cross-border satellite feeds. Agricultural clusters in the Cerrado biome lack precision storm alerting infrastructure for crop-loss modeling.
South Korea
Telecom operators offer guaranteed-latency 5G slices for fire and police department alert systems. MFDS regulations govern medical-grade wearable integrations for emergency responder deployments. Seoul Capital Area municipalities consolidate vendor relationships around web-based multi-user dashboard platforms.
Global Storm Tracking Apps Market Competitive Landscape
Concentration sits with established meteorological data aggregators and aviation safety specialists who control proprietary radar network access and FAA-certified feed provenance. The competitive landscape bifurcates between legacy providers with embedded government contracts and cloud-native entrants leveraging generative nowcasting models on open satellite datasets. Three archetypes dominate: radar network operators with dense ground sensor infrastructure, satellite data integrators with SAR constellation partnerships, and edge-native platforms deploying lightweight precipitation models directly onto mobile devices. Dominant competitive moves include exclusive aviation safety integrations and geographic expansion into agricultural corridor white spaces.
Among United States-based weather intelligence platforms, AccuWeather, Inc. and The Weather Company exemplify the radar network operator archetype with embedded state emergency management relationships. DTN LLC occupies a position within the aviation safety specialist tier through flight path optimization integrations. These three entities represent the institutional procurement gravity that is displacing consumer-download monetization models across the sector.
| Leading Market Players |
|---|
| AccuWeather, Inc. |
| The Weather Company |
| DTN LLC |
| WeatherBug |
| ACME AtronOmatic |
| Radarscope LLC |
| CARROT Weather |
| Apalon LLC |
| The Scripps Company |
| Others |
Supply & Pricing Matrix
Long-term enterprise licensing agreements with state emergency management departments lock in multi-year revenue visibility while securing exclusive data feed access from NOAA infrastructure. These contractual structures tether vendor pricing power to institutional procurement cycles rather than consumer download volatility.
Pricing Analysis
Volume-discount tiering separates enterprise government contracts from individual consumer subscriptions. Three-tier pricing structure across premium aviation safety, standard disaster management, and economy consumer tiers reflects certification overhead and data provenance requirements. Cost compression in the consumer tier intensifies because neural network nowcasting startups undercut legacy radar operators by forty to sixty percent. Government agencies exhibit lowest price sensitivity due to FEMA grant funding, while outdoor enthusiasts demonstrate highest elasticity with hurricane-season surge behavior.
Supply Chain Analysis
Taiwan and South Korea anchor edge processing chipset fabrication for mobile radar computation. Taiwan Semiconductor Manufacturing and Samsung Foundry supply the silicon that powers sub-minute alerting capabilities. The supply chain draws from rare-earth magnet producers in China and lithium battery cell manufacturers across East Asia. Single-source vulnerability concentrates in Taiwan-based fabrication capacity exposed to geopolitical disruption. Distribution runs through telecom operator partnerships for 5G network slicing and direct enterprise sales to aviation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Satellite-to-mobile data pipelines compressing alert latency from minutes to seconds constitute a technological inflection reshaping competitive moats. FEMA procurement standards mandating sub-minute capabilities simultaneously create institutional demand pull and vendor eligibility barriers.
For Market Incumbents: Secure exclusive aviation safety integrations with FAA-certified feed provenance to defend against generative nowcasting entrants. Deepen backward integration into synthetic aperture radar constellation partnerships to maintain data exclusivity. Cloud-native startups training models on open satellite datasets threaten radar network operators with subscription pricing forty to sixty percent below legacy tiers.
For New Entrants and Emerging Players: Anchor in Brazil's agricultural corridor where Mato Grosso soybean cooperatives lack Portuguese-language precision storm alerting. Target parametric insurance integration in India and Kenya as a B2B2C distribution channel through automated payout triggers. White-space demand concentrates in crop-loss modeling for agricultural cooperatives underserved by incumbent geographic focus.
For Investors and Strategic Acquirers: Edge-native platform specialists with lightweight precipitation models deployable directly onto smartphones represent the most defensible acquisition archetype. These vendors reduce connectivity dependency while capturing 5G network slicing monetization opportunities. Watch for telecom operator guaranteed-latency slice commercialization as inflection signal for emergency responder segment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Aperture Radar Partnership | All-weather precipitation monitoring eliminates optical satellite data gaps during nighttime events. |
| 5G Network Slicing Integration | Guaranteed-latency slices enable quality-of-service monetization to fire and police departments. |
| Parametric Insurance Data Licensing | Verified storm intensity triggers automate crop and property payout decisions in emerging markets. |
| Edge-Native Model Deployment | Lightweight precipitation algorithms on smartphones reduce cloud dependency for remote users. |
| EU AI Act Compliance Certification | Algorithmic audit trails satisfy European regulatory requirements for explainable prediction models. |
Research Methodology
The analysis maps consumer handheld platforms, enterprise workstation deployments, and embedded aviation systems, each validated through emergency management procurement officers, airline operations executives, agricultural cooperative managers, and meteorological laboratory directors. Primary interviews with these stakeholders combined with secondary validation from FAA regulatory filings, NOAA technical specifications, EUMETNET data licensing records, and FEMA procurement databases. Bottom-up triangulation across platform deployment counts and top-down reconciliation against institutional budget allocations anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include platform ecosystem, application focus, end-user contract structure, and subscription model architecture. CAGRs derived from fitted growth curves incorporating satellite data pipeline latency improvements, 5G network slicing commercialization timelines, and regulatory procurement standard adoptions. Forecast inputs encompass SAR constellation deployment schedules and edge processing chipset supply constraints.
Decision-makers should treat outputs as directional under assumptions of continued NOAA infrastructure funding and stable Taiwan-based fabrication capacity; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in FEMA procurement standard revisions and commercial satellite constellation launch schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sales Enablement Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Ad Creation Software Market
Software & Services
Global Configuration Management Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Intellectual Property Software Market
Software & Services
Commercial Drone Software Market
Software & Services
Device Tracking Software Market
Software & Services
Global Decision Making Software Market
Software & Services
Photo Editing Software Market
Software & Services
Automated Testing Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Global Nosql Software Market