
 Quality Management Software Market | 2026-2036
Quality Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Quality Management Software Market Intelligence
Mid-market pharmaceutical manufacturers is rotating demand toward integrated compliance platforms that unify document control with supplier quality workflows. SAP leverages its ERP backbone to anchor enterprise deployments across regulated manufacturing environments. ETQ specializes in configurable quality suites that compete on deployment speed for firms with limited IT resources. Veeva Systems dominates cloud-native validation, extending its platform from life sciences into adjacent regulated sectors.
Quality management software comprises modular digital platforms that enforce standardized workflows for corrective action tracking, statistical process control, and audit trail generation, primarily serving organizations subject to ISO 9001, FDA 21 CFR Part 11, or EU MDR documentation mandates. Cloud-based deployment leads solution uptake as manufacturers prioritize remote accessibility and reduced infrastructure overhead, while on-premise installations retain footholds where data sovereignty or air-gapped security requirements dominate. Compliance management and document control modules capture concentrated margin pools due to their direct linkage to regulatory audit outcomes and certification maintenance.
FDA 21 CFR Part 11 and EU MDR frameworks compel pharmaceutical and medical device manufacturers to maintain immutable electronic records, directly expanding subscription demand for validation-ready software. ISO 9001 and IATF 16949 standards in automotive and aerospace supply chains further tighten documentation requirements, forcing tier-one suppliers to digitize quality workflows or risk contract disqualification. Stakeholders must monitor evolving FDA guidance on artificial intelligence in quality decision-making to anticipate validation burden shifts.
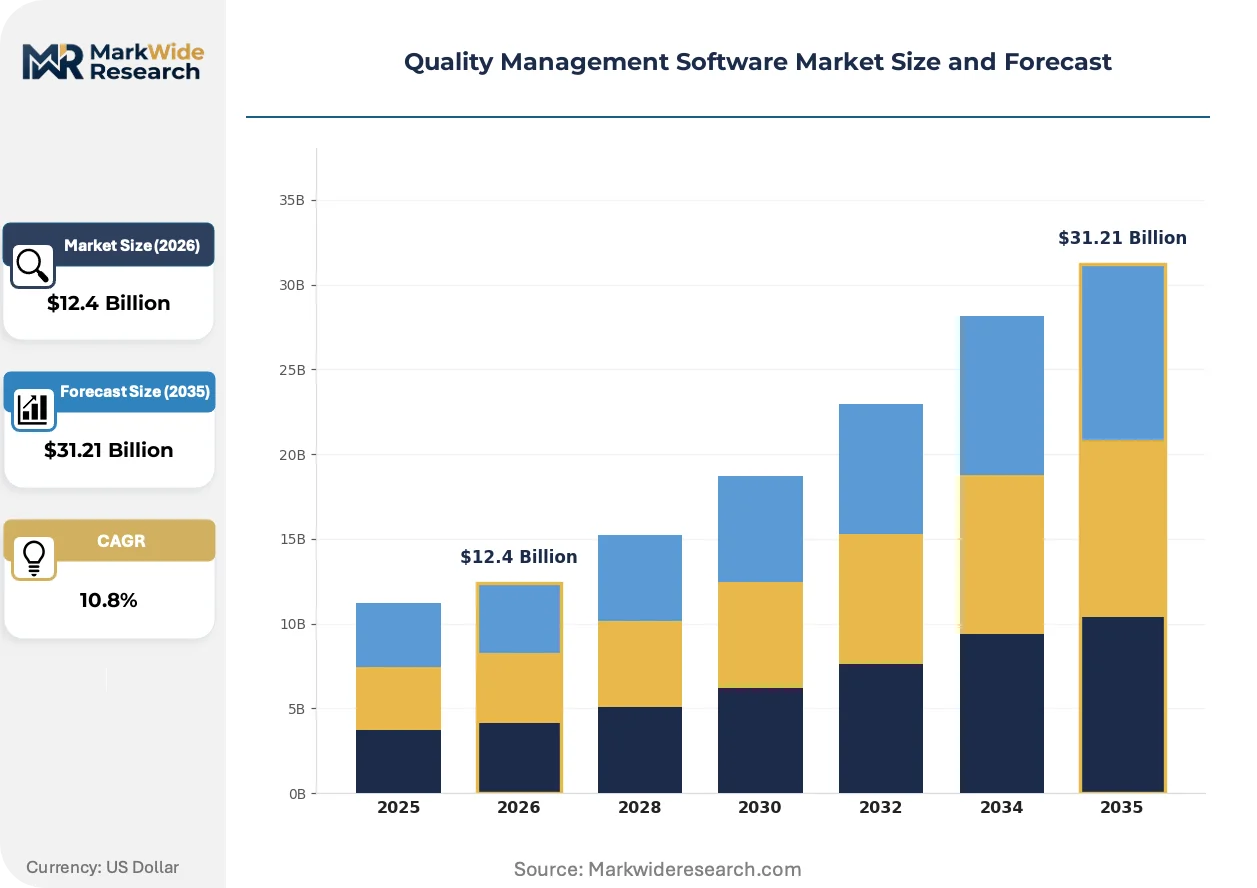
Market Dynamics
Cloud migration is compressing deployment cycles for quality management software as pharmaceutical manufacturers abandon multi-year on-premise implementations in favor of subscription-based validation platforms. This infrastructure shift is redistributing vendor power toward platforms with pre-built FDA 21 CFR Part 11 compliance modules.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates for pharmaceutical manufacturers are accelerating replacement of paper-based quality systems with validated digital audit trails.
- EU MDR documentation requirements:Medical device manufacturers face expanded technical file obligations, forcing digitization of design history records and post-market surveillance workflows.
- Automotive IATF 16949:Tier-one suppliers must demonstrate closed-loop corrective action tracking to retain OEM contracts, driving enterprise quality platform adoption.
Market Restraints
- Validation cost structure:FDA computer system validation requirements impose 18-24 month implementation timelines that freeze mid-market capital allocation.
- Specialized talent scarcity:Qualified CSV engineers command premium compensation, constraining deployment velocity for resource-constrained manufacturers.
- Legacy system entrenchment:On-premise ERP integrations with 15+ year depreciation cycles block cloud migration for regulated facilities with validated environments.
Strategic Opportunities
- AI-enabled quality decision support:Machine learning algorithms for predictive deviation detection represent unpenetrated white space beyond rules-based workflow automation.
- Supplier quality networks:Multi-enterprise platforms connecting OEMs with tiered suppliers capture value currently fragmented across email and spreadsheet coordination.
- India pharmaceutical manufacturing:CDSCO's alignment with ICH Q10 guidelines creates regulatory tailwind for quality digitization among export-oriented API producers.
Industry Challenges
- Computer System Validation expertise gap:Manufacturers struggle to recruit personnel capable of authoring IQ/OQ/PQ protocols that satisfy FDA inspector scrutiny.
- Integration complexity with MES and LIMS:Bidirectional data exchange between quality platforms and manufacturing execution systems requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quality Management Software Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $31.21 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile Solution Type: Audit Management, Compliance Management, Document Control, Risk Management, Supplier Quality Management Application: Pharmaceutical Manufacturing, Aerospace Manufacturing, Food Processing, Automotive Assembly, Electronics Production End User Industry: Life Sciences, Transportation Equipment, Consumer Goods, High Tech, Chemical Production |
| Companies Covered | SAP, Oracle, Microsoft, IBM, Siemens, MasterControl, ETQ, Veeva Systems, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quality Management Software Market Strategic Shifts & Innovations
Artificial intelligence capabilities are penetrating quality decision workflows faster than regulatory frameworks can validate them, creating competitive separation between vendors with pre-validated AI modules and those reliant on manual statistical process control. This capability gap is restructuring procurement criteria for pharmaceutical quality leaders.
Machine learning algorithms for predictive deviation detection are bifurcating the competitive landscape. Early adopters in sterile injectables manufacturing deploy neural networks to flag process anomalies before batch failures occur. Latecomers remain dependent on reactive CAPA workflows, compressing their margin position as audit costs mount.
EMA's forthcoming guidance on artificial intelligence in GxP environments is tightening validation requirements for algorithmic decision support. Pharmaceutical manufacturers are responding by demanding vendor-supplied algorithm transparency documentation. Cloud-native platforms with embedded explainability features capture preference share in EU-regulated submissions.
Subscription pricing for quality modules is displacing perpetual license models among mid-market life sciences firms. Buyers now expect validation documentation, training content, and regulatory update subscriptions bundled into annual contracts. This preference shift concentrates purchasing power with vendors offering integrated compliance-as-a-service rather than standalone software licenses.
Quality Management Software Market Segmentation
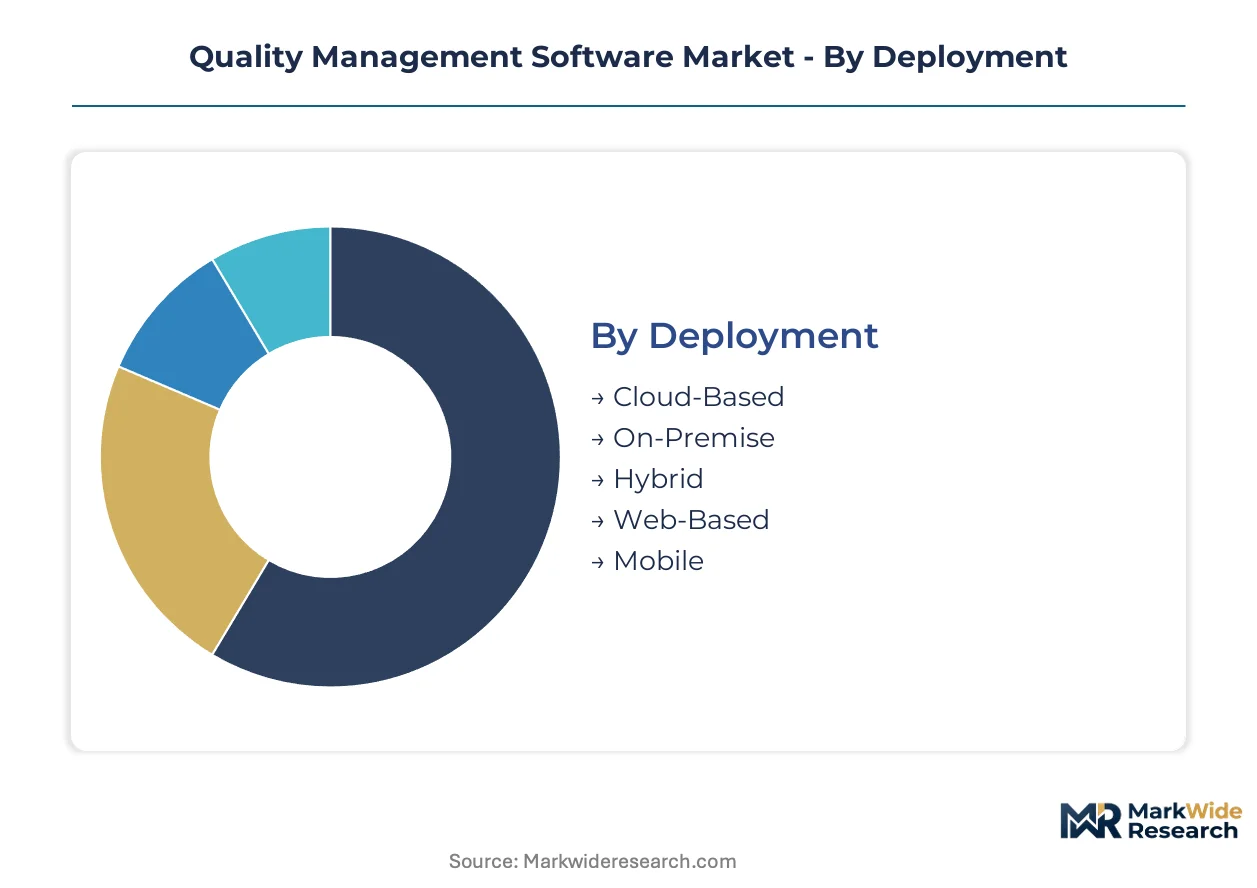
Quality management software procurement patterns diver sharply across deployment modes and solution architectures. Pharmaceutical manufacturers prioritize validation-ready configurations, while automotive and aerospace sectors weight supplier integration capabilities more heavily.
Deployment:
Cloud-based solutions flow through subscription channels with bundled compliance documentation, while on-premise deployments concentrate in direct enterprise sales with heavy professional services attachment.
- Cloud-Based:Multi-tenant SaaS architectures with pre-validated FDA 21 CFR Part 11 modules reduce implementation timelines from 24 months to under six. Mid-market life sciences firms in the United States concentrate procurement here, prioritizing remote audit accessibility and automatic regulatory update propagation.
- On-Premise:Single-tenant installations with full data sovereignty control serve manufacturers with air-gapped security requirements or 15-plus year ERP depreciation cycles. European medical device producers with EMA inspection histories favor this mode for design history file custody.
- Hybrid:Split architectures keeping critical records on-premise while routing collaborative workflows through cloud interfaces.
- Web-Based:Browser-accessible platforms with lighter infrastructure requirements for smaller quality teams.
- Mobile:Native applications enabling floor-level deviation reporting and real-time CAPA initiation.
On-premise systems dominate installed base. Cloud-based deployment is where expansion concentrates.
Solution Type:
Pricing stratifies sharply across modules based on validation burden and audit linkage, with compliance management commanding premium tiers.
- Compliance Management:Validated workflow engines enforcing FDA 21 CFR Part 11, EU MDR, and ISO 9001 documentation mandates with immutable audit trails. Pharmaceutical manufacturers facing FDA warning letter remediation concentrate demand here, treating these modules as insurance against consent decree exposure.
- Document Control:Revision-locked repositories with electronic signature workflows for standard operating procedures and batch records. Life sciences quality teams in the United States and Germany prioritize these systems for inspection readiness.
- Audit Management:Scheduling and findings-tracking platforms with inspector response templates.
- Risk Management:FMEA and risk register tools linking design controls to post-market surveillance.
- Supplier Quality Management:Multi-enterprise portals for corrective action coordination across tiered supply chains.
Compliance management anchors vendor profitability. Supplier quality management is climbing the fastest as OEMs push digitization downstream.
Application:
Regulatory stringency determines solution complexity, with pharmaceutical and medical device manufacturing requiring the most extensive validation documentation.
- Pharmaceutical Manufacturing:Batch release workflows with statistical process control integration and electronic batch record enforcement. Sterile injectables producers in the United States deploy predictive deviation detection here, pressured by FDA intensifying data integrity inspections.
- Aerospace Manufacturing:AS9100-compliant configuration management with supplier first-article inspection tracking. Tier-one aerostructures suppliers concentrate procurement where OEMs mandate closed-loop corrective action visibility.
- Food Processing:HACCP plan digitization with environmental monitoring integration.
- Automotive Assembly:IATF 16949 documentation with layered process audits and customer-specific requirement matrices.
- Electronics Production:RoHS and REACH compliance tracking with material declaration management.
Pharmaceutical manufacturing commands the highest module pricing. Aerospace manufacturing is gaining share fastest as defense procurement tightens quality traceability.
End User Industry:
Customer sophistication and regulatory exposure create distinct purchasing patterns across verticals.
- Life Sciences:Pharmaceutical, biotech, and medical device manufacturers with GxP validation requirements and FDA/EMA inspection exposure. Quality leaders here demand vendor-supplied algorithm transparency documentation as EMA finalizes AI guidance.
- Transportation Equipment:Automotive and aerospace manufacturers with IATF 16949 and AS9100 certification maintenance needs.
- Consumer Goods:Food and personal care producers with brand protection-driven quality investments.
- High Tech:Semiconductor and electronics manufacturers with complex supply chain traceability requirements.
- Chemical Production:Process manufacturers with REACH compliance and batch consistency mandates.
Life Sciences anchors vendor R&D investment. Transportation equipment is where pricing pressure concentrates as OEMs consolidate supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market pharmaceutical manufacturers in the United States concentrate procurement of cloud-based validation platforms, while export-oriented API producers in India and sterile injectables specialists in Germany drive regional adoption patterns.
United States
FDA 21 CFR Part 11 enforcement is accelerating replacement of paper-based quality systems among sterile injectables manufacturers. The agency's intensifying data integrity inspections force firms toward subscription-based platforms with pre-validated electronic batch record modules. Greater Boston and the Research Triangle host the densest clusters of cloud-native quality software deployments.
Germany
EMA inspection exposure and EU MDR technical file obligations compel medical device manufacturers toward digitized design history records. The country's automotive tier-one suppliers simultaneously face IATF 16949 corrective action mandates from OEMs. Baden-Württemberg and Bavaria concentrate demand for hybrid deployment models balancing data sovereignty with collaborative supplier portals.
India
CDSCO's alignment with ICH Q10 guidelines creates regulatory tailwinds for export-oriented API producers seeking FDA inspection readiness. The country's contract manufacturing organizations prioritize deployment speed over customization depth. Maharashtra and Gujarat pharmaceutical corridors anchor quality digitization investments among mid-market generic manufacturers.
Japan
PMDA's GxP inspection protocols and aging workforce demographics push pharmaceutical manufacturers toward automated deviation detection workflows. The country's precision equipment suppliers extend quality platform requirements downstream to component vendors. The Kansai region around Osaka hosts concentrated adoption of AI-enabled statistical process control among sterile formulation specialists.
Switzerland
Swissmedic's rigorous batch release documentation requirements sustain premium pricing for validation-heavy compliance modules. The country's biologics manufacturers demand vendor-supplied algorithm transparency as they pilot machine learning for predictive quality decisions. Basel's pharmaceutical cluster anchors enterprise platform deployments with extensive professional services attachment.
Quality Management Software Market Key Industry Players
Player mix skews toward diversified enterprise software conglomerates with adjacent ERP or PLM footprints, creating tiered competition against specialized quality suite vendors. The structure concentrates R&D investment among platforms with pre-built FDA validation modules, while mid-market specialists compete on deployment velocity. Two strategic archetypes dominate: ERP-anchored conglomerates leveraging cross-sell integration, and cloud-native specialists competing on regulatory update speed. Consolidation through strategic acquisitions and vertical integration into validation services represent the dominant competitive moves.
Within the ERP-anchored tier, SAP and Oracle exemplify platforms leveraging existing manufacturing customer relationships to cross-sell quality modules. ETQ and Veeva Systems occupy positions as cloud-native specialists competing on deployment speed and regulatory update automation. Siemens represents the industrial software conglomerate archetype, bridging manufacturing execution and quality workflows through its digital thread strategy. Each anchors distinct procurement criteria: integration breadth versus validation agility versus shop-floor connectivity.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| Microsoft |
| IBM |
| Siemens |
| MasterControl |
| ETQ |
| Veeva Systems |
| Dassault Systèmes |
| Others |
Cost & Logistics Intelligence
FDA 21 CFR Part 11 validation requirements simultaneously gate vendor qualification and stratify price tiers across the quality management software landscape, compressing margins for non-compliant platforms while elevating subscription premiums for pre-validated configurations. Pharmaceutical manufacturers absorb these certification costs through bundled annual contracts that embed compliance documentation, training modules, and regulatory update services.
Pricing Analysis
Next-generation AI-enabled quality platforms command 40-60% subscription premiums over legacy rules-based systems, while prior-generation on-premise installations face accelerating price erosion as cloud-native alternatives displace capital-intensive deployments. Pricing stratifies across premium, standard, and economy tiers keyed to validation depth, with FDA 21 CFR Part 11-ready modules anchoring the premium band and lighter document-control suites populating standard tiers. Cost compression in the mid-market intensifies as SAP and Oracle leverage ERP cross-sell to discount quality modules. Contract research organizations exhibit highest price sensitivity due to thin margins, while sterile injectables specialists prioritize validation assurance over cost.
Supply Chain Analysis
Implementation lead times stretch 18-24 months for validated environments, compressing effective vendor capacity and creating backlog premiums for qualified deployment teams. Software development concentrates in the United States, Ireland, and India, with regulatory consulting services anchored in Germany and Switzerland. Platform architecture draws from cloud infrastructure providers, specialized CSV engineering labor pools, and compliance documentation libraries. Single-source vulnerability permeates the computer system validation talent layer, where qualified IQ/OQ/PQ protocol authors remain scarce. Distribution runs through direct enterprise sales with heavy professional services attachment for on-premise deployments, while cloud-native platforms flow through subscription channels with automated provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud migration and AI validation are reshaping competitive positioning in quality management software, with EMA's forthcoming algorithmic guidance creating a regulatory inflection that separates pre-validated vendors from laggards.
For Market Incumbents: Consolidate around pre-validated AI modules before EMA guidance finalizes, acquiring specialized CSV consultancies to anchor implementation capacity. SAP and Oracle should deepen integration between ERP backbones and quality workflows to defend against cloud-native disintermediation. ETQ and Veeva must accelerate regulatory update automation to maintain deployment velocity advantages. For New Entrants and Emerging Players: Mid-market pharmaceutical manufacturers in India represent the most penetrable segment, as CDSCO's ICH Q10 alignment creates inspection-readiness urgency without entrenched vendor relationships. Supplier quality management networks connecting OEMs with tiered vendors offer white-space beyond saturated compliance management modules. A compliance-as-a-service go-to-market model, bundling validation documentation with subscription pricing, bypasses capital-constrained procurement cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial software conglomerates seeking to divest non-core quality modules that lack AI roadmaps. Long-term viability hinges on algorithmic explainability capabilities as regulatory scrutiny of machine learning in GxP environments intensifies. Watch FDA warning letter trends for deviation detection automation as an inflection indicator—accelerating citations signal replacement demand for predictive quality platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | CSV consultancies with FDA inspection relationships accelerate deployment capacity and reduce talent scarcity bottlenecks. |
| Platform Integration | Native MES and LIMS connectivity eliminates custom middleware development that prolongs implementation timelines. |
| Regulatory Approval Pathway | Pre-validated FDA 21 CFR Part 11 modules reduce customer validation burden from 24 months to under six. |
| Geographic Expansion | India's pharmaceutical corridors offer untapped mid-market demand among export-oriented API producers. |
| Product Launch | AI-enabled predictive deviation detection captures premium positioning ahead of EMA algorithmic guidance finalization. |
Research Approach
Initial hypotheses were tested against primary input from quality assurance directors, CSV engineers, regulatory affairs leads, and IT procurement officers at pharmaceutical and medical device manufacturers, then refined through secondary validation against FDA 483 observations, EMA inspection reports, ISO certification databases, and vendor SEC filings. Bottom-up sizing of module-level subscriptions combined with top-down cross-checks against total addressable manufacturer counts across regulated industries. Primary interviews concentrated in the United States, Germany, and India to capture divergent regulatory enforcement patterns.
Variance decomposition across deployment modes, solution architectures, and end-user industries structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate assumptions calibrated to regulatory mandate timelines and cloud migration velocity. Modeled dimensions included deployment model, organization size by revenue, vertical regulatory stringency, and integration complexity with adjacent manufacturing systems. Forecast inputs incorporated FDA inspection intensity trends, EMA guidance publication schedules, and ICH Q10 adoption trajectories in export markets.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EU MDR, and ICH Q10 frameworks; material policy shifts would require re-modeling validation burden and implementation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America IT Services Market
Software & Services
Pure Play Software Testing Market
Software & Services
Towing Software Market
Software & Services
SMS Marketing Software Market
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Email Management Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Lead Management Software Market
Software & Services
Home Design Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Global Proposal Management Software Market