
 Tech Support Services Market | 2026-2036
Tech Support Services Market Size, Share, and Industry Trends Forecast 2026-2036
Tech Support Services Market Analytics
Aftermarket service revenue is tilting from break-fix engagements toward subscription-based managed services. IBM leverages its hybrid cloud infrastructure expertise to capture recurring support contracts across enterprise accounts. Accenture anchors its position through AI-driven diagnostic platforms that reduce mean-time-to-resolution for client IT environments.
Tech support services encompass the remote and on-site assistance, system monitoring, and incident resolution activities that maintain operational continuity of hardware, software, and network infrastructure, typically delivered through tiered escalation protocols with defined service-level agreements specifying response times from fifteen minutes to four hours depending on severity classification. Their primary commercial purpose is to minimize downtime costs and extend technology asset lifecycles for organizations lacking internal technical depth. Managed services commands the largest margin pool through multi-year contracts with guaranteed uptime commitments, while AI-driven solutions within the technology dimension represents the fastest-expanding segment as automated root-cause analysis displaces Level-1 human triage. Cloud-based deployment continues to outpace on-premise alternatives as distributed workforces require location-agnostic access to technical assistance.
FDA oversight of software-as-a-medical-device and HIPAA security requirements shape how healthcare tech support providers structure access controls and audit trails. The EU AI Act imposes conformity obligations on automated decision-support systems that European tech support vendors integrate into client workflows. Stakeholders must monitor whether emerging algorithmic accountability rules will require human-in-the-loop mandates that alter the cost structure of AI-augmented service delivery.
Market Dynamics
Enterprise migration toward AI-augmented service desks is compressing traditional tiered support hierarchies while HIPAA and EU AI Act compliance mandates force architectural redesigns of automated diagnostic platforms.
Growth Catalysts
- Telemedicine infrastructure expansion:Healthcare systems in the United States require continuous EHR system maintenance and remote patient monitoring platform support, creating durable demand for specialized technical assistance.
- EU Digital Operational Resilience Act:Financial institutions across Germany, France, and Italy must strengthen IT service continuity frameworks, mandating external expertise for stress testing and incident response protocols.
- Edge computing deployment:Manufacturing facilities and logistics hubs are distributing compute infrastructure to plant floors, necessitating localized on-site support capabilities that managed service providers are racing to build.
Market Restraints
- Certified cybersecurity talent scarcity:The shallow pool of professionals holding CISSP and GIAC credentials in secondary US metropolitan markets inflates labor costs for security-focused support contracts.
- Single-source cloud dependency:Concentration of enterprise workloads on hyperscaler platforms creates cascading failure risks when regional outages disable multi-tenant diagnostic tools.
- Generative AI substitution threat:Large language models capable of code generation and automated troubleshooting are encroaching on Level-1 and Level-2 human support functions.
Strategic Opportunities
- Indian SME digitization:Small and medium enterprises across Maharashtra and Karnataka remain underserved by premium support tiers, presenting volume opportunities for localized managed service offerings.
- Convergence of AIOps and observability:Integration of machine learning-driven anomaly detection with full-stack monitoring platforms enables predictive intervention before system degradation impacts operations.
- Brazilian data localization mandates:ANVISA and central bank regulations requiring domestic data residency are compelling multinational healthcare and financial firms to establish in-country support operations.
Industry Challenges
- Multi-cloud architecture complexity:Enterprises operating across AWS, Azure, and Google Cloud environments demand support engineers fluent in divergent native tooling and interoperability troubleshooting.
- ISO 27001 certification timelines:Extended audit cycles and documentation requirements delay market entry for regional providers seeking to serve regulated industries.
- Technical debt integration friction:Decades-old COBOL and mainframe systems in banking and insurance verticals resist seamless incorporation into modern API-driven support workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tech Support Services Market |
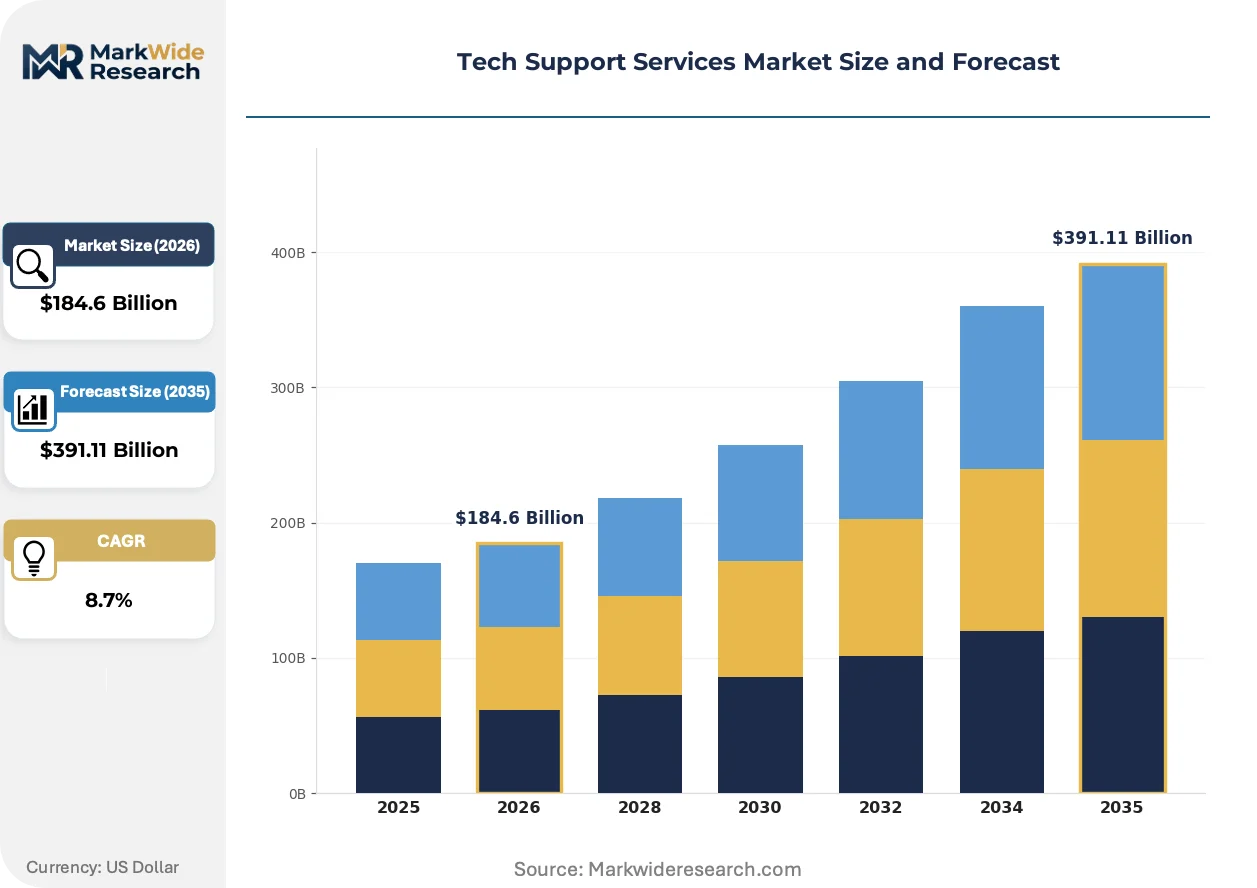
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $391.11 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Remote Support, On-Site Support, Managed Services, Help Desk Customer Type: SMEs, Enterprises, Government Agencies, Non-Profits Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Technology: AI-Driven Solutions, Chatbots, Automated Ticketing, Remote Desktop Tools |
| Companies Covered | Tata Consultancy Services (TCS), DXC Technology, Accenture, IBM, NTT Data, Infosys, Capgemini, Genpact, Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tech Support Services Market Evolving Landscape
Automated root-cause analysis and predictive maintenance algorithms are redistributing value capture from human labor hours to software-enabled uptime guarantees. Vendors are racing to embed these capabilities into multi-year contracts.
Generative AI copilots are migrating from experimental pilots to production incident management workflows. Large enterprises in financial services and healthcare are deploying these tools for automated log analysis and knowledge base synthesis. The technology is migrating from novelty demonstrations to contractual SLA commitments, compressing pricing power for purely human-delivered Level-1 triage.
The EU AI Act's conformity assessment requirements for high-risk automated decision systems are forcing European tech support vendors to reengineer diagnostic algorithms. Providers must now document training data provenance and implement human oversight mechanisms for AI-generated remediation recommendations. Medical device support operations in Germany and France face the steepest compliance curves as software-as-a-medical-device classifications expand.
Outcome-based contracting is displacing per-ticket pricing in enterprise procurement. Buyers in the United States and United Kingdom are demanding guaranteed mean-time-to-resolution metrics with financial penalties for misses. This shift concentrates vendor selection on predictive platform maturity rather than headcount scale, favoring providers with mature telemetry infrastructure over regional staffing networks.
Tech Support Services Market Segmentation
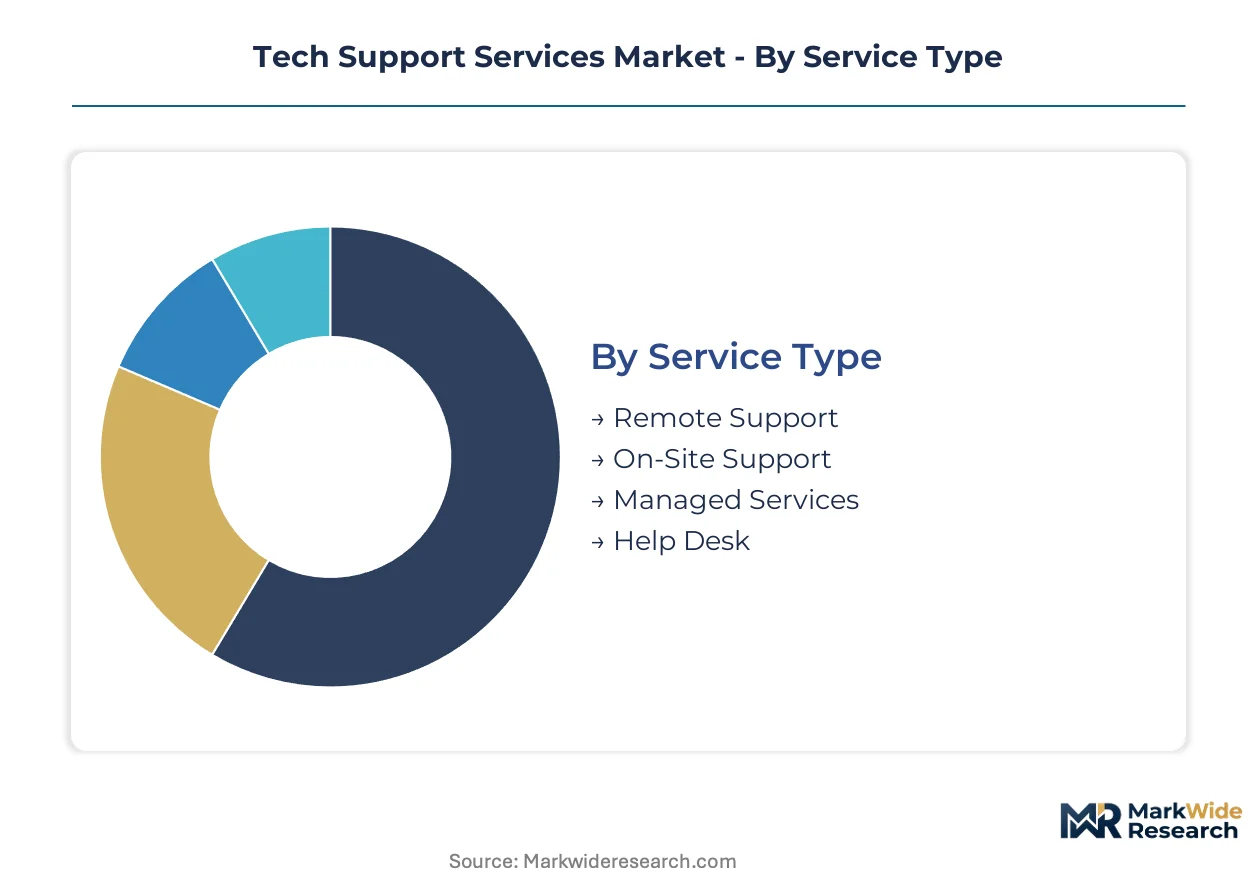
Segmentation in tech support services reveals how procurement patterns diverge across contract structures and infrastructure choices. Service buyers optimize across cost predictability, response velocity, and compliance requirements.
Service Type:
Contract renewal cycles vary dramatically, with break-fix arrangements turning over quarterly while managed services lock in multi-year commitments.
- Managed Services:Multi-year contracts bundle proactive monitoring, patch management, and guaranteed uptime SLAs. Financial institutions in Germany and France are consolidating vendor relationships here to satisfy EU Digital Operational Resilience Act continuity mandates.
- Remote Support:Tiered escalation protocols deliver incident resolution through VPN-based diagnostic access and screen-sharing tools. Distributed workforces across US technology clusters demand this format for location-agnostic assistance.
- On-Site Support:Field engineer dispatch for hardware replacement and physical infrastructure troubleshooting.
- Help Desk:First-contact triage through voice, chat, and email channels with defined severity classifications.
Managed Services anchors the volume base while AI-augmented Remote Support gains share at the steepest rate.
Customer Type:
Procurement sophistication stratifies sharply, with enterprise buyers demanding outcome-based contracts and smaller entities prioritizing per-incident affordability.
- Enterprises:Complex multi-site environments require dedicated account teams and custom SLA architectures. US healthcare systems expanding telemedicine infrastructure are driving premium contract values here.
- SMEs:Price-sensitive buyers favor standardized service catalogs with limited customization. Manufacturing clusters in Maharashtra and Karnataka present volume opportunities as digitization accelerates.
- Government Agencies:Federated procurement frameworks with stringent security clearance requirements.
- Non-Profits:Grant-dependent budgets favor discounted or donated support tiers.
Enterprises dominate current revenue while SME adoption climbs most rapidly.
Deployment:
Infrastructure location decisions trade latency optimization against data sovereignty constraints.
- Cloud-Based:Browser-delivered support portals and API-integrated diagnostic tools eliminate on-premise agent installation. Brazilian healthcare multinationals are migrating here to satisfy ANVISA data localization mandates through domestic cloud regions.
- Hybrid:Sensitive workloads remain on-premise while routine diagnostics leverage cloud elasticity. European financial institutions favor this architecture to reconcile GDPR residency requirements with scalability needs.
- On-Premise:Air-gapped installations for classified government and defense environments.
- Mobile:Smartphone-native support applications for field service technicians.
Cloud-Based deployment commands the largest install base while Hybrid configurations expand quickest.
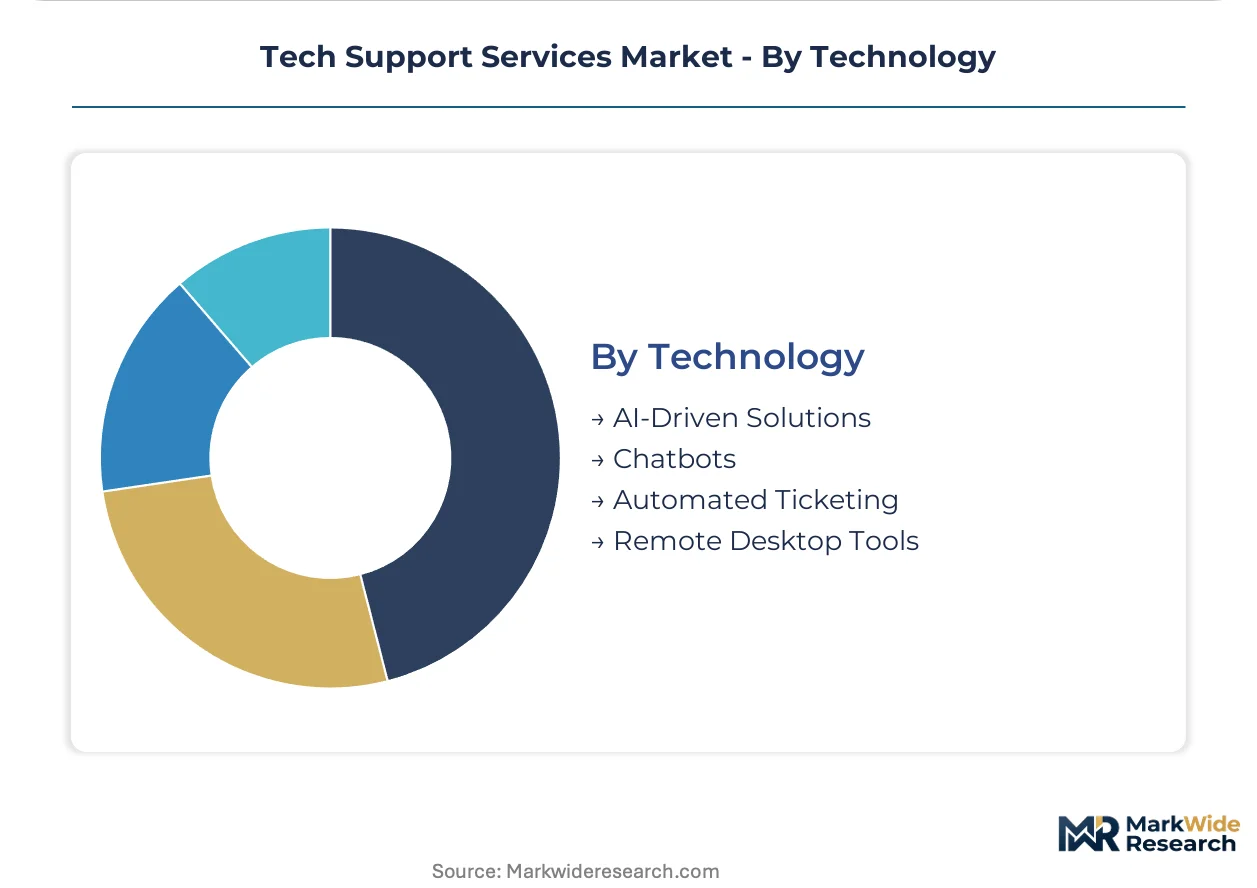
Technology:
Automation maturity determines whether vendors capture value through software margins or labor arbitrage.
- AI-Driven Solutions:Machine learning models perform automated root-cause analysis and predictive failure detection. German medical device support operations are reengineering these algorithms to satisfy EU AI Act conformity assessments for high-risk automated decision systems.
- Automated Ticketing:NLP-based classification routes incidents without human triage. US financial services firms are embedding these tools into contractual SLA commitments.
- Chatbots:Conversational interfaces handling password resets and knowledge base queries.
- Remote Desktop Tools:Screen control and file transfer capabilities for hands-on remediation.
AI-Driven Solutions anchor vendor R&D investment while Automated Ticketing achieves production scale fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Indian SMEs bargain aggressively for per-incident support, while German financial institutions pay premiums for guaranteed uptime SLAs under regulatory pressure.
United States
Enterprise digital transformation and legacy system modernization drive substantial procurement of managed support contracts. HIPAA security requirements shape how healthcare tech support providers structure access controls and audit trails for electronic health record systems. Technology clusters in California and Texas demand location-agnostic remote assistance for distributed workforces.
Germany
Financial institutions must strengthen IT service continuity frameworks to satisfy EU Digital Operational Resilience Act mandates. The EU AI Act imposes conformity obligations on automated decision-support systems that German tech support vendors integrate into client workflows. Medical device support operations in Bavaria face steep compliance curves as software-as-a-medical-device classifications expand.
India
Small and medium enterprises across Maharashtra and Karnataka remain underserved by premium support tiers, presenting volume opportunities for localized managed service offerings. The country's national IT regulator shapes data localization expectations for cloud-based support portals. Manufacturing digitization in Gujarat accelerates demand for predictive maintenance capabilities.
Brazil
ANVISA and central bank regulations requiring domestic data residency compel multinational healthcare and financial firms to establish in-country support operations. Brazilian data localization mandates create barriers to centralized regional delivery models. São Paulo anchors the largest concentration of certified support engineers serving Latin American enterprise accounts.
United Kingdom
Buyers in London and the Southeast demand guaranteed mean-time-to-resolution metrics with financial penalties for misses. GDPR residency requirements shape hybrid deployment architectures for sensitive workloads. Outcome-based contracting concentrates vendor selection on predictive platform maturity rather than headcount scale.
Tech Support Services Market Competitive Landscape
Global systems integrators and specialized managed service providers split the market along contract complexity lines. Consolidation favors vendors with multi-cloud diagnostic platforms and established compliance certifications. Three archetypes dominate: hyperscaler-aligned consultancies, vertical specialists with healthcare or financial services depth, and automation-first platforms betting on AI-augmented resolution. Competitive moves center on predictive capability acquisitions and geographic footprint expansion into data-mandated jurisdictions.
Within the hyperscaler-aligned tier, IBM leverages hybrid cloud infrastructure expertise while Accenture anchors its position through AI-driven diagnostic platforms. Indian-origin systems integrators Tata Consultancy Services, Infosys, and Wipro occupy positions scaling standardized delivery models across North American and European enterprise accounts.
| Leading Market Players |
|---|
| Tata Consultancy Services (TCS) |
| DXC Technology |
| Accenture |
| IBM |
| NTT Data |
| Infosys |
| Capgemini |
| Genpact |
| Wipro |
| Others |
Value Network & Pricing Analysis
Single-source cloud dependency concentrates pricing power among hyperscaler-aligned vendors while compressing margins for regional providers lacking multi-tenant diagnostic infrastructure. This structural vulnerability determines both the spread between premium managed services and commoditized break-fix tiers and the geographic distribution of certified engineering talent pools.
Pricing Analysis
Subscription-based managed services contracts anchor lifetime value capture through recurring revenue streams with guaranteed uptime SLAs. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification depth—ISO 27001 and HIPAA compliance tiers command substantial premiums over uncertified alternatives. Cost compression in Level-1 triage intensifies as generative AI copilots displace human labor for routine incident classification. Indian SMEs exhibit the highest price sensitivity, while German financial institutions under EU Digital Operational Resilience Act mandates show minimal elasticity for guaranteed continuity pricing.
Supply Chain Analysis
Extended payment terms from enterprise buyers strain working capital for regional managed service providers competing against global systems integrators. Engineering talent concentrates in India, the Philippines, and Poland as delivery hubs for remote support operations. Cloud compute capacity, cybersecurity tooling licenses, and CISSP-certified labor constitute critical input dependencies. Single-source vulnerability runs through hyperscaler platform concentration—AWS, Azure, or Google Cloud regional outages cascade through multi-tenant diagnostic tools. Distribution runs through direct enterprise sales teams, channel partners, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise IT budget cyclicality drives procurement postponement during macroeconomic contraction phases, creating recovery windows when digital transformation programs resume. The current cycle favors vendors with predictive platform maturity over headcount-dependent delivery models.
For Market Incumbents: Harden multi-cloud diagnostic capabilities across AWS, Azure, and Google Cloud native tooling to defend against specialized automation-first platforms encroaching on enterprise accounts. Invest in EU AI Act conformity documentation for German and French medical device support operations before human-in-the-loop mandates alter cost structures. Vertical integration into proprietary AIOps telemetry infrastructure reduces dependency on third-party observability vendors. For New Entrants and Emerging Players: Mid-market manufacturing clusters in Maharashtra and Karnataka represent the most penetrable entry point, as these SMEs remain underserved by premium support tiers from global incumbents. Brazilian data localization mandates for ANVISA-regulated healthcare data create jurisdictional white space requiring in-country engineering presence. A channel partnership route through hyperscaler marketplaces accelerates customer acquisition without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: EU AI Act conformity deadlines reshape the acquisition landscape toward vendors with documented training data provenance and human oversight mechanisms already engineered. The five-to-ten-year viability window favors automation-first platforms with predictive intervention capabilities over staffing-heavy regional providers. Target acquisition archetype: AIOps-observability convergence specialists with production-scale anomaly detection deployed in US financial services or German healthcare accounts. The signal to watch is contractual SLA migration from per-ticket pricing to guaranteed mean-time-to-resolution metrics with financial penalty clauses.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Diagnostic Platform Development | Automated root-cause analysis displaces Level-1 human triage, compressing resolution timelines for US healthcare EHR systems. |
| Multi-Cloud Certification Investment | Fluency across AWS, Azure, and Google Cloud tooling addresses enterprise demand for interoperability troubleshooting expertise. |
| EU AI Act Conformity Engineering | Documented training data provenance satisfies German medical device support requirements for high-risk automated decision systems. |
| Geographic Expansion into Data-Mandated Jurisdictions | Brazilian in-country operations capture ANVISA-regulated healthcare multinationals requiring domestic data residency compliance. |
| Predictive Maintenance Algorithm Integration | Machine learning-driven anomaly detection enables outcome-based contracting with guaranteed uptime commitments in financial services. |
Research Methodology
Desk research of regulatory filings, hyperscaler service documentation, and healthcare IT procurement databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Primary fieldwork captured contractual SLA architectures, pricing model migration patterns, and AI adoption timelines across US, German, and Indian enterprise accounts. Secondary validation drew from SEC filings, hyperscaler capex disclosures, and EU regulatory impact assessments. Bottom-up service provider revenue estimates triangulated against top-down market sizing from digital transformation spend analyses.
Forecast assumptions held cloud migration velocity, regulatory enforcement timelines, and generative AI capability maturation as variable inputs while fixing baseline IT support spend ratios to enterprise revenue. Segmentation dimensions modeled encompass service type, deployment architecture, customer scale tier, and vertical regulatory intensity across the projection horizon. CAGRs derived from weighted scenario analysis of AI substitution rates and compliance-driven contract consolidation. Industry-specific inputs included HIPAA audit frequency patterns, EU Digital Operational Resilience Act implementation phases, and Brazilian data localization enforcement trajectories.
Practitioners should monitor hyperscaler outage frequency, EU AI Act conformity assessment rulings, and generative AI troubleshooting accuracy benchmarks for early signals of model revision needs. Forecasts reflect documented assumptions about automation adoption curves and regulatory implementation schedules. Macroeconomic deviation affecting enterprise IT budgets, regulatory acceleration of human-in-the-loop mandates, or breakthrough advances in autonomous code generation would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Self-Storage Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Salon Booking Software Market
Software & Services
Global Polling Software Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
IT Services Market
Software & Services
LTFS Copy Software Market
Software & Services
Global Brain Training Software Market
Software & Services
Generative Design Software Market
Software & Services
Global Software Quality Assurance Market
Software & Services
Backend-As-A-Service Market
Software & Services
Europe Yacht Management Software Market
Software & Services
Global Journal App Market
Software & Services
Intellectual Property Software Market
Software & Services
Global Data Integration and Integrity Software Market