
 Global Translation Software Market | 2026-2036
Global Translation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Translation Software Market Foresight
ISO 17100 certification for translation services is collapsing the barrier between professional linguists and automated platforms, forcing vendors to demonstrate human-in-the-loop quality assurance. Google LLC leverages its search-index data corpus to dominate statistical machine translation training sets. DeepL anchors European market trust through neural architecture optimized for Indo-European language pairs. Microsoft Corporation extends enterprise reach by embedding translation APIs directly into Office 365 and Teams collaboration stacks.
Translation software encompasses computational systems that convert text or speech between natural languages through statistical, neural, or hybrid processing engines, typically operating with latency thresholds under 500 milliseconds for real-time applications and supporting 50 to 100+ language pairs in production deployments. Cloud-based deployment leads solution type adoption as enterprises abandon on-premises infrastructure maintenance. Machine Translation captures the fastest expansion within solution types, driven by API-first consumption models. Website Localization commands concentrated margin pools among application segments, reflecting recurring content update cycles and SEO-integrated workflows.
FDA guidance on software-as-a-medical-device intersects with HIPAA requirements when translation tools process clinical trial documentation or patient-facing health portals in the United States, while the EU AI Act mandates risk classification and human oversight for high-stakes automated translation in legal and financial services. China's SAMR enforces algorithmic transparency and data localization for cloud translation services operating within its jurisdiction. Stakeholders must monitor divergence between regional AI governance frameworks when architecting multi-tenant translation infrastructure.
Market Dynamics
Neural machine translation architectures are compressing latency thresholds below 200 milliseconds for real-time video conferencing, forcing legacy statistical engines into obsolescence and redrawing competitive moats around training-data scale.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision systems in legal and financial services now require human oversight, creating certified workflow demand that elevates premium translation vendors above commodity API providers.
- Automotive technical documentation:German industrial exporters require ISO 17100-certified translation pipelines for safety-critical component manuals, locking in recurring revenue streams.
- Real-time collaboration APIs:Enterprise IT departments embed machine translation directly into unified communications stacks, displacing post-hoc document translation with synchronous multilingual interaction.
Market Restraints
- Compute cost volatility:GPU cluster pricing for large language model inference fluctuates with semiconductor foundry capacity, squeezing margin on high-volume API tiers.
- Training data concentration:High-quality parallel corpora for low-resource languages cluster in academic repositories and government archives, creating supply bottlenecks for African and Southeast Asian language pairs.
- Hallucination risk in clinical contexts:FDA scrutiny of software-as-a-medical-device raises liability barriers for translation tools processing patient-facing health portals.
Strategic Opportunities
- India's pharmaceutical export documentation:CDSCO regulatory filing requirements for generic drug approvals create demand for certified translation of chemistry-manufacturing-controls data.
- Speech-to-speech convergence:Neural audio codecs merging with text-based translation engines enable offline mobile interpretation for field service technicians in mining and energy infrastructure.
- China's algorithmic transparency rules:SAMR data-localization mandates force global vendors to establish domestic cloud infrastructure, opening partnership slots for local operators.
Industry Challenges
- Computational linguist scarcity:Rare language expertise in Uralic and Dravidian families commands premium compensation, constraining expansion into emerging markets.
- Legacy TMS integration friction:Decades-old translation management systems in publishing and legal sectors resist API-native replacement, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Translation Software Market |
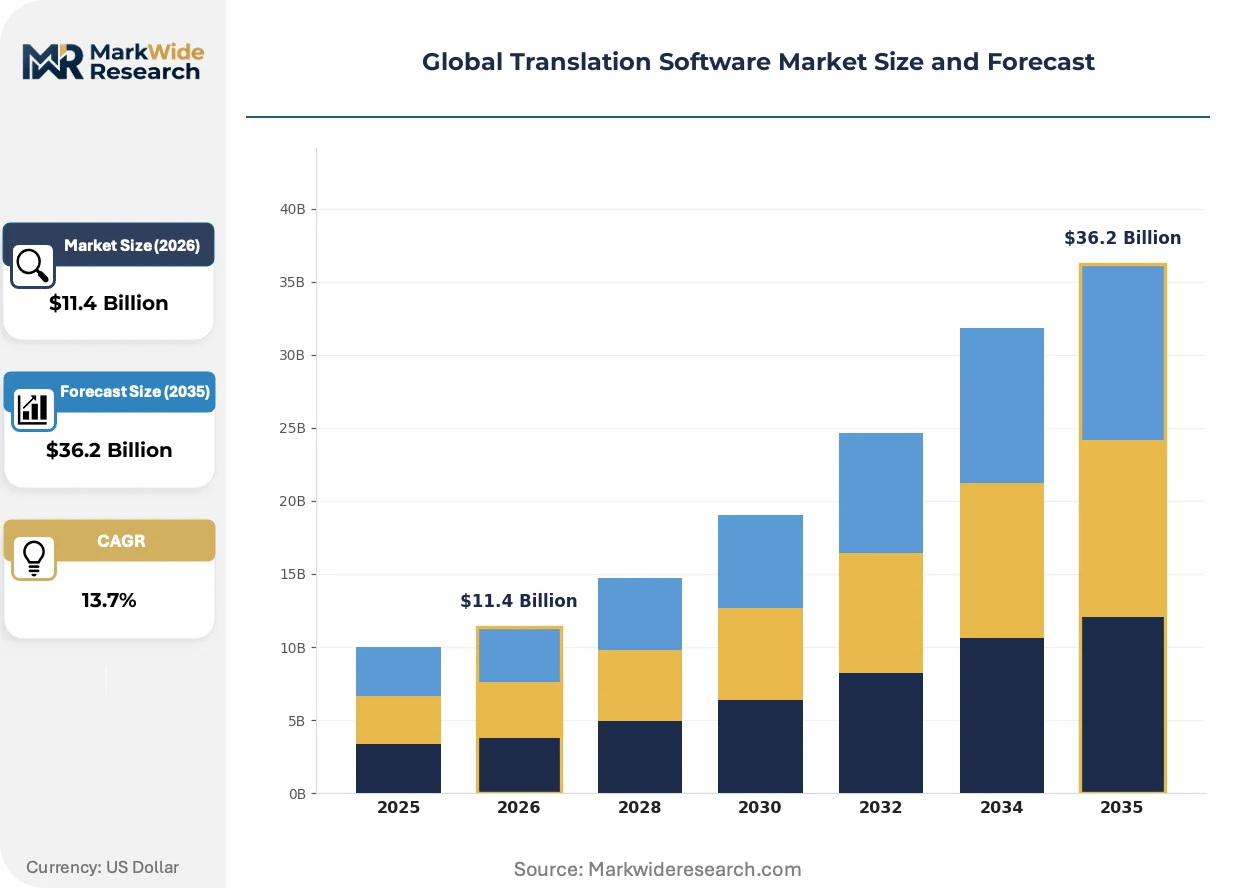
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $36.2 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, SaaS Solution Type: Machine Translation, Computer-Assisted Translation, Translation Management System, Terminology Management Application: Website Localization, Document Translation, Multimedia Translation, Software Localization End User Industry: Information Technology, Legal Services, Finance & Banking, E-learning |
| Companies Covered | Google LLC, Microsoft Corporation, IBM Corp, Amazon Web Services, DeepL, SYSTRAN SA, RWS Group, Lionbridge Technologies, TransPerfect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Translation Software Market Shifts & Advancements
Foundation-model architectures are fragmenting the translation stack into modular inference layers, separating encoding, alignment, and decoding into swappable components that vendors recombine for specialized domains.
Mixture-of-experts routing is decomposing monolithic neural translation models into domain-specialized subnetworks. Automotive suppliers in Stuttgart and Wolfsburg deploy fine-tuned expert clusters for technical terminology. This decomposition collapses the cost of maintaining separate engines for legal, medical, and engineering verticals.
The EU AI Act's risk-classification framework now mandates conformity assessments for high-stakes automated translation in judicial and financial services. Vendors must document training-data provenance and human-in-the-loop protocols. German legal-tech providers are restructuring product tiers to isolate certified workflows from general-purpose APIs.
Buyers now unbundle translation quality assurance from core engine licensing, contracting specialized linguist marketplaces for post-editing while sourcing base inference from commodity APIs. This bifurcation concentrates margin in quality-certification layers rather than raw token throughput, with pharmaceutical and medical-device manufacturers in Basel and Cambridge driving the shift.
Global Translation Software Market Segmentation
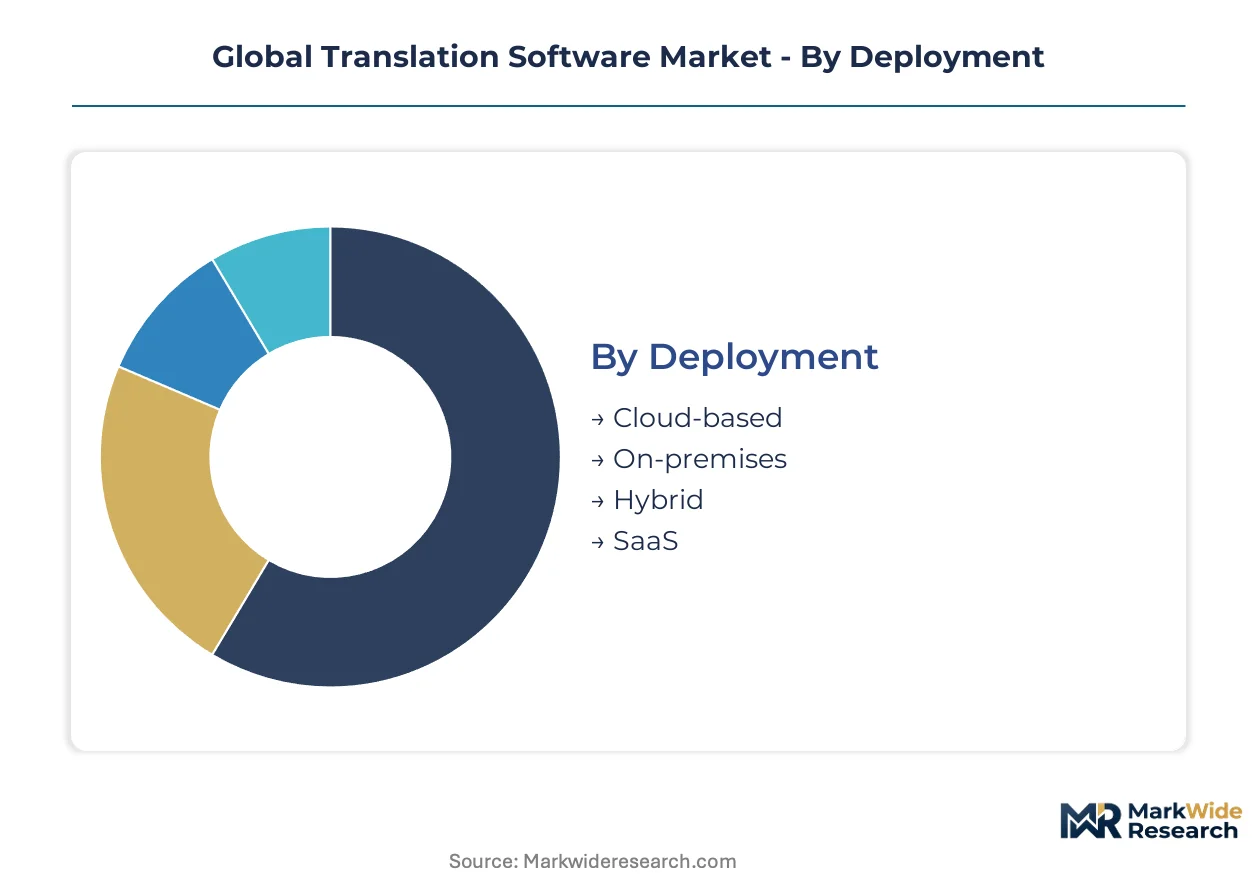
Translation software procurement patterns diverge sharply across deployment modes and solution architectures. Enterprise buyers route high-volume workflows through cloud APIs while reserving on-premises infrastructure for regulated data. Channel strategy must align with these structural splits to capture margin across the stack.
Deployment:
Cloud-based deployment flows through hyperscaler marketplaces and direct API contracts. On-premises and hybrid solutions move through systems integrators and value-added resellers with compliance expertise.
- Cloud-based:Multi-tenant infrastructure with sub-500 millisecond latency SLAs dominates real-time collaboration use cases. German automotive exporters and US healthcare networks drive concentrated demand for elastic scaling during quarterly reporting cycles.
- On-premises:Air-gapped installations serve defense contractors and intelligence agencies with classified-circuit requirements. Air-gapped deployments in Basel pharmaceutical clusters satisfy Swissmedic data-residency mandates for clinical trial documentation.
- Hybrid:Sensitive pre-processing occurs locally before cloud inference for high-volume batch jobs. Hybrid architectures appeal to Japanese financial institutions balancing METI guidance with cost optimization.
- SaaS:Browser-native interfaces with per-seat licensing accelerate adoption among mid-market legal practices. SaaS tiers capture solo practitioners and boutique firms in Paris and Frankfurt seeking ISO 17100-aligned workflows without capital expenditure.
By volume, Cloud-based leads. By growth pace, Hybrid is climbing the fastest as regulated industries seek architectural compromise.
Solution Type:
Cost tiering separates commodity API inference from certified quality-assurance layers. Machine Translation commands the lowest per-token pricing while Translation Management Systems capture recurring platform fees.
- Machine Translation:Neural engines process 100+ language pairs through transformer architectures with sub-200 millisecond latency. API-first consumption models displace legacy statistical engines in Stuttgart automotive technical documentation pipelines.
- Computer-Assisted Translation:Human-in-the-loop interfaces integrate translation memory and terminology databases for post-editing workflows. Basel medical-device manufacturers contract specialized linguist marketplaces atop commodity inference engines.
- Translation Management System:Workflow orchestration platforms coordinate distributed linguist teams with version control and quality metrics. TMS deployments extend sales cycles in publishing and legal sectors with decades-old legacy infrastructure.
- Terminology Management:Controlled vocabulary systems enforce brand consistency and regulatory compliance across multilingual content repositories. Terminology databases anchor certified workflows for EU AI Act high-risk translation in judicial and financial services.
By volume, Machine Translation leads. By margin concentration, Computer-Assisted Translation is gaining share fastest as quality certification unbundles from core engine licensing.
Application:
Application segmentation tracks content lifecycle economics. Website Localization generates recurring revenue through SEO-integrated update cycles while Document Translation remains project-based and price-sensitive.
- Website Localization:Continuous deployment pipelines automate extraction, translation, and reintegration of dynamic web content. E-commerce platforms in Mumbai and São Paulo drive demand for real-time multilingual product catalogs.
- Document Translation:Batch processing of contracts, patents, and regulatory filings with certified output formats. CDSCO filing requirements for Indian pharmaceutical exports create specialized demand for chemistry-manufacturing-controls documentation.
- Multimedia Translation:Subtitle synchronization, dubbing, and audio description for streaming and broadcast distribution. Neural audio codecs merging with text engines enable offline mobile interpretation for mining field technicians in Western Australia.
- Software Localization:Resource file translation and UI adaptation for application internationalization. DevOps-integrated localization accelerates release cycles for SaaS vendors targeting European multilingual markets.
By volume, Document Translation leads. By recurring revenue potential, Website Localization shows the steepest expansion trajectory.
End User Industry:
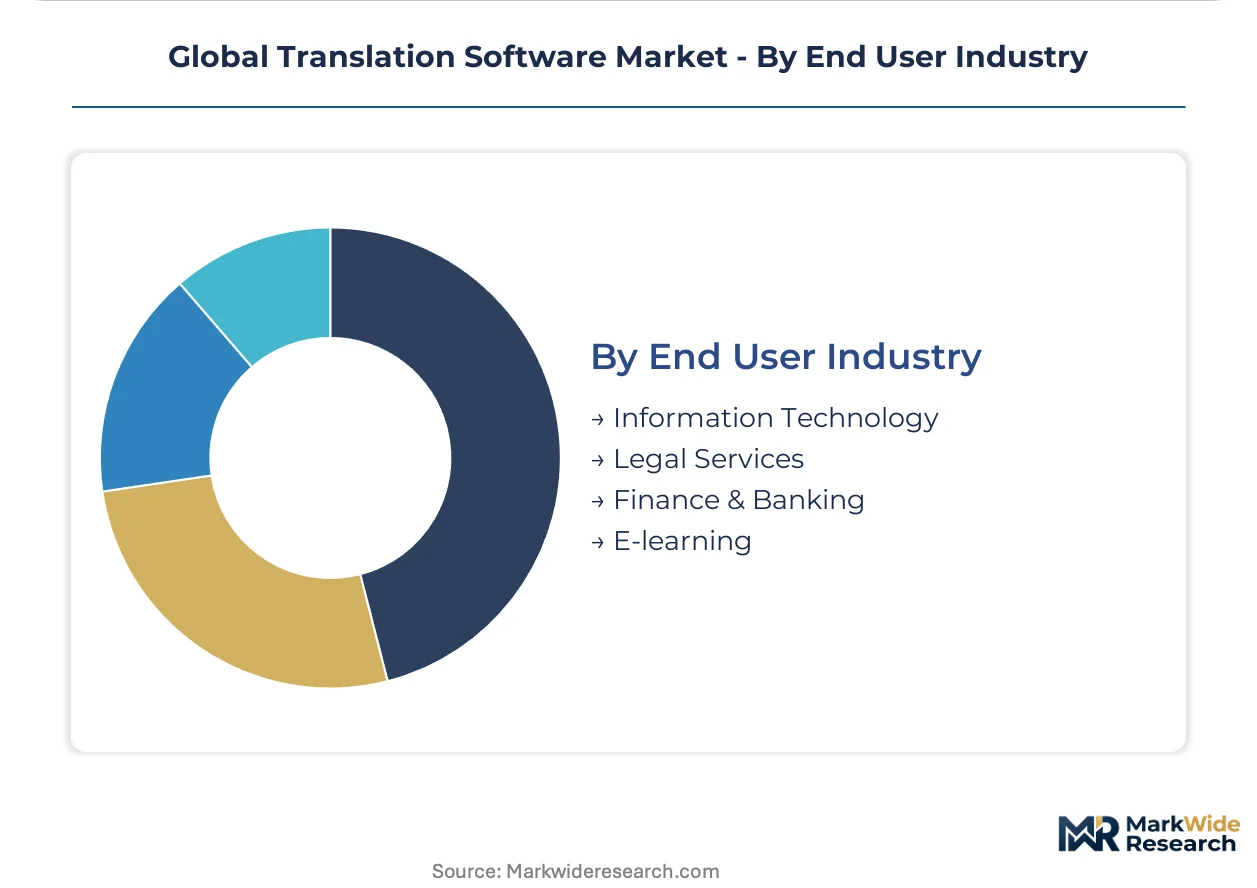
Customer type determines procurement authority and compliance burden. Finance & Banking demands audit trails and human oversight while E-learning prioritizes scale and cost efficiency.
- Information Technology:Native integration of translation APIs into collaboration stacks and developer tools. Microsoft embeds inference directly into Office 365 and Teams, displacing third-party procurement for enterprise IT departments.
- Legal Services:Certified workflows with documented human review for contract and litigation support. German legal-tech providers restructure product tiers to isolate EU AI Act-compliant offerings from general-purpose APIs.
- Finance & Banking:Real-time multilingual communication for trading floors and regulatory reporting. SAMR algorithmic transparency rules force global vendors into domestic cloud partnerships for China operations.
- E-learning:Massive-scale course translation with adaptive difficulty and cultural localization. Indian ed-tech platforms drive volume for spoken-content translation across Dravidian and Indo-European language families.
By volume, Information Technology leads. By compliance premium, Legal Services is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT departments in Germany and the United States drive concentrated procurement of certified translation workflows. Automotive exporters and healthcare networks anchor demand for ISO 17100-compliant pipelines. Regulatory divergence between the EU AI Act and FDA guidance fragments vendor compliance strategies across jurisdictions.
United States
FDA scrutiny of software-as-a-medical-device intersects with HIPAA requirements for clinical trial documentation translation. Healthcare networks in Boston and the Research Triangle demand air-gapped processing for patient-facing portals. Silicon Valley collaboration-stack vendors embed real-time APIs directly into unified communications infrastructure.
Germany
Automotive suppliers in Stuttgart and Wolfsburg require ISO 17100-certified pipelines for safety-critical technical documentation. The EU AI Act mandates human-in-the-loop protocols for high-risk legal and financial translation workflows. German legal-tech providers restructure product tiers to isolate certified offerings from commodity API access.
China
SAMR enforces algorithmic transparency and data localization for cloud translation services operating within its jurisdiction. Domestic pharmaceutical manufacturers filing with the national pharmaceutical regulator require certified documentation for export markets. Yangtze River Delta technology clusters drive demand for localized inference infrastructure.
India
CDSCO regulatory filing requirements for generic drug approvals create specialized demand for chemistry-manufacturing-controls documentation translation. Indian ed-tech platforms in Bengaluru and Hyderabad drive volume for spoken-content translation across Dravidian language families. Pharmaceutical exporters in Gujarat and Maharashtra anchor certified workflow procurement.
Switzerland
Swissmedic data-residency mandates force pharmaceutical clusters in Basel to maintain air-gapped translation infrastructure for clinical trial documentation. Medical-device manufacturers demand ISO 17100-aligned quality assurance for regulatory submissions. Geneva-based financial institutions require audit-trail documentation for EU AI Act compliance on automated decision systems.
Global Translation Software Market Competitive Landscape
Player mix skews toward hyperscaler-platform providers with search-index data advantages and specialized neural-translation boutiques with linguistic depth. The vendor base separates into three strategic tiers: cloud-native API providers embedding translation into productivity suites, certified-quality specialists serving regulated industries, and legacy translation-management platforms with entrenched publishing-sector relationships. Dominant competitive moves include M&A to acquire training-data corpora and strategic partnerships to secure regional cloud infrastructure for data-localization mandates.
Within the hyperscaler tier, Google LLC and Microsoft Corporation exemplify platform-embedded distribution models that displace third-party procurement for enterprise IT departments. DeepL occupies a position as a European-anchored specialist in neural architecture optimization for Indo-European language pairs. Among legacy service providers, RWS Group and TransPerfect sit within the certified-quality tier serving pharmaceutical and legal verticals with human-in-the-loop workflows.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| IBM Corp |
| Amazon Web Services |
| DeepL |
| SYSTRAN SA |
| RWS Group |
| Lionbridge Technologies |
| TransPerfect |
| Others |
Supply & Pricing Matrix
Neural engine substitution for legacy statistical architectures redraws supply geography toward GPU cluster operators while compressing per-token pricing economics across API tiers. This displacement simultaneously concentrates inference capacity in hyperscaler-controlled regions and fragments margin pools between commodity throughput and certified quality layers.
Pricing Analysis
Cost-plus contracts with GPU cluster pricing indexation dominate high-volume API procurement, exposing buyers to semiconductor foundry capacity volatility. Three-tier pricing structure across premium certified, standard enterprise, and economy developer tiers separates ISO 17100-aligned human-in-the-loop workflows from raw neural inference. Price differentiation rests on certification grade and latency SLA tiering. Cost compression in economy API tiers is intensifying because training-data scale advantages consolidate among hyperscalers. Mid-market legal practices exhibit highest price sensitivity; pharmaceutical manufacturers in Basel show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Just-in-time provisioning of GPU inference capacity prevails among cloud-native vendors, while certified-quality specialists maintain strategic stockpiles of linguist marketplace capacity for compliance-driven demand spikes. Supply concentrates in United States hyperscaler regions, Germany for automotive-certified pipelines, and Switzerland for pharmaceutical air-gapped infrastructure. Raw dependencies span NVIDIA GPU silicon, high-quality parallel corpora from academic repositories, and specialized computational linguist labor pools. Single-source vulnerability in GPU semiconductor supply chains feeds from foundry capacity constraints. Distribution runs through hyperscaler marketplaces, systems integrators with compliance expertise, and direct API contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise IT procurement cycles are recovering from post-pandemic budget compression, with quarterly reporting demands resuming normal cadence and restoring translation API contract velocity.
For Market Incumbents: Secure training-data corpus acquisitions to defend against open-source foundation model commoditization. Deepen backward integration into specialized linguist marketplaces for EU AI Act-certified workflow tiers. Lock in long-term GPU cluster reservations to buffer margin against foundry pricing volatility. Channel control through embedded Office 365 and Teams distribution insulates against third-party API displacement. For New Entrants and Emerging Players: ISO 17100 fast-track certification for automotive technical documentation opens white-space in Stuttgart and Wolfsburg supplier ecosystems. Target India's CDSCO filing segment for pharmaceutical export documentation where incumbent coverage remains thin. Speech-to-speech neural audio codecs for offline mining field technicians represent the most penetrable application. Go-to-market through regional systems integrators with SAMR compliance expertise accelerates China market entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of specialized neural-translation boutiques with domain-specific training data. Long-term viability hinges on regulatory certification moats rather than raw inference scale. Target acquisition archetype: European-anchored vendors with EU AI Act compliance infrastructure and automotive vertical depth. Watch GPU cluster pricing volatility as the inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Training-data corpus purchases secure competitive moats in low-resource language pairs. |
| Strategic Partnership | SAMR-compliant domestic cloud infrastructure unlocks China market access for global vendors. |
| Product Launch | ISO 17100-certified workflow tiers capture automotive technical documentation premium pricing. |
| Platform Integration | Embedded Office 365 APIs displace third-party procurement for enterprise IT departments. |
| Geographic Expansion | India CDSCO filing services address pharmaceutical export documentation demand concentration. |
Research Methodology
Initial hypotheses were tested against primary input from enterprise IT procurement officers, computational linguists, regulatory affairs leads at pharmaceutical manufacturers, and automotive technical documentation managers, then refined through secondary validation. Sources drew from SEC filings of hyperscaler platform providers, EU AI Act implementation guidance documents, CDSCO regulatory filing databases, and Swissmedic data-residency compliance bulletins. Bottom-up demand modeling across deployment modes and solution types was triangulated with top-down market sizing from vendor revenue disclosures.
Variance decomposition across the projection horizon isolates contribution from neural architecture improvements, regulatory compliance cost inflation, and GPU capacity pricing cycles. Segmentation dimensions modeled include deployment architecture, solution type tiering, application lifecycle economics, and end-user industry compliance burden. CAGRs were derived from elasticity-adjusted adoption curves. Industry-specific inputs encompass EU AI Act conformity assessment timelines and FDA software-as-a-medical-device guidance evolution.
Decision-makers should treat outputs as directional under assumptions of sustained enterprise IT budget recovery and stable GPU foundry capacity expansion; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act enforcement intensity or GPU cluster pricing volatility crosses thresholds that restructure vendor margin economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
G Suite Technology Services Market
Software & Services
Customer Self-Service Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Online Whiteboard Software Market
Software & Services
Family Office Software Solutions Market
Software & Services
Telecom IT Services Market
Software & Services
Global Church Management Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
RIP Color Management Software Market
Software & Services
Lead Mining Software Market
Software & Services
Plant Design Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Referral Marketing Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Global Architecture Software Market
Software & Services
Attendance Management Software Market