
 Lending Software Market | 2026-2036
Lending Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lending Software Market Insights
The EU AI Act is recalibrating risk-modeling requirements across automated credit-decisioning stacks, compelling vendors to embed explainability modules. FIS leverages its core-banking integration depth to anchor enterprise lending workflows across North American banks. Finastra specializes in open-finance architecture, sustaining competitive position through API-first loan origination design. Jack Henry & Associates dominates the community and regional bank segment, controlling branch-originated loan digitization at scale.
Lending software comprises integrated technology platforms that automate borrower onboarding, credit assessment, collateral valuation, documentation, disbursement, and servicing across consumer and commercial credit products. These systems embed decision engines processing structured and alternative data sources, with throughput measured in loan applications per underwriter per day. Cloud-based deployment leads absolute spending as regulated institutions migrate from legacy mainframe environments, while SaaS models capture the fastest expansion by eliminating capital-intensive infrastructure commitments. Loan origination solutions command the largest solution-type revenue pool, though credit scoring modules are deepening AI integration fastest as lenders compete on speed-to-yes.
The Consumer Financial Protection Bureau in the United States enforces fair-lending algorithmic accountability, while the EU AI Act classifies credit-scoring automation as high-risk, mandating human oversight and audit trails. The Financial Conduct Authority in the United Kingdom supervises open-banking compliance, shaping how lending software interfaces with account-aggregation services. Stakeholders must weigh interoperability investment against regulatory fragmentation as jurisdictions diverge on AI governance intensity.
Market Dynamics
Cloud-native loan origination platforms are compressing deployment cycles from 18 months to under 90 days, forcing incumbent vendors to dismantle monolithic architectures or cede mid-market share to API-first challengers.
Growth Catalysts
- Open Banking API Mandates:The EU's PSD2 framework and the United Kingdom's Open Banking Standard compel legacy core banking vendors to expose loan-application data through standardized interfaces. This interoperability push accelerates third-party fintech integration.
- Community Bank Digitization:Credit unions and regional banks in the United States pursue branch-originated loan digitization to reduce per-application processing costs. Cloud SaaS models eliminate capital-intensive infrastructure commitments.
- Alternative Data Proliferation:Cash-flow underwriting using real-time bank-account aggregation is displacing traditional FICO-centric scoring. Lenders compete on speed-to-yes using AI-powered decision engines.
Market Restraints
- Core Banking Lock-In:Mainframe-dependent institutions face prohibitive migration costs when replacing legacy loan servicing modules. Technical debt accumulated over decades constrains rip-and-replace strategies.
- Regulatory Fragmentation:Divergent AI governance intensity between the EU AI Act, the US Consumer Financial Protection Bureau fair-lending rules, and the UK Financial Conduct Authority open-banking supervision forces vendors to maintain jurisdiction-specific compliance stacks.
- Talent Scarcity:Explainable AI engineering and model-risk management expertise concentrates in fintech hubs. Traditional vendors struggle to recruit practitioners capable of embedding audit-trail modules.
Strategic Opportunities
- Embedded Finance Convergence:Point-of-sale lending integration with e-commerce checkout flows creates new origination channels. Retail platforms in the United States and Germany seek white-label loan-origination APIs.
- Climate-Linked Credit Products:The EU Green Deal taxonomy and sustainable-finance disclosure requirements spur demand for carbon-footprint scoring modules. Green mortgage origination workflows represent an emerging application.
- SME Cash-Flow Lending:Underpenetrated small-business credit markets in India and Brazil attract API-first platforms. Real-time accounting software integration enables automated collateral-light underwriting.
Industry Challenges
- Model Explainability Engineering:The EU AI Act mandates human oversight for high-risk credit-scoring automation. Vendors must rebuild black-box neural networks into interpretable decision trees without sacrificing predictive accuracy.
- Legacy System Integration Complexity:Decades-old core banking databases lack standardized data schemas. Middleware development consumes 40-60% of implementation timelines for cloud-native origination platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lending Software Market |
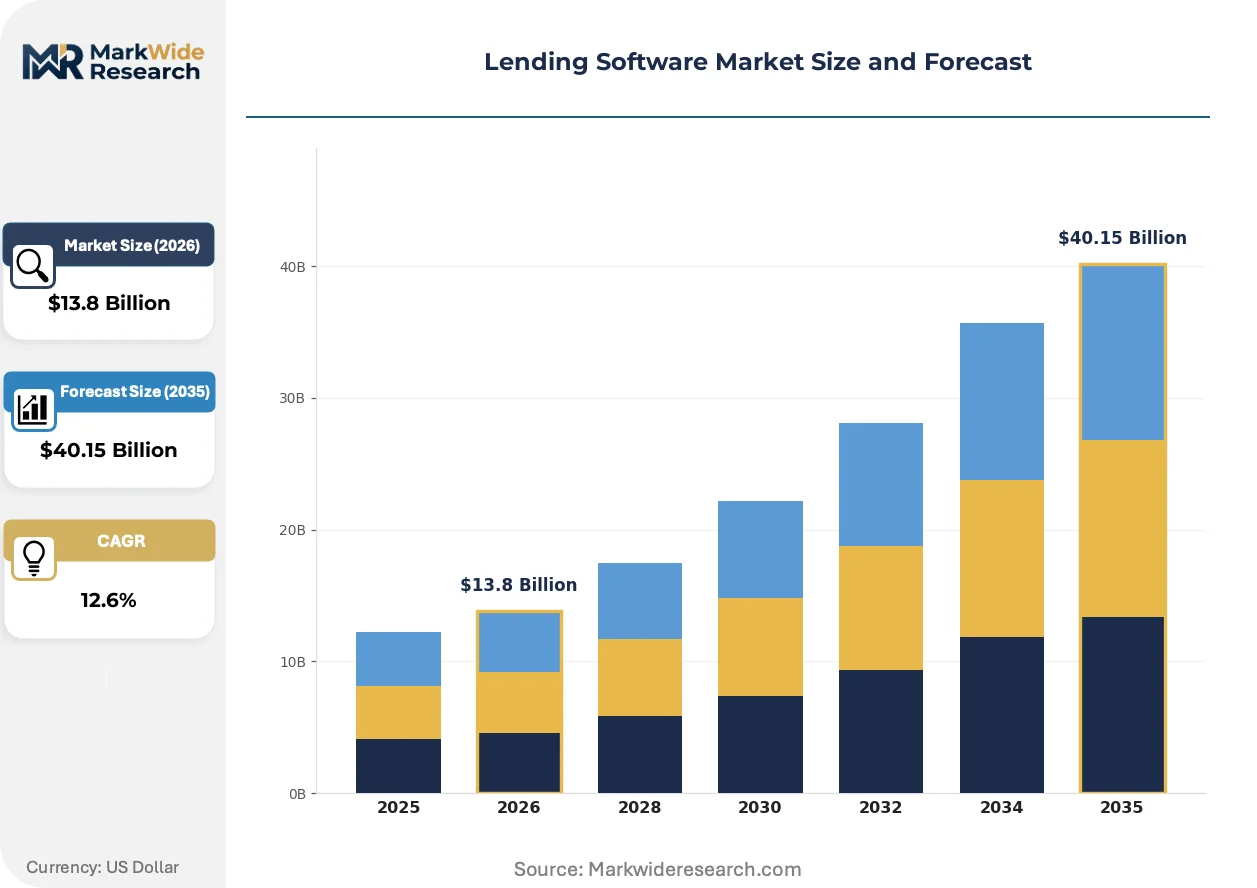
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $40.15 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Application: Personal Loans, Small Business Financing, Mortgage Lending, Student Credit, Equipment Financing End User: Consumer Finance Firms, Microfinance Institutions, Credit Unions, Peer-to-Peer Lenders, Online Lenders Solution Type: Loan Origination, Loan Management, Credit Scoring, Risk Analysis, Compliance Management |
| Companies Covered | FIS, Fiserv, Finastra, Newgen Software, Ellie Mae, Nucleus Software, Pegasystems, Jack Henry & Associates, TurnKey Lender, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lending Software Market Trends and Innovations
Artificial intelligence is compressing credit-decision latency from days to minutes while regulators simultaneously demand algorithmic transparency. This tension is reshaping vendor R&D priorities and buyer procurement criteria.
Microservices-based loan origination architecture is modularizing previously monolithic underwriting stacks. Community banks and credit unions in the United States are adopting containerized deployment to isolate credit-scoring, document management, and compliance modules. This modularization enables phased migration from legacy mainframes without full-stack replacement.
The EU AI Act's high-risk classification for automated credit-decisioning mandates human-in-the-loop oversight and comprehensive audit trails. Vendors must embed explainability modules that trace individual loan decisions to specific data inputs and model parameters. European banks are responding by procurement committees requiring algorithmic accountability certifications before vendor selection.
Buyers are unbundling loan origination from full-suite core banking contracts. Regional banks now procure best-of-breed credit-scoring modules through API subscriptions rather than accepting bundled offerings from incumbent vendors. This procurement pattern shift is most visible in the United States, where credit unions pursue competitive RFP processes for origination technology independent of core system providers.
Lending Software Market Segmentation
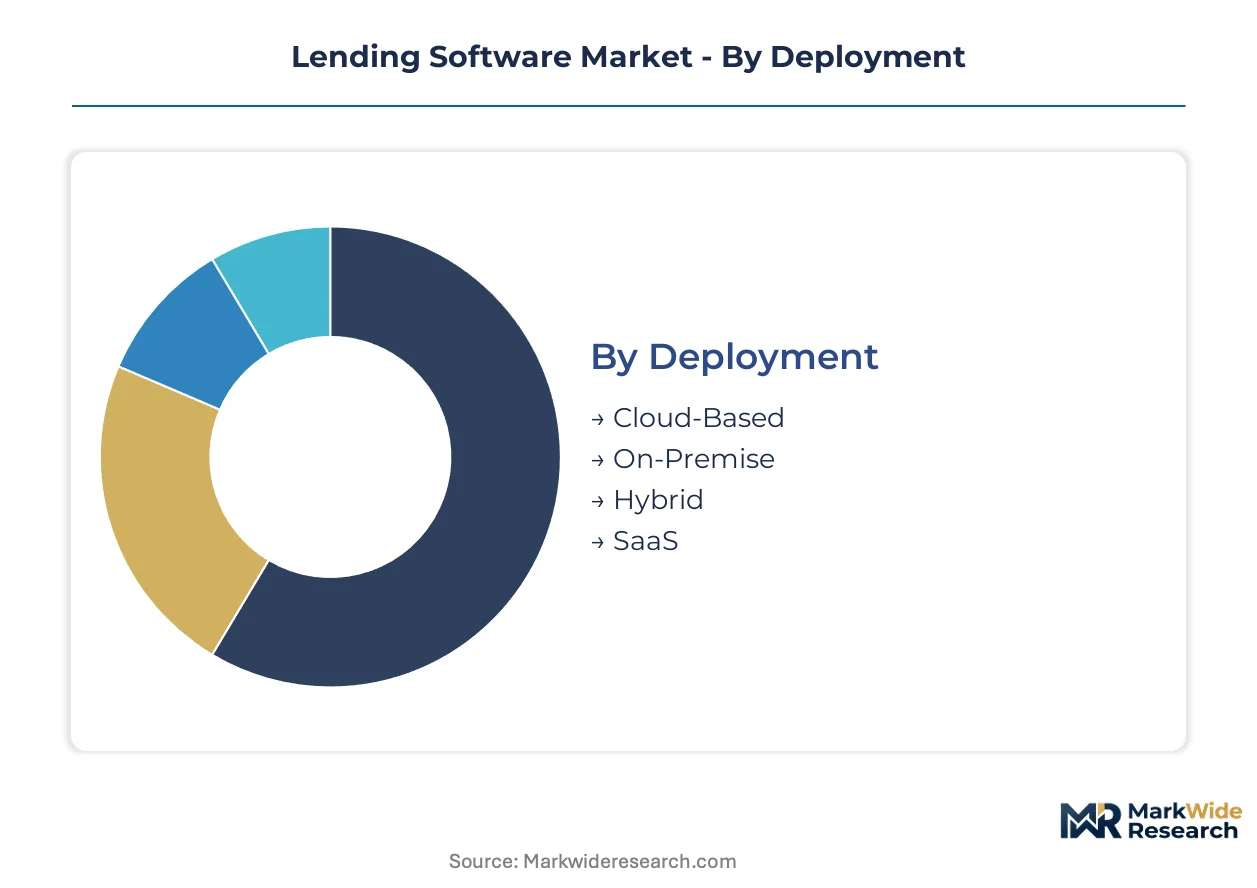
Lending software segmentation reveals how procurement priorities diverge across institution types and use cases. Deployment models and application verticals command distinct vendor strategies as buyers weigh regulatory exposure against speed-to-market requirements.
Deployment:
Upgrade cycles for lending infrastructure now compress from multi-year mainframe migrations to modular cloud transitions. Institutions evaluate total cost of ownership across capital expenditure, compliance overhead, and internal engineering burden.
- Cloud-Based:Multi-tenant architectures eliminate data center maintenance for regional banks. United States credit unions accelerate adoption to satisfy NCUA examination expectations for disaster recovery and data residency.
- SaaS:Subscription pricing aligns vendor incentives with client retention. German cooperative banks favor SaaS origination modules to minimize BaFin-mandated audit scope for internally managed systems.
- On-Premise:Air-gapped installations persist where national regulators mandate physical data sovereignty.
- Hybrid:Sensitive underwriting data remains on-premise while customer-facing portals deploy to public cloud.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
Application:
Loan product complexity determines workflow customization depth and integration touchpoints with external data providers.
- Mortgage Lending:Collateral valuation pipelines ingest automated valuation models and title records. United States originators face CFPB scrutiny on fair lending algorithms embedded in pre-approval engines.
- Small Business Financing:Cash-flow underwriting demands real-time accounting software integration. Indian NBFCs deploy API-first platforms connecting to GST filing systems for revenue verification.
- Personal Loans:Thin-file scoring relies on alternative data aggregation from telco and utility payment histories.
- Equipment Financing:Asset-level depreciation schedules integrate with residual value forecasting.
- Student Credit:Enrollment verification and future income estimation require education data provider contracts.
Mortgage Lending retains the largest revenue footprint, though Small Business Financing shows the steepest expansion trajectory.
End User:
Institutional charter type shapes procurement authority, vendor due diligence intensity, and acceptable integration timelines.
- Credit Unions:Member-owned governance structures prioritize cost containment over feature breadth. United States federally chartered credit unions select CUSO-affiliated vendors to satisfy NCUA third-party risk management guidance.
- Online Lenders:Digital-native operations demand sub-minute decision latency and seamless mobile onboarding. Brazilian fintechs leverage central bank open banking APIs for instant credit assessment.
- Consumer Finance Firms:Retail partnership origination requires white-label customization and embedded checkout integration.
- Microfinance Institutions:Low ticket sizes necessitate extreme automation to achieve unit economics.
- Peer-to-Peer Lenders:Marketplace structures require dual-sided underwriting for borrower and investor risk alignment.
Credit Unions anchor procurement volume in North America, with Online Lenders expanding most quickly across emerging markets.
Solution Type:
Functional module unbundling enables phased modernization without full-stack replacement of legacy servicing systems.
- Loan Origination:End-to-end automation spans application intake, document verification, and approval workflow. United Kingdom banks embed FCA-mandated affordability assessments into origination decision trees.
- Credit Scoring:Model development platforms support challenger scorecards against bureau-dependent legacy approaches. EU AI Act compliance tooling now differentiates vendor offerings for European deployments.
- Loan Management:Servicing modules handle payment processing, escrow administration, and investor reporting.
- Risk Analysis:Portfolio monitoring aggregates loan-level performance into concentration and stress testing outputs.
- Compliance Management:Audit trail generation and regulatory reporting automation reduce examination preparation burden.
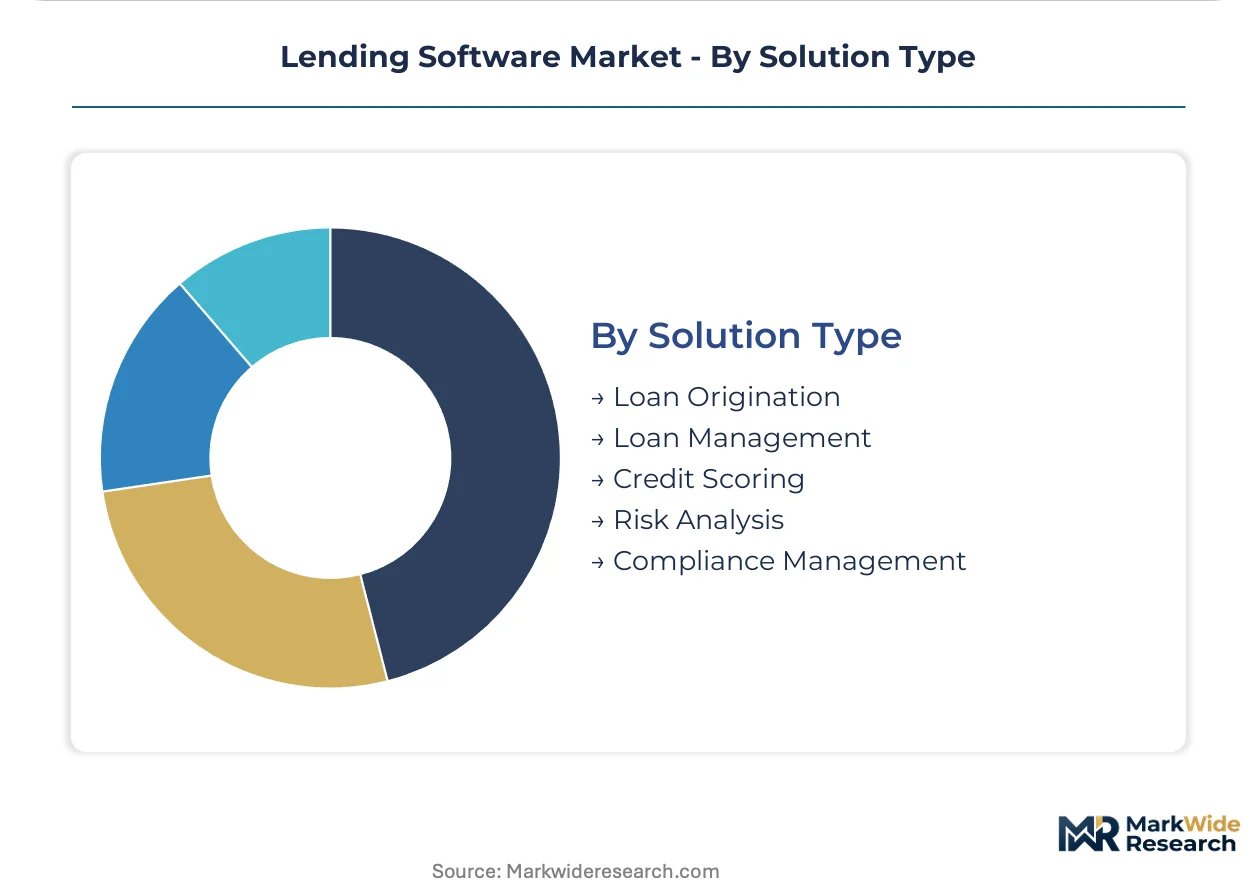
Loan Origination commands the largest solution investment, with Credit Scoring gaining share fastest as AI governance requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in San Francisco, London, and Bangalore anchor lending technology development. These concentrations attract venture capital and enterprise procurement budgets alike. Regional regulatory divergence shapes vendor product roadmaps.
United States
Credit unions and regional banks drive cloud-native origination adoption to satisfy NCUA examination expectations. The Consumer Financial Protection Bureau enforces fair-lending algorithmic accountability across automated underwriting. Charlotte and New York City host concentrated fintech engineering talent developing decision-engine modules.
United Kingdom
Open Banking Standard compliance compels legacy vendors to rebuild interoperability layers for account-aggregation services. The Financial Conduct Authority supervises API security and affordability assessment integration. London's fintech corridor attracts API-first challengers targeting incumbent market share.
Germany
Cooperative banks favor SaaS origination modules to minimize BaFin-mandated audit scope for internally managed systems. The EU AI Act classifies credit-scoring automation as high-risk, mandating explainability tooling. Frankfurt's financial center concentrates vendor compliance engineering resources.
India
Non-banking financial companies deploy API-first platforms connecting to GST filing systems for small-business revenue verification. The Reserve Bank of India regulates digital lending aggregation and data localization requirements. Mumbai and Bangalore host concentrated engineering teams building cash-flow underwriting modules.
Brazil
Central bank open banking APIs enable instant credit assessment for digital-native lenders competing on speed-to-yes. The national monetary authority mandates interoperability standards for financial data sharing. São Paulo's fintech ecosystem anchors Latin American lending software development.
Lending Software Market Competitive Landscape
Capital-heavy core banking vendors compete with asset-light API-first specialists in lending software delivery. The market structure tiers between incumbent full-suite providers, modular challengers, and embedded-finance enablers. Strategic archetypes include mainframe-anchored incumbents, cloud-native disruptors, and vertical SaaS specialists. Dominant competitive moves encompass M&A for technology tuck-ins and strategic partnerships for distribution reach.
Within the incumbent tier, FIS leverages core-banking integration depth across North American banks, while Finastra sustains position through open-finance architecture specialization. Jack Henry & Associates occupies a concentrated position serving community and regional bank digitization requirements. These three exemplify how vendor scale and regulatory compliance capabilities determine procurement outcomes in regulated lending markets.
| Leading Market Players |
|---|
| FIS |
| Fiserv |
| Finastra |
| Newgen Software |
| Ellie Mae |
| Nucleus Software |
| Pegasystems |
| Jack Henry & Associates |
| TurnKey Lender |
| Others |
Pricing and Supply Chain Analysis
Cloud-native microservices architecture is collapsing implementation timelines from legacy mainframe migrations, simultaneously compressing vendor cost structures and redistributing supply power toward API-first specialists. This technical transition enables subscription pricing models to displace perpetual licensing, while geographic talent clusters in San Francisco, London, and Bangalore anchor development cost differentials.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation driven by integration complexity and regulatory compliance certification. Premium tiers embed EU AI Act explainability modules and SOC 2 Type II audit trails, while economy offerings target single-product credit unions with stripped-down origination workflows. Cost compression in the standard tier is intensifying because mid-market banks now procure best-of-breed modules through API subscriptions rather than accepting bundled core banking contracts. Community banks exhibit the highest price sensitivity due to member-owned governance constraints, whereas money-center banks prioritize compliance depth over cost minimization.
Supply Chain Analysis
Direct-to-bank channels handle enterprise procurement for tier-one institutions, while cloud marketplace distribution and CUSO-affiliated vendor networks serve regional buyers. Software engineering supply concentrates in the United States, the United Kingdom, and India, with development costs varying substantially across these hubs. The supply chain draws from specialized talent pools spanning explainable AI engineering, model-risk management, and regulatory compliance architecture. Single-source vulnerability exists where core banking lock-in creates dependency on incumbent vendors for legacy system integration middleware. Distribution runs through implementation partners and system integrators who consume 40-60% of deployment timelines building custom middleware for decades-old database schemas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lending software market functions as a geographic-arbitrage play where engineering talent cost differentials between San Francisco and Bangalore enable margin expansion for vendors with distributed development footprints, while regulatory divergence between the EU AI Act and US fair-lending rules creates compliance-cost asymmetries.
For Market Incumbents: Deploy API-first interoperability layers to counter cloud-native challengers eroding mid-market share. Incumbents must dismantle monolithic architectures within 90-day deployment windows or cede regional banks to modular competitors. Backward integration into explainable AI tooling addresses the EU AI Act's high-risk classification mandates, while channel control through CUSO partnerships defends credit union procurement volume against fintech entrants. For New Entrants and Emerging Players: Embedded finance APIs represent the most penetrable route for bypassing core banking lock-in. New entrants should target white-label point-of-sale lending integration with e-commerce platforms in the United States and Germany, where retail checkout flows demand sub-minute decision latency. A go-to-market angle centered on climate-linked credit scoring modules exploits the EU Green Deal taxonomy gap among incumbent vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical SaaS specialists with narrow product scope but deep regulatory compliance capabilities. Long-term viability across the projection horizon favors vendors embedding audit-trail modules and human-in-the-loop oversight architectures required by divergent AI governance regimes. The signal to watch is procurement committee mandates for algorithmic accountability certifications before vendor selection, which accelerates consolidation toward compliance-heavy platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture enables third-party fintech connectivity mandated by UK Open Banking Standard. |
| Acquisition of Specialist Firm | Explainable AI engineering talent concentrates in fintech hubs and resists organic recruitment. |
| Geographic Expansion | Brazilian and Indian NBFC markets offer underpenetrated small-business credit origination opportunities. |
| Strategic Partnership | CUSO alliances satisfy NCUA third-party risk management guidance for credit union procurement. |
| Product Launch | Carbon-footprint scoring modules address EU Green Deal sustainable-finance disclosure requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bank CTOs, credit union procurement officers, fintech platform engineers, and regulatory compliance leads with secondary validation. SEC 10-K filings, NCUA examination guidance documents, EU AI Act regulatory texts, and UK Financial Conduct Authority open banking technical specifications anchored the secondary foundation. Bottom-up loan origination deployment tallies and top-down software spending estimates were triangulated to constrain forecast variance.
Segment-weighting applied deployment model, institution type, loan product complexity, and regional regulatory intensity as orthogonal dimensions across the modeling period. CAGRs were derived from fitted growth curves calibrated to disclosed vendor booking trends and buyer procurement cycle compression. Forecast inputs included cloud migration velocity at regional banks, open banking API adoption rates, and AI governance implementation lag times across jurisdictions.
Regulatory enforcement intensity shifts, core banking vendor consolidation events, and alternative data provider market structure changes are the dominant revision risks. Forecasts reflect assumptions about continued cloud adoption acceleration and sustained API standardization momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Hotel Management Software Market
Software & Services
Global Log Management Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Salesforce Services Market
Software & Services
Multi-Cloud SDN Market
Software & Services
Global Virtual Desktop Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Optical Design Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Royalty Management Software and Services Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Spain Sports Management Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Point of Sale (Pos) Software Market