
 OCR Scanning Software Market | 2026-2036
OCR Scanning Software Market Size, Share, and Industry Trends Forecast 2026-2036
OCR Scanning Software Market Analytics
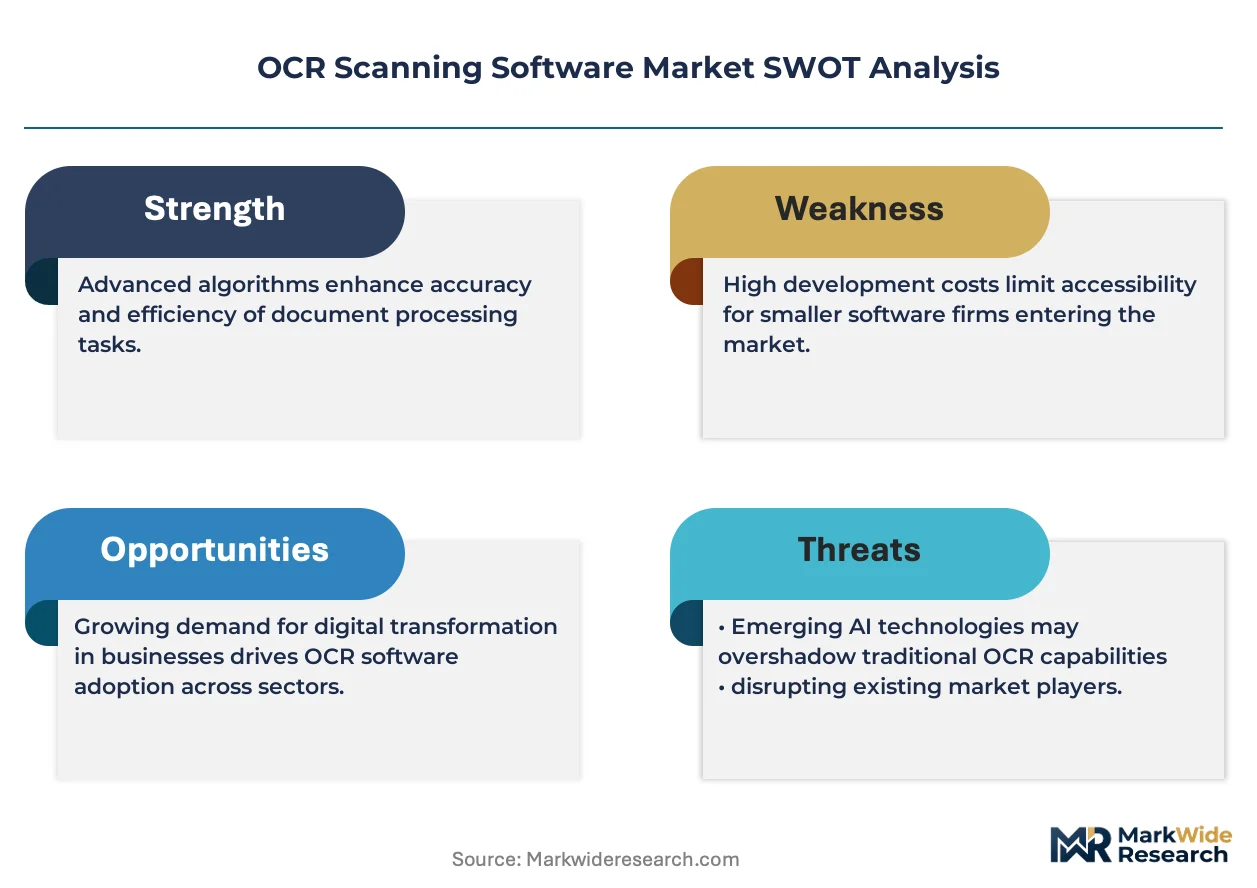
Buyer concentration in the banking sector is recalibrating procurement patterns across the OCR scanning software landscape. ABBYY leverages deep document intelligence specialization to anchor enterprise contracts with tier-one financial institutions. Google competes through cloud-native API architectures that reduce deployment friction for mid-market banks. Microsoft sustains platform integration advantages by embedding OCR capabilities across its productivity and Azure ecosystems.
OCR scanning software converts printed, handwritten, or image-based text into machine-readable formats through optical character recognition engines achieving accuracy rates above 99% on clean documents, with preprocessing pipelines handling skew correction, noise reduction, and font normalization. Its primary commercial purpose centers on eliminating manual data entry, accelerating document workflows, and enabling searchable archives across paper-intensive operations. Cloud-based solutions represent the fastest-expanding deployment architecture as enterprises prioritize elastic scaling and reduced infrastructure ownership. The BFSI end-user segment commands the deepest margin pools due to compliance-driven refresh cycles and high-volume transaction processing requirements.
The EU AI Act imposes transparency obligations on automated document processing systems, pushing vendors toward explainable extraction methodologies and audit trail architectures. HIPAA in the United States mandates access controls and encryption standards for healthcare OCR implementations handling protected health information. ISO 27001 certification has become a baseline gating factor for vendor selection in government and financial procurement frameworks. Stakeholders must monitor evolving algorithmic accountability requirements as regulators tighten oversight on AI-assisted decision-making pipelines.
Market Dynamics
Healthcare digitization mandates and EU algorithmic accountability rules are compressing procurement cycles while forcing vendors to rearchitect extraction pipelines for auditable transparency.
Growth Catalysts
- HIPAA Compliance Pressure:US healthcare providers must digitize patient records with encryption and access controls, accelerating OCR procurement for protected health information workflows.
- Industrial Document Automation:German manufacturing clusters lead European uptake, with automotive and machinery sectors deploying OCR for supply chain documentation and quality certification processing.
- EU AI Act Transparency Mandates:Automated document processing systems now require explainable extraction methodologies, pushing enterprises toward vendors with built-in audit trail architectures.
Market Restraints
- Specialized Hardware Dependencies:High-resolution scanning equipment and GPU-accelerated preprocessing infrastructure create capital barriers for mid-market deployment.
- Input Cost Volatility:Cloud compute pricing fluctuations directly impact SaaS OCR margins, with hyperscaler rate changes compressing vendor profitability.
- Legacy System Integration Friction:Decades-old enterprise content management systems in banking and insurance resist API-native OCR insertion without costly middleware development.
Strategic Opportunities
- Underpenetrated SME Banking:Community and regional banks in the United States lack dedicated document intelligence teams, creating whitespace for templated vertical solutions.
- Convergence with Robotic Process Automation:OCR engines paired with RPA bots enable straight-through processing for invoice and claims workflows without human validation loops.
- India's Digital Public Infrastructure:Aadhaar-linked document verification mandates and GST invoice digitization create regulatory tailwinds for localized OCR deployment.
Industry Challenges
- Multilingual Model Training Costs:Low-resource language support requires expensive labeled datasets, stretching R&D budgets for vendors targeting emerging markets.
- ISO 27001 Certification Timelines:Government and financial procurement frameworks demand current certification, with audit backlogs delaying vendor qualification by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OCR Scanning Software Market |
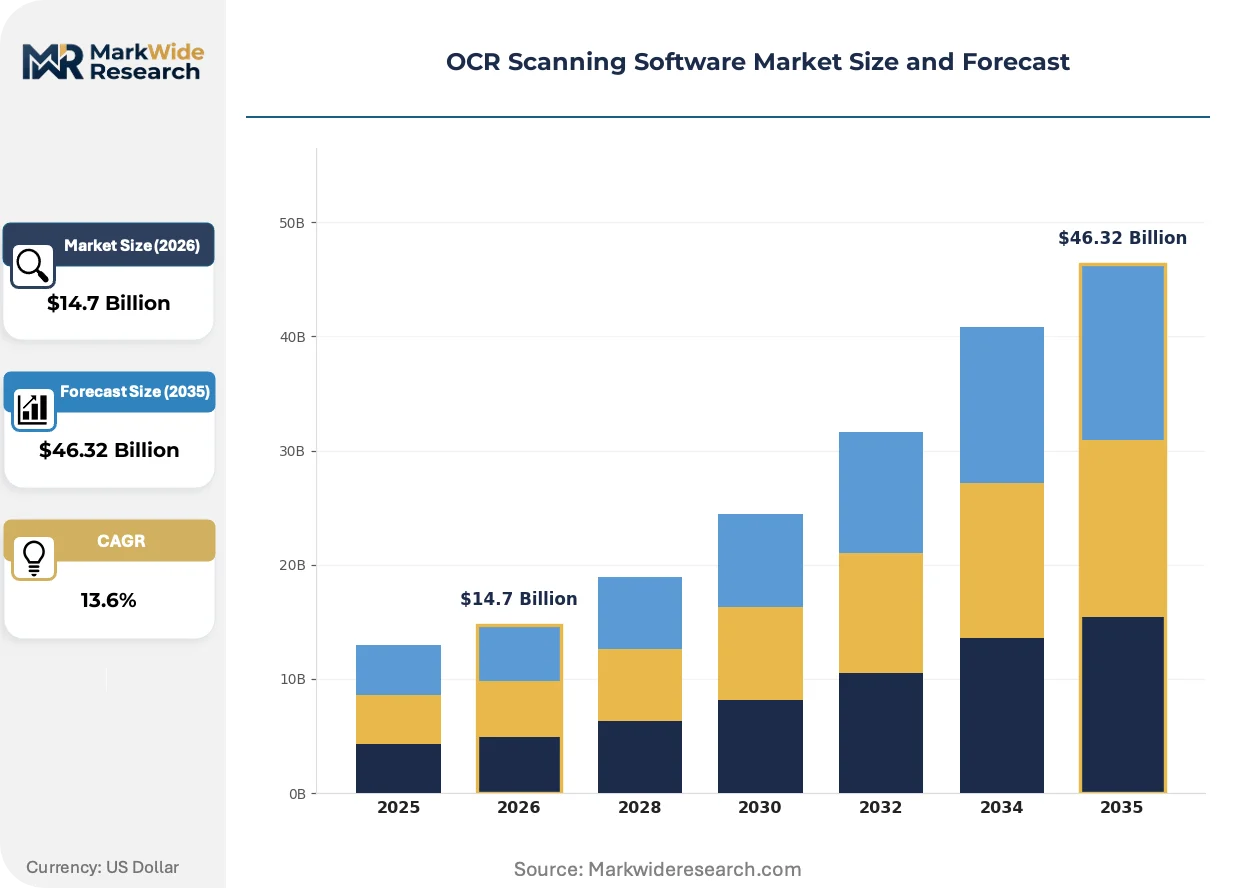
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $46.32 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Mobile Application, Cloud-based Solution, SDK Deployment: On-premise, SaaS, Hybrid, Managed Service End User: BFSI, Healthcare, Education, Government Functionality: Text Extraction, Data Classification, Barcode Recognition, Image Enhancement |
| Companies Covered | ABBYY, Adobe, Google, Microsoft, IBM, Kofax, Amazon Web Services, UiPath, OpenText Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OCR Scanning Software Market Evolving Landscape
Document intelligence architectures are fragmenting into composable microservices, enabling buyers to swap extraction engines without replacing entire workflow stacks. This decomposition is redistributing value toward specialized preprocessing and post-processing layers.
Transformer-based OCR architectures are modularizing document understanding pipelines into discrete components for layout analysis, table extraction, and handwriting recognition. Tier-one financial institutions in Germany and the United States are adopting these componentized systems to mix proprietary and third-party engines within single workflows. This modularity is compressing vendor lock-in and accelerating procurement decisions based on task-specific accuracy rather than platform breadth.
The EU AI Act's risk classification framework is forcing vendors to document training data provenance and model decision boundaries for high-risk document processing applications. Financial services procurement teams in France and the Netherlands now require algorithmic impact assessments as standard tender components. This regulatory layering is advantaging European-headquartered vendors with established GDPR compliance infrastructures over cloud-native competitors.
Subscription fatigue among enterprise buyers is fragmenting OCR procurement into unbundled consumption models separating extraction volume from storage, workflow orchestration, and human-in-the-loop validation. Mid-market logistics operators in the United Kingdom and manufacturing procurement departments in Japan are driving this shift toward metered API pricing. The disaggregation is pressuring platform vendors to defend margin through preprocessing specialization rather than bundled workflow suites.
OCR Scanning Software Market Segmentation
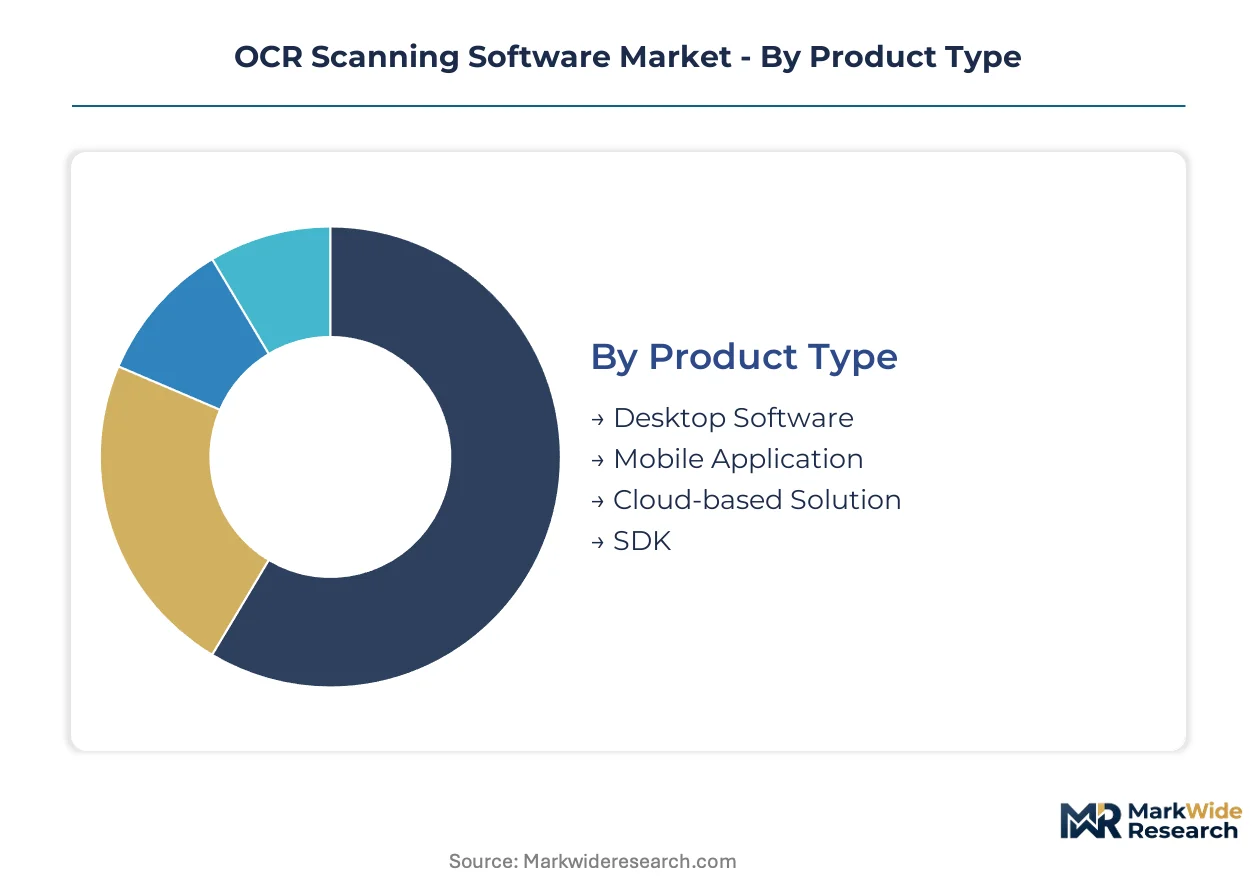
OCR scanning software vendors architect product portfolios around deployment constraints, regulatory exposure, and workflow integration depth. Segment boundaries are blurring as extraction engines become composable microservices.
Product Type:
Supply concentration favors vendors controlling preprocessing pipelines and model training infrastructure over pure-play interface providers.
- Desktop Software:Installed applications process documents locally using CPU-bound recognition engines with offline capability. German automotive suppliers and Japanese machinery manufacturers deploy these for quality certification workflows where cloud connectivity creates operational risk. HIPAA-covered entities in the United States prefer desktop deployments for patient record digitization to minimize data residency exposure.
- Cloud-based Solution:API-accessible extraction services leverage elastic GPU clusters for transformer-based document understanding. Mid-market banks in France and the Netherlands accelerate procurement for these architectures to satisfy EU AI Act audit trail requirements without capital infrastructure commitments. Metered consumption models are displacing perpetual licenses in logistics operations across the United Kingdom.
- Mobile Application:Smartphone-native capture tools use on-device neural engines for real-time text recognition. India's Aadhaar verification workflows and GST invoice digitization mandates drive installation volumes.
- SDK:Embedded libraries enable OEM integration into document scanners and enterprise content management systems. Japanese multifunction printer manufacturers represent concentrated demand.
Today's leader: Cloud-based Solution. Tomorrow's challenger: SDK.
Deployment:
Cost tier stratification separates capital-intensive infrastructure ownership from operational expenditure models.
- SaaS:Fully managed extraction services eliminate hardware procurement and model maintenance burdens. Community banks in the United States lacking dedicated document intelligence teams adopt templated vertical solutions through browser-based interfaces. Subscription fatigue is fragmenting procurement into unbundled consumption separating extraction volume from workflow orchestration.
- On-premise:Self-hosted deployments retain data within organizational network perimeters using containerized recognition services. Tier-one financial institutions in Germany maintain on-premise architectures for high-risk document processing applications subject to EU AI Act transparency mandates.
- Hybrid:Split architectures route sensitive preprocessing on-premise while leveraging cloud inference for non-critical workloads. Healthcare providers in the United States balance HIPAA encryption requirements with elastic scaling demands.
- Managed Service:Vendor-operated private cloud instances deliver dedicated infrastructure with outsourced operational responsibility. Government procurement frameworks in France require ISO 27001 certification that managed service providers consolidate.
SaaS commands current procurement volume. Hybrid architectures are climbing the fastest as compliance requirements harden.
End User:
Application-specific accuracy requirements and regulatory refresh cycles determine margin capture across verticals.
- BFSI:Banking, financial services, and insurance operations process high-volume transaction documentation with 99%+ accuracy requirements. Compliance-driven refresh cycles in the United States and Germany sustain deep margin pools. ABBYY anchors enterprise contracts through specialized document intelligence for tier-one institutions.
- Healthcare:Patient record digitization mandates HIPAA encryption and access control implementations. US providers accelerate procurement to eliminate manual data entry in protected health information workflows.
- Government:Public sector procurement frameworks demand ISO 27001 certification and algorithmic impact assessments under EU AI Act risk classifications. French and Dutch tender processes now require documented training data provenance.
- Education:Academic institutions and examination boards deploy OCR for transcript processing and assessment digitization. Budget constraints favor open-source preprocessing pipelines.
BFSI dominates revenue concentration. Healthcare is gaining share fastest through regulatory compression of procurement cycles.
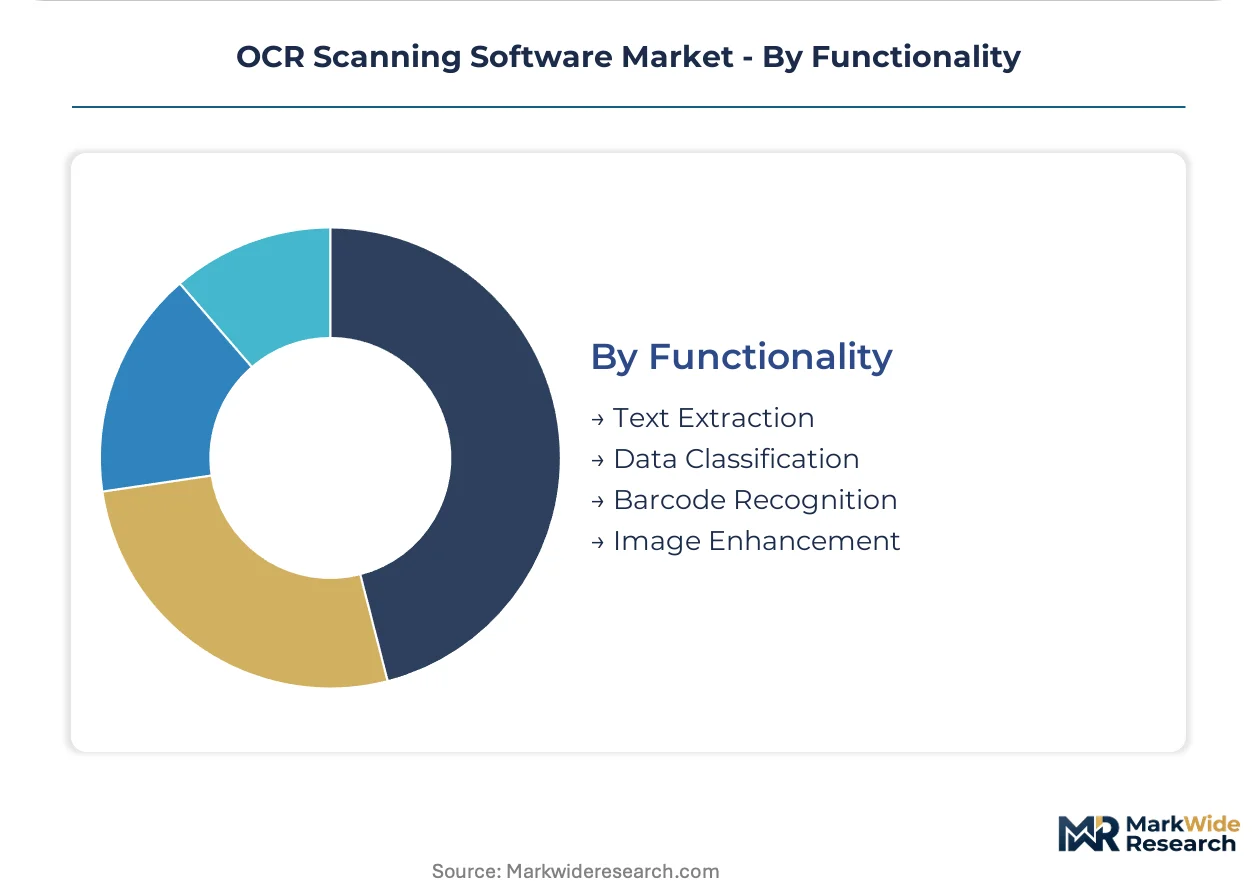
Functionality:
Maturity gradients separate commoditized text recognition from specialized extraction capabilities commanding premium positioning.
- Text Extraction:Core optical character recognition engines convert printed and handwritten content into machine-readable formats. Accuracy rates above 99% on clean documents represent baseline market entry requirements.
- Data Classification:Intelligent document understanding categorizes content by type, sender, and semantic structure. Financial services procurement teams in Germany adopt these capabilities for automated routing of loan applications and insurance claims.
- Barcode Recognition:Specialized decoding for 1D and 2D symbologies enables supply chain tracking and inventory management. Manufacturing procurement departments in Japan drive integration with enterprise resource planning systems.
- Image Enhancement:Preprocessing pipelines correct skew, reduce noise, and normalize fonts before recognition. GPU-accelerated infrastructure creates capital barriers that advantage vendors with dedicated hardware partnerships.
Text Extraction remains table stakes. Data Classification represents the steepest expansion trajectory as document intelligence architectures fragment into composable microservices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation investment outpaces US healthcare digitization spend, while India's digital public infrastructure creates regulatory tailwinds unmatched elsewhere.
United States
HIPAA-covered healthcare providers digitize patient records with encryption mandates, accelerating procurement for protected health information workflows. FDA oversight of clinical documentation systems reinforces audit trail requirements. Boston-area hospital networks deploy desktop OCR for local processing to minimize data residency exposure.
Germany
Automotive and machinery sectors process supply chain documentation through industrial document automation clusters. EU AI Act transparency obligations force explainable extraction methodologies on high-risk applications. Bavarian manufacturing procurement departments drive integration with enterprise resource planning systems for quality certification workflows.
India
Aadhaar-linked document verification mandates and GST invoice digitization create volume demand for mobile-native capture tools. RBI oversight of financial documentation standards accelerates banking sector procurement. Mumbai and Bangalore logistics operators adopt metered API pricing for invoice processing workflows.
United Kingdom
Mid-market logistics operators fragment procurement into unbundled consumption models separating extraction volume from workflow orchestration. GDPR compliance requirements push vendors toward auditable data extraction architectures. London financial services procurement teams require algorithmic impact assessments for automated document processing tenders.
France
Public sector procurement frameworks demand ISO 27001 certification and documented training data provenance under EU AI Act risk classifications. ANSM and CNIL oversight of healthcare documentation reinforces encryption standards. Paris-based financial institutions adopt componentized document understanding systems to mix proprietary and third-party engines.
OCR Scanning Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction engine architectures, creating tiered procurement patterns based on integration depth and deployment flexibility. The vendor base stratifies between platform-embedded capabilities and standalone document intelligence offerings. Three archetypes dominate: hyperscaler cloud providers, enterprise software incumbents with workflow integration advantages, and specialized document intelligence vendors with vertical accuracy optimization. Competitive moves center on API-native insertion strategies and preprocessing pipeline specialization that reduces customer switching costs.
Within the specialized document intelligence tier, ABBYY occupies a position exemplifying deep vertical specialization for tier-one financial institutions. Among hyperscaler-based offerings, Google and Microsoft sit within the platform-embedded archetype, representing divergent routes to enterprise adoption through cloud-native architectures and productivity ecosystem integration respectively.
| Leading Market Players |
|---|
| ABBYY |
| Adobe |
| Microsoft |
| IBM |
| Kofax |
| Amazon Web Services |
| UiPath |
| OpenText Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up document intelligence specialists anchor supply-side discipline through platform consolidation, translating GPU infrastructure control into tiered SaaS pricing power while compressing margins for pure-play API vendors lacking preprocessing pipeline ownership.
Pricing Analysis
Capacity additions in hyperscaler cloud regions are reshaping price floors for extraction volume, forcing specialized vendors toward value-based differentiation. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified managed services from metered API consumption. Price differentiation hinges on audit trail depth and EU AI Act compliance documentation. Mid-market logistics operators exhibit highest price sensitivity, while tier-one German financial institutions absorb premium tiers for explainable extraction methodologies.
Supply Chain Analysis
Refurbishment flows for GPU-accelerated preprocessing hardware concentrate in Taiwan and South Korea, with secondary markets emerging for decommissioned cloud inference clusters. Core supply draws from NVIDIA datacenter partnerships, specialized scanner OEM relationships in Japan, and open-source transformer model repositories. Single-source vulnerability around transformer training data provenance creates procurement risk for EU AI Act compliance. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OCR scanning software represents a late-cycle quality story as procurement teams prioritize ISO 27001 certification and algorithmic audit trails over raw extraction accuracy, compressing vendor selection toward compliance-validated architectures.
For Market Incumbents: Deploy backward integration into GPU preprocessing infrastructure to defend margin against hyperscaler API commoditization. Consolidate specialized document intelligence capabilities through targeted acquisition of handwriting recognition specialists. Reinforce platform stickiness by embedding EU AI Act audit trail architectures directly into managed service offerings before regulatory deadlines harden procurement requirements. For New Entrants and Emerging Players: Launch via templated vertical solutions targeting underpenetrated community banks in the United States lacking dedicated document intelligence teams. Exploit whitespace in India's Aadhaar-linked verification workflows through mobile-native capture tools with localized language support. Partner with robotic process automation platforms for straight-through processing bundles that bypass incumbent workflow suites. For Investors and Strategic Acquirers: Enterprise software conglomerates pursuing workflow integration are the most active acquirer in this space, valuing preprocessing pipeline specialization over pure-play recognition engines. Target mid-cap vendors with established GDPR compliance infrastructures and German automotive sector penetration. Monitor EU AI Act implementation timelines as inflection indicator for compliance-validated vendor premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding OCR engines within Microsoft Azure and Google Cloud ecosystems reduces deployment friction for mid-market banks. |
| Acquisition of Specialist Firm | Consolidating handwriting recognition capabilities addresses low-resource language gaps in India's Aadhaar verification workflows. |
| Strategic Partnership | Pairing extraction engines with UiPath RPA bots enables straight-through invoice processing without human validation loops. |
| Geographic Expansion | Localized deployment in Mumbai and Bangalore captures GST invoice digitization mandates driving metered API adoption. |
| Product Launch | Componentized document understanding systems allow Paris financial institutions to mix proprietary and third-party extraction engines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs at tier-one financial institutions, IT procurement officers at HIPAA-covered healthcare providers, platform engineers at hyperscaler cloud divisions, and integration specialists at RPA vendors with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and hospital procurement databases. Bottom-up volume modeling and top-down market sizing triangulated across deployment architecture, organization size, vertical compliance exposure, integration complexity, and regional adoption patterns.
Historical reference periods anchored growth trajectory assumptions across the modeling period, with segmentation dimensions including deployment model, end-user vertical, functionality tier, and regional regulatory cluster. CAGRs derived from elasticity analysis linking extraction volume growth to compliance mandate implementation timelines, cloud infrastructure expansion rates, and document digitization spend intensity in banking and healthcare sectors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or hyperscaler pricing volatility. Practitioners should monitor ISO 27001 certification audit backlogs and transformer model training cost inflation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Board Management Software Market
Software & Services
Simulation Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Content Creation Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Global Email Management Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
LTFS Copy Software Market
Software & Services
Audit Management Software Market
Software & Services
Customer Revenue Optimization Software Market