
 Global OEE Software Market | 2026-2036
Global OEE Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global OEE Software Market Foresight
Germany's industrial automation ecosystem is reshaping competitive dynamics in OEE software. Siemens AG leverages its native manufacturing relationships to anchor cloud-to-edge integration offerings. ABB Ltd. competes through deep specialization in robotics-linked performance analytics for automotive lines. Rockwell Automation Inc. extends its North American channel control into European pharmaceutical facilities with modular deployment architectures.
Overall Equipment Effectiveness (OEE) software quantifies manufacturing productivity by measuring availability, performance, and quality against theoretical maximum output, typically integrating with SCADA and PLC systems via OPC UA or MQTT protocols to deliver sub-second cycle-time visibility. The primary commercial purpose is to convert shop-floor data into actionable loss categorization that reduces unplanned downtime and defect rates. Cloud-based deployment leads solution type adoption among mid-market food and beverage processors seeking lower capital barriers, while integrated Manufacturing Execution Systems capture the deepest margin pools in semiconductor fabrication where wafer traceability mandates unified data layers. Predictive analytics represents the fastest-expanding use case segment as pharmaceutical manufacturers deploy machine-learning models for root-cause identification.
The EU AI Act, GDPR, and FDA 21 CFR Part 11 collectively shape product architecture by mandating algorithmic transparency, data residency, and electronic record integrity across regulated manufacturing environments. Germany's BSI IT-Grundschutz standards and Japan's METI data-free-flow-with-trust framework further fragment compliance requirements for multi-national deployments. Stakeholders must evaluate sovereign cloud partnerships and audit-trail capabilities before committing to platform architectures that will face escalating cross-border certification complexity.
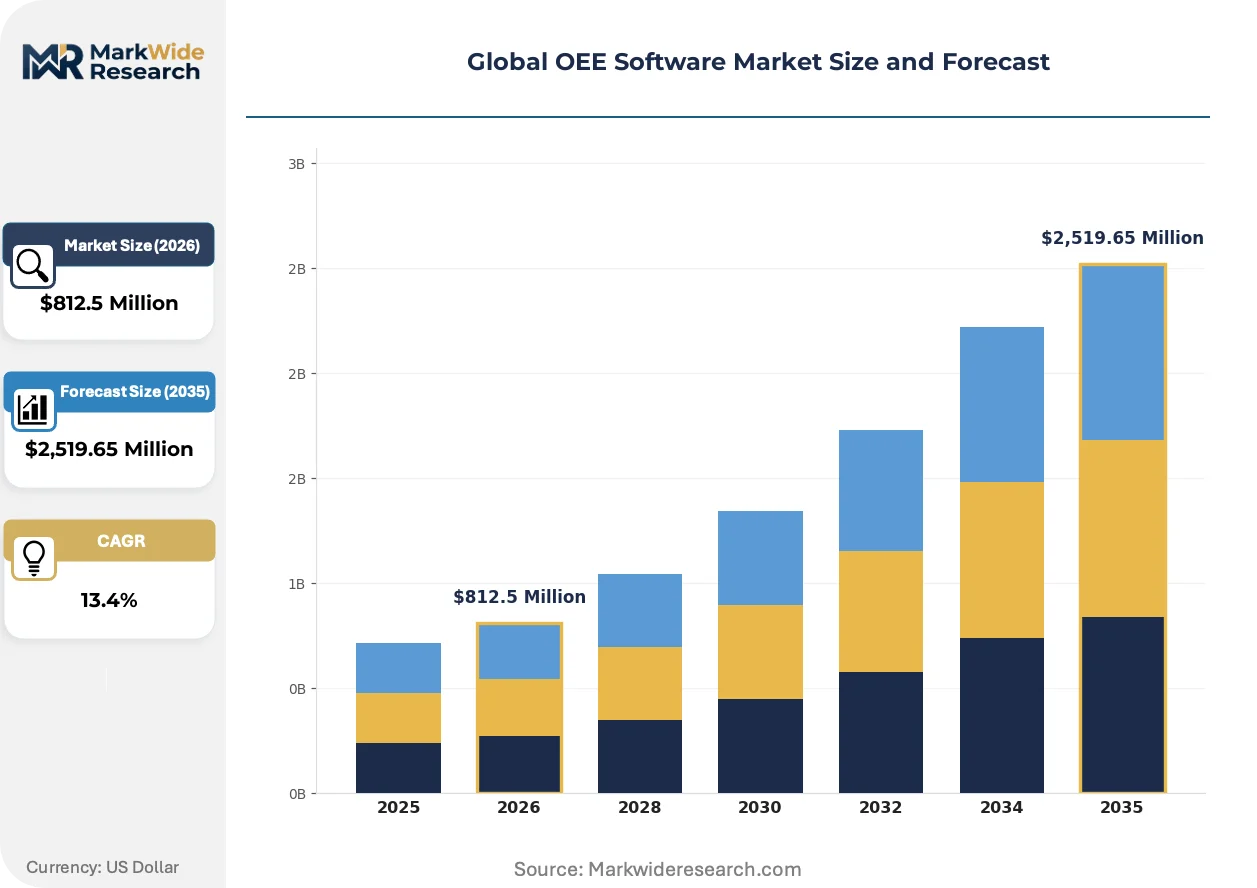
Market Dynamics
The convergence of edge computing architectures with sovereign cloud mandates is fragmenting deployment strategies across regulated manufacturing environments, forcing platform vendors to engineer dual-compliance stacks that satisfy both real-time latency requirements and data residency constraints.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Manufacturers in pharmaceutical and medical device segments must deploy explainable machine-learning models for quality deviation analysis, accelerating replacement of black-box analytics with auditable OEE platforms.
- Automotive OEM real-time monitoring:German and Japanese vehicle producers are embedding OEE modules directly into press shop and paint line control systems to compress cycle-time visibility below 500 milliseconds.
- Semiconductor wafer traceability requirements:Unified data layers integrating OEE with MES and ERP systems capture mandatory process genealogy for advanced node fabrication in Taiwan and South Korea.
Market Restraints
- Specialized OT-IT integration talent scarcity:Shortage of engineers fluent in both PLC ladder logic and cloud-native microservices architecture inflates implementation timelines and service delivery costs.
- Sovereign cloud infrastructure concentration:Limited certified providers in Germany, France, and Japan create vendor lock-in risks and regional supply bottlenecks for GDPR-compliant deployments.
- Legacy brownfield integration complexity:Proprietary protocols in aging SCADA systems require expensive protocol gateways, delaying ROI realization in food and beverage mid-market installations.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO compliance requirements and PLI scheme incentives are driving greenfield facility construction where cloud-native OEE can anchor digital-first architectures without legacy debt.
- Predictive quality analytics convergence:Integration of computer vision defect detection with OEE quality metrics creates new subscription revenue pools in automotive stamping and electronics assembly.
- Outcome-based performance contracts:Equipment vendors in packaging machinery are bundling OEE analytics with uptime guarantees, shifting revenue from capital sales to recurring operational expenditure models.
Industry Challenges
- Cross-border certification timeline fragmentation:FDA 21 CFR Part 11, EU MDR, and Japan PMDA electronic record requirements demand parallel validation tracks that extend enterprise sales cycles.
- Edge-to-cloud security architecture complexity:Manufacturing CISOs must reconcile IEC 62443 zone-based segmentation with zero-trust cloud access, creating procurement friction and technical risk exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global OEE Software Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $2,519.65 Million |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Deployment Solution Type: Standalone OEE, Integrated Manufacturing Execution System, Real-Time Monitoring, Predictive Analytics, Reporting Tools Use Case: Downtime Tracking, Performance Analysis, Quality Control, Capacity Planning, Root Cause Analysis End User Industry: Automotive OEMs, Food & Beverage Processors, Semiconductor Fabricators, Pharmaceutical Manufacturers, Consumer Electronics Producers |
| Companies Covered | Rockwell Automation Inc., ABB Ltd., Siemens AG, SAP SE, Oracle Corporation, Honeywell International Inc., General Electric Company, Litmus Automation, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global OEE Software Market Shifts & Advancements
Digital twin technology is virtualizing physical production lines, compressing the feedback loop between simulation and shop-floor execution while regulatory pressure on algorithmic accountability intensifies platform engineering priorities.
Edge-native OEE platforms are virtualizing data processing workflows by executing analytics on factory-floor gateways rather than centralized cloud instances. Automotive and semiconductor manufacturers in Germany and Taiwan are deploying these architectures to achieve sub-100-millisecond latency for emergency stop integration. This virtualization is compressing infrastructure costs while satisfying GDPR data minimization principles.
EU AI Act risk classification requirements are mandating human-in-the-loop oversight for high-risk manufacturing AI systems. Pharmaceutical and medical device producers must maintain algorithmic decision trails and bias audit documentation, driving demand for OEE platforms with built-in explainability dashboards. German BSI IT-Grundschutz certification is emerging as a procurement filter for multi-site European deployments.
Buyer procurement patterns are consolidating vendor relationships around integrated manufacturing software stacks rather than point solutions. Food and beverage processors in the United States and Brazil are favoring OEE modules embedded within broader MES platforms, displacing standalone deployments. This concentration is elevating platform ecosystem breadth above specialized feature depth in competitive evaluations.
Global OEE Software Market Segmentation
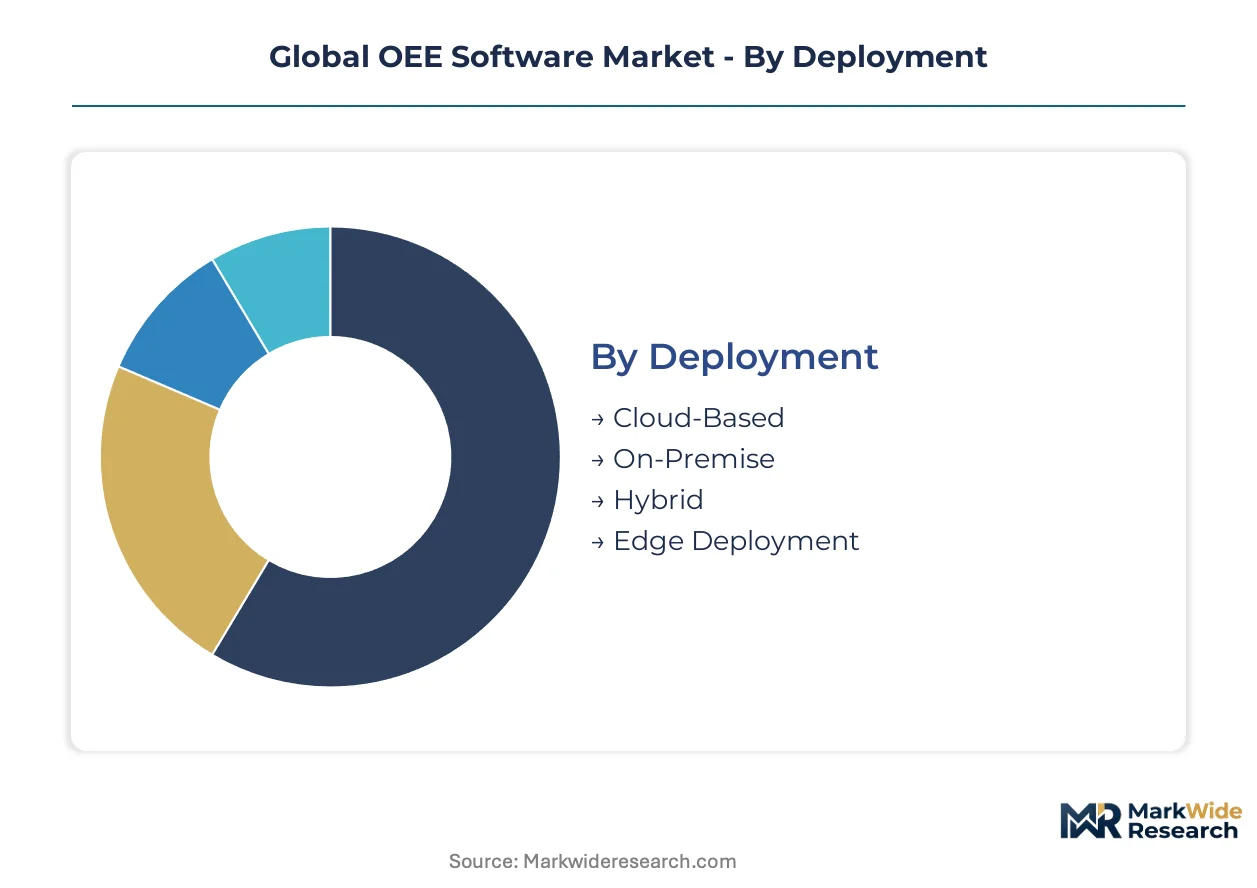
OEE software segmentation reflects divergent buyer priorities across latency requirements, regulatory exposure, and integration depth. Deployment choices determine compliance architecture, while solution type selection signals digital maturity and capital commitment levels.
Deployment:
Mature cloud configurations dominate mid-market adoption, while edge-native architectures emerge as the critical frontier for latency-sensitive manufacturing.
- Cloud-Based:Multi-tenant SaaS architectures deliver rapid deployment without on-site infrastructure investment. Food and beverage processors in Brazil and the United States favor this model to minimize capital barriers and accelerate time-to-value.
- On-Premise:Dedicated server installations within facility firewalls satisfy stringent data residency mandates. Pharmaceutical manufacturers in Germany and Switzerland deploy these configurations to meet EU AI Act algorithmic transparency requirements and BSI IT-Grundschutz certification standards.
- Hybrid:Split architectures process sensitive quality data locally while aggregating analytics in sovereign cloud instances. Semiconductor fabricators in Taiwan use this approach to balance wafer traceability compliance with centralized benchmarking.
- Edge Deployment:Gateway-level analytics execute within 100 milliseconds of physical events. Automotive press shops in Germany embed these modules for emergency stop integration and real-time cycle-time compression.
Cloud-based deployments handle the majority of throughput; edge deployment is the fastest mover on share.
Solution Type:
Buyer procurement patterns favor integrated stacks over point solutions, with predictive modules commanding premium positioning.
- Standalone OEE:Dedicated availability-performance-quality measurement tools with modular SCADA integration. Mid-market metal fabrication facilities in India select these for focused loss categorization without MES complexity.
- Integrated Manufacturing Execution System:Unified data layers combining OEE with work-order management and genealogy tracking. Semiconductor fabricators in South Korea mandate these for advanced node process documentation.
- Real-Time Monitoring:Sub-second visibility dashboards streaming from PLC gateways via OPC UA or MQTT protocols. Paint line operators in Germany deploy these to compress defect response windows.
- Predictive Analytics:Machine-learning models forecasting equipment degradation and quality deviation. Pharmaceutical manufacturers in Ireland integrate these with computer vision for root-cause automation.
- Reporting Tools:Configurable dashboards and automated compliance documentation generators. Medical device producers in the United States leverage these for FDA 21 CFR Part 11 electronic record integrity.
Integrated MES solutions capture the deepest margin pools; predictive analytics is climbing the fastest in procurement priority.
Use Case:
Application focus varies by operational pain point, with downtime and quality commanding the largest implementation budgets.
- Downtime Tracking:Automated classification of stop events by reason code and duration impact. Packaging machinery operators in Italy deploy these to quantify changeover losses and justify capital replacement.
- Performance Analysis:Speed loss quantification against theoretical maximum cycle times. Consumer electronics assembly lines in Vietnam use these to identify micro-stoppages invisible to manual observation.
- Quality Control:Real-time defect rate monitoring with automatic lot segregation triggers. Pharmaceutical tablet presses in Germany integrate these with METI data-free-flow-with-trust frameworks for cross-border batch release.
- Capacity Planning:OEE-derived throughput forecasting for production scheduling optimization. Food processors in Spain leverage these to align seasonal demand spikes with maintenance windows.
- Root Cause Analysis:Correlation engines linking multiple loss categories to underlying equipment or process conditions. Automotive stampers in Mexico deploy these to reduce recurring die-change delays.
Downtime tracking handles the majority of throughput; root cause analysis is gaining share fastest as AI-enabled diagnostic tools mature.
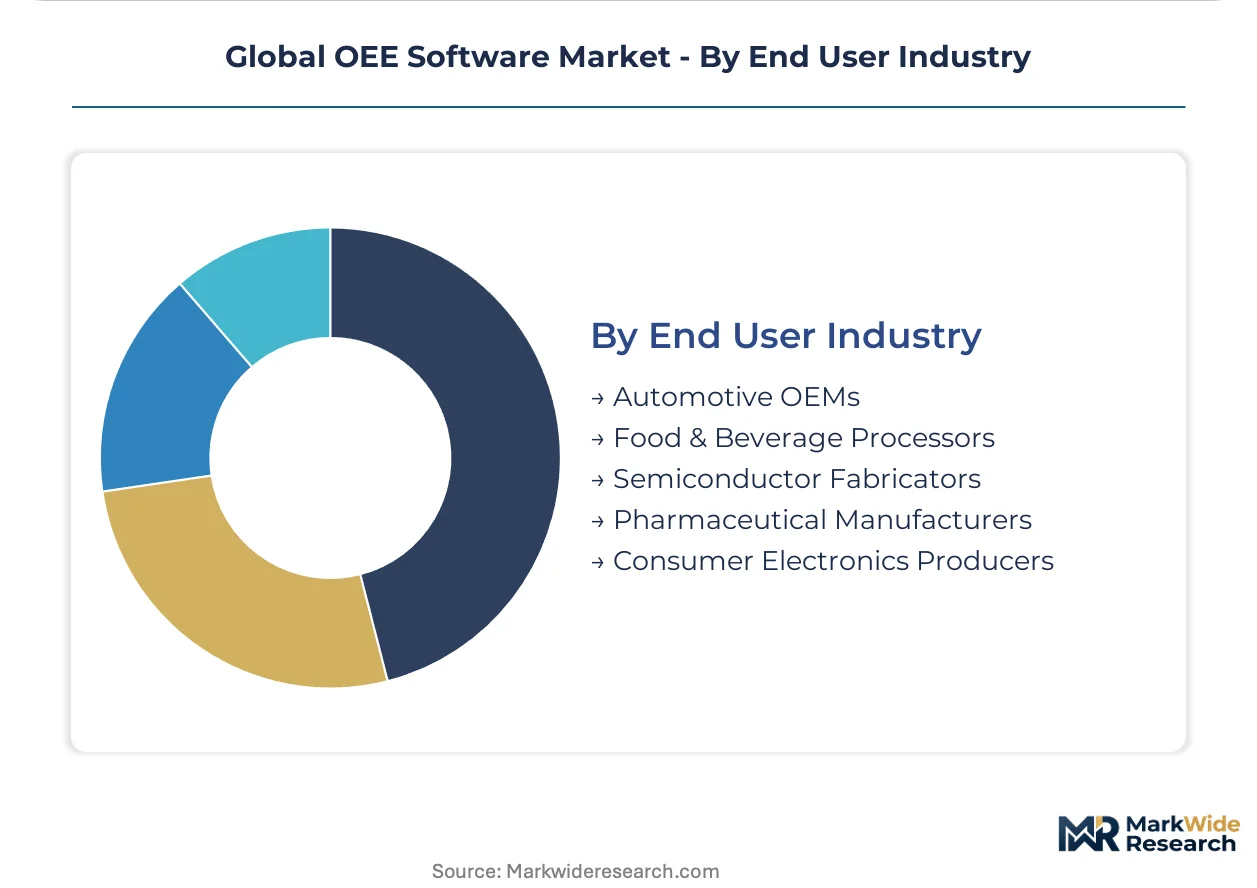
End User Industry:
Industry-specific regulatory density and automation sophistication create sharply differentiated deployment requirements.
- Automotive OEMs:High-volume, low-mix environments demanding sub-500-millisecond latency for press shop and paint line integration. German and Japanese vehicle producers anchor this segment with embedded control system architectures.
- Food & Beverage Processors:Batch-oriented operations prioritizing rapid deployment and hygiene-compliant hardware. Brazilian meatpacking facilities favor cloud-native modules to avoid on-premise server maintenance in washdown environments.
- Semiconductor Fabricators:Cleanroom environments with mandatory wafer-level traceability and unified MES-OEE-ERP data layers. Taiwan and South Korean foundries drive specifications for this segment.
- Pharmaceutical Manufacturers:Regulated environments requiring algorithmic explainability, data residency, and electronic batch records. German and Irish facilities lead adoption under EU AI Act and EMA guidance.
- Consumer Electronics Producers:High-mix, high-velocity assembly with compressed product lifecycles. Vietnamese and Mexican contract manufacturers prioritize rapid reconfiguration and multilingual operator interfaces.
Automotive OEMs handle the majority of throughput; pharmaceutical manufacturers are expanding most quickly as compliance mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR and the EU AI Act anchor compliance architecture in Germany, where automotive and pharmaceutical clusters drive edge-deployment specifications. Sovereign cloud mandates fragment across Japan's METI framework and US FDA electronic record requirements. Industrial automation density concentrates procurement power in specific manufacturing corridors.
Germany
Automotive OEMs embed OEE modules into press shop control systems for sub-500-millisecond cycle-time visibility. BSI IT-Grundschutz certification filters multi-site procurement decisions. The Stuttgart automotive cluster and Ludwigshafen chemical corridor anchor edge-native deployment specifications.
United States
Food and beverage processors favor cloud-native modules to minimize capital barriers in brownfield facilities. FDA 21 CFR Part 11 mandates electronic record integrity for pharmaceutical and medical device producers. The Midwest manufacturing belt and Texas chemical corridor concentrate predictive analytics adoption.
Japan
Vehicle producers integrate OEE platforms directly into paint line control systems for real-time defect response. METI's data-free-flow-with-trust framework shapes cross-border batch release protocols. The Nagoya automotive cluster and Osaka electronics corridor drive sub-100-millisecond latency requirements.
India
CDSCO compliance requirements and PLI scheme incentives accelerate greenfield pharmaceutical facility construction. Cloud-native OEE anchors digital-first architectures without legacy protocol debt. The Maharashtra pharmaceutical cluster and Gujarat chemical corridor concentrate new procurement.
South Korea
Semiconductor fabricators mandate unified MES-OEE-ERP data layers for advanced node wafer traceability. MFDS electronic record requirements align with FDA and EMA standards for multi-site validation. The Seoul capital area and Busan-Ulsan industrial corridor anchor high-volume deployment specifications.
Global OEE Software Market Competitive Landscape
Capability concentration sits with specialized automation vendors; scale advantage sits with diversified industrial conglomerates. The vendor base organizes around three strategic archetypes: native control system providers, enterprise software integrators, and edge-native specialists. Dominant competitive moves include cloud-to-edge integration partnerships and sovereign cloud certification investments.
Among Germany-based industrial conglomerates, Siemens AG anchors cloud-to-edge integration offerings through native manufacturing relationships. ABB Ltd. exemplifies robotics-linked performance analytics specialization for automotive production lines. Rockwell Automation Inc. occupies a position extending North American channel control into European pharmaceutical facilities with modular deployment architectures.
| Leading Market Players |
|---|
| Rockwell Automation Inc. |
| ABB Ltd. |
| Siemens AG |
| SAP SE |
| Oracle Corporation |
| Honeywell International Inc. |
| General Electric Company |
| Litmus Automation |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud infrastructure across Germany and the United States compresses SaaS margins while edge hardware shortages in Taiwan tighten on-premise deployment costs, creating divergent pricing trajectories across deployment architectures.
Pricing Analysis
Geographic price spreads of 40-60 percent separate German pharmaceutical installations from Brazilian food and beverage deployments, reflecting sovereign cloud certification premiums and GDPR compliance engineering costs. Pricing stratifies across premium certified tiers, mid-market SaaS bundles, and economy self-serve modules, with certification level and customization depth as primary differentiation drivers. Cost compression in the mid-market tier intensifies as hyperscaler partnerships reduce infrastructure overhead. Food and beverage processors in Brazil exhibit highest price sensitivity, while semiconductor fabricators in Taiwan accept premium positioning for wafer traceability integration.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing risk for edge gateway hardware, forcing dual-sourcing strategies across Taiwan and South Korean fabrication facilities. Supply concentration centers on Germany for industrial automation software engineering, the United States for cloud infrastructure, and Taiwan for semiconductor-dependent edge devices. Raw material dependencies span silicon wafers, industrial-grade memory modules, and specialized enclosure materials for washdown environments. Single-source vulnerability in EU sovereign cloud certification bodies creates procurement bottlenecks for multi-site pharmaceutical deployments. Distribution runs through direct enterprise sales teams for large automotive OEMs, with systems integrators and channel partners serving mid-market food and beverage processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to automotive capital expenditure cycles, with German OEM tool replacement schedules signaling the current upswing phase.
For Market Incumbents: Pre-empt margin erosion in the mid-market SaaS tier by deepening sovereign cloud certification portfolios before EU AI Act enforcement hardens procurement filters. Anchor defensive positioning through exclusive partnerships with German BSI auditors and Japanese METI framework consultants, while adding edge-native engineering capacity in Taiwan to compress latency specifications below 100 milliseconds. For New Entrants and Emerging Players: Establish a beachhead in India's greenfield pharmaceutical corridor where CDSCO compliance requirements and PLI incentives create vendor-agnostic procurement windows. Target cloud-native predictive analytics modules for mid-tier contract manufacturers in Vietnam and Mexico, bypassing entrenched MES incumbents through API-first integration architectures and rapid deployment guarantees. For Investors and Strategic Acquirers: Capital is best deployed toward edge-native specialists with existing IEC 62443 security certifications and proven automotive press shop deployments, as these capabilities face supply scarcity across the analysis window. Long-term viability favors platforms with dual-stack engineering—sovereign cloud compliance plus sub-100-millisecond edge execution—rather than pure-play SaaS vendors. Watch for inflection in automotive OEM RFP volumes as the signal for cyclical peak positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | BSI IT-Grundschutz and GDPR compliance unlock German pharmaceutical procurement pipelines. |
| Edge-Native Platform Development | Sub-100-millisecond latency modules capture automotive emergency stop integration specifications. |
| Predictive Analytics Module Launch | Machine-learning quality deviation tools address EU AI Act algorithmic transparency mandates. |
| Strategic Partnership with Systems Integrators | Channel control in Brazil and India accelerates mid-market food and beverage penetration. |
| Acquisition of Computer Vision Specialist | Defect detection integration creates bundled subscription revenue in automotive stamping lines. |
Research Methodology
A spread of perspectives from plant engineers at automotive OEMs, pharmaceutical manufacturing IT directors, semiconductor fab operations managers, and food and beverage maintenance heads converged on the working assumptions, supplemented by secondary validation against SEC 10-K filings, EMA regulatory guidance documents, EU AI Act implementation texts, and hyperscaler cloud infrastructure disclosures. Bottom-up deployment counts triangulated against top-down software spending estimates across the modeled segments.
Demand-supply-balance framing anchored the analytical framework, with capacity utilization in German automotive press shops and Taiwan semiconductor cleanrooms serving as near-term demand proxies across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, integration depth, and regional regulatory cluster. CAGRs derived from slope-consensus methodology incorporating capital expenditure cycle phasing and compliance mandate implementation timelines. Industry-specific inputs encompassed OPC UA protocol adoption rates and sovereign cloud provider certification velocity.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor capital expenditure cycles, or pharmaceutical facility construction rates would shift the trajectory. Forecasts reflect documented assumptions regarding EU AI Act enforcement timing and edge hardware cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Gym Motion Tracking Software Market
Software & Services
Stock Footage Software Market
Software & Services
Global Automotive Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
Desktop Hypervisor Market
Software & Services
Construction Simulation Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
File Analysis Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Office Productivity Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
ID Photo Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Mobile Application Development Platform (MADP) Market