
 Ground Handling Software Market | 2026-2036
Ground Handling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Handling Software Market Analysis
Airport technology procurement channels is reconfiguring around SaaS subscription models and direct vendor partnerships, bypassing legacy systems integrators. Sita leverages its IATA-aligned messaging standards to dominate inter-airline data exchange. Amadeus IT Group anchors its position through deep integration with airline reservation systems. Sabre competes by extending its software stack into ground operations from its historical strength in passenger service systems.
Ground handling software comprises modular digital platforms that coordinate aircraft turnaround, passenger processing, baggage flow, and resource allocation through real-time data synchronization across airport stakeholders. These systems typically operate on sub-second update cycles to ensure gate assignments, fuel loads, and crew rotations remain synchronized during narrow turnaround windows. Baggage tracking solutions lead in deployment velocity as IATA Resolution 753 compliance deadlines harden accountability requirements. Cloud-based deployment is accelerating fastest among mid-tier airports seeking to avoid capital-intensive on-premise infrastructure. Resource management tools occupy the deepest margin pools due to their complexity in optimizing labor, equipment, and gate assets simultaneously.
FAA operational safety directives and IATA operational safety audits shape software certification requirements for US-based deployments, while the EU Green Deal's emissions reporting frameworks mandate granular data capture during ground operations. The UK's CAA maintains distinct slot coordination rules that influence software configuration for London Heathrow and Gatwick operations. Stakeholders must monitor how emerging AI-driven predictive maintenance modules reshape procurement criteria before standards consolidate.
Market Dynamics
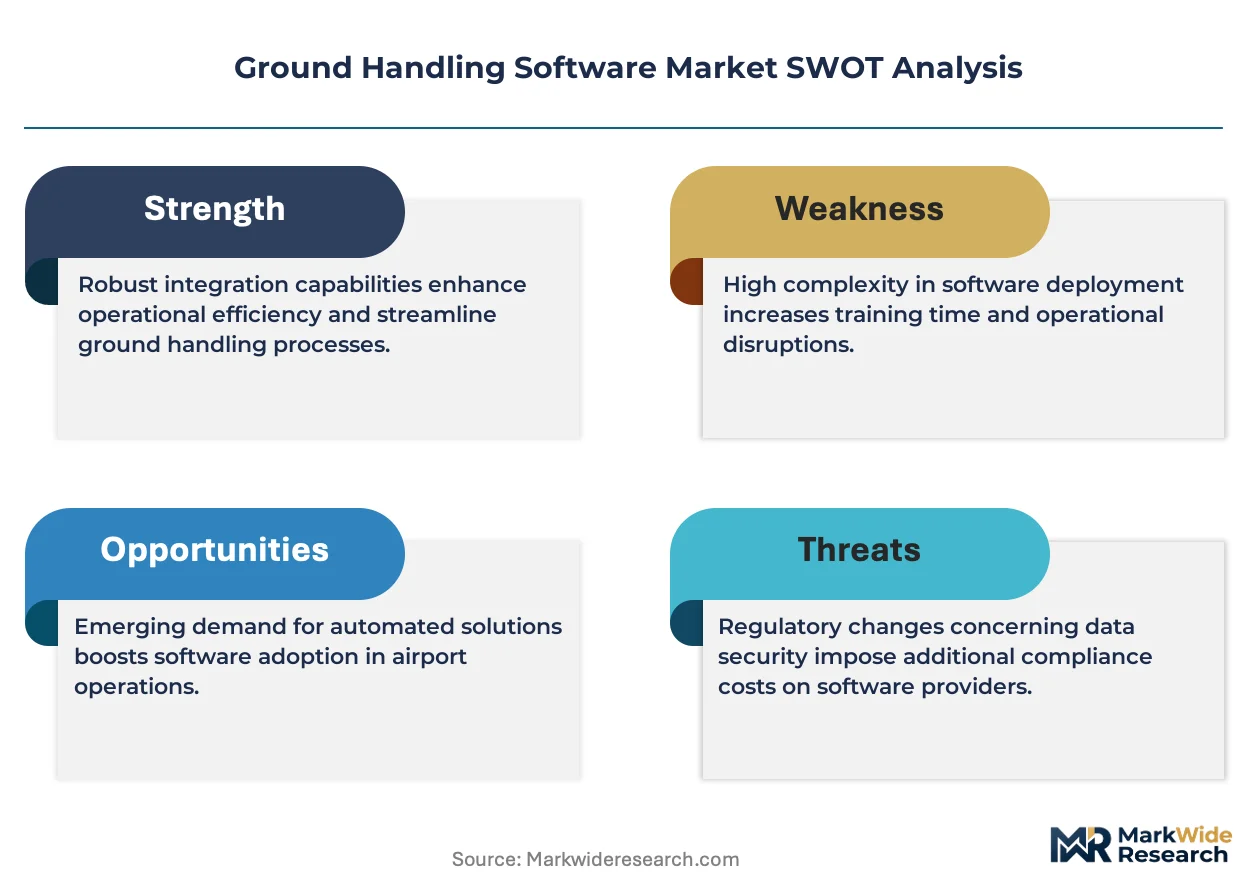
Airlines are consolidating ground operations under unified digital command centers, forcing software vendors to integrate baggage, fuel, and crew modules into single-pane platforms rather than selling point solutions.
Growth Catalysts
- IATA Resolution 753:Airlines must demonstrate end-to-end baggage tracking accountability, accelerating investment in reconciliation platforms that tag and trace every checked item through hub transfers.
- EU Green Deal emissions mandates:Ground handlers in Frankfurt, Amsterdam, and Paris must digitize turnaround processes to capture real-time carbon data for regulatory reporting.
- Hub-and-spoke network densification:Major carriers are adding spokes to existing hubs, multiplying the node count requiring synchronized ground handling software licenses.
Market Restraints
- Legacy system entrenchment:Decades-old mainframe architectures at tier-one airports create integration friction that slows cloud migration timelines and inflates customization costs.
- Specialized labor scarcity:Airports in secondary German cities face shortages of technicians certified to maintain both aviation-grade hardware and modern API gateways.
- Cybersecurity compliance layering:Each national aviation authority imposes distinct data sovereignty rules, fragmenting vendor development roadmaps and raising certification overhead.
Strategic Opportunities
- Predictive maintenance convergence:Ground handlers can combine IoT sensor streams with AI models to anticipate equipment failures before they delay turnarounds.
- Mid-tier airport cloud bypass:SaaS deployment models allow airports in Spain and Italy to access enterprise-grade resource optimization without capital-intensive server farms.
- Carbon offset verification services:Software vendors can monetize emissions data by selling audit-ready reporting modules to handlers seeking green financing.
Industry Challenges
- API standardization delays:Proprietary data formats between airline reservation systems and ground handling platforms force expensive middleware development.
- Real-time synchronization tolerance:Sub-second update requirements for gate reassignments during weather disruptions strain legacy network infrastructure.
Report Scope
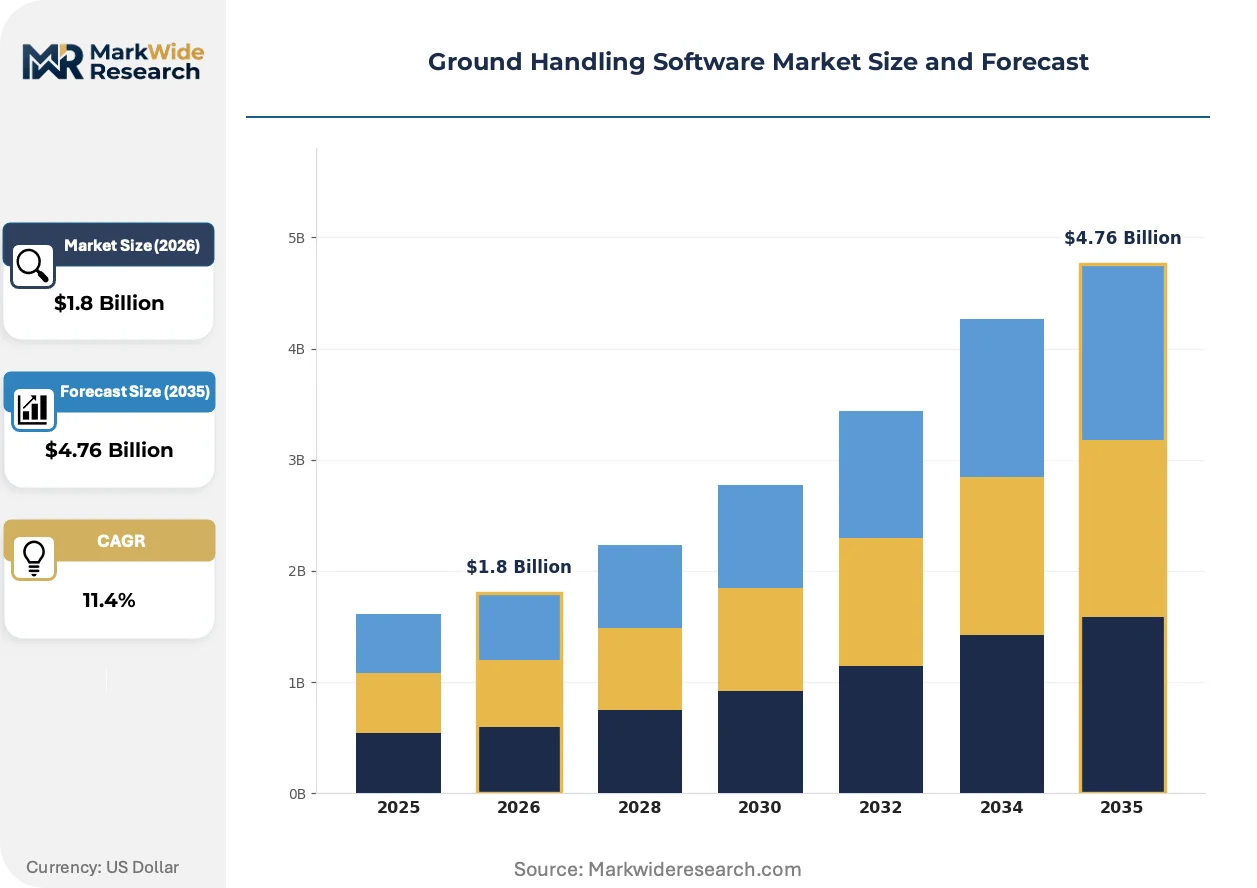
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Handling Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Status Systems, Resource Management Tools, Baggage Tracking Solutions, Check-in Software Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solutions End User: Airlines, Ground Handlers, Airports, Service Providers Technology: Artificial Intelligence, Internet of Things, Machine Learning, Blockchain |
| Companies Covered | Sita, Topsystem, Rockwell Collins, Inform, Arepo Solutions, Sabre, Damarel Systems International, Resa Airport Data Systems, Amadeus IT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Handling Software Market Emerging Trajectories
Digital twin architectures are displacing static scheduling tools across European hub airports, creating dynamic simulations that preemptively reroute baggage flows before congestion forms.
Digital twin technology is virtualizing physical airport operations into software replicas that mirror every conveyor, tug, and gate in real time. Frankfurt Airport's operations team uses these models to stress-test turnaround scenarios before peak summer schedules deploy. The technology is virtualizing capital planning decisions, allowing handlers to justify equipment purchases through simulated ROI rather than historical averages.
EU Green Deal reporting frameworks now require granular emissions capture during every ground operation phase, from auxiliary power unit connection to pushback. Handlers must install metering hardware and software modules that timestamp fuel burn and electricity draw against specific flight records. German ground handlers face the tightest compliance windows, with Frankfurt and Munich airports already mandating real-time data feeds to port authority dashboards.
Airlines are consolidating vendor relationships, awarding multi-year ground handling software contracts to single platforms rather than assembling best-of-breed modules. Lufthansa and Air France-KLM have both moved to unified procurement frameworks that bundle baggage, resource, and passenger processing under one vendor. This concentration is most visible in Central Europe, where hub carriers wield sufficient volume to dictate integration roadmaps to their software suppliers.
Ground Handling Software Market Segmentation
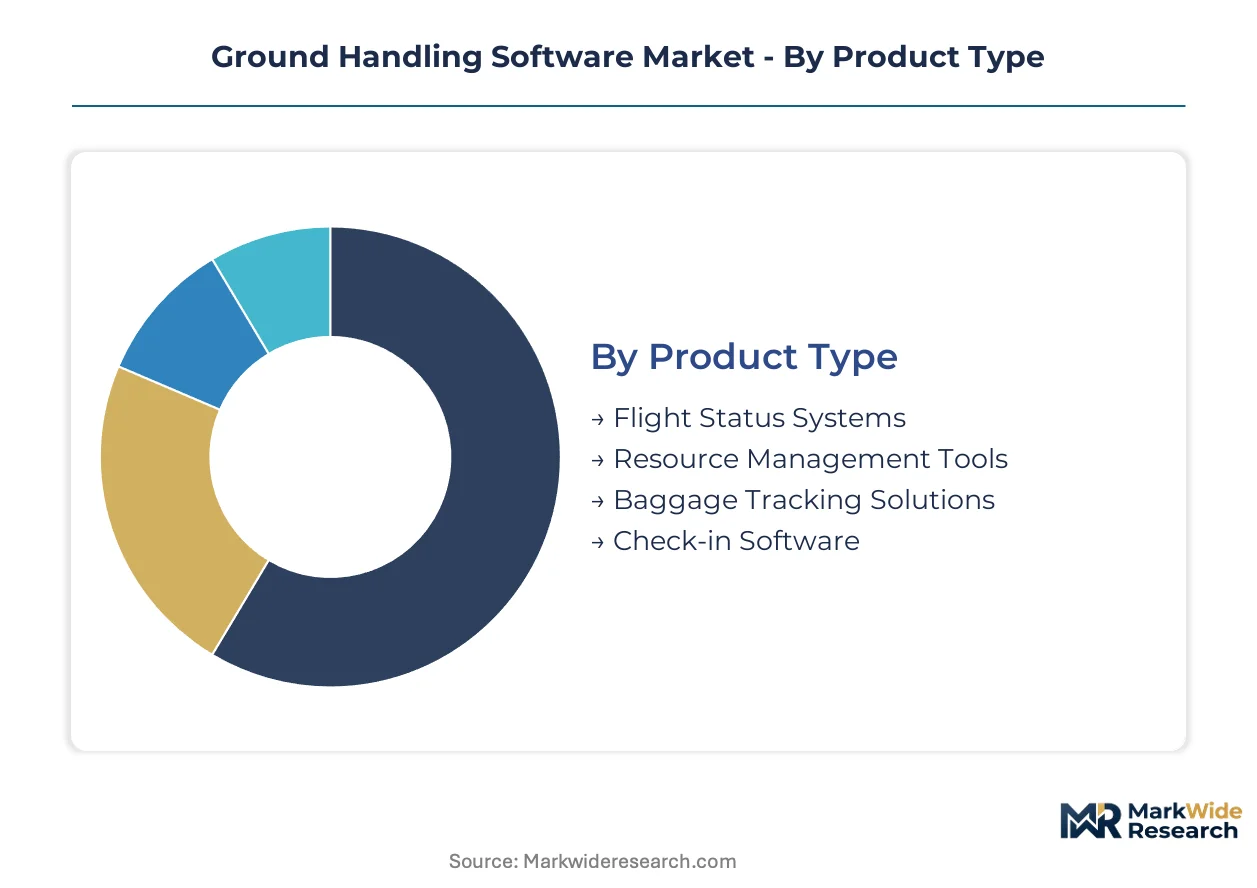
Ground handling software procurement varies sharply across deployment modes and user types, with after-sales service intensity highest in mission-critical baggage tracking and resource optimization modules where downtime costs exceed hardware replacement values. Vendors structure maintenance contracts around update frequency, regulatory recertification, and 24/7 support tiers that scale with airport throughput.
Product Type:
After-sales service intensity peaks in modules requiring continuous calibration against shifting aviation authority mandates and real-time integration with airline operational databases.
- Baggage Tracking Solutions:These platforms encode IATA Resolution 753 compliance into scan-point logic across conveyor networks and tarmac handoffs. Frankfurt Airport's handlers deploy these systems most densely, driven by EU Green Deal mandates requiring timestamped accountability for every checked item through hub transfers.
- Resource Management Tools:Optimization engines synchronize gate assignments, fueling schedules, and crew rotations through sub-second recalculation loops. German ground handlers at Munich and Hamburg airports concentrate procurement here, constrained by specialized technician scarcity that elevates vendor dependency for algorithm tuning.
- Flight Status Systems:Real-time departure and arrival dashboards feeding passenger-facing displays and operational command centers.
- Check-in Software:Passenger processing modules integrating with airline reservation systems for document verification and seat allocation.
By volume, Resource Management Tools leads. By growth pace, Baggage Tracking Solutions is climbing the fastest.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from subscription-based cloud access that mid-tier airports favor for budget predictability.
- Cloud-Based:SaaS delivery eliminates server infrastructure ownership, with Spanish and Italian airports adopting fastest to bypass hardware capital expenditure. EU data sovereignty rules fragment vendor roadmaps, forcing region-specific hosting certifications that inflate service pricing.
- Hybrid:Split architectures retain sensitive passenger data locally while pushing analytics workloads to remote servers. German airports prefer this model to satisfy federal data protection requirements without sacrificing computational scale.
- On-Premise:Fully captive installations at tier-one hubs with decades-old mainframe entrenchment.
- Mobile Solutions:Tablet and handheld applications for ramp agents and baggage handlers requiring tarmac mobility.
By installed base, On-Premise dominates legacy hubs. By expansion trajectory, Cloud-Based is gaining share fastest.
End User:
Application focus diverges between carriers optimizing network-wide consistency and airports prioritizing multi-tenant flexibility across competing ground handlers.
- Airlines:Hub-and-spoke carriers like Lufthansa and Air France-KLM consolidate procurement under unified digital command centers, bundling baggage, fuel, and crew modules to reduce vendor fragmentation. IATA Resolution 753 deadlines harden their baggage tracking investment timelines.
- Ground Handlers:Independent service providers such as those operating at Frankfurt and Amsterdam face EU Green Deal emissions reporting mandates that require real-time carbon capture software during every turnaround phase.
- Airports:Infrastructure owners licensing platform access to multiple ground handling tenants.
- Service Providers:Specialized contractors for fueling, catering, or cleaning seeking API integration with core turnaround platforms.
By contract value, Airlines leads. By procurement velocity, Ground Handlers is expanding most quickly.
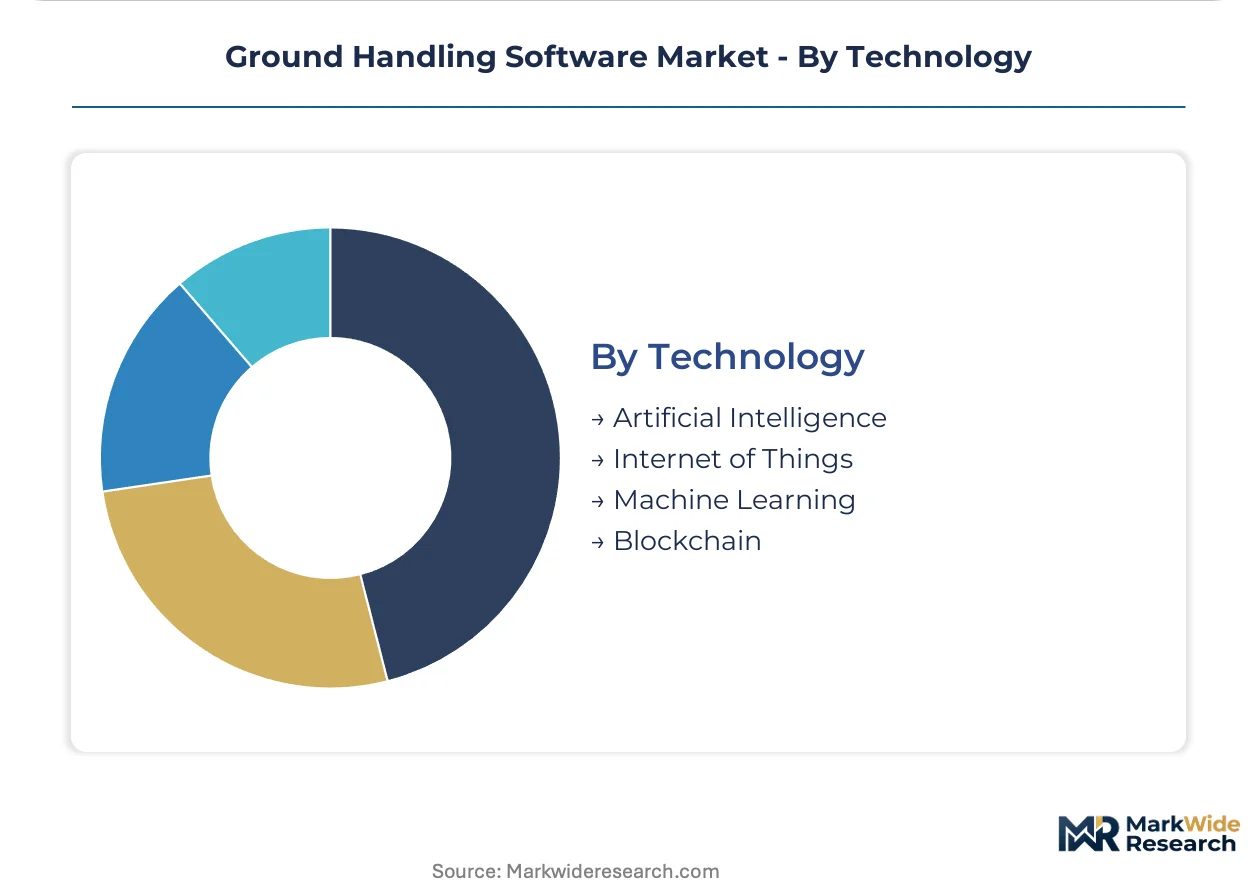
Technology:
Maturity gradients separate proven sensor networks from emerging AI architectures that lack standardized certification pathways for safety-critical aviation deployments.
- Internet of Things:Sensor networks on baggage carts, fuel trucks, and ground power units stream positional and operational data into centralized platforms. Frankfurt Airport's digital twin deployment relies on this foundation for real-time equipment tracking and predictive congestion modeling.
- Artificial Intelligence:Neural networks anticipate equipment failures and optimize turnaround sequencing, though FAA and EASA certification timelines lag technical capability. German handlers pilot these systems most aggressively within constrained trial frameworks.
- Machine Learning:Statistical models refining resource allocation based on historical flight patterns and weather disruptions.
- Blockchain:Distributed ledger architectures for baggage custody documentation and carbon credit verification.
By deployment scale, Internet of Things leads. By investment growth, Artificial Intelligence shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA operational safety directives and EU Green Deal emissions frameworks create divergent compliance pathways across major aviation hubs. Software procurement concentrates where regulatory pressure intersects with hub-and-spoke network density.
United States
FAA mandates for operational safety audits drive certification requirements for ground handling software deployments at major hubs. Airlines operating at Dallas-Fort Worth and Atlanta Hartsfield-Jackson invest heavily in baggage reconciliation platforms to meet IATA Resolution 753 timelines. Cloud migration accelerates fastest among mid-tier carriers seeking to bypass legacy mainframe infrastructure.
Germany
EU Green Deal emissions monitoring mandates push Frankfurt and Munich airports toward real-time carbon tracking digitization. The KBA influences aviation data protection standards that shape hybrid cloud adoption patterns. Ground handlers in Bavaria face specialized technician scarcity that elevates vendor dependency for system maintenance.
United Kingdom
CAA slot coordination rules at London Heathrow and Gatwick require software configurations that differ from continental European standards. British Airways and Virgin Atlantic consolidate procurement under unified digital command centers. The UK's departure from EU regulatory frameworks creates parallel certification tracks for vendors serving both markets.
France
Air France-KLM's unified procurement framework bundles baggage, resource, and passenger processing under single-vendor contracts. EU Green Deal reporting requirements mandate granular emissions capture during every turnaround phase at Paris Charles de Gaulle. The ANSM oversees data sovereignty compliance for passenger processing modules.
Spain
Mid-tier airports in Barcelona and Madrid adopt SaaS deployment models to avoid capital-intensive server infrastructure. Iberia's hub operations drive demand for cloud-based resource optimization tools. Spanish ground handlers prioritize subscription pricing predictability over ownership models.
Ground Handling Software Market Vendor Landscape
Aviation technology specialists and diversified IT conglomerates split the market between domain-specific depth and platform breadth. Consolidation pressure intensifies as airlines demand single-pane integration across baggage, fuel, and crew modules. Three archetypes dominate: IATA-aligned messaging standard bearers, airline reservation system integrators, and ground operations pure-plays. Competitive moves center on strategic partnerships for API standardization and portfolio diversification into predictive maintenance modules.
Within the messaging infrastructure tier, Sita leverages its IATA alignment to anchor inter-airline data exchange positioning. Amadeus IT Group and Sabre exemplify the reservation-system extension archetype, each occupying distinct competitive territory through historical passenger service system strength. These three entities represent the primary competitive anchors shaping vendor consolidation dynamics.
| Leading Market Players |
|---|
| Sita |
| Topsystem |
| Rockwell Collins |
| Inform |
| Arepo Solutions |
| Sabre |
| Damarel Systems International |
| Resa Airport Data Systems |
| Amadeus IT Group |
| Others |
Supply Flow & Price Mechanics
Undercapacity in certified API gateway technicians across Bavaria and Baden-Württemberg compresses vendor pricing power while inflating after-sales contract premiums, forcing buyers toward bundled SaaS tiers that internalize maintenance risk.
Pricing Analysis
Geographic price spreads between Frankfurt hub deployments and Spanish mid-tier airports exceed three-to-one for equivalent resource optimization modules. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and regulatory certification grade, with EU Green Deal compliance modules commanding substantial premiums. Pricing pressure stems from cloud-native entrants undercutting on-premise legacy vendors in the Italian and Iberian markets. Mid-tier airports exhibit highest price sensitivity due to capital constraint, while Lufthansa-scale carriers prioritize switching-cost avoidance over unit economics.
Supply Chain Analysis
Extended payment terms now stretch 90-120 days for hardware-software bundles, with supply-chain finance facilities increasingly underwriting vendor working capital. Germany, the United States, and India concentrate software development capacity, while aviation-grade sensor hardware sources from Taiwan, South Korea, and Japan. Raw material dependencies center on semiconductor components, precision LiDAR units, and ruggedized edge computing modules. Single-source vulnerability in IATA-certified messaging protocol stacks threatens continuity. Distribution runs through direct vendor partnerships with major hub carriers, bypassing legacy systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: IATA messaging standards and FAA certification pathways create switching costs that cement incumbent positions across multi-year contract cycles.
For Market Incumbents: Pre-empt cloud-native disruption by acquiring mid-tier SaaS specialists in Spain and Italy before they scale. Deepen API standardization coalitions with Amadeus and Sabre to raise integration barriers for challengers. Invest in predictive maintenance R&D to capture carbon-offset verification revenue streams before EU Green Deal reporting requirements harden. For New Entrants and Emerging Players: Eastern European ground handling markets present underpenetration ripe for SaaS-first entry, particularly Poland and Czech Republic hubs outside EU Green Deal immediate enforcement zones. Target independent ground handlers at secondary German airports facing technician scarcity and vendor dependency fatigue. Lead with mobile-first deployment models that bypass capital-intensive infrastructure requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment segments, compressing traditional hardware-software margin profiles. Acquisition targets should exhibit IATA Resolution 753 compliance modules and established airline API integrations. Watch for AI-driven predictive maintenance certification breakthroughs as inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies baggage, fuel, and crew modules under single-vendor contracts at Lufthansa-scale carriers. |
| Strategic Partnership | API standardization coalitions with IATA-aligned messaging vendors reduce middleware development friction. |
| Acquisition of Specialist Firm | Mid-tier SaaS providers in Spain and Italy offer cloud-native entry points for hub market expansion. |
| Product Launch | Carbon offset verification modules monetize EU Green Deal emissions data for green financing access. |
| Geographic Expansion | Eastern European hub development outside immediate EU Green Deal enforcement creates first-mover positioning. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ground handling operations directors, airline IT procurement officers, airport technology managers, and aviation authority certification leads; and secondary validation against IATA operational safety audit documentation, FAA airworthiness directives, EU Green Deal implementation guidance, SEC filings from listed aviation technology vendors, and customs records for aviation-grade sensor hardware imports. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Forecast inputs considered deployment model migration curves, regulatory compliance deadline clustering, and hub-and-spoke network densification patterns across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user category, and technology maturity tier. CAGRs derived from logistic diffusion curves fitted to historical adoption rates in analogous aviation digitization markets, with IATA Resolution 753 compliance timelines and EU Green Deal enforcement phasing as primary demand-shaping variables.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by reservation-system integrators would shift outcomes. Macroeconomic contraction in air travel demand, accelerated AI certification pathways by EASA, or fragmentation in API standardization coalitions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
North America Deck Design Software Market
Software & Services
Feedback Management Software Market
Software & Services
Online Lottery Software Market
Software & Services
PAC Programming Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Projector Software Market
Software & Services
Global Project Software Market
Software & Services
Spend Analysis Software Market
Software & Services
Indoor Cycling Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Smartphone Music Production Software Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Global Email Management Software Market
Software & Services
Cloud Enterprise Application Software Market