
 Over the Air (OTA) Updates Market | 2026-2036
Over the Air (OTA) Updates Market Size, Share, and Industry Trends Forecast 2026-2036
Over the Air (OTA) Updates Market Insights
OTA update infrastructure across Tier 1 automotive electronics suppliers is consolidating as vehicle architectures shift to zonal computing and centralized gateways. Robert Bosch GmbH leverages its embedded software stack to anchor European OEM programs, while HARMAN International sustains dominance in infotainment subsystem updates through its Samsung-backed connectivity platform. Qualcomm Technologies, Inc. competes aggressively by integrating modem and compute silicon with over-the-air orchestration layers.
Over the Air updates deliver software payloads to embedded systems without physical service intervention, typically employing differential compression algorithms and cryptographic verification chains to minimize bandwidth and prevent tampering. The primary commercial purpose is maintaining functional safety, cybersecurity posture, and feature currency across distributed device fleets. Cloud-based deployment architectures lead solution delivery for automotive OEMs given their elasticity and centralized fleet management capabilities, while edge computing variants grow fastest in telematics where latency-sensitive cabin functions require localized staging. Firmware updates occupy the largest solution share due to regulatory-mandated safety patches, though feature enhancement modules capture expanding margin pools as automakers monetize software-defined vehicle capabilities.
UNECE WP.29 regulations, the EU Cyber Resilience Act, and China's MIIT vehicle cybersecurity standards collectively mandate type-approved update mechanisms, reshaping supplier certification requirements and OEM procurement criteria. The FDA's evolving guidance on connected medical devices and FCC spectrum allocations for automotive cellular links further constrain technology choices and market access pathways. Stakeholders must monitor regulatory divergence between cybersecurity certification regimes and spectrum harmonization timelines to align platform investments with enforceable compliance deadlines.
Market Dynamics
Zonal vehicle architectures and centralized gateway consolidation are compressing supplier hierarchies, forcing Tier 1 electronics vendors to bundle OTA orchestration layers with compute silicon or risk disintermediation by vertically integrated OEM programs.
Growth Catalysts
- UNECE WP.29 cybersecurity mandates:European type-approval requirements for software update mechanisms are compelling OEMs to retrofit legacy fleets and standardize update protocols across model lines.
- Connected medical devices:FDA evolving guidance on embedded system patchability is extending OTA infrastructure from automotive into diagnostic equipment and therapeutic hardware.
- Germany:Telematics infrastructure density and premium automotive manufacturing concentration create concentrated demand for differential compression and cryptographic verification toolchains.
Market Restraints
- Cellular bandwidth costs:Differential payload compression reduces data volumes but cellular subscription fees for fleet-wide deployments strain operational budgets in price-sensitive segments.
- Semiconductor supply concentration:Modem and gateway silicon sourcing from concentrated East Asian foundries creates vulnerability for OTA platform vendors building integrated hardware-software stacks.
- Regulatory fragmentation:Divergent certification timelines between UNECE WP.29, China's MIIT standards, and US NHTSA guidance force redundant engineering cycles and delay platform standardization.
Strategic Opportunities
- Edge computing staging:Latency-sensitive cabin functions in luxury vehicles are driving localized update staging before cloud propagation, creating service revenue pools for telematics infrastructure providers.
- Software-defined vehicle monetization:Feature enhancement modules unlock recurring revenue streams as automakers unbundle functionality from hardware release cycles.
- EU Cyber Resilience Act:Broad embedded device cybersecurity mandates beyond automotive are expanding addressable market for OTA platform vendors into industrial automation and smart infrastructure.
Industry Challenges
- Cryptographic engineering talent scarcity:End-to-end verification chain design and secure boot implementation require specialized firmware security expertise that outpaces graduate pipeline output.
- Legacy fleet integration:Pre-2020 vehicle architectures with distributed ECUs lack centralized gateway capacity, forcing expensive hardware retrofits or exclusion from full feature update paths.
- Cross-certification timelines:Simultaneous type-approval across UNECE, MIIT, and NHTSA regimes extends product launch windows and defers revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over the Air (OTA) Updates Market |
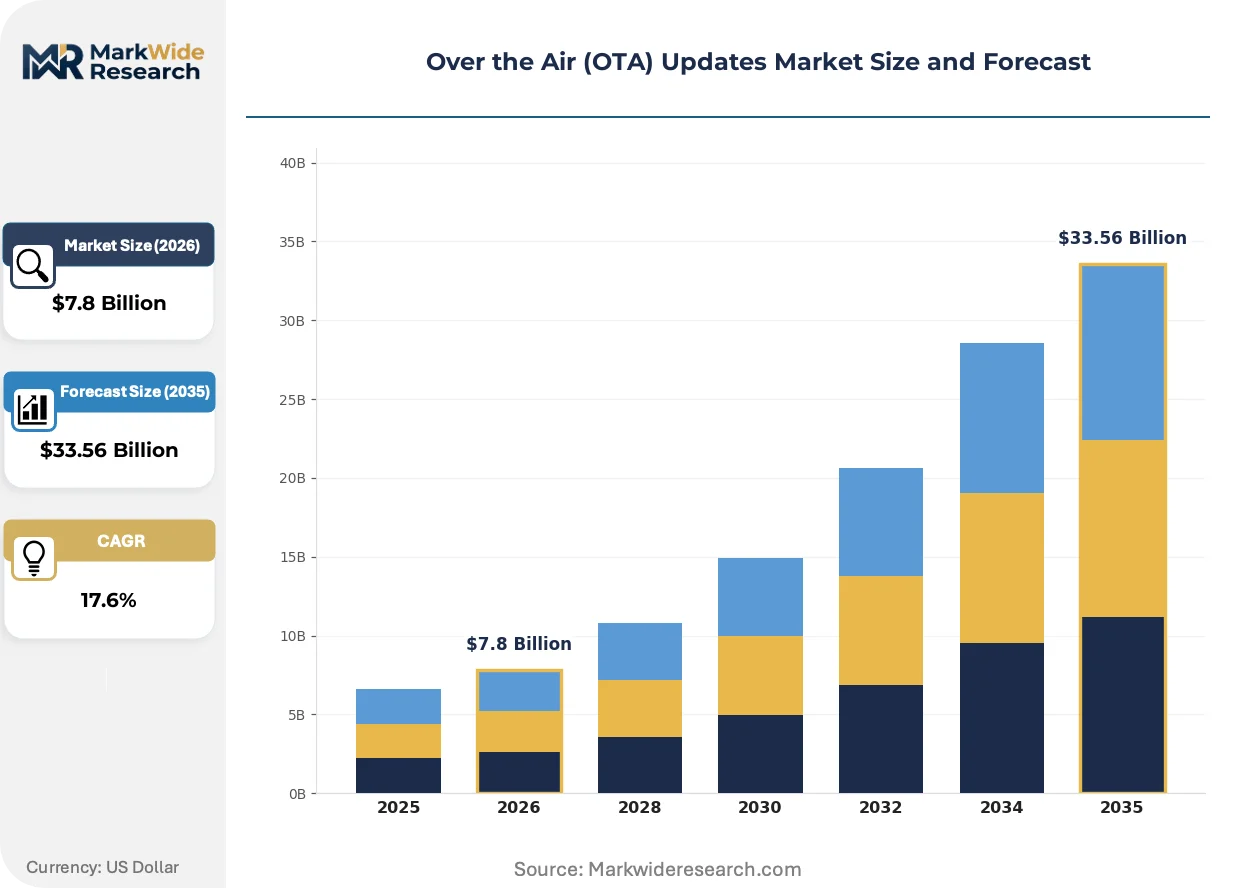
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, Edge Computing, Hybrid, On-premises End User: Automotive OEMs, Consumer Electronics, Healthcare Providers, Telecommunication Firms Solution: Firmware Updates, Security Patches, Feature Enhancements, Configuration Changes Technology: Wi-Fi, Cellular, Bluetooth, Satellite |
| Companies Covered | Robert Bosch GmbH, Continental AG, HARMAN International, Garmin Ltd, Qualcomm Technologies, Inc., NXP Semiconductors N.V., Airbiquity Inc, Verizon Communications Inc., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over the Air (OTA) Updates Market Trends and Innovations
OTA update architectures are bifurcating between cloud-native orchestration for fleet management and edge-staged deployment for latency-critical functions, with differential compression algorithms and hardware-rooted trust anchors emerging as the critical differentiating layers.
Differential compression with cryptographic signing is electrifying bandwidth economics for automotive firmware distribution. European premium OEMs are mandating this toolchain for all safety-critical updates. The technology is compressing data costs and enabling over-the-air recall resolution without dealer network burden.
EU Cyber Resilience Act implementation timelines are forcing embedded device manufacturers to pre-certify update mechanisms before market entry. Industrial automation and medical device vendors face compressed compliance windows. German automotive suppliers are responding by integrating UNECE-compliant verification chains into non-automotive product lines.
Automotive procurement is consolidating vendor relationships around full-stack OTA platform providers capable of silicon, gateway software, and cloud orchestration. Tier 1 electronics suppliers with fragmented point solutions are losing position to integrated competitors. This concentration is most visible in US and German OEM programs where zonal architecture timelines demand unified accountability.
Over the Air (OTA) Updates Market Segmentation
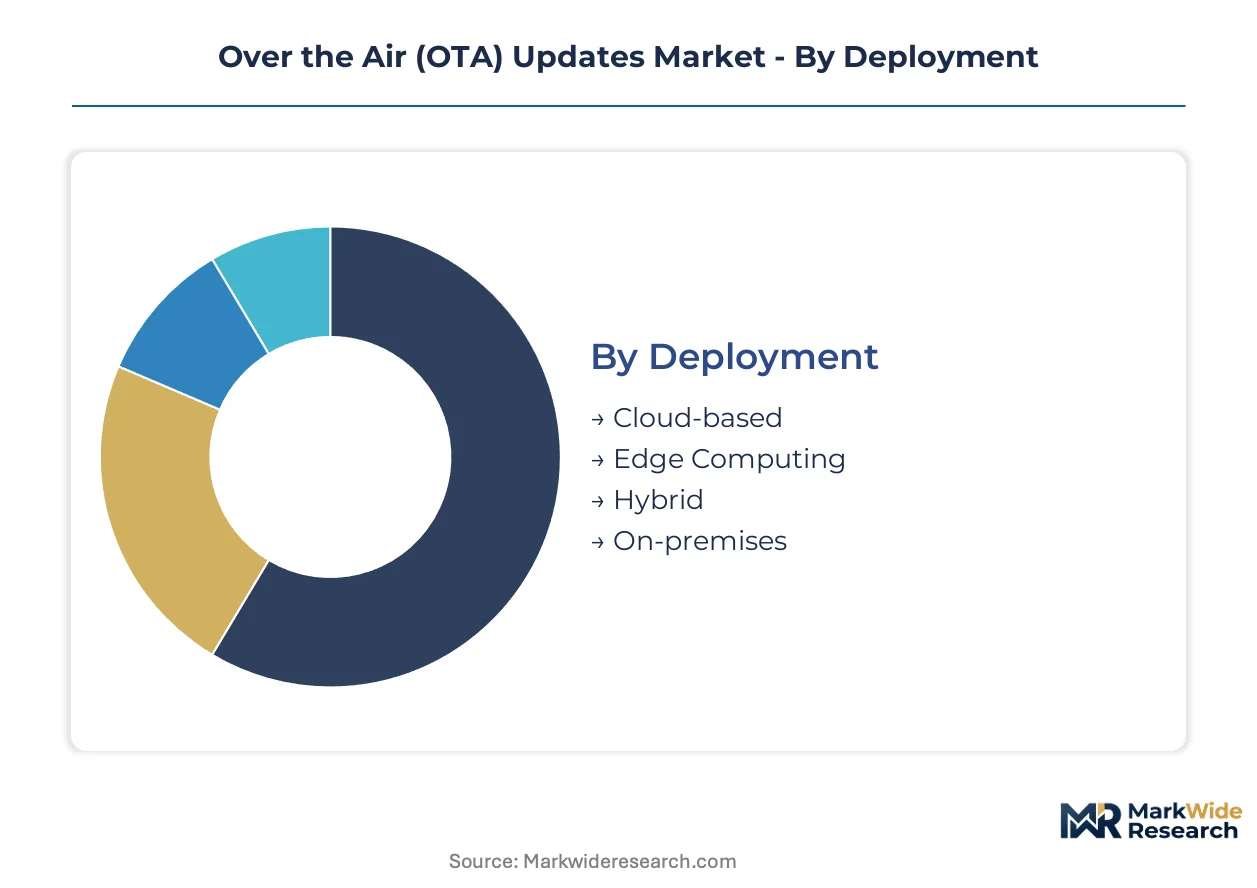
OTA update architectures fragment across deployment models, end-user verticals, solution types, and connectivity technologies. Each dimension carries distinct margin profiles, certification requirements, and infrastructure dependencies that reshape vendor positioning.
Deployment:
Customization intensity varies from fully managed cloud stacks to captive on-premises installations, with hybrid architectures occupying the middle ground.
- Cloud-based:Centralized orchestration platforms leverage elastic compute and storage for fleet-wide update campaigns. Automotive OEMs in Germany and the United States concentrate procurement here due to scalability demands and UNECE WP.29 audit trail requirements.
- Edge Computing:Localized staging servers cache payloads before vehicle-side delivery, cutting latency for cabin function updates. Luxury automotive programs and telematics infrastructure providers in China are expanding deployment fastest.
- Hybrid:Combines cloud fleet management with edge payload distribution for bandwidth optimization. Industrial automation vendors favor this model where intermittent connectivity demands local resilience.
- On-premises:Captive data center installations serving defense and critical infrastructure operators with air-gapped security postures. Healthcare providers with FDA-connected device portfolios specify this architecture for audit control.
Leading the category by volume: Cloud-based. Expanding most quickly: Edge Computing.
End User:
Procurement sophistication escalates from consumer electronics through regulated medical devices, with automotive OEMs setting the technical benchmark.
- Automotive OEMs:Fleet-scale software deployment with zonal architecture integration and type-approved verification chains. UNECE WP.29, MIIT, and NHTSA compliance mandates dominate vendor selection criteria.
- Consumer Electronics:High-frequency incremental updates for smartphones, wearables, and home devices. Volume concentration in China and South Korea drives cost-per-update optimization.
- Healthcare Providers:FDA-guided patchability for diagnostic and therapeutic hardware. Procurement prioritizes cryptographic provenance and rollback capabilities over speed.
- Telecommunication Firms:Network equipment and customer premise device management with carrier-grade reliability requirements. Infrastructure vendors bundle OTA with managed services.
Capturing dominant share: Automotive OEMs. Steepest expansion trajectory: Healthcare Providers.
Solution:
Margin pools stratify from mandatory safety compliance through discretionary feature monetization.
- Firmware Updates:Low-level embedded system patches for microcontrollers and powertrain controllers. Regulatory-mandated safety fixes in Europe and China create baseline demand.
- Security Patches:Cryptographically signed vulnerability remediation with rollback protection. EU Cyber Resilience Act and FDA guidance are extending addressable market beyond automotive.
- Feature Enhancements:Software-defined vehicle capability unlocks and infotainment upgrades. German premium OEMs monetize these through subscription tiers.
- Configuration Changes:Parameter updates for vehicle dynamics, charging profiles, and user preferences. Telematics providers deliver these as over-the-top services.
Highest volume segment: Firmware Updates. Fastest margin expansion: Feature Enhancements.
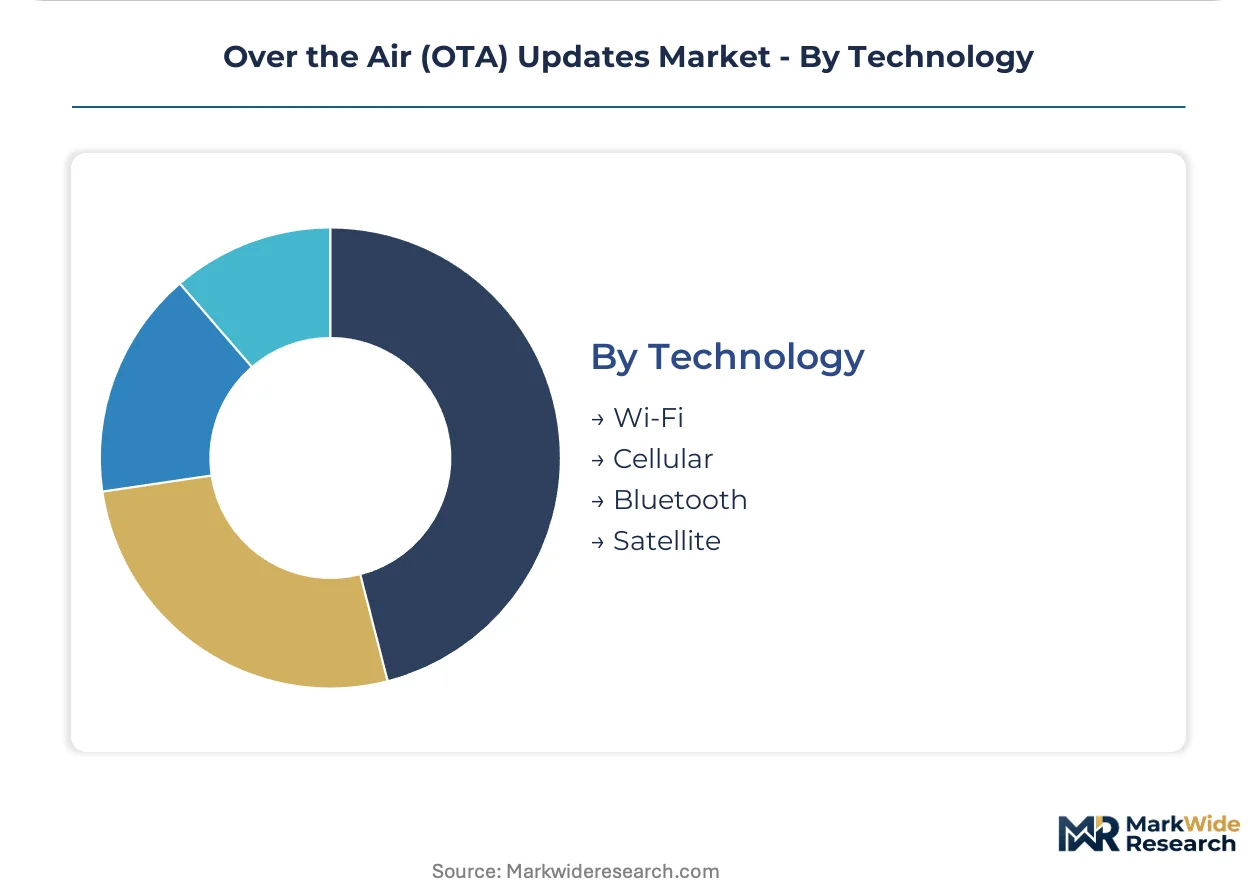
Technology:
Connectivity choice trades bandwidth economics against coverage reliability and spectrum licensing cost.
- Cellular:LTE and 5G modem-based delivery with carrier subscription models. Automotive programs in Germany, the United States, and China standardize on this for ubiquitous coverage.
- Wi-Fi:High-throughput local delivery for infotainment payloads and home-based device updates. Consumer electronics and residential IoT deployments concentrate here.
- Bluetooth:Low-energy proximity transfer for wearables and peripheral pairing. Limited to small payload scenarios with intermittent connectivity.
- Satellite:Global coverage for maritime, aerospace, and remote fleet applications. Premium automotive and defense programs absorb higher per-bit costs for connectivity assurance.
Dominant by deployment scale: Cellular. Gaining share fastest: Satellite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in Germany, the United States, and China anchor OTA infrastructure deployment. These three markets concentrate modem silicon sourcing, gateway manufacturing, and cloud orchestration platform development.
Germany
Automotive OEM demand for differential compression and cryptographic verification toolchains concentrates around Stuttgart and Munich manufacturing corridors. UNECE WP.29 type-approval requirements compel standardized update protocols across premium vehicle fleets. Bosch and Continental anchor European supplier hierarchies with integrated hardware-software stacks.
United States
FDA evolving guidance on connected medical devices extends OTA patchability requirements into diagnostic equipment and therapeutic hardware beyond automotive. FCC spectrum allocations for automotive cellular links constrain technology choices for domestic deployment. Silicon Valley and Detroit corridors host competing cloud-native and edge-staging platform development.
China
MIIT vehicle cybersecurity standards mandate type-approved update mechanisms for domestic OEM programs and imported vehicle fleets alike. Yangtze River Delta and Pearl River Delta clusters concentrate telematics infrastructure manufacturing and 5G modem integration. HARMAN International sustains infotainment subsystem dominance through Samsung-backed connectivity platforms serving both export and domestic markets.
Japan
METI industrial policy prioritizes embedded system security for automotive and factory automation convergence. JIS standards alignment with UNECE frameworks facilitates export-oriented supplier certification. Kanto and Kansai manufacturing belts host Tier 1 electronics vendors bundling OTA orchestration with zonal gateway silicon.
South Korea
Seoul Capital Area semiconductor foundries supply modem and gateway silicon for integrated OTA hardware-software stacks. MFDS medical device cybersecurity guidance mirrors FDA patchability trajectories, expanding addressable market for verification chain vendors. Samsung Electronics-backed platforms compete aggressively in infotainment and cabin function update segments.
Over the Air (OTA) Updates Market Competitive Landscape
Global majors compete with regional champions across certification regime alignment and silicon-software integration depth. Market structure tilts toward consolidation as automotive procurement favors full-stack platform providers capable of unified accountability across zonal architectures. Three archetypes dominate: diversified automotive electronics conglomerates with captive software stacks, semiconductor specialists integrating modem-compute silicon with orchestration layers, and connectivity-focused telematics vendors. M&A activity concentrates on cryptographic engineering talent acquisition, while strategic partnerships bridge cloud infrastructure and edge staging capabilities.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify European suppliers bundling embedded software with gateway hardware to defend procurement relationships. HARMAN International occupies a position representing connectivity-centric specialists leveraging Samsung-backed platform scale for infotainment subsystem dominance. Qualcomm Technologies, Inc. anchors the semiconductor-integrated archetype, competing through modem-compute silicon convergence with over-the-air orchestration layers. These three entities collectively illustrate competitive positioning strategies across the certification-driven procurement landscape.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| HARMAN International |
| Garmin Ltd |
| Qualcomm Technologies, Inc. |
| NXP Semiconductors N.V. |
| Airbiquity Inc |
| Verizon Communications Inc. |
| Infineon Technologies AG |
| Others |
Pricing and Supply Chain Analysis
Captive modem silicon integration anchors both supply security and pricing power for OTA platform vendors serving automotive OEMs under UNECE WP.29 mandates. Tier 1 electronics suppliers with in-house semiconductor sourcing command premium positioning against software-only competitors dependent on merchant silicon.
Pricing Analysis
Warranty and service bundling separates full-stack platform providers from point-solution vendors in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from German and Chinese OEMs. Cost compression in the economy tier is intensifying because merchant silicon sourcing exposes vendors to foundry pricing volatility. Fleet-scale automotive OEMs exhibit lowest price sensitivity due to regulatory compliance deadlines, while industrial automation buyers prioritize per-update cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced modem and gateway silicon fabrication. OTA hardware-software stacks draw from concentrated East Asian foundry capacity for 5G modem chipsets, automotive-grade microcontrollers, and secure element components. Tariff exposure on semiconductor imports threatens margin stability for US and European platform vendors. Distribution runs through Tier 1 automotive electronics suppliers who bundle OTA orchestration with zonal gateway hardware for OEM direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryptographic engineering talent scarcity props pricing for verification chain specialists as automotive OEMs race UNECE WP.29 compliance deadlines. Foundry capacity constraints on automotive-grade silicon perpetuate supply-side leverage for integrated platform vendors.
For Market Incumbents: Deepen backward integration into secure element manufacturing to insulate margins from foundry pricing cycles. Consolidate cryptographic engineering talent through targeted acquisition of firmware security boutiques before EU Cyber Resilience Act implementation accelerates competitor hiring. Certification investment in MIIT and NHTSA parallel tracks defends procurement relationships against emerging Chinese platform vendors.
For New Entrants and Emerging Players: The price-point gap between premium full-stack platforms and economy-tier point solutions creates white-space opportunity in healthcare provider segments. Target FDA-connected medical device vendors with standalone security patch offerings before incumbent automotive specialists extend vertically. Telematics infrastructure providers in China represent the most penetrable geography given MIIT standardization timelines and localized staging requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in semiconductor-integrated platform acquisitions by automotive OEMs seeking captive OTA capability. Long-term viability favors vendors with simultaneous UNECE, MIIT, and FDA certification traction across the analysis window. Watch for inflection in cross-certification timeline compression as signal for platform consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | UNECE WP.29 compliance mandates unified update protocols across model lines for German OEMs. |
| Software-Defined Vehicle Investment | Feature enhancement modules unlock recurring revenue streams beyond hardware release cycles. |
| Geographic Manufacturing Footprint | Regional foundry partnerships reduce tariff exposure and secure automotive-grade silicon supply. |
| Strategic Partnership | Cloud infrastructure alliances bridge fleet management scalability with edge staging latency requirements. |
| Acquisition of Specialist Firm | Cryptographic engineering boutiques accelerate secure boot implementation and verification chain design. |
Research Methodology
Document review covered SEC filings from semiconductor and automotive electronics suppliers, complemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and telematics infrastructure providers. Secondary validation drew from UNECE WP.29 regulatory documentation, MIIT vehicle cybersecurity standards, FDA connected device guidance, and vehicle production databases. Bottom-up and top-down triangulation reconciled component-level pricing with fleet-scale deployment forecasts.
Segmentation outputs across deployment models, end-user verticals, solution types, and connectivity technologies informed volume and value projections throughout the forecast period. CAGRs derived from elasticity modeling against cellular bandwidth cost trajectories and regulatory compliance deadline clustering. Vehicle zonal architecture adoption curves and differential compression algorithm penetration served as automotive-specific forecast inputs.
Inputs from regulatory filings and semiconductor foundry disclosures were available through the study window; gaps in OEM proprietary platform development timelines introduce uncertainty bands around adoption curve assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Document Control Software Market
Software & Services
PCB Design Software Market
Software & Services
Global Third-Party Logistics Software Market
Software & Services
Global Application Performance Monitoring (APM) Market
Software & Services
Attendance Tracking Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Global Handyman Software Market
Software & Services
Global Architect Software Market
Software & Services
United States Donation Management Software Market
Software & Services
Global Open API Market
Software & Services
Truck Dispatch Software Market
Software & Services
Dental Practice Management Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Architectural Rendering Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Global Programming Software Market