
 Medical Equipment Repair Software Market | 2026-2036
Medical Equipment Repair Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Equipment Repair Software Market Analytics
Subscription-based leasing for enterprise software licenses is rewriting competitive entry barriers for mid-sized service vendors. Crothall Healthcare leverages its integrated facilities management footprint to bundle repair software with staffing contracts. Hybrent Inc anchors its position through specialized procurement-to-repair workflow automation for ambulatory surgical centers. Accruent eMaint competes by extending computerized maintenance management systems into FDA-compliant medical device tracking.
Medical equipment repair software comprises digital platforms that schedule, document, and audit corrective and preventive maintenance actions on regulated clinical devices, typically integrating work order management with parts inventory and technician certification records. Its primary commercial purpose is ensuring continuous uptime of capital-intensive diagnostic and therapeutic equipment while generating audit trails for regulatory inspections. Cloud-based deployment now leads new installations as hospitals prioritize remote access and reduced IT overhead, while imaging systems represent the most complex product type due to multimodal calibration requirements and parts traceability mandates. Maintenance services command the largest service-type revenue pool, though software integration grows fastest as legacy systems require API connectivity to enterprise resource planning platforms.
FDA quality system regulations and ISO 13485 standards shape product design by mandating electronic records integrity and device history file accessibility, directly increasing software validation requirements for vendors. The EU Medical Device Regulation imposes additional post-market surveillance obligations that drive European hospital demand for automated incident reporting modules. Stakeholders must monitor how converging cybersecurity frameworks from NIST and IEC 62304 reshape software architecture requirements for networked repair platforms.
Market Dynamics
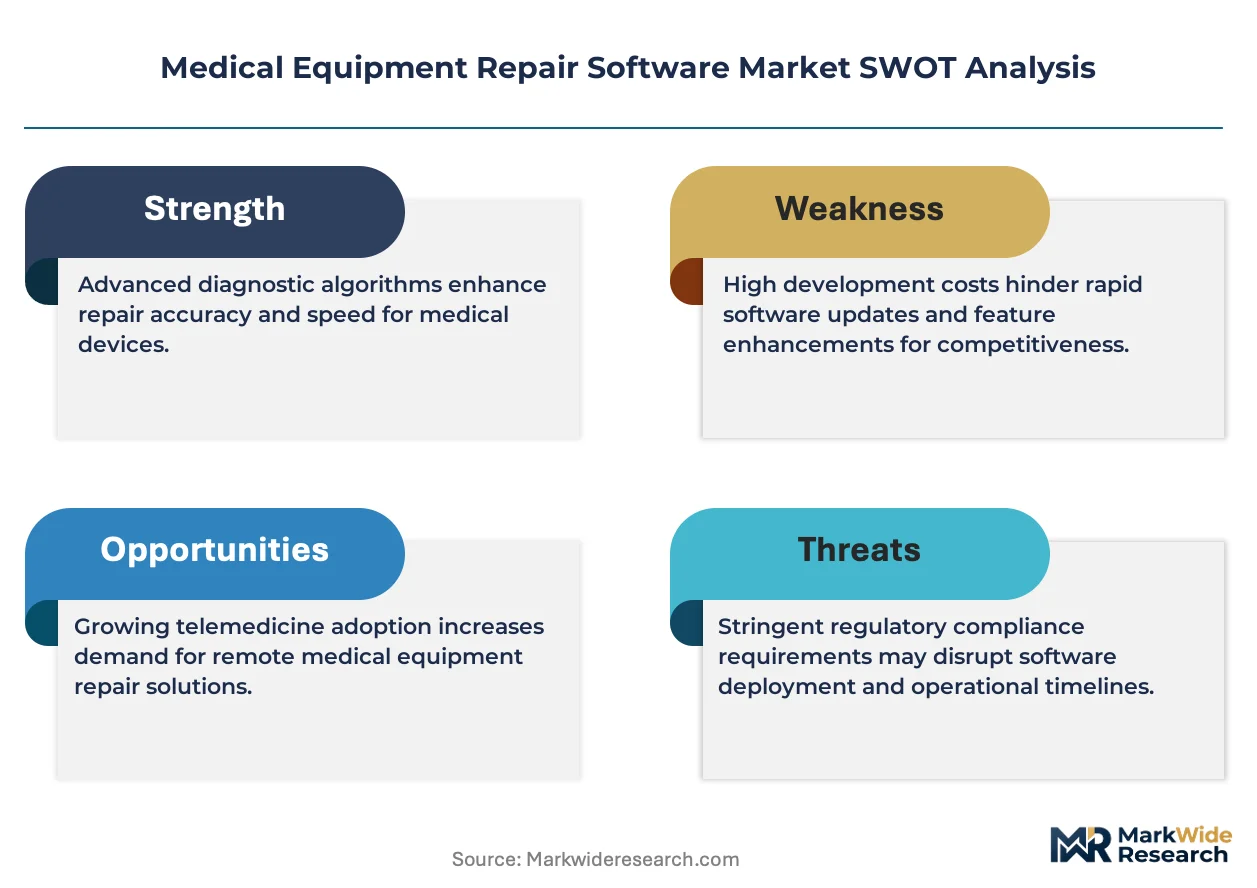
Hospital procurement departments are consolidating vendor management platforms under stricter FDA quality system regulations, forcing repair software vendors to embed electronic records integrity and device history file accessibility as core architectural requirements rather than optional modules.
Growth Catalysts
- Cloud-based deployment models:Health systems in Germany and the United States prioritize remote access and reduced IT overhead, accelerating replacement of on-premise legacy installations with SaaS architectures that enable centralized fleet management across distributed hospital networks.
- FDA 21 CFR Part 820 enforcement:Medical device manufacturers and hospital service departments face intensified inspection scrutiny for corrective and preventive maintenance documentation, mandating software platforms that generate automated audit trails for quality system reviews.
- Diagnostic equipment fleet expansion:Capital-intensive imaging modalities including MRI, CT, and PET systems require multimodal calibration tracking and parts traceability that legacy spreadsheet systems cannot support, creating replacement demand for integrated repair platforms.
Market Restraints
- Software validation costs:FDA-mandated computer system validation for electronic records creates six-figure implementation barriers for mid-sized independent service organizations with limited quality assurance staffing.
- Concentrated cloud infrastructure:Dominance of hyperscale providers in data center hosting concentrates operational risk, where regional outages or cybersecurity incidents cascade across multiple hospital clients simultaneously.
- Legacy system entrenchment:Decades-old computerized maintenance management systems with customized workflows create switching friction that extends sales cycles and inflates migration costs for replacement vendors.
Strategic Opportunities
- EU Medical Device Regulation post-market surveillance:Automated incident reporting modules that streamline vigilance obligations for European hospitals represent white-space functionality that incumbent North American vendors have underdeveloped.
- API connectivity to ERP platforms:Integration middleware that bridges repair software with SAP and Oracle enterprise resource planning systems captures fastest-growing revenue pools as health systems demand unified procurement-to-maintenance workflows.
- Ambulatory surgical center penetration:Specialized procurement-to-repair automation for outpatient facilities addresses an underpenetrated segment where equipment downtime carries disproportionate revenue impact relative to hospital scale.
Industry Challenges
- Technician certification tracking:Maintaining current records for ISO 13485-competent personnel across dispersed field service teams requires real-time mobile interfaces that many platforms lack.
- Interoperability with cybersecurity frameworks:NIST and IEC 62304 convergence demands architectural redesigns for networked repair platforms, compressing development timelines while validation requirements expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Equipment Repair Software Market |
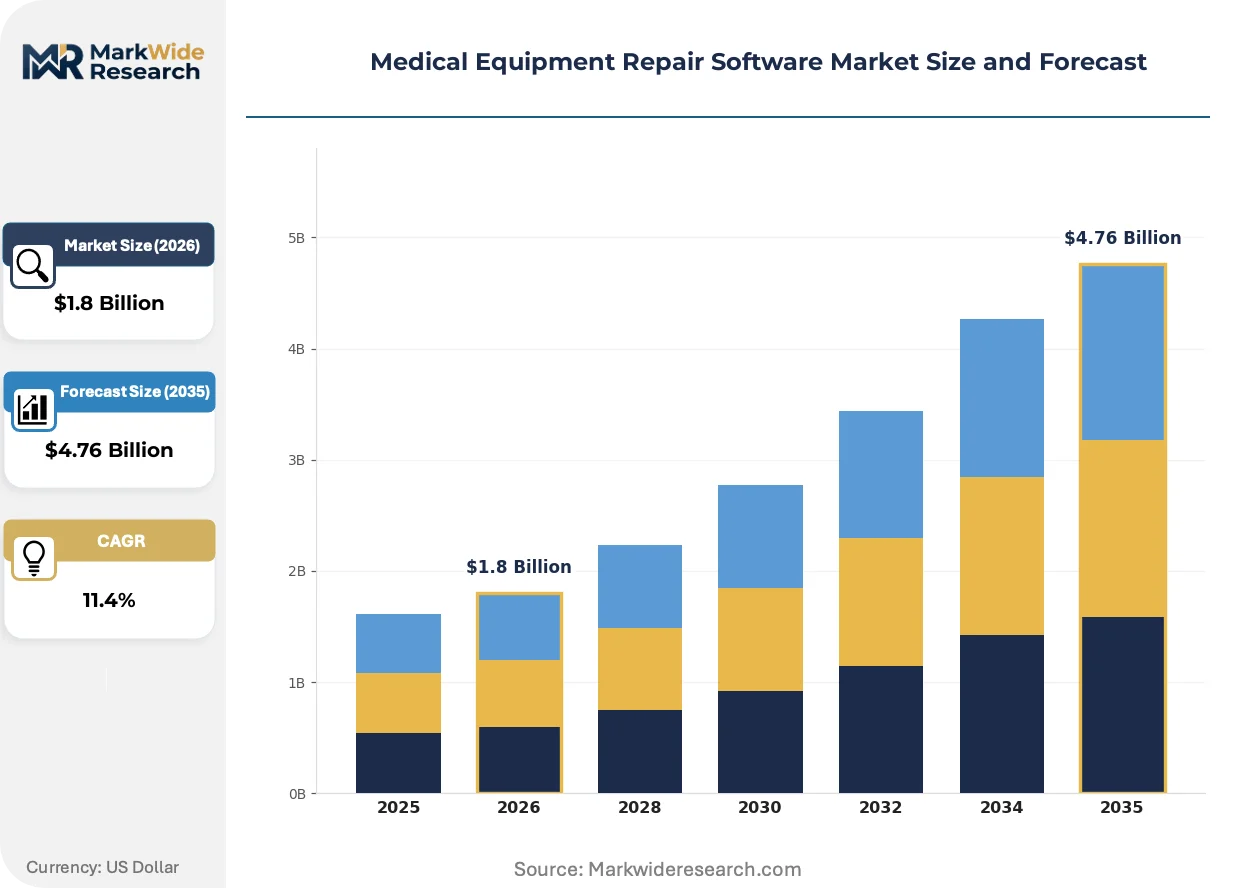
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Monitoring Devices, Imaging Systems Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Rehabilitation Centers Service Type: Maintenance, Calibration, Inspection, Software Integration |
| Companies Covered | Crothall Healthcare, Hybrent Inc, Accruent eMaint, Service Works Global, EZOfficeInventory, Fortunesoft, eTurns Inc, Mymediset, Innomaint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Equipment Repair Software Market Evolving Landscape
Digital twin architectures and predictive analytics are compressing maintenance intervals from calendar-based to condition-based schedules, while regulatory pressure on cybersecurity and post-market surveillance accelerates platform consolidation.
Digital twin technology is virtualizing physical diagnostic equipment into software representations that simulate component degradation and predict failure modes before operational impact. Academic medical centers with large imaging fleets are piloting these systems at accelerated procurement cycles compared to community hospitals. This virtualization is compressing spare parts inventory requirements by enabling just-in-time procurement tied to predicted rather than scheduled maintenance windows.
The EU Medical Device Regulation imposes expanded post-market surveillance obligations including systematic literature reviews and periodic safety update reports that hospitals must document. European health systems are responding by demanding repair software with integrated vigilance modules that automate incident classification and regulatory submission workflows. Imaging system service departments face the steepest compliance burden due to their classification as highest-risk device categories under MDR Annex VIII.
After-sales service unbundling is separating software licenses from maintenance labor contracts, enabling hospitals to negotiate standalone platform subscriptions while sourcing technician staffing through alternative channels. Original equipment manufacturers with captive service divisions are resisting this disintermediation through bundled pricing, but procurement departments in the United States are extracting concessions by threatening third-party software adoption. This pattern is most visible in radiology departments where equipment specialization creates vendor lock-in risks that chief procurement officers actively mitigate.
Medical Equipment Repair Software Market Segmentation
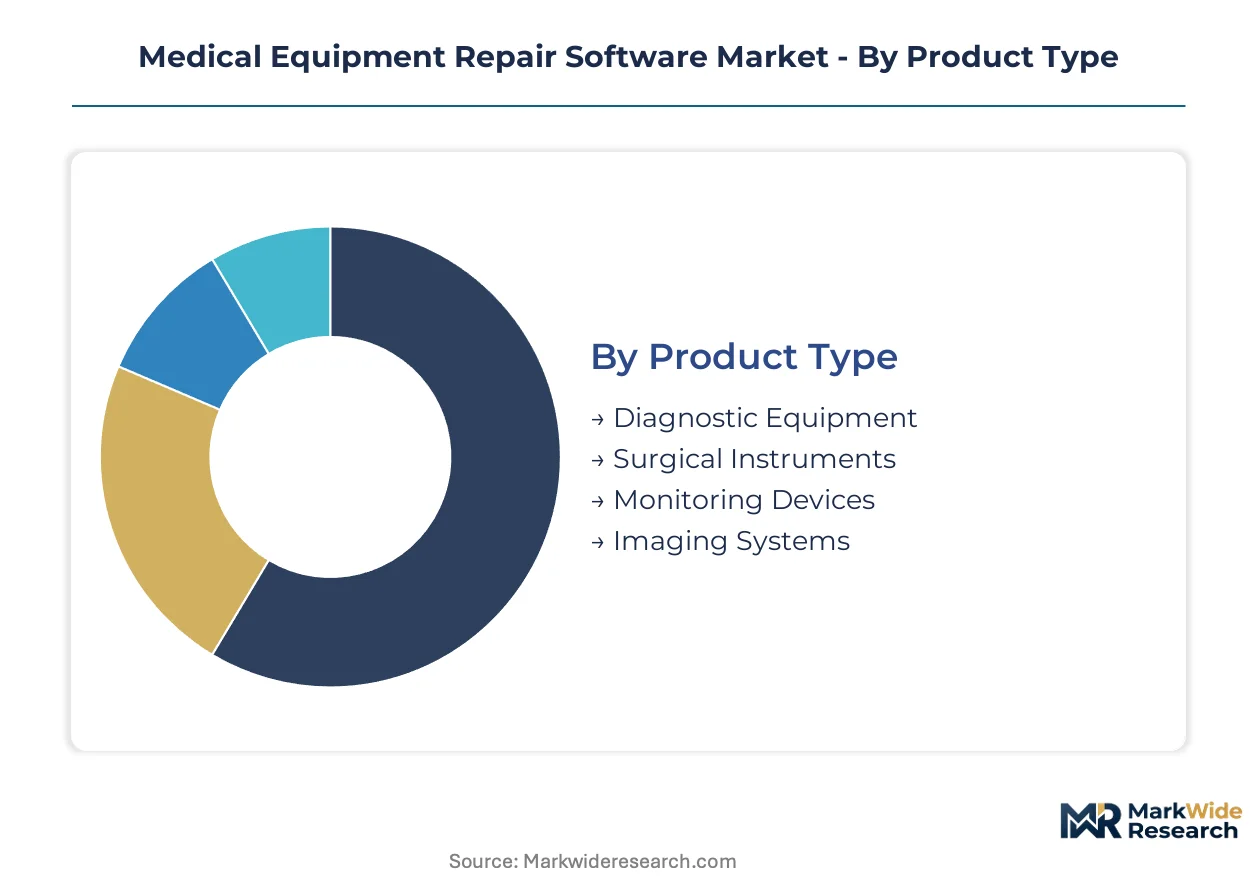
Segmentation in medical equipment repair software reveals divergent replacement cycles across product types and deployment models. Procurement departments align software refresh timelines with capital equipment depreciation schedules and regulatory audit calendars.
Product Type:
Replacement cycles stretch from quarterly calibration intervals for surgical instruments to multi-year overhauls for imaging platforms. Diagnostic equipment and imaging systems command extended sales cycles due to integration complexity.
- Imaging Systems:MRI, CT, and PET modalities require multimodal calibration tracking and parts traceability that legacy systems cannot support. Academic medical centers in Germany and the United States pilot digital twin architectures at accelerated procurement cycles compared to community hospitals.
- Diagnostic Equipment:Capital-intensive analyzers and testing platforms generate the largest maintenance revenue pools. Hospital procurement departments consolidate vendor management platforms for these assets under stricter FDA quality system regulations.
- Surgical Instruments:High-turnover device categories with rapid sterilization validation requirements. Ambulatory surgical centers prioritize procurement-to-repair workflow automation for these assets.
- Monitoring Devices:Networked patient monitors with cybersecurity frameworks from NIST and IEC 62304 compliance obligations.
Imaging systems anchors the volume base while diagnostic equipment gains share at the steepest rate.
Deployment:
Cost tiers separate enterprise installations from departmental deployments. Cloud architectures reduce upfront validation burdens while hybrid models preserve legacy data accessibility.
- Cloud-Based:SaaS architectures enable centralized fleet management across distributed hospital networks. Health systems in the United States and Germany prioritize remote access and reduced IT overhead.
- On-Premises:Legacy installations with customized workflows create switching friction. FDA-mandated computer system validation for electronic records creates six-figure implementation barriers.
- Hybrid:Mixed environments bridging legacy CMMS with modern API connectivity. ERP integration middleware captures fastest-growing revenue pools.
- Mobile:Real-time interfaces for ISO 13485-competent personnel across dispersed field service teams.
On-premises deployments retain the installed base while cloud-based solutions climb the fastest.
End User:
Customer type determines feature prioritization and contract structuring. Hospital procurement departments negotiate enterprise licenses while outpatient facilities seek specialized automation.
- Hospitals:Large health systems demand unified procurement-to-maintenance workflows with SAP and Oracle ERP integration. FDA 21 CFR Part 820 enforcement intensifies inspection scrutiny for corrective and preventive maintenance documentation.
- Ambulatory Surgical Centers:Underpenetrated segment where equipment downtime carries disproportionate revenue impact. Specialized procurement-to-repair automation addresses workflow gaps.
- Diagnostic Laboratories:High-throughput environments requiring automated incident reporting modules. EU Medical Device Regulation post-market surveillance obligations drive demand for vigilance functionality.
- Rehabilitation Centers:Smaller-scale facilities with limited quality assurance staffing facing software validation cost barriers.
Hospitals anchor the volume base while ambulatory surgical centers expand most quickly.
Service Type:
Margin structures vary across labor-intensive maintenance and high-margin software integration. After-sales service unbundling separates platform subscriptions from technician staffing contracts.
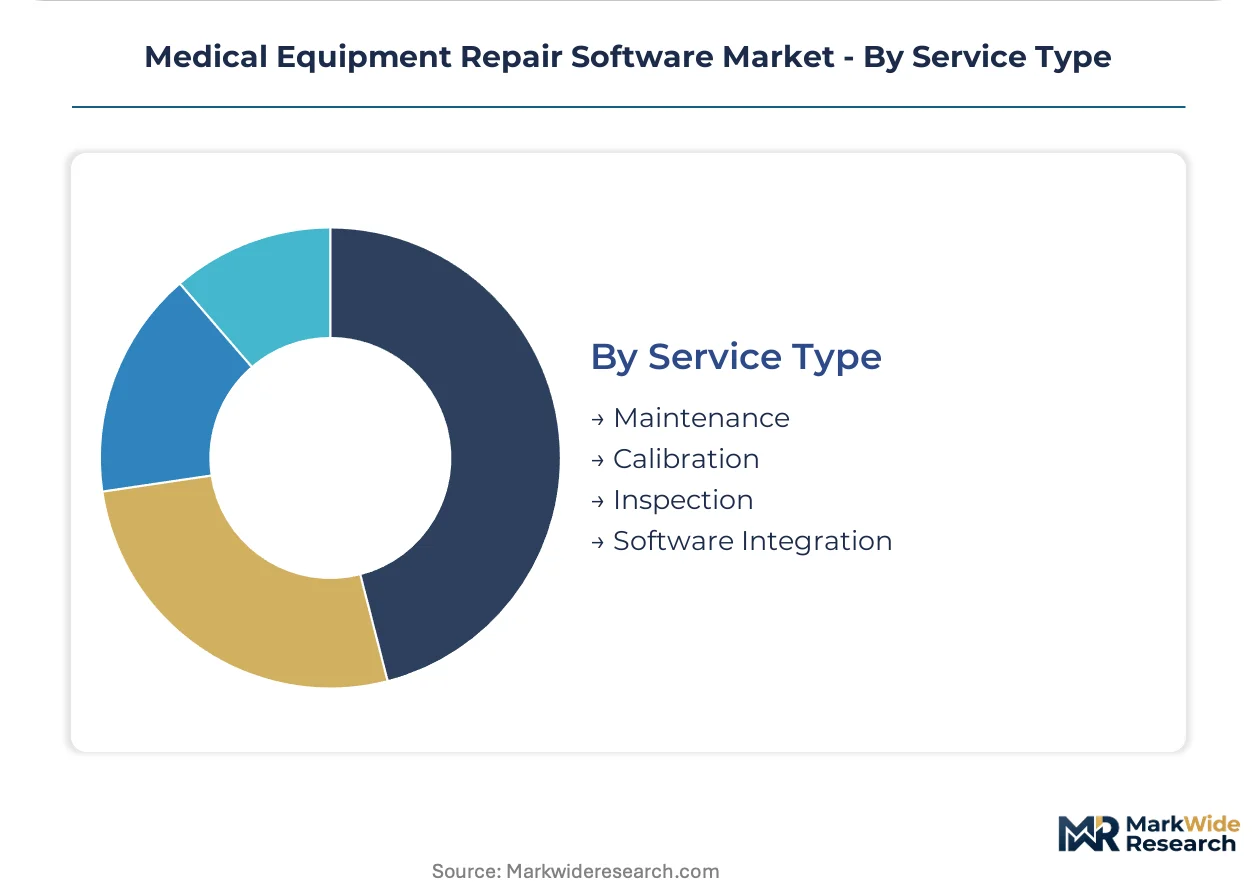
- Maintenance:Corrective and preventive maintenance actions on regulated clinical devices generate the largest service-type revenue pool. Work order management integrates with parts inventory and technician certification records.
- Software Integration:API connectivity to enterprise resource planning platforms captures fastest-growing revenue. Legacy systems require architectural redesigns for networked repair platforms.
- Calibration:Multimodal tracking for imaging modalities with FDA-compliant device history file accessibility.
- Inspection:Automated audit trail generation for regulatory inspections under intensified FDA scrutiny.
Maintenance services anchor the volume base while software integration expands at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA quality system regulations and EU Medical Device Regulation enforcement are redirecting hospital procurement budgets toward compliant repair software platforms across major healthcare markets.
United States
Hospital procurement departments are consolidating vendor management platforms under intensified FDA 21 CFR Part 820 scrutiny. Academic medical centers in Boston and the Research Triangle pilot digital twin architectures for imaging fleet management at accelerated procurement cycles. Cloud-based SaaS deployments dominate new installations as health systems prioritize remote access across distributed networks.
Germany
Health systems are replacing on-premise legacy installations with cloud architectures to enable centralized fleet management across hospital networks. The EU Medical Device Regulation imposes expanded post-market surveillance obligations that drive demand for automated vigilance modules. Medical technology clusters in Baden-Württemberg and Bavaria anchor software validation service expansion for mid-sized independent service organizations.
United Kingdom
NHS procurement frameworks are unbundling after-sales service contracts to negotiate standalone platform subscriptions. The Medicines and Healthcare products Regulatory Agency intensifies inspection scrutiny for electronic records integrity in device maintenance. London and Southeast England health systems lead ERP integration middleware adoption for unified procurement-to-maintenance workflows.
Japan
METI guidelines on medical device cybersecurity are reshaping software architecture requirements for networked repair platforms. Pharmaceutical and Medical Devices Agency quality system inspections mandate automated audit trail generation for corrective and preventive maintenance. The Kanto region around Tokyo concentrates pilot deployments of predictive analytics for capital-intensive imaging modalities.
India
Central Drugs Standard Control Organization medical device rules are formalizing quality management system requirements for hospital service departments. CDSCO's phased implementation of risk-based classification creates compliance windows for software platform adoption. Diagnostic laboratory clusters in Maharashtra and Karnataka drive demand for automated incident reporting modules tied to vigilance obligations.
Medical Equipment Repair Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: integrated facilities management platforms bundling repair software with staffing contracts, specialized procurement-to-repair workflow automation vendors, and computerized maintenance management system extenders targeting FDA compliance. Dominant competitive moves include strategic partnerships with ERP platform providers and geographic expansion through subscription-based leasing models.
Within the integrated facilities management tier, Crothall Healthcare exemplifies channel control through bundled service offerings. Hybrent Inc occupies a specialist position focused on ambulatory surgical center workflows. Accruent eMaint anchors the CMMS extension archetype by targeting FDA-compliant medical device tracking requirements. These three companies represent distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Crothall Healthcare |
| Hybrent Inc |
| Accruent eMaint |
| Service Works Global |
| EZOfficeInventory |
| Fortunesoft |
| eTurns Inc |
| Mymediset |
| Innomaint |
| Others |
Value Network & Pricing Analysis
Hyperscale cloud infrastructure concentration in the United States and Germany concentrates data center hosting costs, pushing margin pools toward software vendors with captive validation service capabilities rather than pure-play SaaS providers. Hospital procurement departments exploit this concentration by demanding bundled compliance modules that absorb implementation cost risk.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-validated enterprise tiers and basic work-order management subscriptions. Three-tier pricing structure across FDA-grade, CE-marked, and standard maintenance tiers separates academic medical centers from ambulatory surgical centers on price sensitivity. Cost compression in mid-market segments intensifies as independent service organizations absorb validation burden to compete with OEM bundled offerings. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while integrated delivery networks negotiate volume-based enterprise licenses with minimal per-seat escalation.
Supply Chain Analysis
Tariff exposure between United States and China semiconductor components elevates risk for on-premise server hardware dependent on imported processing units. Software development labor concentrates in India, Poland, and Romania, with cloud infrastructure sourcing from hyperscale providers in the United States, Ireland, and Singapore. Single-source vulnerability in API middleware for SAP and Oracle integration creates bottleneck risk for ERP-connected deployments. Distribution runs through direct enterprise sales teams with specialized healthcare vertical expertise, supplemented by GPO contract vehicles for hospital system procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hospital procurement departments consolidate vendor management platforms under stricter FDA quality system regulations, fragmenting incumbent market share across specialized compliance modules.
For Market Incumbents: Pre-empt disintermediation by unbundling software licenses from maintenance labor contracts before procurement departments force the issue through third-party platform adoption. Defend position by deepening captive validation service capabilities in Germany and the United States, the geographies with steepest regulatory enforcement. Channel control through GPO contract vehicles remains the priority lever against emerging SaaS-native entrants. For New Entrants and Emerging Players: India's diagnostic laboratory clusters represent the most penetrable geography, with CDSCO's phased risk-based classification creating compliance windows for automated incident reporting modules. White-space opportunity sits in EU Medical Device Regulation vigilance workflow automation for European hospitals, where incumbent North American vendors maintain underdeveloped functionality. Go-to-market through specialized procurement-to-repair positioning for ambulatory surgical centers bypasses entrenched hospital CMMS relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CMMS extenders targeting FDA-compliant medical device tracking, where platform consolidation opportunity overlaps with regulatory tailwinds. Long-term viability favors vendors with architectural flexibility for NIST and IEC 62304 cybersecurity convergence. Watch for inflection signals in hospital IT budget reallocation toward API connectivity and ERP integration middleware.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 820 Compliance Module Development | Automated audit trail generation addresses intensified inspection scrutiny for corrective and preventive maintenance documentation. |
| EU MDR Vigilance Workflow Integration | Streamlined incident classification captures white-space functionality for European hospital post-market surveillance obligations. |
| API Connectivity to ERP Platforms | SAP and Oracle integration middleware captures fastest-growing revenue pools in unified procurement-to-maintenance workflows. |
| Digital Twin Architecture Pilot Programs | Academic medical center partnerships accelerate procurement cycles for predictive analytics in imaging fleet management. |
| Ambulatory Surgical Center Specialized Automation | Procurement-to-repair workflow positioning addresses underpenetrated segment with disproportionate revenue impact from downtime. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, GPO contracts managers, and software integration specialists, and refined through secondary validation. FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract vehicles anchored quantitative sizing. Bottom-up deployment modeling across cloud, on-premise, hybrid, and mobile architectures was triangulated with top-down health system IT budget analysis.
Demand-supply balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product type, deployment model, end user category, and service type, with regulatory compliance tier as an industry-specific overlay. CAGRs were derived from replacement cycle analysis tied to capital equipment depreciation schedules and audit calendar alignment. Forecast inputs incorporated FDA enforcement intensity indices and EU MDR transition timeline assumptions.
Practitioners should monitor CDSCO implementation phases, NIST cybersecurity framework updates, and hyperscale cloud regional outage patterns for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Casino Management Systems Market
Software & Services
Global Recipe Apps Market
Software & Services
Global PPC Software Market
Software & Services
Dealer Management System Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Global License Management Market
Software & Services
Discount Management Software Market
Software & Services
Test Automation Market
Software & Services
File Sharing Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
Weather Forecast Software Market