
 Global Electronic Lab Notebook (ELN) Market | 2026-2036
Global Electronic Lab Notebook (ELN) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Lab Notebook (ELN) Market Foresight
Data-scientist shortages across contract research organizations is reorganizing how biopharma outsources digital lab infrastructure. Thermo Fisher Scientific leverages its instrument-software integration to anchor enterprise ELN deployments. Benchling competes through biology-native cloud architecture designed for gene-editing workflows. LabWare sustains its position in regulated quality-control environments through LIMS-ELN convergence.
An electronic lab notebook is a software application that replaces paper laboratory notebooks with structured digital records, capturing experimental protocols, raw data entries, instrument outputs, and audit trails with timestamped user authentication. Its primary commercial purpose is ensuring data integrity, traceability, and intellectual-property protection across research and quality-assurance operations. Cloud-based ELN leads product-type segmentation by reducing IT overhead for mid-sized biotech firms, while pharmaceutical research dominates application demand due to FDA validation requirements and multi-site collaboration needs. Hybrid deployment models are gaining fastest in academic consortia balancing sensitive proprietary data with cost-conscious shared infrastructure.
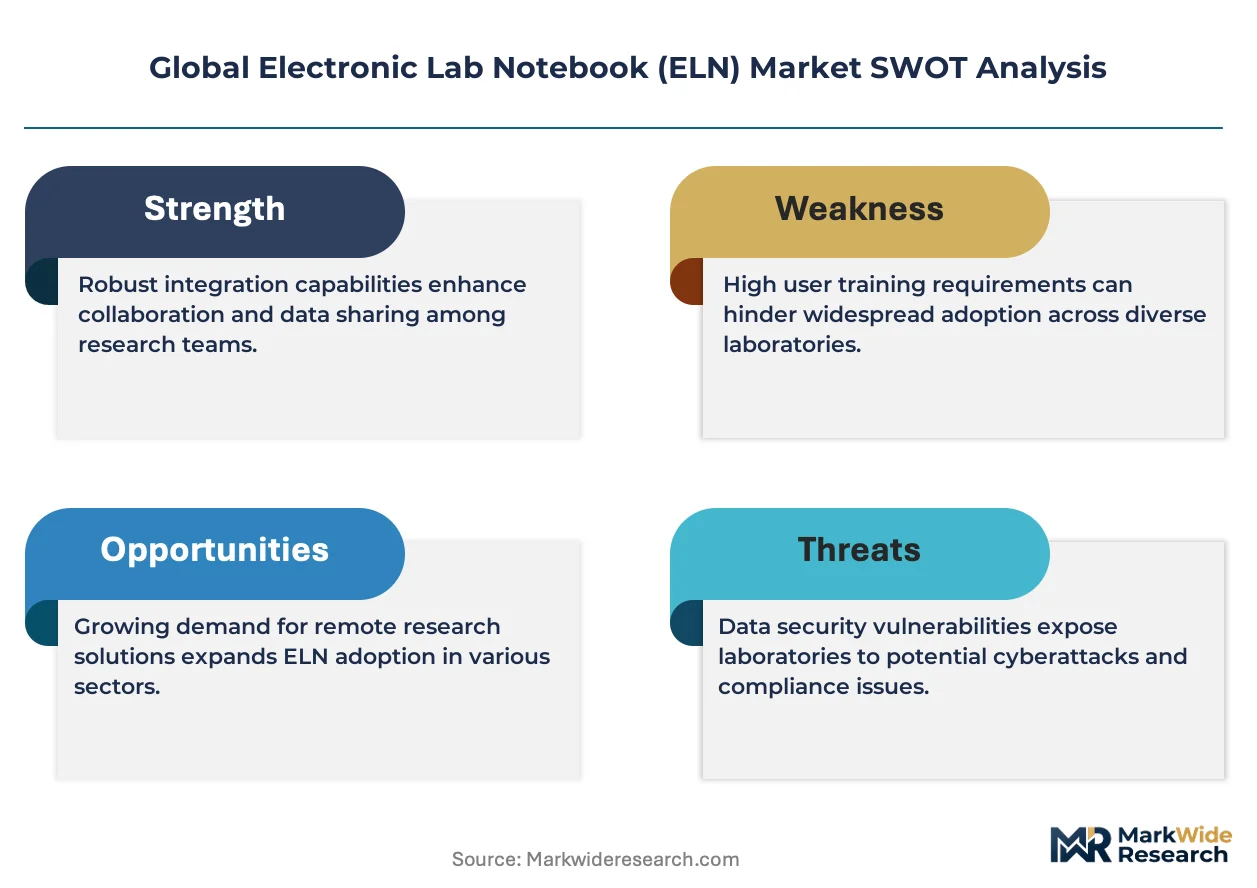
FDA 21 CFR Part 11, EU GDPR, and ISO 17025 collectively shape ELN procurement by mandating electronic signatures, data residency controls, and calibration documentation standards that paper-based or generic software systems cannot satisfy. EMA's Good Manufacturing Practice Annex 11 updates are forcing European pharma labs to revalidate legacy systems or migrate to compliant platforms. Stakeholders must monitor evolving AI-generated data protocols, as regulatory bodies begin scrutinizing machine-learning model traceability within electronic record systems.
Market Dynamics
Biopharma contract research organizations face acute data-scientist shortages, forcing accelerated outsourcing of digital lab infrastructure and cloud-based validation workflows.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature mandates push pharmaceutical quality-control labs toward validated ELN platforms, eliminating paper-based audit trails.
- Gene-editing workflows:CRISPR-intensive biotech firms require biology-native cloud architectures capturing protocol variations across distributed research teams.
- United States federal funding:NIH grant requirements for data management plans sustain procurement pressure across academic and government research facilities.
Market Restraints
- Cloud vendor concentration:Mid-sized biotech firms face vendor lock-in risks with limited migration pathways between dominant platform providers.
- EU GDPR data residency:Cross-border clinical trials require fragmented infrastructure investments to satisfy territorial storage mandates.
- Legacy LIMS integration:Pharmaceutical manufacturers confront technical debt from decades-old quality systems resisting API-based connectivity.
Strategic Opportunities
- India biopharma outsourcing:CDMO clusters in Hyderabad and Bengaluru lack validated electronic systems, creating first-mover advantages for compliant platform entrants.
- AI-generated data protocols:Machine-learning model traceability requirements are opening new compliance service layers around audit trail documentation.
- Academic consortia hybrid models:Shared infrastructure arrangements balance sensitive proprietary data with cost-conscious resource pooling across institutional networks.
Industry Challenges
- Validation specialist scarcity:Pharmaceutical manufacturers compete for limited talent capable of executing FDA-compliant system deployments.
- Multi-site synchronization:Contract research organizations struggle to maintain data integrity consistency across geographically dispersed trial locations.
- Interoperability standards:Absence of universal file formats forces redundant data entry between ELN, LIMS, and instrument control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Lab Notebook (ELN) Market |
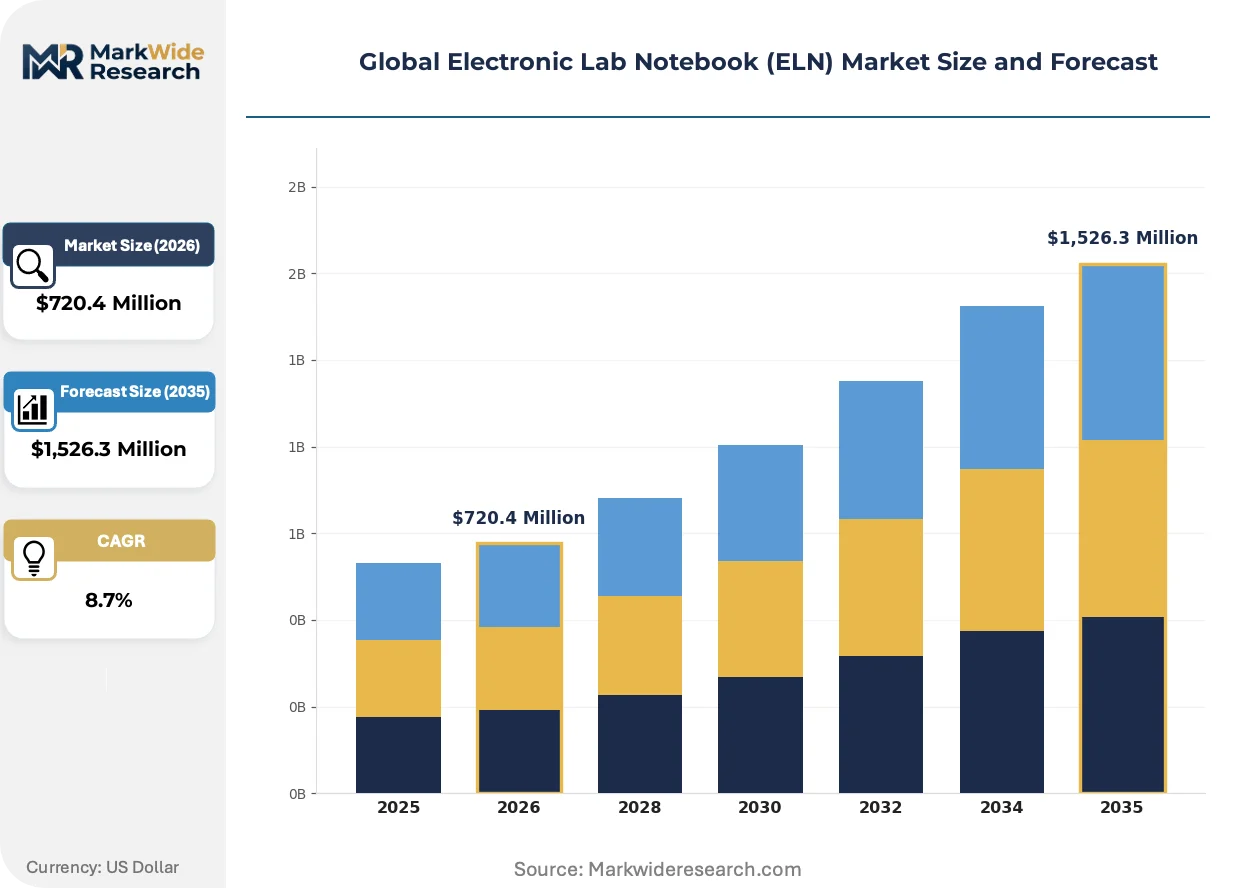
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,526.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based ELN, Web-Based ELN, Client-Server ELN, Hybrid ELN Application: Pharmaceutical Research, Biotechnology Labs, Academic Research, Food Safety Analysis, Chemical Analysis End User: Pharma Research Centers, Biotech Firms, University Laboratories, Food Testing Facilities, Chemical Manufacturers Deployment Model: Public Cloud, Private Cloud, On-Premises, Hybrid Cloud |
| Companies Covered | Thermo Fisher Scientific Inc., Benchling, LabWare, LabVantage Solutions Inc., Dassault Systèmes, Revvity, Inc., Abbott Informatics, Bruker Corporation, Agilent Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Lab Notebook (ELN) Market Shifts & Advancements
Artificial intelligence integration and modular cloud architectures are compressing deployment timelines while fragmenting traditional vendor consolidation patterns.
Natural language processing for experimental protocol transcription is fragmenting manual data-entry workflows. Contract research organizations in the United States adopt these tools to accelerate study startup phases. The technology compresses documentation labor costs while introducing new validation requirements for AI-generated record integrity.
EMA's Good Manufacturing Practice Annex 11 updates force European pharmaceutical manufacturers to revalidate legacy electronic systems or execute full platform migrations. Manufacturers in Germany and Switzerland face compressed compliance timelines through 2025. The regulation accelerates replacement demand for systems lacking contemporary audit trail capabilities.
Subscription-based pricing models displace perpetual license structures among mid-sized biotechnology firms. Vendors unbundle implementation services from core platform fees, shifting cost recognition patterns. This restructuring is most visible in United States and United Kingdom markets where capital efficiency pressures dominate procurement committees.
Global Electronic Lab Notebook (ELN) Market Segmentation
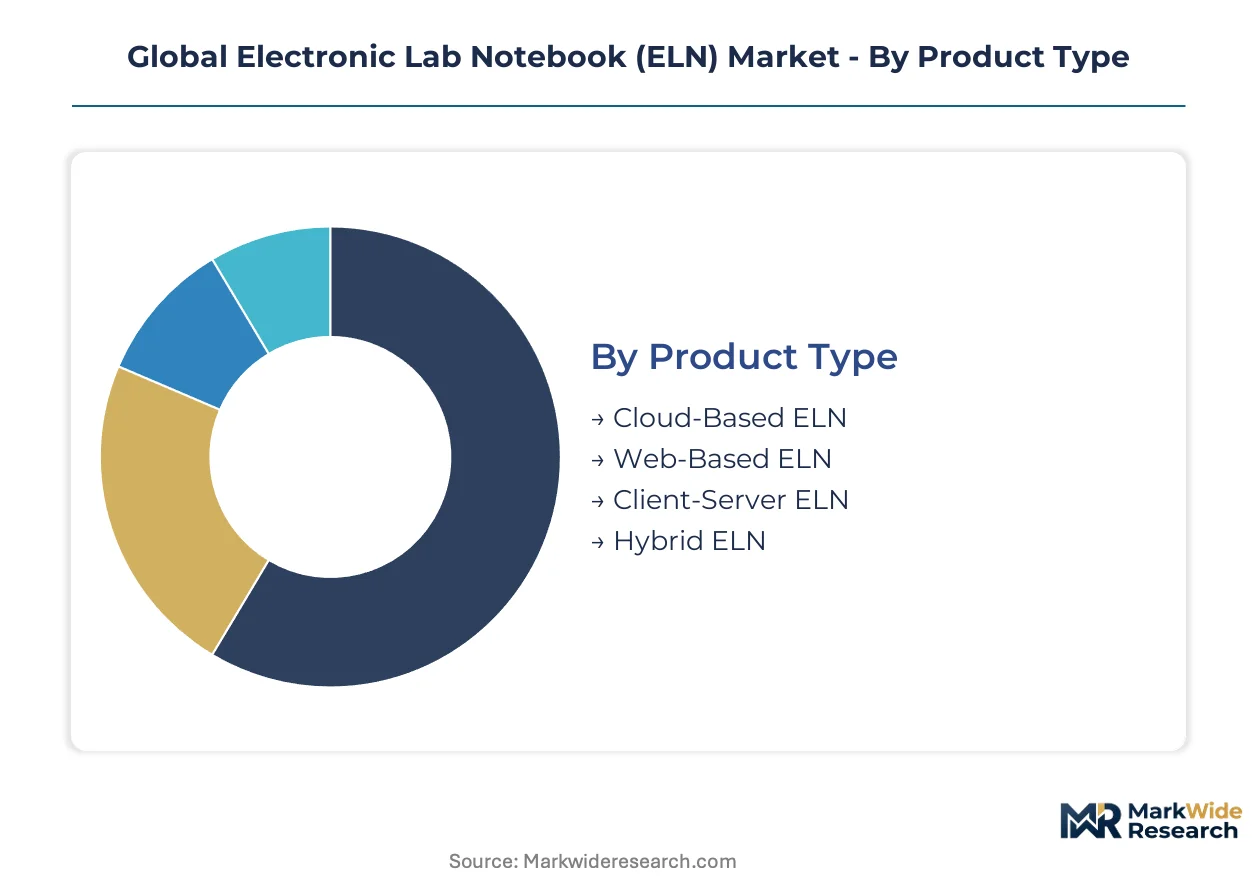
ELN procurement patterns diverge sharply across infrastructure choices and institutional settings. Deployment architecture determines validation pathways, while end-user scale dictates whether cloud elasticity or on-premises control dominates purchasing decisions.
Product Type:
Cloud-based platforms flow through vendor-direct channels and systems integrators, while hybrid configurations route through specialized compliance consultants serving regulated manufacturers.
- Cloud-Based ELN:Multi-tenant SaaS architecture eliminates server maintenance overhead for mid-sized biotech firms. Demand concentrates in United States contract research organizations facing NIH data management mandates and compressed IT staffing.
- Hybrid ELN:Split architectures separate proprietary assay data on-premises from collaborative protocols in cloud instances. Academic consortia in Germany and Switzerland adopt these configurations to balance GDPR territorial requirements with cross-institutional resource pooling.
- Web-Based ELN:Browser-accessible platforms with lighter infrastructure requirements serve smaller analytical chemistry labs.
- Client-Server ELN:Legacy architectures persist in pharmaceutical quality-control environments with decades-old LIMS integration dependencies.
Cloud-Based ELN dominates installed base. Hybrid ELN is where expansion concentrates.
Application:
Cost tiering separates validated pharmaceutical deployments from academic implementations, with biotechnology labs occupying a mid-tier pricing band.
- Pharmaceutical Research:Multi-site trial coordination demands audit trails satisfying FDA 21 CFR Part 11 and EMA Annex 11 simultaneously. United States and European Union facilities drive procurement volume through mandatory electronic signature frameworks.
- Biotechnology Labs:Gene-editing workflows require biology-native data structures capturing CRISPR protocol variations. CRISPR-intensive firms in Boston and San Francisco clusters prioritize cloud architectures enabling distributed team synchronization.
- Academic Research:Grant-funded installations emphasize cost efficiency over compliance depth.
- Food Safety Analysis:ISO 17025 documentation requirements shape platform selection for testing laboratories.
- Chemical Analysis:Analytical method transfer protocols influence electronic record system design.
Pharmaceutical Research commands premium pricing. Biotechnology Labs are climbing the fastest.
End User:
Customer scale determines whether enterprise licensing or per-seat subscriptions dominate contract structures.
- Pharma Research Centers:Multi-departmental deployments spanning discovery through quality assurance require tiered access controls and instrument integration layers. United States facilities face sustained procurement pressure from federal funding visibility requirements.
- Biotech Firms:Venture-backed companies prioritize capital-efficient SaaS models with rapid implementation timelines. Early-stage firms in Cambridge, Massachusetts and South San Francisco favor unbundled implementation services to preserve runway.
- University Laboratories:Shared core facilities balance sensitive proprietary data from industry partnerships against open collaboration needs.
- Food Testing Facilities:Regulatory inspection readiness drives platform selection over feature depth.
- Chemical Manufacturers:Process analytical technology integration shapes system requirements.
Pharma Research Centers anchor enterprise revenue. Biotech Firms are expanding most quickly.
Deployment Model:
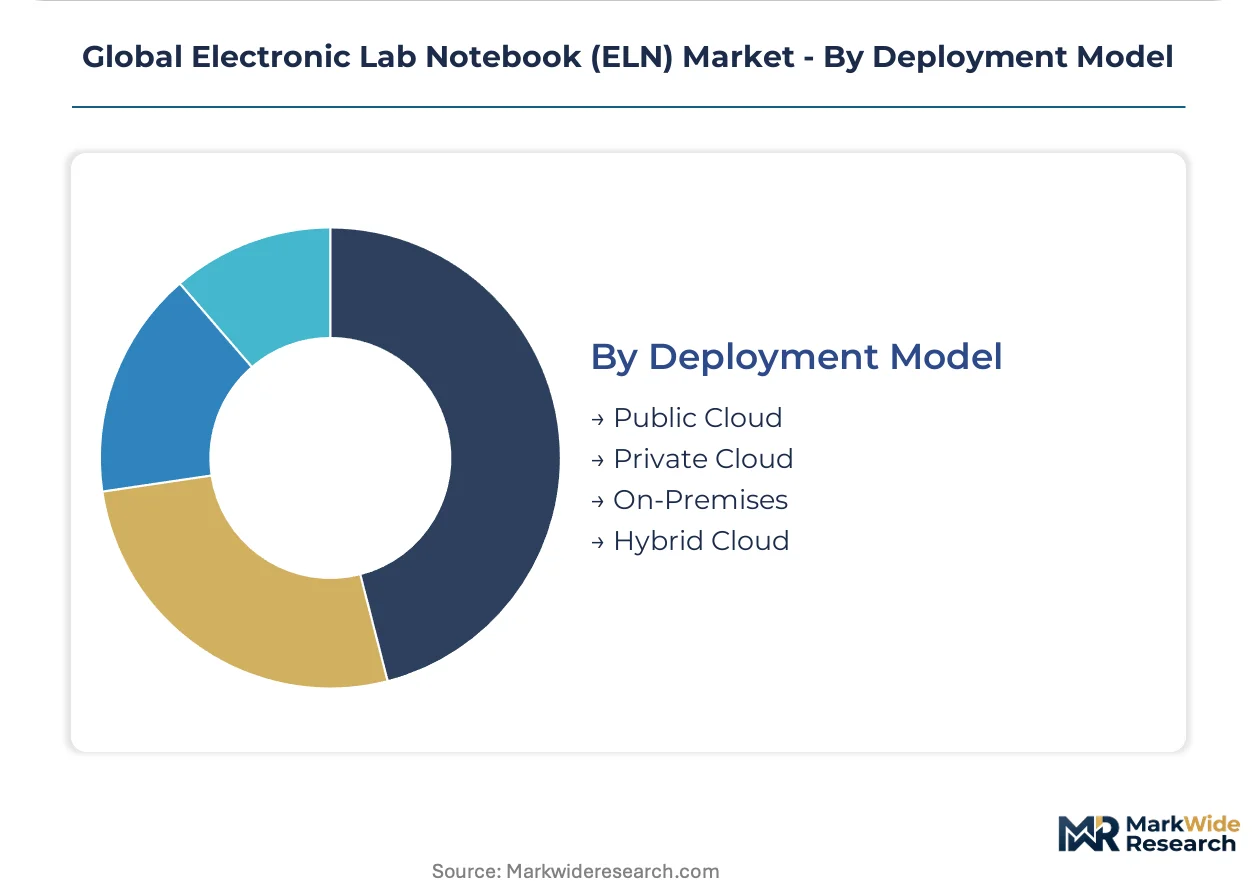
Volume concentration in public cloud deployments contrasts with margin concentration in private infrastructure serving classified or proprietary research.
- Public Cloud:Shared infrastructure delivers lowest per-seat economics for non-regulated research phases. Mid-sized biotechnology firms in United Kingdom and United States markets displace perpetual licenses with subscription structures.
- Private Cloud:Single-tenant environments satisfy data residency mandates for cross-border clinical trials. European pharmaceutical manufacturers deploy these configurations to satisfy GDPR territorial storage requirements without sacrificing cloud elasticity.
- On-Premises:Air-gapped installations persist in defense-adjacent research and select quality-control environments.
- Hybrid Cloud:Workload-specific routing separates sensitive genomic data from collaborative protocol development.
Public Cloud holds majority volume. Private Cloud is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States facilities deploy cloud-native architectures for multi-site trial coordination, while German and Swiss laboratories prioritize private infrastructure for GDPR-compliant genomic data storage. This consumption-mix differential separates North American velocity from European control requirements.
United States
NIH data management mandates and compressed IT staffing at contract research organizations accelerate public cloud procurement. FDA 21 CFR Part 11 enforcement eliminates paper-based audit trails in quality-control environments. Boston and San Francisco biotech clusters drive biology-native platform demand for CRISPR protocol synchronization.
Germany
EMA Annex 11 revalidation deadlines through 2025 force pharmaceutical manufacturers toward compliant platform migrations. The country's national pharmaceutical regulator scrutinizes legacy system audit trail capabilities. Rhine-Main and Bavarian pharmaceutical manufacturing hubs concentrate replacement demand for electronic signature frameworks.
Switzerland
Swissmedic inspection protocols and banking-sector data security standards elevate private cloud requirements for clinical research. GDPR territorial storage mandates fragment cross-border trial infrastructure investments. Basel and Zurich pharmaceutical research centers anchor premium-tier validated system deployments.
India
CDSCO quality-control documentation requirements and biopharma outsourcing growth create first-mover opportunities for compliant platform entrants. The country's national pharmaceutical regulator tightens electronic record standards for contract manufacturing organizations. Hyderabad and Bengaluru CDMO clusters lack validated electronic systems, generating rapid procurement expansion.
United Kingdom
MHRA post-Brexit data integrity guidance and capital efficiency pressures displace perpetual licenses with subscription structures. NHS research funding visibility requirements sustain academic and government facility procurement. Cambridge and Oxford university-industry partnerships balance sensitive proprietary data with collaborative protocol sharing.
Global Electronic Lab Notebook (ELN) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with instrument manufacturers leveraging hardware-software bundles against cloud-native entrants. Thermo Fisher Scientific anchors enterprise deployments through analytical instrument integration. Benchling occupies the biology-native cloud segment. LabWare sustains regulated quality-control positions through LIMS convergence. Strategic moves concentrate on API-based connectivity investments and unbundled implementation service structures.
Within the integrated instrument-software tier, Thermo Fisher Scientific Inc. represents the convergence archetype, while Benchling exemplifies cloud-native specialization for gene-editing workflows. LabWare occupies a position in regulated LIMS-ELN convergence. These three anchors illustrate the market's vertical stratification between hardware-coupled incumbents and architecture-focused challengers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Benchling |
| LabWare |
| LabVantage Solutions Inc. |
| Dassault Systèmes |
| Revvity, Inc. |
| Abbott Informatics |
| Bruker Corporation |
| Agilent Technologies, Inc. |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 validation tiers gate both supplier qualification and price differentiation simultaneously, separating validated pharmaceutical deployments from cost-optimized academic installations. Cloud-native entrants compete against instrument-software bundles on implementation speed rather than license cost alone.
Pricing Analysis
Subscription-based SaaS contracts dominate mid-sized biotechnology procurement, displacing perpetual licenses with unbundled implementation fees. Price differentiation rests on validation depth and instrument integration complexity, with FDA-compliant tiers commanding premiums over research-grade alternatives. Cost compression in academic segments intensifies as shared consortia pool infrastructure investments. Contract research organizations exhibit lowest price sensitivity due to NIH funding visibility requirements, while early-stage biotech firms prioritize capital-efficient entry points.
Supply Chain Analysis
The United States and Germany anchor enterprise ELN platform development, while India and Ireland concentrate implementation services and validation consulting. Software architecture draws from open-source frameworks and proprietary instrument control libraries, with cloud infrastructure resting on hyperscaler data center networks. Single-source vulnerability concentrates in instrument-software bundles where hardware lock-in limits migration pathways. Distribution runs through vendor-direct sales for enterprise accounts and systems integrators serving mid-market implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic lab notebook adoption sits in early-cycle expansion, with biopharma outsourcing growth and AI-generated data protocols accelerating penetration beyond traditional pharmaceutical quality control.
For Market Incumbents: Fortify instrument-software integration layers to defend against cloud-native disintermediation in gene-editing workflows. Deepen API-based connectivity investments to reduce legacy LIMS integration friction. Prioritize validation specialist certification programs to address talent scarcity constraining enterprise deployment timelines. For New Entrants and Emerging Players: FDA 21 CFR Part 11 fast-track certification programs open first-mover positioning in India's CDMO clusters, where Hyderabad and Bengaluru facilities lack validated electronic systems. Target academic consortia hybrid deployments balancing GDPR territorial requirements with cost-conscious resource pooling. Lead with biology-native architectures capturing CRISPR protocol variations across distributed research teams. For Investors and Strategic Acquirers: Carve-out targets emerge from analytical instrument manufacturers seeking to monetize software capabilities through standalone platform spinouts. Five-to-ten-year viability hinges on AI-generated data protocol compliance service layers. Monitor EMA Annex 11 revalidation deadlines as inflection indicator for European replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-based connectivity reduces friction between ELN, LIMS, and instrument control systems. |
| Regulatory Approval Pathway | FDA 21 CFR Part 11 validation accelerates pharmaceutical quality-control procurement decisions. |
| Acquisition of Specialist Firm | Validation consulting capabilities address talent scarcity constraining enterprise deployments. |
| Geographic Expansion | India CDMO clusters present first-mover opportunities for compliant platform entrants. |
| Strategic Partnership | Hyperscaler alliances satisfy GDPR territorial storage without sacrificing cloud elasticity. |
Research Methodology
The analysis maps cloud-based, hybrid, web-based, and client-server ELN architectures, each validated through interviews with laboratory informatics directors, regulatory affairs leads at pharmaceutical manufacturers, IT procurement officers at contract research organizations, and validation specialists. Secondary sources include FDA 21 CFR Part 11 guidance documents, EMA Annex 11 updates, NIH data management plan requirements, and ISO 17025 calibration standards. Bottom-up installation base estimates triangulate against top-down addressable market calculations.
Consistency checks validate volume and value outputs against hyperscaler cloud infrastructure disclosures, academic research funding databases, and pharmaceutical R&D expenditure patterns. Segmentation dimensions span deployment model, end-user scale, application intensity, and regional regulatory cluster. Growth trajectories derive from adoption curve modeling across biopharma outsourcing expansion and AI-generated data protocol emergence.
Underlying assumptions cover sustained NIH funding visibility, EMA revalidation deadline adherence, and cloud vendor concentration stability, with deviation risk concentrated in data residency mandate fragmentation and validation specialist supply constraints. Recalibration cycles align with material shifts in regulatory enforcement intensity and biopharma outsourcing geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
User Experience (UX) Research Software Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Global Intranet Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Global Web Scraper Software Market
Software & Services
Europe Business Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Consignment Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Construction Estimating Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
Expense Management Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Sales Compensation Software Market
Software & Services
Transient Analysis Software Market