
 Artwork Management Software Market | 2026-2036
Artwork Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Artwork Management Software Market Insights
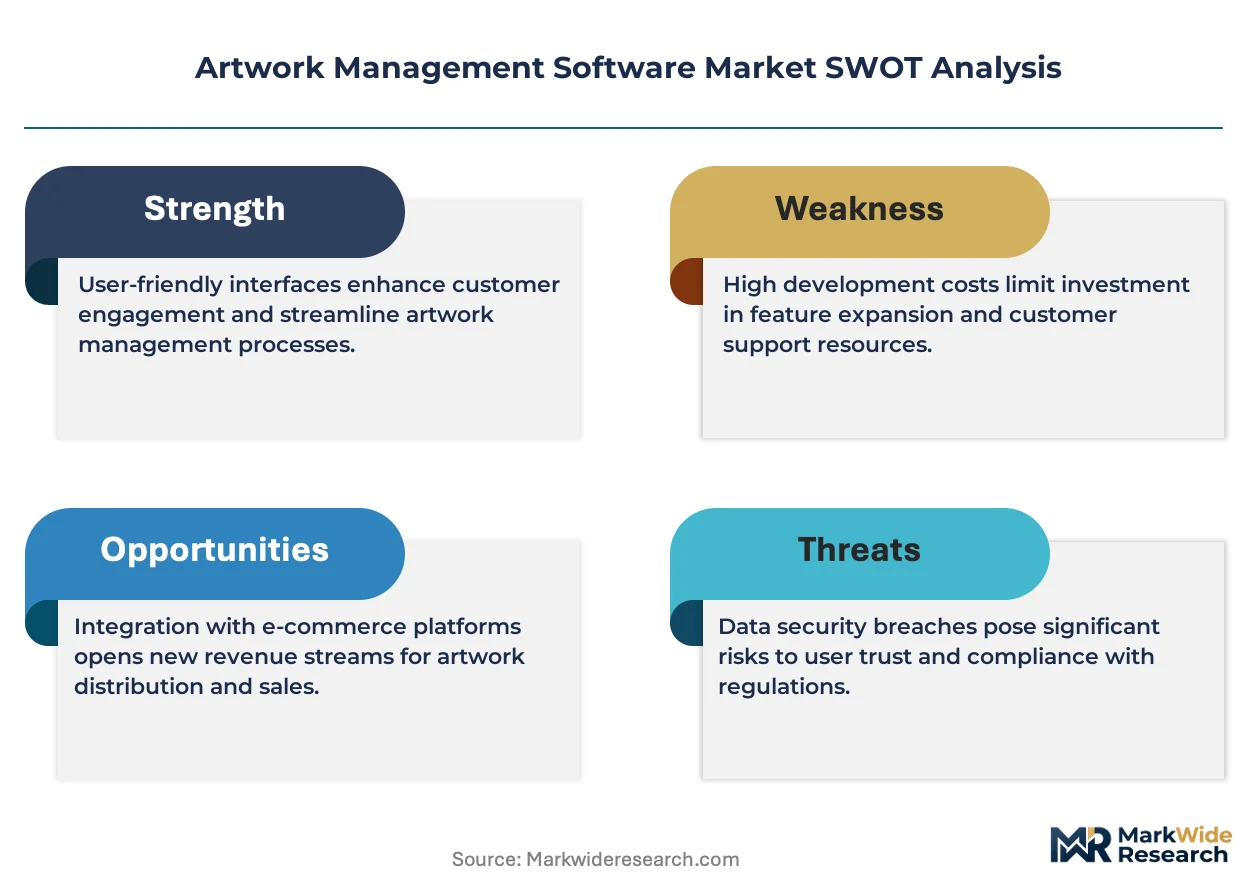
Subscription-based versioning layers is repositioning how artwork management vendors monetize core functionality. Esko leverages deep prepress integration to sustain its position in packaging-heavy workflows. Loftware anchors its competitive stance through enterprise-grade label-artwork convergence. ManageArtworks differentiates via vertical specialization in regulated consumer goods sectors.
Artwork management software comprises digital platforms that govern the creation, revision, approval, and distribution of product labels, packaging graphics, and marketing collateral through structured workflow engines with metadata tagging and role-based access protocols. These systems serve industrial and commercial purposes by eliminating manual proofing cycles and ensuring regulatory compliance across distributed supply chains. Cloud-based solutions lead structural deployment patterns as enterprises prioritize remote collaboration and reduced infrastructure overhead, while approval workflow modules capture concentrated margin pools due to their direct impact on audit readiness and time-to-market compression. Pharmaceutical end users represent the fastest-growing adoption segment as serialization mandates and evolving health authority labeling rules intensify compliance complexity.
FDA 21 CFR Part 11 electronic records requirements, EU MDR traceability standards, and ISO 9001 quality management frameworks collectively shape product specifications and market access thresholds for artwork management platforms. Health Canada and ANVISA labeling directives extend compliance obligations for vendors serving multinational pharmaceutical and medical device manufacturers. Stakeholders must evaluate how impending AI-generated content disclosure rules across multiple jurisdictions will reshape version control architectures and approval chain documentation.
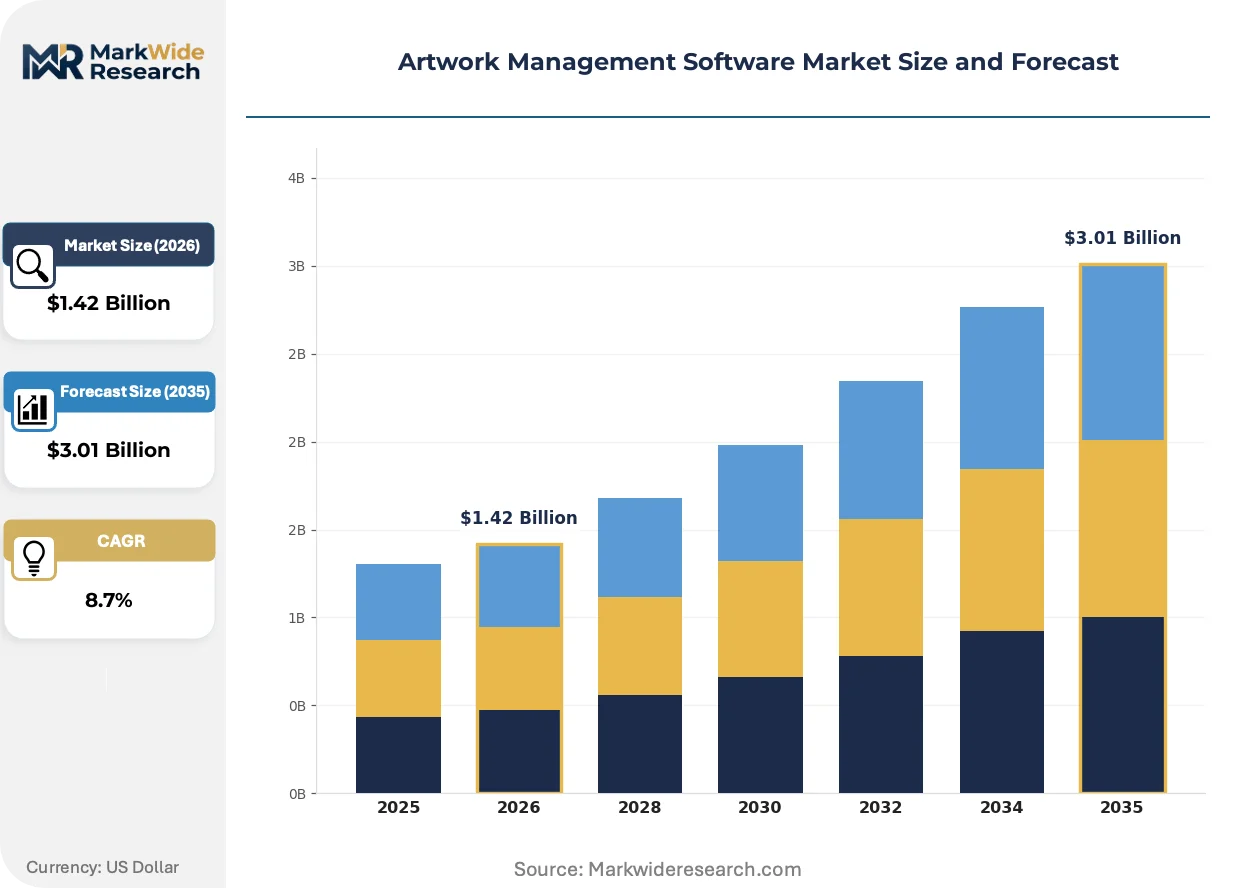
Market Dynamics
Cloud-native workflow engines are compressing approval cycles from weeks to days, forcing legacy on-premise vendors to rearchitect their platforms or cede mid-market share to SaaS-native competitors.
Growth Catalysts
- EU MDR traceability mandates:Pharmaceutical manufacturers across Germany, France, and Italy now require audit-ready version control for every label revision, expanding platform deployments.
- Serialization integration:Track-and-trace requirements for pharmaceutical packaging in the United States and Brazil are fusing artwork management with supply chain visibility systems.
- Remote collaboration infrastructure:Distributed creative teams in consumer goods sectors are driving demand for browser-based proofing and real-time annotation tools.
Market Restraints
- Implementation cost barriers:Mid-sized food and beverage manufacturers face capital constraints when migrating from file-server workflows to enterprise-grade platforms with validation protocols.
- Data residency requirements:China's Cybersecurity Law and Russia's data localization rules fragment cloud deployment architectures, increasing vendor compliance overhead.
- Prepress vendor lock-in:Deep integration with Esko Automation Engine and similar incumbent tools creates switching friction for packaging converters seeking modular alternatives.
Strategic Opportunities
- Medical device labeling expansion:Class II and III device manufacturers in the United States remain underpenetrated relative to pharmaceutical adopters, presenting greenfield deployment potential.
- AI-assisted content generation:Convergence of generative image tools with compliance-checking algorithms offers first-mover advantage for vendors integrating disclosure audit trails.
- Subscription versioning modules:Modular pricing for approval workflow layers allows vendors to capture smaller cosmetics and nutraceutical brands previously priced out of full suites.
Industry Challenges
- Regulatory affairs talent scarcity:Shortage of professionals fluent in both FDA 21 CFR Part 11 requirements and creative workflow management slows enterprise implementations.
- Legacy ERP integration complexity:SAP and Oracle connector development demands specialized engineering resources, extending deployment timelines for multinational manufacturers.
- Multi-jurisdiction content disclosure rules:Emerging AI-generated content labeling requirements across the European Union, United States, and China create conflicting documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artwork Management Software Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Cloud-Based, On-Premises, Hybrid, Mobile-Optimized End User: Consumer Goods, Retailers, Beverage Industry, Pharmaceutical Deployment: Single-Tenant, Multi-Tenant, Dedicated Server, Virtual Private Cloud Feature: Version Control, Collaboration Tools, Approval Workflow, Reporting Module |
| Companies Covered | Cway, Loftware, ManageArtworks, GLAMS, Twona, Esko, Kallik, Seagull Scientific, Artwork Flow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artwork Management Software Market Trends and Innovations
Intelligent automation is dissolving the boundary between creative production and compliance verification, embedding regulatory checks directly into design iteration cycles rather than treating them as terminal gates.
Generative AI content engines are electrifying how marketing collateral and packaging variants get produced. Consumer goods brand teams are adopting these tools to spawn localized label adaptations at scale. This compression of creative iteration is electrifying competitive pressure on traditional agency-retainer models and forcing artwork platforms to embed provenance tracking natively.
EU AI Act transparency obligations are mandating disclosure documentation for algorithmically generated visual content. Pharmaceutical and medical device manufacturers must now maintain audit trails distinguishing human-created from AI-assisted label elements. European marketing compliance teams are responding by demanding workflow platforms with automated lineage capture and immutable version hashing.
Enterprise buying committees are consolidating vendor relationships around integrated label-to-artwork suites rather than maintaining separate systems. Food and beverage procurement teams in North America are displacing point solutions with converged platforms that handle both regulatory label data and marketing graphics. This consolidation pattern is most visible among mid-market CPG manufacturers seeking to reduce supplier management overhead.
Artwork Management Software Market Segmentation
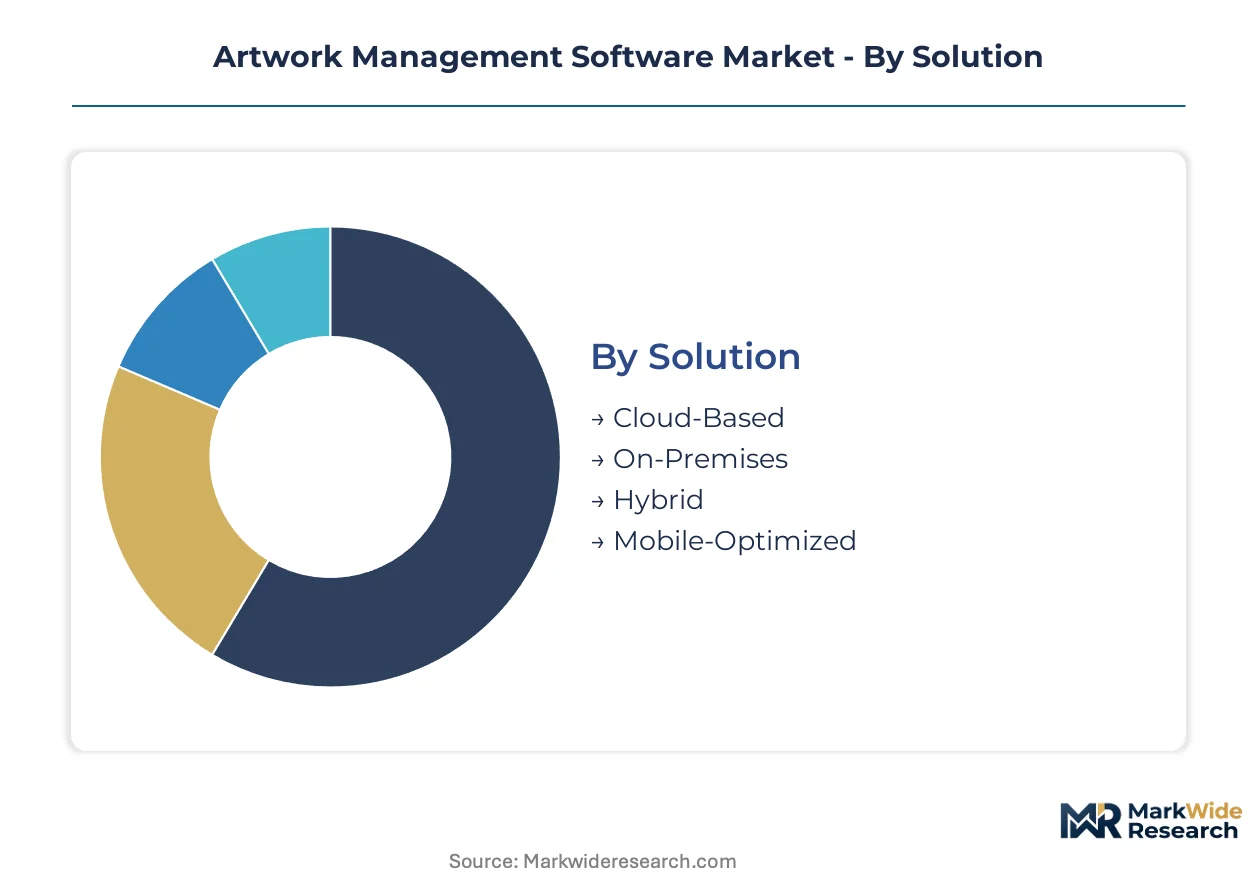
Artwork management software segments reflect divergent infrastructure requirements across regulated industries. Deployment architectures and feature priorities vary sharply between pharmaceutical compliance mandates and consumer goods velocity demands.
Solution:
Supply concentration in cloud-native platforms is compressing pricing power for legacy on-premise vendors while creating margin pools for hybrid orchestration specialists.
- Cloud-Based:Browser-accessible platforms with elastic compute and automatic patch management. Demand concentrates among mid-market consumer goods manufacturers in the United States seeking zero-infrastructure deployment with FDA 21 CFR Part 11 validation packages.
- On-Premises:Self-hosted installations with air-gapped security and custom hardware stacks. German pharmaceutical manufacturers under EU MDR traceability rules anchor residual demand for controlled-environment deployments with immutable audit logs.
- Hybrid:Split architectures processing sensitive data locally while leveraging cloud collaboration layers.
- Mobile-Optimized:Touch-native interfaces for field-based approval workflows and warehouse floor annotations.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
End User:
Cost tier stratification separates enterprise-grade pharmaceutical deployments from lightweight consumer goods implementations with divergent compliance overhead.
- Pharmaceutical:Serialization-integrated platforms with health authority submission gateways and multi-language label variant management. FDA and EMA regulatory complexity in the United States and Germany drives premium pricing for validation-ready systems with electronic signature workflows.
- Consumer Goods:High-velocity SKU proliferation tools with rapid versioning and retailer portal integration. French and Italian cosmetics brands with frequent packaging refreshes represent the steepest expansion trajectory for modular subscription tiers.
- Beverage Industry:Seasonal campaign management with alcohol content disclosure and regional distribution label variants.
- Retailers:Private-label governance with supplier onboarding and quality gate enforcement.
Pharmaceutical commands margin. Consumer Goods commands volume.
Deployment:
Application criticality determines tenancy isolation requirements, with medical device manufacturers rejecting shared infrastructure despite cost premiums.
- Multi-Tenant:Shared resource pools with logical data separation and unified upgrade cycles. SaaS-native vendors in the United States concentrate development investment here, capturing mid-market food and beverage manufacturers with standardized workflows.
- Single-Tenant:Dedicated instance isolation with custom configuration retention. Brazil's ANVISA serialization mandates for pharmaceutical track-and-trace are expanding demand among multinational manufacturers requiring sovereign data boundaries.
- Dedicated Server:Physical hardware assignment with performance guarantees.
- Virtual Private Cloud:Network-segmented cloud environments with encrypted tunneling.
Multi-Tenant dominates new bookings. Single-Tenant dominates expansion revenue.
Feature:
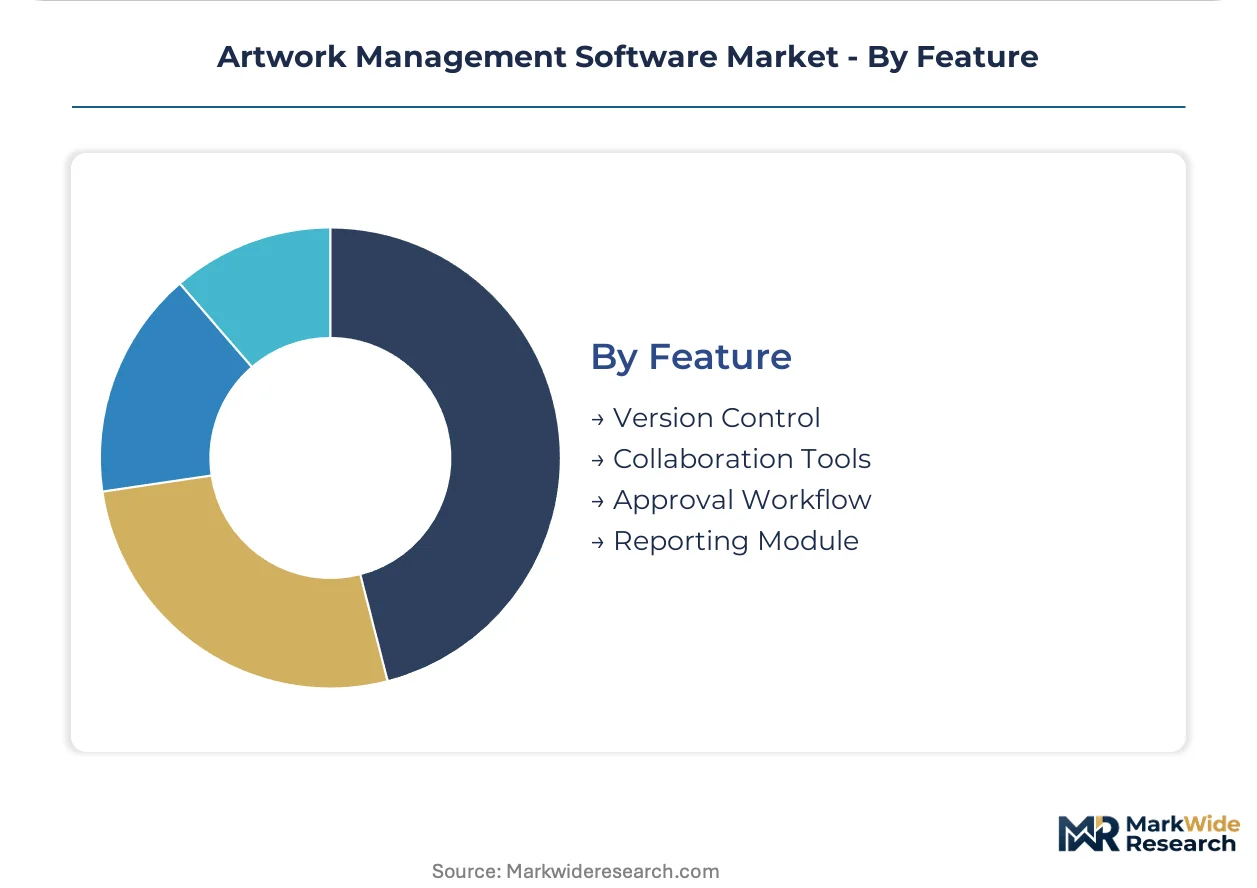
Margin capture concentrates in workflow automation layers that compress approval latency rather than passive storage or viewing functions.
- Approval Workflow:Role-based routing engines with escalation triggers and audit trail generation. Pharmaceutical quality assurance teams in Switzerland and the United States prioritize these modules for FDA inspection readiness and EU MDR technical documentation compliance.
- Version Control:Immutable revision hashing with lineage visualization and rollback capabilities. Medical device labeling teams expanding into AI-generated content under EU AI Act transparency rules are driving fastest uptake of automated provenance capture.
- Collaboration Tools:Real-time annotation, compare modes, and stakeholder notification systems.
- Reporting Module:Compliance dashboards, cycle time analytics, and bottleneck identification.
Approval Workflow extracts premium pricing. Version Control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates cloud-native deployment demand while Germany sustains on-premise infrastructure for pharmaceutical traceability, revealing divergent infrastructure preferences across Atlantic markets.
United States
FDA 21 CFR Part 11 validation packages and serialization mandates for pharmaceutical packaging drive enterprise procurement. Health authority submission gateways in Rockville, Maryland anchor regulatory technology development. Mid-market food and beverage manufacturers in Chicago and Minneapolis adopt multi-tenant SaaS platforms to compress approval cycles.
Germany
EU MDR traceability rules and immutable audit log requirements sustain demand for air-gapped installations. The national pharmaceutical regulator enforces technical documentation standards for every label revision. Bavarian medical device clusters around Munich deploy hybrid architectures processing sensitive data locally.
France
ANSM labeling directives and cosmetics packaging refresh cycles create dual demand streams. The national data protection authority shapes cloud deployment risk assessments for consumer goods brands. Parisian beauty and personal care headquarters drive modular subscription tier adoption for high-velocity SKU management.
Brazil
ANVISA serialization mandates for pharmaceutical track-and-trace expand sovereign data boundary requirements. The national health surveillance agency enforces supply chain visibility integration with artwork platforms. São Paulo-based multinational manufacturers prioritize single-tenant isolation for compliance-critical deployments.
Switzerland
Swissmedic inspection readiness standards and pharmaceutical quality assurance concentration elevate approval workflow module pricing. The national regulator mandates electronic signature protocols for technical documentation. Basel and Zurich clusters anchor premium-tier platform deployments for validation-ready systems.
Artwork Management Software Market Competitive Landscape
Top-tier vendors anchor enterprise-grade pharmaceutical deployments, while mid-market specialists capture consumer goods volume through modular subscription tiers. The vendor base stratifies across prepress-integrated incumbents, cloud-native challengers, and vertical specialists. Three archetypes dominate: packaging workflow incumbents with deep Adobe-Esko integration, SaaS-native platforms with browser-based proofing, and regulated-industry specialists with health authority submission gateways. Competitive moves concentrate on M&A for label-artwork convergence and API-first partnerships with ERP vendors.
Within the prepress-integrated tier, Esko and Loftware occupy positions sustained by packaging converter relationships and enterprise label management convergence. Kallik represents the regulated-industry specialist archetype with pharmaceutical validation heritage. Cloud-native challengers including ManageArtworks and Twona exemplify vertical specialization strategies targeting cosmetics and nutraceutical brands with tiered pricing for approval workflow modules.
| Leading Market Players |
|---|
| Cway |
| Loftware |
| ManageArtworks |
| GLAMS |
| Twona |
| Esko |
| Kallik |
| Seagull Scientific |
| Artwork Flow |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure costs cascade through SaaS pricing tiers, with United States-based hyperscaler fees compressing margins for mid-market vendors while German pharmaceutical buyers absorb premiums for air-gapped validation packages. Subscription versioning modules allow vendors to segment price-sensitive cosmetics brands from compliance-driven medical device manufacturers.
Pricing Analysis
Capacity additions in United States cloud regions are reshaping price floors for browser-based proofing platforms, forcing legacy on-premise vendors toward SaaS-tiered subscription models. Three-tier pricing structure across enterprise validation, professional workflow, and modular entry tiers separates FDA 21 CFR Part 11-ready pharmaceutical deployments from lightweight consumer goods implementations. Price differentiation hinges on electronic signature certification depth and health authority gateway integration. Cost compression in mid-market segments intensifies because SaaS-native challengers undercut incumbent maintenance contracts. Cosmetics and nutraceutical brands in France exhibit highest price sensitivity; Swiss pharmaceutical quality assurance teams show lowest.
Supply Chain Analysis
FDA 21 CFR Part 11 and EU MDR qualification gating concentrates certified engineering talent in Switzerland, Germany, and the United States, creating regional supply bottlenecks for validation-ready platform development. Cloud-native architectures draw from Amazon Web Services, Microsoft Azure, and Google Cloud infrastructure; on-premise deployments rest on Dell, HPE, and Lenovo server hardware with Oracle or SAP database licensing. Single-source vulnerability runs through Esko Automation Engine prepress integration for packaging converters. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and channel partners for mid-market consumer goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as pharmaceutical procurement committees shift specification weight toward AI-generated content provenance tracking and immutable audit architectures.
For Market Incumbents: Acquire specialized regulatory technology assets with EU AI Act disclosure lineage capabilities. Consolidate label-artwork convergence through API-first ERP partnerships to defend against SaaS-native challengers. Add validation engineering capacity in Basel and Zurich clusters to capture Swissmedic premium pricing. For New Entrants and Emerging Players: Enter via modular subscription tiers targeting underpenetrated Class II and III medical device manufacturers in the United States. White-space concentrates in Brazilian ANVISA serialization-integrated deployments and French cosmetics high-velocity SKU management. Go-to-market through vertical-specific compliance messaging rather than generic workflow efficiency. For Investors and Strategic Acquirers: Consolidation pressure builds where SaaS-native platforms achieve FDA validation parity with incumbent prepress-integrated vendors. Five-to-ten year viability favors vendors with health authority submission gateway relationships and pharmaceutical customer concentration. Target acquisition archetype: regulated-industry specialists with EU MDR technical documentation heritage. Watch for AI-generated content disclosure rule harmonization across FDA, EMA, and NMPA as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Captures EU AI Act provenance tracking capabilities for pharmaceutical compliance pipelines. |
| Platform Integration | Embeds artwork management within SAP and Oracle ERP ecosystems to reduce switching friction. |
| Geographic Expansion | Establishes sovereign data boundaries in Brazil for ANVISA serialization-mandated deployments. |
| Product Launch | Introduces AI-assisted content generation with automated disclosure audit trail capture. |
| Strategic Partnership | Links cloud-native proofing with Esko prepress automation for packaging converter retention. |
Research Methodology
Direct dialogue with pharmaceutical regulatory affairs directors, consumer goods brand managers, IT procurement officers at medical device manufacturers, and prepress operations heads grounded qualitative findings. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA technical documentation standards, EU AI Act transparency obligation drafts, and ANVISA serialization mandates. Bottom-up deployment sizing across cloud-native, on-premise, and hybrid architectures triangulated against top-down enterprise software spending patterns.
Segmentation outputs across deployment model, end-user vertical, organization size tier, and geographic regulatory cluster structured the analytical framework throughout the forecast period. CAGRs emerged from elasticity modeling of compliance mandate intensity against technology substitution curves. Pharmaceutical serialization integration velocity and AI-generated content disclosure rule adoption served as primary forecast inputs.
Inputs from health authority guidance publications and vendor pricing disclosures were available through the study window; gaps in mid-market food and beverage procurement intention surveys introduce uncertainty bands around consumer goods adoption trajectories. Forecasts reflect documented assumptions regarding EU MDR enforcement consistency and cloud infrastructure cost trajectories. A model refresh is warranted upon material change in FDA AI-generated content labeling requirements or ANVISA serialization deadline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Engineering Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Global Video Streaming Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Web Scraping Software Market
Software & Services
Custom Software Development Market
Software & Services
Automotive Customization Software Market
Software & Services
Programming Language Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Creative Software Market
Software & Services
Global Archiving Software Market
Software & Services
Global Database Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Vlog Editing Software Market
Software & Services
Quality Management Software Market