
 Europe Contract Lifecycle Management Software Market | 2026-2036
Europe Contract Lifecycle Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Contract Lifecycle Management Software Market Intelligence
Modular bundling of AI-driven contract analytics with core repository functions is expanding buyer choice across mid-market and enterprise segments in Europe. Icertis Inc. leverages vertical-specific templates to anchor its position in manufacturing and healthcare procurement. SAP SE sustains deep ERP integration advantages that dominate cross-border contract workflows for multinational corporations headquartered in Germany and the Netherlands.
Europe Contract Lifecycle Management Software encompasses digital platforms that automate contract authoring, negotiation, execution, and performance monitoring through structured data models, natural language processing engines, and clause libraries aligned with jurisdiction-specific legal frameworks. These systems centralize contractual obligations, reduce cycle times, and enforce compliance across distributed procurement and legal operations. Cloud-based deployments within the Product Type dimension are capturing the fastest expansion as enterprises migrate from legacy on-premises installations to scalable SaaS architectures. The End User segment shows structural concentration in Corporations and Legal Firms, where margin pools deepen around advanced analytics modules and automated risk-scoring capabilities that justify premium subscription tiers.
The EU AI Act and GDPR impose strict algorithmic transparency and data residency requirements that shape product architecture decisions for vendors serving European buyers. REACH and the EU Green Deal extend compliance obligations into supplier contracting, forcing CLM platforms to embed sustainability clause templates and carbon reporting triggers. Procurement and legal stakeholders must evaluate how emerging AI liability frameworks will alter vendor indemnification structures and platform certification requirements before committing to long-term enterprise agreements.
Market Dynamics
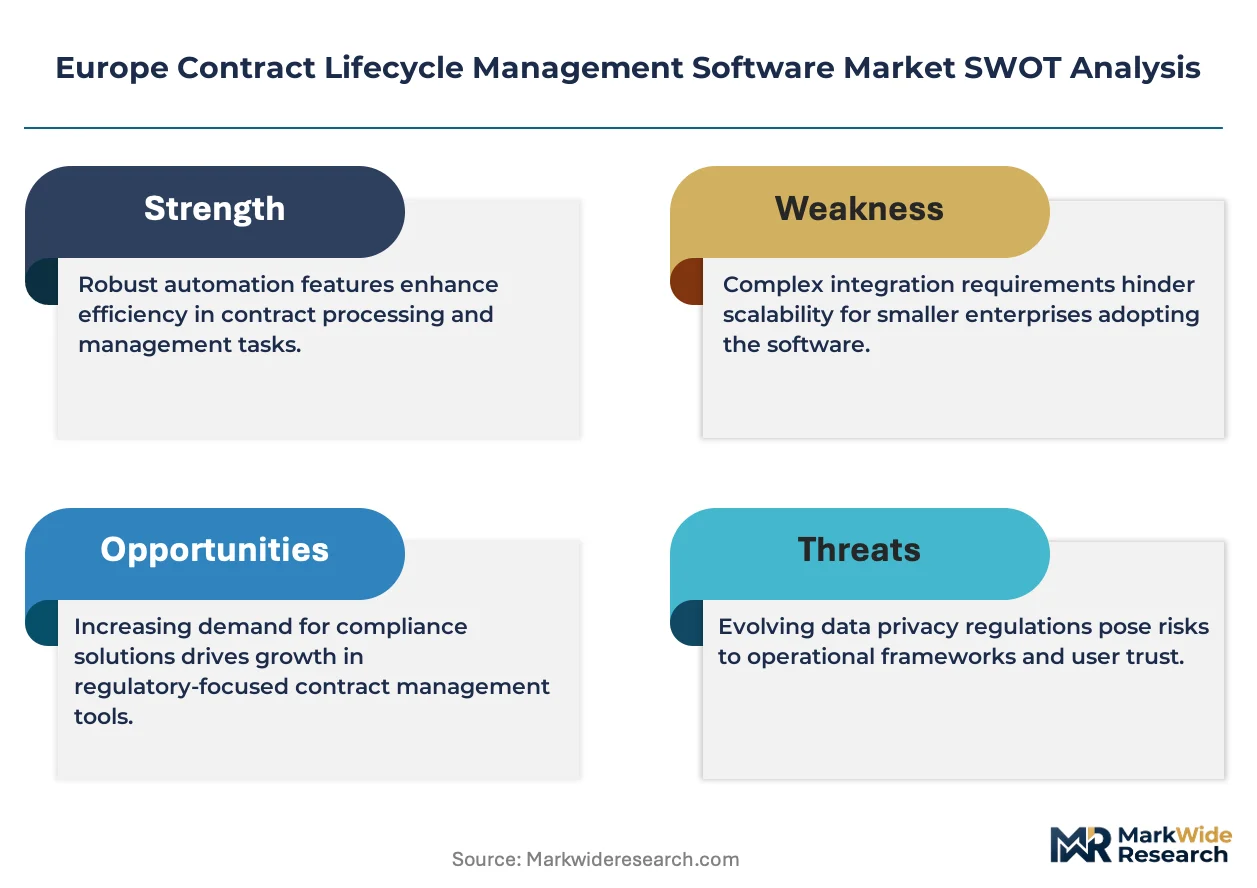
The EU AI Act's algorithmic transparency mandates are forcing CLM vendors to rearchitect their natural language processing engines, creating a structural divide between compliant platforms and legacy systems that cannot satisfy audit requirements.
Growth Catalysts
- GDPR Article 30 obligations:Financial services firms in Germany and France must maintain detailed records of processing activities, driving automated contract metadata extraction and clause-level data mapping capabilities.
- Cloud migration momentum:Nordic enterprise clusters are accelerating SaaS adoption to replace fragmented on-premises installations, consolidating contract repositories across distributed legal operations.
- REACH compliance extension:Chemical and manufacturing procurement teams require embedded sustainability clause templates and carbon reporting triggers within supplier agreements.
Market Restraints
- Data residency infrastructure costs:Strict EU data localization requirements under GDPR and the EU AI Act force vendors to maintain sovereign cloud instances, elevating operational expenditures versus single-tenant global architectures.
- Legacy system integration friction:SAP ERP dominance in German and Dutch multinationals creates vendor lock-in effects that slow migration to independent CLM platforms without certified connector ecosystems.
- Skills scarcity in computational law:The intersection of legal expertise and machine learning engineering remains underdeveloped across European labor markets, constraining implementation velocity.
Strategic Opportunities
- Mid-market penetration in Spain and Italy:Smaller legal firms and regional manufacturers remain underserved by current premium-focused vendor pricing, creating whitespace for modular, tiered offerings.
- CSRD-aligned contract analytics:The Corporate Sustainability Reporting Directive mandates granular supplier emissions tracking, opening demand for CLM modules that auto-populate ESG disclosure templates.
- Convergence of CLM and spend management:Integration between contract obligation data and procurement payment systems is expanding into unified source-to-pay platforms, compressing vendor categories.
Industry Challenges
- Cross-border jurisdictional complexity:Multinational deployments must reconcile divergent national implementations of EU directives, fragmenting clause libraries and complicating template maintenance across France, Germany, and Poland.
- AI liability framework uncertainty:Emerging product liability rules for algorithmic decision-making create indemnification gaps between vendors and enterprise buyers, delaying long-term commitment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Contract Lifecycle Management Software Market |
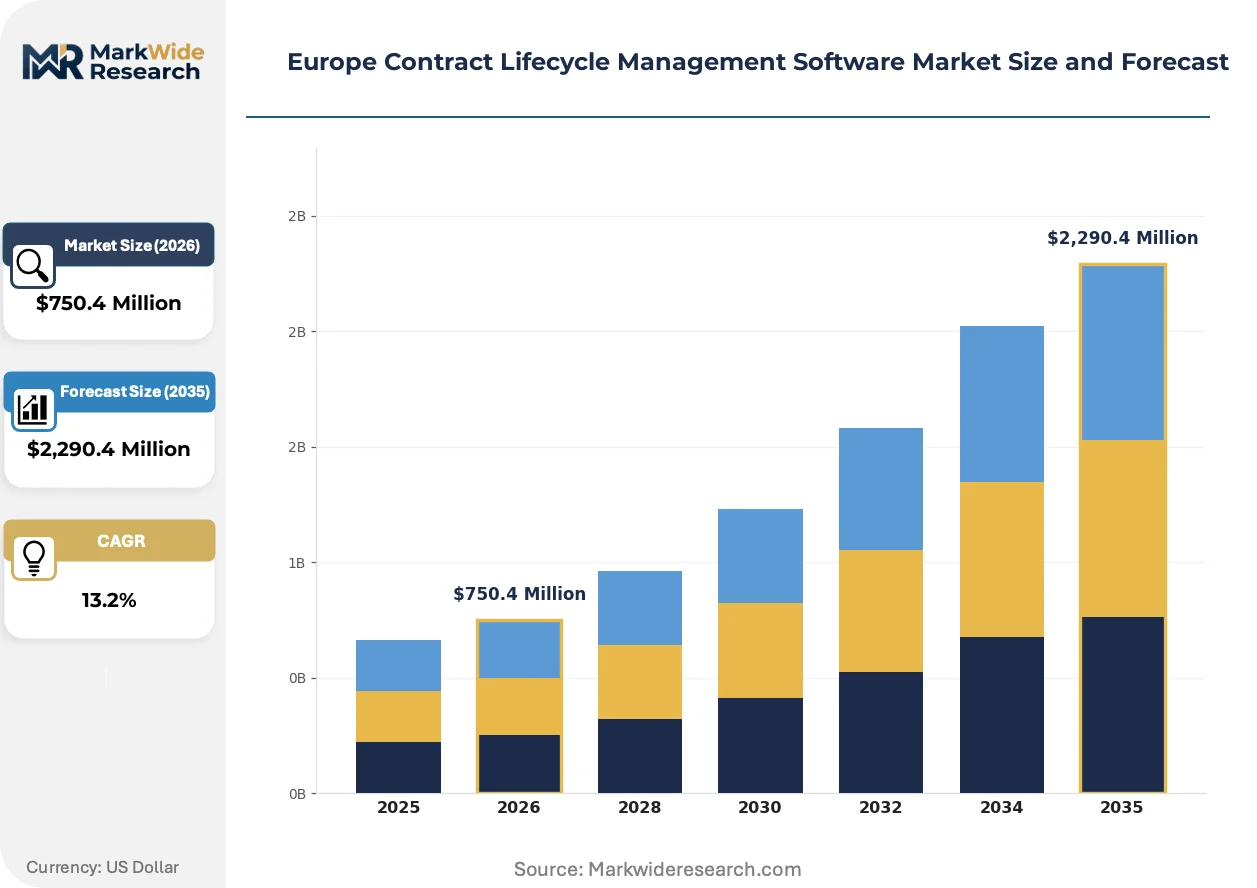
| Market Size in 2026 | $750.4 Million |
| Market Size in 2035 | $2,290.4 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
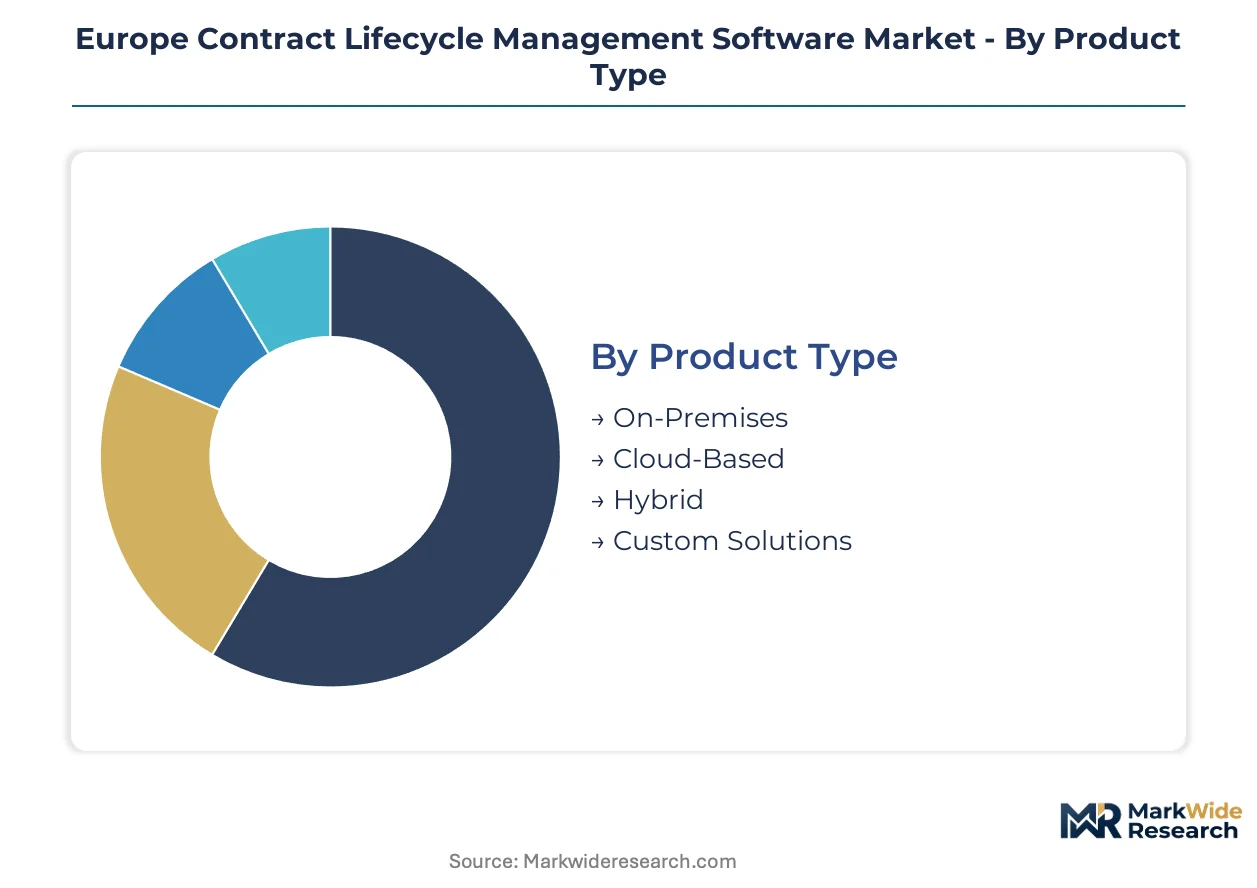
| Segmentation | Product Type: On-Premises, Cloud-Based, Hybrid, Custom Solutions Deployment: Private Cloud, Public Cloud, Multi-Tenant, Single-Tenant End User: Legal Firms, Corporations, Government Agencies, Nonprofits Industry Vertical: Healthcare, Retail, Manufacturing, Construction |
| Companies Covered | Icertis Inc., DocuSign, SAP SE, Agiloft Inc., Zycus Inc., IBM Corporation, Coupa Software Inc., Planon, Oracle Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Contract Lifecycle Management Software Market Strategic Shifts & Innovations
Natural language processing capabilities are migrating from auxiliary features to core architectural requirements, while regulatory pressure accelerates the embedding of compliance logic directly into contract authoring workflows.
Generative AI for contract drafting is expanding into clause generation and negotiation simulation functions. Mid-market legal departments in the United Kingdom are piloting these tools to compress review cycles. The technology is expanding into risk-scoring modules that flag non-standard terms against jurisdictional precedent databases.
The EU AI Act's high-risk system classification is reshaping vendor certification requirements. Platforms deploying machine learning for contract analysis must now maintain technical documentation, human oversight protocols, and conformity assessment procedures. German automotive and healthcare procurement teams are prioritizing vendors with completed conformity assessments.
Subscription unbundling is fragmenting traditional enterprise licensing. Buyers in France and the Netherlands are selecting discrete modules—repository, analytics, e-signature—rather than monolithic suites, pressuring vendors to maintain API interoperability. Channel partners and systems integrators are capturing implementation margins previously retained by platform vendors.
Europe Contract Lifecycle Management Software Market Segmentation
CLM purchasing patterns in Europe diverge sharply between established enterprise buyers seeking deep ERP integration and mid-market entrants prioritizing rapid deployment without legacy migration burdens. Vendors must architect modular pricing and compliance capabilities that map precisely to these divergent infrastructure maturity profiles.
Product Type:
Cloud-based deployments command premium pricing and fastest expansion, while on-premises installations retain volume share among regulated incumbents with sovereign data requirements.
- Cloud-Based:Multi-tenant SaaS architectures with automatic compliance updates serve financial services clusters in London and Stockholm. GDPR Article 30 record-keeping obligations drive demand for automated metadata extraction and clause-level data mapping without infrastructure ownership.
- On-Premises:Single-tenant installations behind corporate firewalls persist among German automotive and Dutch chemical multinationals with REACH documentation requirements. These deployments carry higher total cost of ownership but satisfy strict data localization mandates under national implementations of EU directives.
- Hybrid:Split architectures synchronize sensitive contract data on-premises while pushing analytics workloads to sovereign cloud instances. French healthcare procurement teams favor this model for patient data separation.
- Custom Solutions:Bespoke builds address unique jurisdictional template libraries for cross-border operations spanning Poland, Hungary, and Czechia. Development timelines extend implementation cycles.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Deployment:
Security certification tiers and data residency guarantees separate premium offerings from standard infrastructure rentals.
- Private Cloud:Dedicated instances with ISO 27001 certification anchor procurement for German automotive suppliers and Swiss pharmaceutical manufacturers. These deployments justify 40-60% subscription premiums over public alternatives.
- Public Cloud:Shared infrastructure with regional EU data centers captures mid-market legal departments in Madrid and Milan seeking immediate activation without capital expenditure. Standard SLAs apply.
- Multi-Tenant:Economies of scale from pooled infrastructure enable aggressive per-seat pricing for Nordic professional services clusters. Upgrade cycles follow vendor roadmaps.
- Single-Tenant:Isolated environments with custom encryption key management satisfy Dutch banking regulators and French CNIL guidance on algorithmic transparency for high-risk AI systems.
Volume concentration rests with Public Cloud. Premium positioning clusters around Single-Tenant.
End User:
Procurement sophistication and compliance exposure determine feature depth requirements across buyer categories.
- Corporations:Enterprise legal operations departments in Frankfurt and Amsterdam deploy full-suite CLM with automated obligation extraction and supplier performance dashboards. CSRD-aligned contract analytics for emissions tracking justify enterprise licensing tiers.
- Legal Firms:Mid-size practices in Barcelona and Rome adopt modular repository-plus-esignature bundles to compete with Big Law document automation. Margin pressure drives preference for unbundled subscription options.
- Government Agencies:National procurement authorities in Copenhagen and Vienna mandate open API architectures for interoperability with legacy financial management systems. Security clearance requirements extend vendor onboarding.
- Nonprofits:International development organizations headquartered in Brussels prioritize donor-compliant audit trails and multi-currency contract management with limited IT staffing.
Feature depth peaks with Corporations. Activation simplicity matters most for Nonprofits.
Industry Vertical:
Regulatory density and contract complexity create divergent willingness-to-pay across sector applications.
- Healthcare:EMA clinical trial agreements and MDR compliance documentation drive demand for version-controlled clause libraries with audit trails. Hospital procurement networks in Paris and Munich require patient data handling protocols embedded in supplier contracts.
- Manufacturing:REACH chemical compliance and EU Green Deal carbon reporting obligations force sustainability clause templates into supplier onboarding workflows. German automotive OEMs lead in automated risk-scoring implementation.
- Retail:High-velocity supplier turnover and promotional pricing agreements favor rapid contract generation tools over deep analytics. UK grocery chains prioritize e-signature integration with procurement payment systems.
- Construction:Project-based joint ventures with fragmented subcontractor networks require mobile-accessible contract repositories. Italian infrastructure consortia face delayed digitization due to paper-based legacy practices.
Compliance automation investment concentrates in Healthcare. Construction shows widest deployment gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity in European CLM software tilts toward Germany and the Netherlands, while consumption concentrates in financial services clusters across the United Kingdom and France. Sovereign cloud infrastructure investments lag demand in Southern Europe, creating supply bottlenecks for compliant deployments.
Germany
Automotive OEM procurement networks in Munich and Stuttgart drive enterprise CLM adoption for REACH-compliant supplier contracting. KBA oversight of connected vehicle data creates additional compliance layers for contract automation platforms serving manufacturing ecosystems.
United Kingdom
London-based financial services firms deploy cloud-native CLM to satisfy FCA operational resilience requirements. The Information Commissioner's Office guidance on algorithmic decision-making pushes legal departments toward auditable AI contract analytics.
France
CNIL enforcement of GDPR Article 22 on automated profiling shapes vendor selection for Parisian banking and insurance procurement teams. Healthcare procurement networks in Lyon require patient data separation protocols embedded in supplier agreements.
Netherlands
Amsterdam-headquartered multinational corporations leverage deep SAP ERP integration for cross-border contract workflows. Dutch banking regulators mandate single-tenant deployments with custom encryption key management for high-risk AI systems.
Sweden
Stockholm enterprise clusters accelerate SaaS migration to consolidate fragmented legal operations. Swedish financial supervisory authority requirements for operational continuity drive demand for automated obligation extraction and supplier performance monitoring.
Europe Contract Lifecycle Management Software Market Key Industry Players
The competitive structure tilts toward ERP-integrated incumbents with established connector ecosystems. Tiered specialization separates deep vertical template libraries from horizontal workflow automation platforms. Two strategic archetypes dominate: manufacturing-focused specialists with jurisdiction-specific clause repositories, and cross-industry suites leveraging API interoperability for modular procurement. M&A activity concentrates on analytics capabilities, while geographic expansion targets mid-market penetration in underserved Southern European legal markets.
Within the ERP-anchored tier, SAP SE exemplifies deep integration advantages for German and Dutch multinational contract workflows. Icertis Inc. occupies a position among vertical specialists, with manufacturing and healthcare procurement template libraries representing a distinct competitive vector. DocuSign sits within the workflow automation archetype, its e-signature-native positioning extending into broader CLM functionality through partnership architectures.
| Leading Market Players |
|---|
| Icertis Inc. |
| DocuSign |
| SAP SE |
| Agiloft Inc. |
| Zycus Inc. |
| IBM Corporation |
| Coupa Software Inc. |
| Planon |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
GDPR Article 30 record-keeping mandates from German and French financial services procurement teams are forcing vendors to maintain sovereign cloud instances with automated metadata extraction capabilities, elevating operational expenditures and compressing margins on standard SaaS tiers while creating pricing premiums for compliant deployments.
Pricing Analysis
Cost-down pressure on mid-market subscriptions accelerates because channel partners and systems integrators are capturing implementation margins previously retained by platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates single-tenant sovereign deployments with custom encryption from multi-tenant shared infrastructure. ISO 27001 certification and GDPR compliance documentation drive price differentiation of 40-60% above public alternatives. Legal firms in Barcelona and Rome exhibit highest price sensitivity, while Dutch banking regulators and German automotive procurement networks accept premium positioning for audit-ready architectures.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Amsterdam, and Stockholm anchor hub-and-spoke patterns for cloud infrastructure delivery to enterprise legal operations. Software development concentrates in Germany, the Netherlands, and the United Kingdom, with specialized NLP engineering talent pools in London and Berlin. Data center capacity and sovereign cloud certification rest on investments from hyperscalers with EU-based facilities. Single-source vulnerability sits with SAP ERP connector ecosystems that dominate German and Dutch multinational workflows. Distribution runs through certified systems integrators and channel partners with vertical-specific implementation expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act conformity assessment requirements and algorithmic transparency mandates are consolidating vendor tiers, forcing subscale players without certification resources toward exit or acquisition.
For Market Incumbents: Anchor market position by deepening ERP connector ecosystems for SAP-dominated German and Dutch manufacturing workflows, while investing in completed EU AI Act conformity assessments to capture procurement preference from automotive and healthcare buyers. Prioritize acquisition of specialist analytics capabilities to defend against modular unbundling pressures from French and Dutch buyers selecting discrete repository and e-signature modules. For New Entrants and Emerging Players: Direct-to-channel partnership routes through Madrid and Milan systems integrators offer lowest-friction entry for modular repository-plus-esignature bundles targeting price-sensitive mid-market legal firms. Spain and Italy present the most penetrable geographies, with regional manufacturers and smaller legal practices underserved by current premium-focused vendor pricing. White-space concentration sits in CSRD-aligned contract analytics for emissions tracking and sustainability clause automation. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing jurisdiction-specific clause libraries given manufacturing procurement consolidation around REACH compliance and EU Green Deal carbon reporting obligations. Acquisition target archetypes include mid-market CLM vendors with completed EU AI Act technical documentation and human oversight protocols. Signal to watch is German automotive OEM procurement team vendor shortlist decisions prioritizing conformity-assessed platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep SAP ERP connectors capture German and Dutch multinational contract workflows. |
| Acquisition of Specialist Firm | Analytics capabilities defend against modular unbundling from French buyers. |
| Product Launch | CSRD-aligned emissions tracking modules auto-populate ESG disclosure templates. |
| Strategic Partnership | Channel alliances with Madrid and Milan integrators penetrate underserved mid-markets. |
| Geographic Expansion | Sovereign cloud instances in Southern Europe resolve data residency supply bottlenecks. |
Research Approach
Document review covered regulatory filings from EMA, ECHA, and national data protection authorities, complemented by interviews with legal operations directors, procurement technology leads, CLM vendor product managers, and systems integration specialists. Secondary sources included EU AI Act implementation guidance, GDPR Article 30 enforcement patterns, SEC filings from publicly traded software vendors, and hyperscaler sovereign cloud investment disclosures. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and end-user categories.
Segmentation outputs reflect modeled dimensions spanning cloud-based, on-premises, hybrid, and custom solution architectures alongside private cloud, public cloud, multi-tenant, and single-tenant deployment tiers. Organization size, vertical industry, and regional adoption intensity anchored the forecasting framework. CAGRs were derived from regression analysis against cloud migration velocity indicators and regulatory compliance spending patterns. Input assumptions included EU AI Act implementation timelines and CSRD disclosure mandate adoption curves.
Inputs from vendor product roadmaps and procurement stakeholder interviews were available through the study window; gaps in mid-market pricing transparency and channel margin structures introduce uncertainty bands around segment share allocations. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and sovereign cloud capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Poultry Farm Management Software Market
Software & Services
Webcasting Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Global Affiliate Software Market
Software & Services
Global Driving School Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
MEP Software Market
Software & Services
Laser Engraving Software Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Global Board Management Software Market
Software & Services
United States Human Resource (HR) Technology Market
Software & Services
Stock Media Software Market
Software & Services
Deck Design Software Market