
 Global Script Writing Software Market | 2026-2036
Global Script Writing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Script Writing Software Market Foresight
ISO/IEC 25010 software quality certification is unwinding competitive barriers for entrants seeking enterprise credibility. Final Draft leverages decades of format standardization to sustain its position among Hollywood guild members. WriterDuet anchors its growth on real-time cloud synchronization for remote writer rooms. Celtx competes through freemium penetration among film schools and emerging content creators.
Script writing software comprises digital authoring environments that enforce industry-standard formatting rules—such as Courier 12pt font, one-inch margins, and scene heading hierarchies—while managing revision metadata and character dialogue continuity for audiovisual production workflows. Cloud-based deployment leads solution type adoption as distributed production teams require simultaneous editing access across time zones; integrated writing suites capture expanding margin pools by bundling storyboarding and scheduling functions that standalone formatting tools cannot match. Professional screenwriters and production studios represent the most concentrated end-user revenue segment, though educational institutions show accelerating uptake as university film programs standardize digital curricula.
FCC content labeling requirements in the United States, GDPR data residency rules across European member states, and the EU AI Act's transparency obligations for generative content tools collectively reshape product architecture and market access conditions for script software vendors. Stakeholders must monitor how emerging copyright frameworks treat AI-assisted screenplay generation and whether guild collective bargaining agreements restrict tool usage in contracted writing work.
Market Dynamics
Cloud-based collaboration platforms are compressing the competitive window for legacy desktop script writing tools, as distributed production teams in Los Angeles, Mumbai, and London demand simultaneous real-time editing access across time zones.
Growth Catalysts
- EU AI Act transparency mandates:Content provenance requirements for generative tools are accelerating vendor investment in audit-trail features that enterprise studios now require for compliance.
- Film school curriculum digitization:University programs in California, Maharashtra, and the United Kingdom are standardizing cloud-based script platforms as core teaching infrastructure.
- Remote writer room normalization:Post-pandemic production workflows have permanently shifted toward distributed creative teams requiring synchronized revision tracking.
Market Restraints
- Data residency fragmentation:GDPR requirements across European member states force costly infrastructure duplication that compresses margins for mid-tier vendors.
- Guild collective bargaining restrictions:Writers Guild of America and similar labor agreements in multiple jurisdictions limit permissible automation in contracted screenplay work.
- Format standardization lock-in:Decades of Final Draft format dominance create switching costs that entrench incumbent positions.
Strategic Opportunities
- Brazilian content production expansion:ANCINE-backed local content quotas are driving studio investment in Portuguese-language script collaboration tools.
- AI-assisted pre-visualization convergence:Integration between script platforms and generative storyboarding tools opens bundled pricing power.
- South Korean webtoon adaptation pipelines:CJ ENM and Kakao Entertainment verticals require specialized formatting for serialized multimedia content.
Industry Challenges
- ISO/IEC 25010 certification timelines:Enterprise sales cycles now require 12-18 month quality validation periods that delay revenue recognition.
- Copyright attribution complexity:AI-assisted dialogue generation creates unresolved authorship disputes that studios hesitate to underwrite.
- Legacy system integration friction:Production management tools from scheduling and budgeting vendors resist API standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Script Writing Software Market |
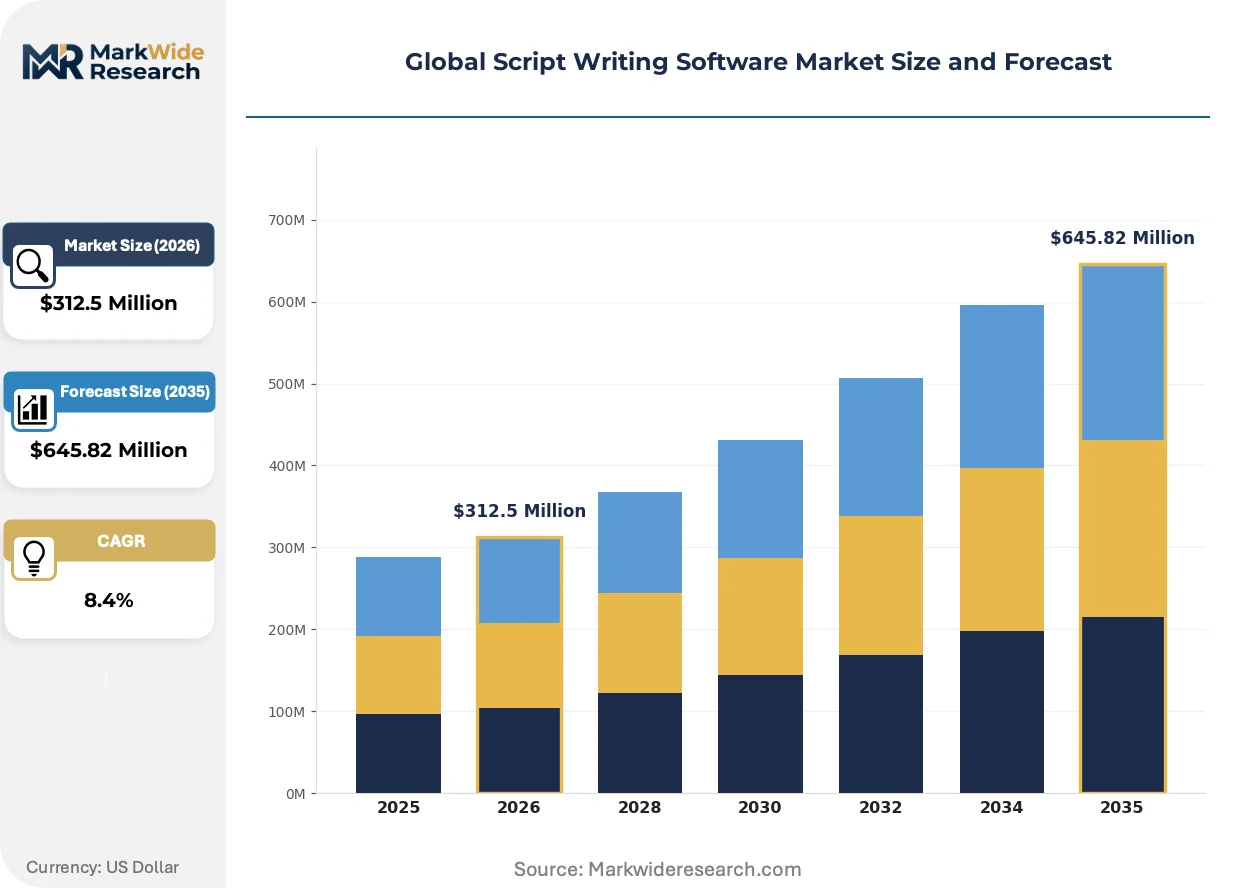
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Desktop Solution Type: Standalone Software, Integrated Writing Suite, Collaboration Platform, Script Formatting Tool, Storyboarding Software Use Case: Film Production, Television Series, Video Game Development, Theatre Playwriting, Podcast Scriptwriting End User: Professional Screenwriters, Independent Filmmakers, Content Creators, Educational Institutions, Production Studios |
| Companies Covered | Final Draft, WriterDuet, Celtx, StudioBinder, Fade In, Arc Studio, Scrivener, GCC Production, Write Brothers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Script Writing Software Market Shifts & Advancements
Generative content capabilities are forcing a structural repositioning of script writing software from passive formatting utilities toward active creative partners, reshaping vendor R&D priorities and buyer evaluation criteria.
Large language model integration is supplanting static autocomplete functions in professional screenwriting workflows. Studio technical buyers in Los Angeles and London are piloting these tools for first-draft scene generation. The technology is supplanting traditional research assistant roles and compressing pre-production timelines by an estimated 30-40% in early deployments.
The EU AI Act's transparency obligations for generative content tools are mandating embedded provenance metadata in all exported script files. Vendors must now architect audit-trail systems that track human versus machine contribution percentages. European production houses are responding by requiring ISO-certified compliance documentation before platform procurement approval.
Subscription fatigue among independent screenwriters is fragmenting demand toward modular, usage-based pricing. Freelance writers in Canada and Australia are abandoning annual commitments for per-project platform access. This behavioral shift is most visible in the sub-$50,000 budget independent film segment, where creators cycle between three to four platforms annually based on specific project requirements.
Global Script Writing Software Market Segmentation
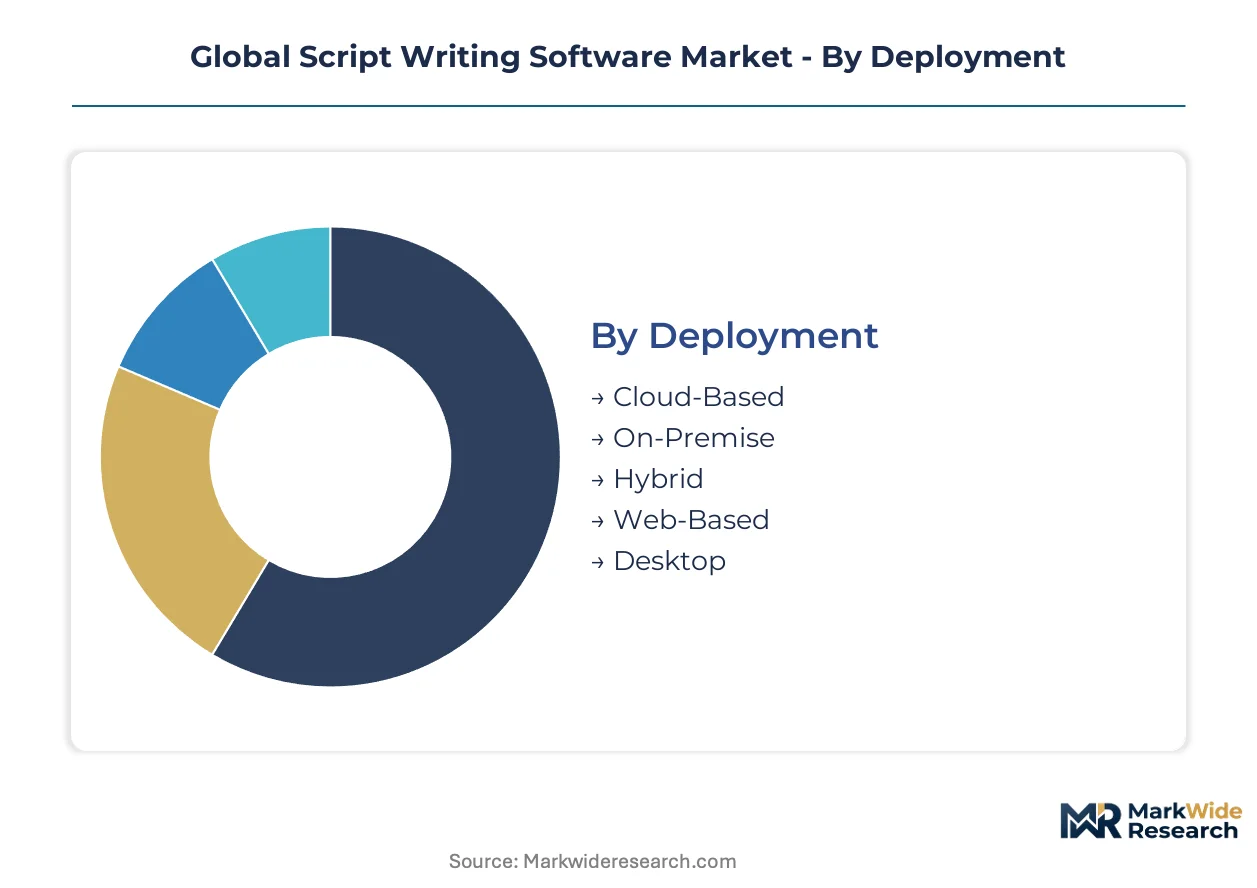
Segmentation in script writing software reveals how deployment architecture, solution bundling, and user sophistication create distinct purchasing behaviors. Channel strategy varies sharply across these dimensions, with enterprise studios demanding ISO-certified cloud platforms while freelancers cycle through lightweight web tools.
Deployment:
Channel economics diverge sharply by deployment model, with cloud-based solutions flowing through direct vendor sales and hybrid deployments requiring systems integrator partnerships.
- Cloud-Based:Multi-tenant SaaS architectures enable real-time synchronization for distributed writer rooms across Los Angeles, Mumbai, and London. Demand concentrates among production studios with cross-border co-productions, driven by GDPR-compliant EU data residency requirements that force regional infrastructure investment.
- On-Premise:Air-gapped installations serve defense-contracted content producers and sensitive IP environments in Burbank and Culver City. Major studios with established IT security protocols favor this model despite higher total cost of ownership, constrained by ISO/IEC 25010 certification timelines that stretch procurement cycles.
- Hybrid:Split architectures allow local rendering with cloud backup for mid-tier independent producers. Named demand centers on Canadian and Australian regional film funds.
- Web-Based:Browser-native platforms eliminate installation friction for educational institutions standardizing curricula across Maharashtra and California university systems.
- Desktop:Legacy perpetual-license tools retain guild-member loyalty through decades of format standardization lock-in.
By volume, cloud-based deployment leads. By growth pace, hybrid architectures are climbing the fastest as security-conscious studios seek middle-ground flexibility.
Solution Type:
Margin structures stratify by solution complexity, with integrated suites capturing expanding service revenue pools that standalone formatting tools cannot access.
- Integrated Writing Suite:Bundled environments combine script formatting, storyboarding, and production scheduling in unified workflows. Demand concentrates at Warner Bros. Discovery and Disney production verticals, driven by compressed pre-production timelines requiring 30-40% efficiency gains from tool consolidation.
- Collaboration Platform:Real-time multi-user editing with revision metadata tracking serves remote writer rooms normalized post-pandemic. Netflix and Amazon Studios content slates in London and Madrid anchor adoption, constrained by Writers Guild of America collective bargaining restrictions on permissible automation.
- Standalone Software:Single-purpose formatting tools retain price-sensitive independent screenwriters through perpetual licensing models.
- Script Formatting Tool:Lightweight utilities target podcast scriptwriters and YouTube content creators with sub-$50,000 production budgets.
- Storyboarding Software:Visual pre-visualization modules integrate with script platforms for Korean webtoon adaptation pipelines at CJ ENM and Kakao Entertainment.
Integrated suites command premium pricing. Collaboration platforms are expanding most quickly as distributed production becomes permanent.
Use Case:
Application-specific requirements reshape feature prioritization, with film and television demanding guild-compliant formatting while gaming and podcasting drive innovation in nonlinear narrative structures.
- Film Production:Feature-length screenplay workflows require strict adherence to Academy and BAFTA submission standards. Studio technical buyers in Los Angeles pilot generative scene generation, navigating unresolved copyright attribution complexity for AI-assisted dialogue.
- Television Series:Serialized content with rotating writer rooms demands robust version control and character continuity tracking across 10-24 episode seasons. Mumbai-based production houses with ANCINE-backed Brazilian co-productions anchor regional growth.
- Video Game Development:Branching narrative architectures with conditional dialogue trees require specialized tools distinct from linear screenplay formats.
- Theatre Playwriting:Stage direction and cue integration features serve Lincoln Center and Royal National Theatre production workflows.
- Podcast Scriptwriting:Audio-first formatting with timestamp notation targets independent creators cycling through per-project platform subscriptions.
Film production maintains revenue concentration. Video game development shows the steepest expansion trajectory as interactive narrative budgets scale.
End User:
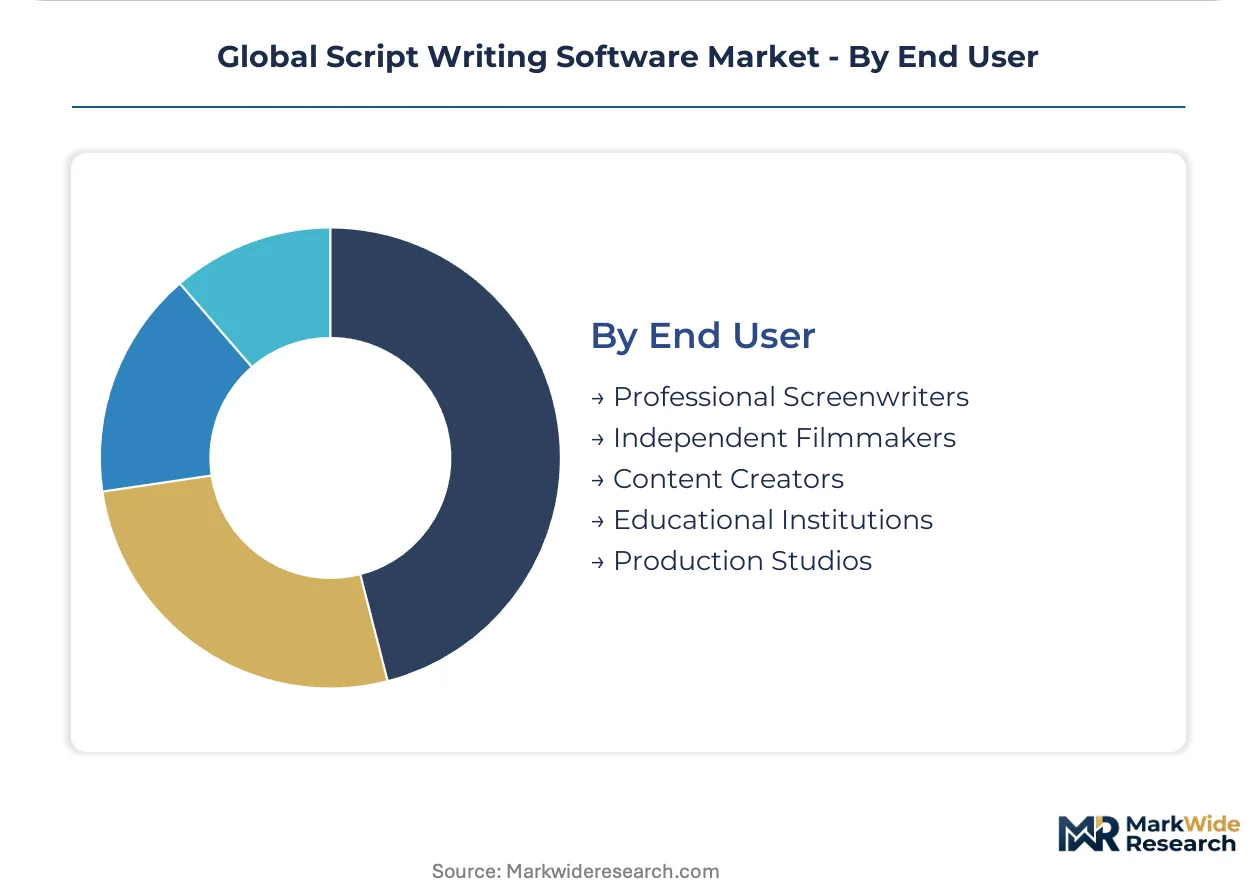
Customer type determines contract structure, with educational institutions demanding multi-seat academic licensing and professional screenwriters driving modular, usage-based purchasing fragmentation.
- Professional Screenwriters:Guild-affiliated writers with WGA, WGGB, or AWG membership require format-standardized tools for contracted studio work. Subscription fatigue among Canadian and Australian freelancers is fragmenting demand toward per-project access models.
- Production Studios:Enterprise procurement teams at major entertainment conglomerates mandate ISO-certified platforms with EU AI Act compliance documentation before approval.
- Independent Filmmakers:Sub-$1 million budget producers prioritize cost efficiency over feature depth, cycling through three to four platforms annually.
- Content Creators:YouTube and TikTok scriptwriters with sub-$50,000 budgets favor freemium penetration models from Celtx and similar vendors.
- Educational Institutions:University film programs in California, Maharashtra, and the United Kingdom standardize cloud-based platforms as core teaching infrastructure.
Production studios dominate revenue contribution. Educational institutions are gaining share fastest as curriculum digitization accelerates globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Studio procurement teams in Los Angeles and Mumbai anchor enterprise demand for script writing software, with educational institutions in California and Maharashtra driving freemium adoption curves.
United States
Warner Bros. Discovery and Disney production verticals mandate ISO-certified cloud platforms with embedded audit trails. FCC content labeling requirements reshape product architecture for domestic distribution. Los Angeles-based writer rooms pilot generative scene generation tools under WGA collective bargaining constraints.
United Kingdom
Netflix and Amazon Studios content slates in London anchor adoption of real-time collaboration platforms. GDPR data residency rules force regional infrastructure investment from SaaS vendors. BAFTA submission standards maintain format standardization requirements that entrench incumbent tool positions.
India
Maharashtra-based production houses with ANCINE-backed Brazilian co-productions drive cross-border platform requirements. University film programs in Mumbai standardize cloud-based curricula. Mumbai and Bengaluru clusters concentrate both studio procurement and educational institution demand.
Germany
EU AI Act transparency obligations mandate provenance metadata in exported script files. Berlin-based independent producers seek hybrid deployment architectures balancing security with collaboration. German public broadcasters require ISO/IEC 25010 certification documentation before procurement approval.
South Korea
CJ ENM and Kakao Entertainment verticals require specialized formatting for webtoon adaptation pipelines. Seoul-based production teams integrate script platforms with generative storyboarding tools. Korean content export growth drives platform localization requirements across Southeast Asian markets.
Global Script Writing Software Market Competitive Landscape
Player mix skews toward legacy format standardizers and cloud-native collaboration specialists competing for overlapping enterprise and freelance segments. Market structure shows moderate consolidation around guild-affiliated incumbents with decades of Hollywood penetration, while mid-tier vendors fragment across educational and independent filmmaker niches. Two strategic archetypes dominate: format gatekeepers leveraging decades of standardization lock-in, and real-time synchronization platforms capturing remote writer room demand. Competitive moves center on ISO certification investment for enterprise credibility and AI-assisted feature integration for differentiation.
Within the legacy standardization tier, Final Draft exemplifies format gatekeeper positioning through decades of Hollywood guild penetration. WriterDuet and Celtx occupy the cloud-native collaboration vector, with the former anchoring real-time synchronization capabilities and the latter exemplifying freemium penetration models among educational institutions. These three companies collectively represent the strategic spectrum from entrenched incumbent to agile challenger archetypes.
| Leading Market Players |
|---|
| Final Draft |
| WriterDuet |
| Celtx |
| StudioBinder |
| Fade In |
| Arc Studio |
| Scrivener |
| GCC Production |
| Write Brothers |
| Others |
Supply & Pricing Matrix
Cloud infrastructure substitution for on-premise server farms simultaneously concentrates vendor hosting costs in United States, Ireland, and Singapore data center clusters while compressing per-seat SaaS pricing elasticity for mid-tier script software vendors competing against hyperscaler-backed platforms.
Pricing Analysis
Annual subscription contracts indexed to ISO/IEC 25010 certification tiers dominate enterprise procurement at Warner Bros. Discovery and Disney verticals. Price differentiation hinges on audit-trail feature depth and EU AI Act compliance documentation bundled into premium tiers. Cost compression in the independent filmmaker segment intensifies because Celtx and Arc Studio freemium models erode paid conversion rates. Freelance screenwriters in Canada and Australia exhibit highest price sensitivity, cycling through per-project licenses, while production studios with WGA-contracted writer rooms show lowest sensitivity due to format lock-in switching costs.
Supply Chain Analysis
Just-in-time provisioning of GPU compute capacity for generative AI features contrasts with strategic stockpiling of legacy format conversion libraries by Final Draft and Write Brothers. Cloud infrastructure supply concentrates in United States, Ireland, and Singapore. Software dependencies rest on open-source parsing engines, proprietary Courier font licensing, and LLM API access from hyperscaler partners. Single-source vulnerability runs through AWS and Azure dominance in studio-preferred hosting regions. Distribution runs through direct vendor sales for enterprise accounts and self-service web portals for educational institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated production studio procurement teams at Warner Bros. Discovery, Netflix, and Disney, fragmenting pricing leverage previously held by individual guild-affiliated writers.
For Market Incumbents: Secure ISO/IEC 25010 certification ahead of 12-18 month enterprise sales cycles to defend against cloud-native challengers. Deepen backward integration into generative storyboarding tools to capture bundled pricing power that standalone formatting vendors cannot match. For New Entrants and Emerging Players: Lead with modular, usage-based pricing targeting subscription-fatigued independent screenwriters in Canada and Australia. Brazilian content production expansion under ANCINE quotas offers the most penetrable geography. Anchor go-to-market through film school curriculum partnerships in Maharashtra and California. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed collaboration platform specialists lacking AI-assisted feature roadmaps. Long-term viability centers on convergence between script environments and pre-visualization tools. Watch for WGA collective bargaining agreement amendments restricting permissible automation as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 25010 Certification Investment | Enterprise procurement teams at Disney mandate certification documentation before platform approval. |
| Generative AI Feature Integration | Studio technical buyers in Los Angeles pilot LLM-assisted scene generation for 30-40% timeline compression. |
| Film School Curriculum Partnership | University programs in California and Maharashtra standardize cloud platforms as core teaching infrastructure. |
| EU AI Act Compliance Architecture | European production houses require embedded provenance metadata tracking human versus machine contributions. |
| Hybrid Deployment Architecture Launch | Berlin-based independent producers seek middle-ground flexibility between security and collaboration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory databases, and guild collective bargaining agreements. Primary interviews engaged CTOs at production studios, IT procurement officers at streaming platforms, platform engineers at SaaS vendors, and film school curriculum directors. Secondary validation drew from Writers Guild of America contract documentation, EU AI Act transparency obligation drafts, and ISO certification registry records. Bottom-up deployment model sizing triangulates against top-down entertainment industry technology spending estimates.
Segmentation dimensions modeled include deployment architecture, solution bundling complexity, end-user sophistication tier, and regional regulatory framework clusters across the projection horizon. CAGRs derive from trend extrapolation of cloud adoption curves and generative AI feature penetration rates. Industry-specific forecast inputs incorporate WGA collective bargaining automation restrictions and ANCINE-backed Brazilian content quota enforcement timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement intensity or WGA automation restriction amendments would require recalibration. Forecasts reflect assumptions of continued cloud infrastructure cost decline and persistent format standardization lock-in. Revision becomes warranted when generative content provenance litigation volume crosses thresholds that deter studio AI feature adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Governance Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Technology CAD Software Market
Software & Services
Trading Software Market
Software & Services
Human Resource Management Software Market
Software & Services
User Research Repositories Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
Global Spa and Salon Software Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Global Forestry Software Market
Software & Services
Camp Management Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Global Software Resellers Market
Software & Services
Telecom Billing Software Market
Software & Services
Global Retail Inventory Management Software Market