
 Cold Storage AGV Market | 2026-2036
Cold Storage AGV Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Storage AGV Market Analytics
Pharmaceutical distributors are rotating toward fully automated cold storage fulfillment as labor constraints and traceability requirements intensify. Daifuku leverages its deep integration with high-bay warehouse systems to anchor large-scale frozen pharmaceutical projects across Asia. Dematic competes through dense shuttle-based architectures that sustain throughput in sub-zero environments. Swisslog differentiates via software-layer orchestration that controls multi-temperature-zone AGV fleets from a single platform.
Cold storage AGVs are battery-powered autonomous vehicles engineered to operate continuously in environments maintained at temperatures as low as minus 25 degrees Celsius, employing heated battery enclosures and specialized lubricants to prevent mechanical failure. Their primary purpose is to eliminate human exposure to extreme cold while maintaining precise inventory tracking in frozen supply chains. Towing AGVs dominate new frozen warehouse deployments due to lower capital intensity and simpler path programming in narrow aisle layouts. Vision-guided technology is displacing magnetic-guided systems as the fastest-growing navigation category, driven by reduced infrastructure cost and dynamic route optimization in facilities with frequent layout changes. Unit load AGVs occupy the premium margin tier where pharmaceutical and biotechnology end users require validated temperature monitoring at the pallet level.
The FDA enforces strict temperature documentation through 21 CFR Part 211, compelling pharmaceutical cold storage operators to deploy AGVs with embedded data-logging capabilities that create immutable chain-of-custody records. EMA's Good Distribution Practice guidelines and the EU F-Gas Regulation together shape equipment specifications, restricting certain refrigerants while mandating energy-efficient automation in new cold storage construction. Stakeholders must monitor evolving interoperability standards between warehouse management systems and AGV fleet controllers, as fragmented software protocols risk locking operators into single-vendor architectures that limit future technology migration.
Market Dynamics
Vision-guided navigation systems are fragmenting the installed base of magnetic-tape AGV fleets as frozen warehouse operators prioritize infrastructure flexibility over path rigidity.
Growth Catalysts
- FDA 21 CFR Part 211:Pharmaceutical cold storage operators must deploy AGVs with embedded data-logging to create immutable chain-of-custody records for temperature-sensitive products.
- Frozen food retail consolidation:German supermarket chains are retrofitting legacy warehouses with autonomous towing fleets to eliminate human exposure in minus 25 degree Celsius environments.
- Lithium iron phosphate batteries:Heated battery enclosures now sustain continuous operation in sub-zero facilities without thermal runaway risk, enabling 24/7 automation.
Market Restraints
- Specialized lubricant supply:Synthetic low-temperature greases concentrate among three European chemical suppliers, creating input cost volatility for AGV manufacturers.
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon refrigerants complicate thermal management system designs for battery-heated AGV architectures.
- Magnetic tape infrastructure:Existing tape-guided installations in Asian frozen warehouses represent sunk capital that slows navigation technology migration.
Strategic Opportunities
- Indian cold chain modernization:FSSAI temperature-integrity mandates for vaccine distribution create first-mover advantage for AGV vendors offering validated pallet-level monitoring.
- Vision-LiDAR fusion:Convergence of camera-based navigation with 3D spatial mapping enables dynamic obstacle avoidance in facilities with frequent layout reconfiguration.
- Third-party logistics unbundling:Frozen warehouse operators are separating AGV fleet ownership from maintenance contracts, opening recurring revenue channels for service specialists.
Industry Challenges
- Sub-zero mechatronics expertise:AGV manufacturers face acute shortages of engineers experienced in seal design and thermal expansion compensation for minus 25 degree Celsius operation.
- WMS-AGV protocol fragmentation:Non-standard middleware between warehouse management systems and fleet controllers locks operators into single-vendor architectures that complicate future migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Storage AGV Market |
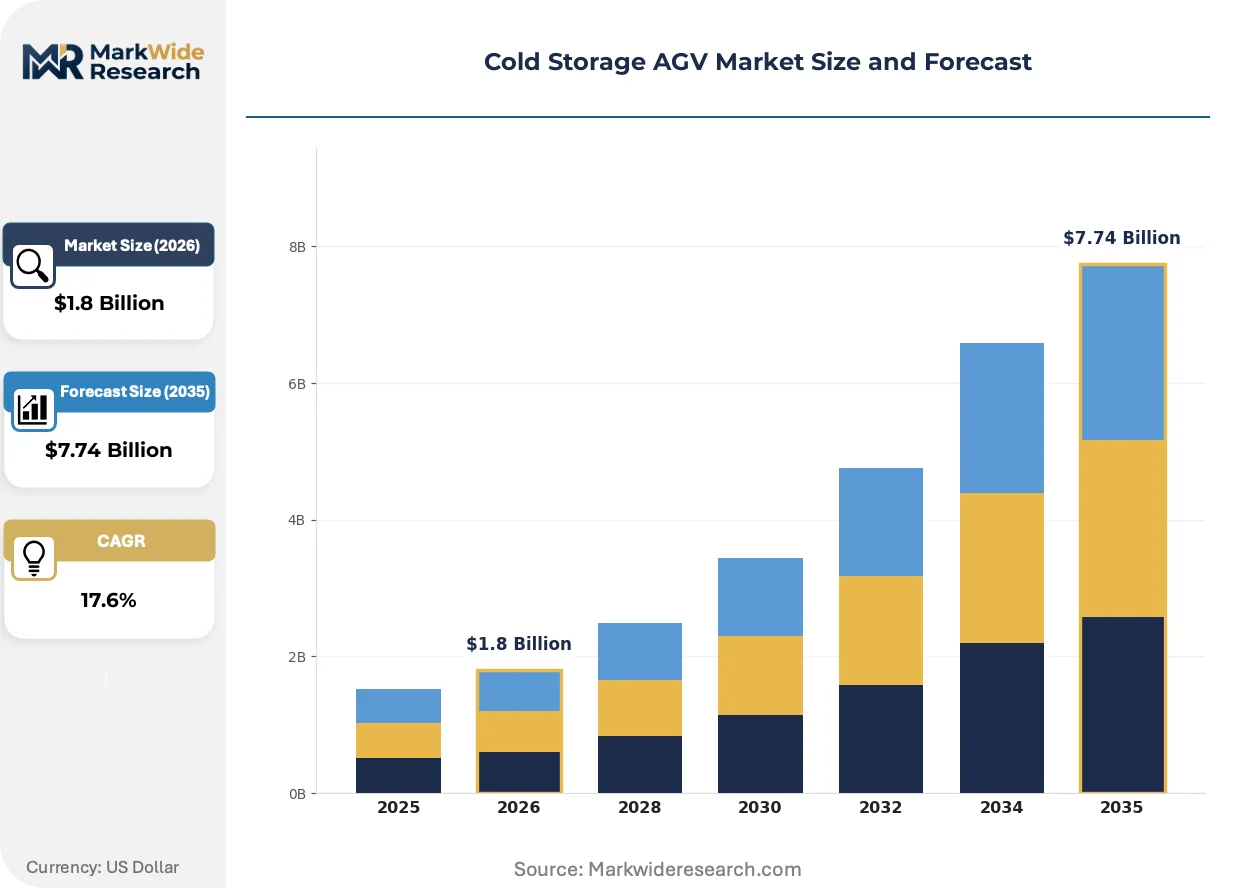
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.74 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Towing AGVs, Unit Load AGVs, Pallet AGVs, Forklift AGVs End User: Food & Beverage, Healthcare, Pharmaceuticals, Retail Technology: Laser Guided, Magnetic Guided, Vision Guided, Autonomous Navigation Installation: New Installations, Upgrades, System Integrations, Custom Solutions |
| Companies Covered | Daifuku, Dematic, Swisslog, JBT, Egemin Automation, Meidensha, Corecon, KUKA, Murata Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Storage AGV Market Evolving Landscape
Navigation technology diversification, regulatory documentation requirements, and procurement model restructuring are converging to reshape competitive positioning in frozen supply chain automation.
Vision-guided navigation is fragmenting the legacy magnetic-tape market by eliminating floor infrastructure requirements. Pharmaceutical distributors in Germany and the Netherlands are adopting camera-based systems at accelerated pace to enable rapid aisle reconfiguration for seasonal SKU shifts. This technology diffusion is compressing margins for tape-based AGV specialists while opening installation services to regional integrators.
REACH chemical restrictions and the EU F-Gas Regulation are forcing battery thermal management redesigns. Industrial consequences include accelerated R&D spending on phase-change materials and solid-state heating elements. Cold storage builders in Denmark and Sweden are responding by specifying AGVs with refrigerant-free battery enclosures in new construction tenders.
Outcome-based fleet performance contracts are displacing traditional equipment purchase models in third-party logistics. Swiss and Austrian frozen warehouse operators now pay per pallet-move rather than capitalizing AGV assets. This shift concentrates vendor selection criteria on uptime guarantees and temperature-validation documentation rather than hardware specifications alone.
Cold Storage AGV Market Segmentation
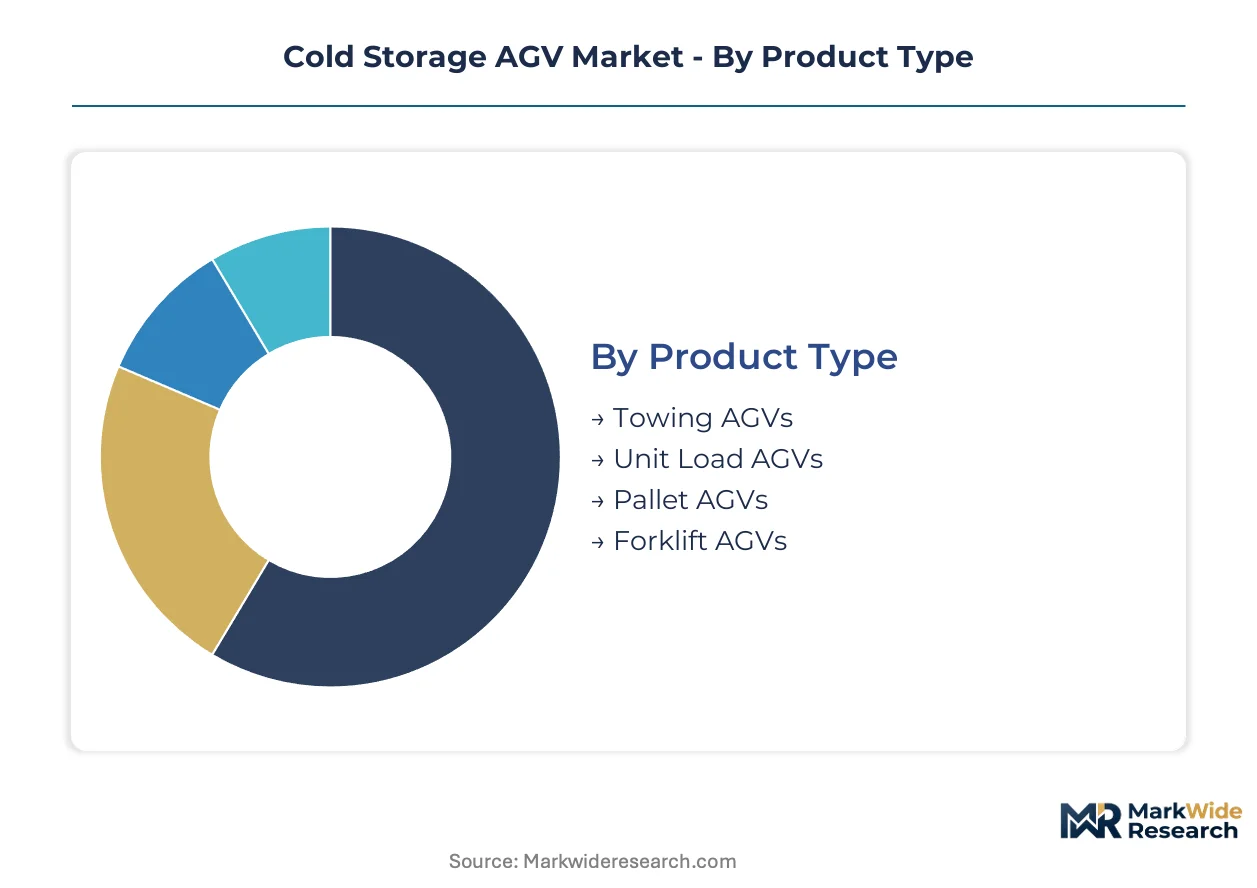
Cold storage AGV purchasing decisions diverge sharply across product architectures and facility maturity levels. Segmentation reveals where capital concentrates versus where upgrade cycles accelerate.
Product Type:
Towing configurations face intensifying substitution pressure from unit load systems in pharmaceutical validation environments.
- Towing AGVs:These vehicles pull multiple carts through narrow frozen warehouse aisles using simple path programming. German food retailers and third-party logistics operators deploy towing fleets to eliminate human exposure in minus 25 degree Celsius environments while minimizing capital outlay per pallet position.
- Unit Load AGVs:Purpose-built for single-pallet transport with integrated weighing and temperature logging. Pharmaceutical and biotechnology end users in the Netherlands specify these for validated chain-of-custody documentation required under EMA guidelines.
- Pallet AGVs:Heavy-duty platforms engineered for standard EUR-pallet dimensions in high-density frozen storage.
- Forklift AGVs:Counterbalance designs replacing manual reach trucks in multi-level racking systems.
Towing AGVs anchor the volume base while unit load AGVs gain share at the steepest rate.
End User:
Capital allocation patterns split between cost-driven food logistics and compliance-driven life sciences.
- Food & Beverage:Frozen warehouse operators prioritize fleet scale over individual unit sophistication. Consolidating supermarket chains in Germany retrofit legacy facilities with autonomous towing fleets to compress labor costs in sub-zero zones.
- Pharmaceuticals:Distribution networks demand AGVs with embedded data-logging for immutable temperature records. FDA 21 CFR Part 211 and EMA Good Distribution Practice mandates force validated hardware selection regardless of price premium.
- Healthcare:Hospital and clinic supply chains require compact AGV footprints for limited cold room dimensions.
- Retail:E-commerce fulfillment centers specify rapid-deployment AGV modules for seasonal demand spikes.
Food and beverage anchors installed capacity while pharmaceuticals expands most quickly.
Technology:
Navigation infrastructure costs now dominate total cost of ownership calculations in retrofit projects.
- Vision Guided:Camera-based systems eliminate floor tape installation and enable dynamic route recalculation. Pharmaceutical distributors in Germany accelerate adoption to support rapid aisle reconfiguration for seasonal SKU shifts without infrastructure rework.
- Magnetic Guided:Legacy tape-based navigation retains installed base in Asian frozen warehouses where sunk capital slows migration timelines.
- Laser Guided:Reflective target systems for high-precision positioning in narrow aisle configurations.
- Autonomous Navigation:SLAM-based mapping without facility infrastructure requirements.
Magnetic guided systems retain the largest installed base while vision guided climbs the fastest.
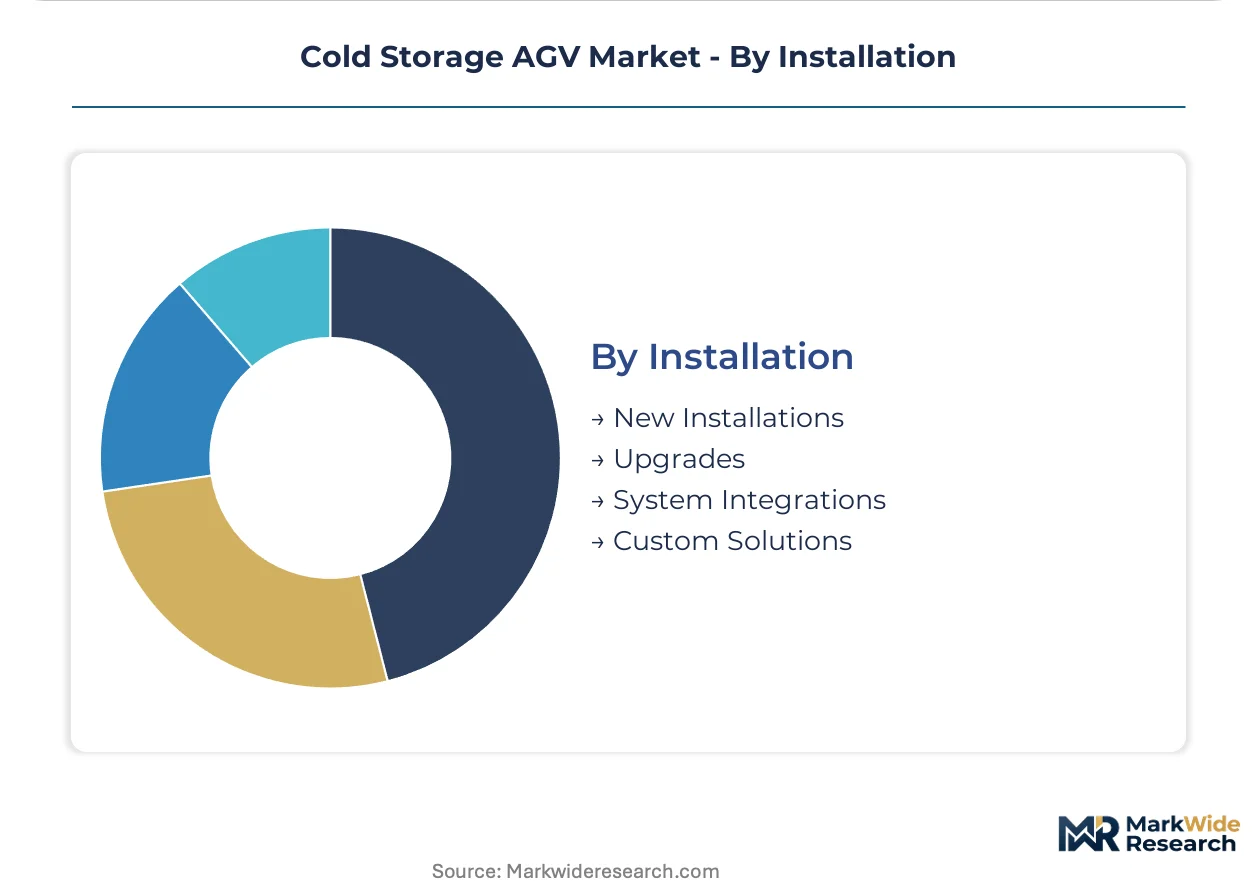
Installation:
Procurement model restructuring separates hardware ownership from operational outcome guarantees.
- New Installations:Greenfield frozen warehouse construction in Denmark and Sweden specifies refrigerant-free battery thermal management to satisfy EU F-Gas Regulation constraints from commissioning date.
- Upgrades:Existing facilities replace magnetic tape infrastructure with vision systems to reduce layout change costs. Swiss and Austrian operators increasingly structure payments per pallet-move rather than capitalizing assets.
- System Integrations:Middleware development connecting AGV fleet controllers to incumbent warehouse management systems.
- Custom Solutions:Engineered variants for non-standard pallet dimensions or extreme temperature ranges.
New installations dominate capital expenditure while upgrades show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distributors and frozen food retailers concentrate purchasing power across five national markets where cold-chain automation mandates intersect with labor cost pressures. Each geography presents distinct regulatory entry points and facility modernization timelines.
Germany
Frozen supermarket chains and third-party logistics operators drive fleet-scale deployments to eliminate human exposure in minus 25 degree Celsius environments. The EU F-Gas Regulation shapes new construction specifications, restricting hydrofluorocarbon refrigerants in battery thermal management systems. The North Rhine-Westphalia logistics corridor hosts concentrated retrofit activity as legacy warehouses adopt vision-guided towing fleets.
United States
FDA 21 CFR Part 211 enforcement compels pharmaceutical cold storage operators to deploy AGVs with embedded data-logging for immutable temperature documentation. The EPA oversees complementary energy efficiency standards for warehouse refrigeration systems. The New Jersey-Pennsylvania pharmaceutical distribution cluster leads validated unit load AGV adoption for chain-of-custody compliance.
Netherlands
Rotterdam-Antwerp port logistics operators prioritize dense shuttle-based architectures that sustain throughput in sub-zero transshipment facilities. EMA Good Distribution Practice guidelines mandate validated hardware selection regardless of price premiums. The Venlo logistics park exemplifies rapid aisle reconfiguration demands that accelerate vision-guided navigation replacement of magnetic tape systems.
India
FSSAI temperature-integrity mandates for vaccine distribution create first-mover openings for vendors offering validated pallet-level monitoring. The national pharmaceutical regulator enforces serialization requirements that converge with cold-chain automation investments. The Hyderabad-Bengaluru pharmaceutical manufacturing belt concentrates demand for unit load systems with integrated temperature logging capabilities.
Denmark
Greenfield frozen warehouse construction specifies refrigerant-free battery thermal management to satisfy EU F-Gas Regulation constraints from commissioning date. REACH chemical restrictions accelerate R&D spending on phase-change materials for heated battery enclosures. The Copenhagen-Malmö cross-border logistics zone hosts outcome-based fleet performance contracts that pay per pallet-move rather than capitalize assets.
Cold Storage AGV Market Competitive Landscape
Player mix skews toward diversified material handling conglomerates with deep integration capabilities across high-bay warehouse systems. The structure concentrates around three to five integrated automation groups that anchor large-scale frozen pharmaceutical and food retail projects. Two strategic archetypes dominate: full-system integrators leveraging warehouse management software orchestration, and component specialists focusing on navigation hardware and sub-zero mechatronics. Competitive moves center on navigation technology licensing partnerships and outcome-based service contract structures that separate fleet ownership from operational guarantees.
Within the integrated-system tier, Daifuku and Dematic anchor distinct approaches to frozen warehouse automation, while Swisslog exemplifies software-layer differentiation. Daifuku represents the high-bay warehouse integration archetype with established presence across Asian pharmaceutical projects. Dematic occupies a position emphasizing dense shuttle-based architectures for sub-zero throughput environments. Swisslog sits within the fleet orchestration specialization, controlling multi-temperature-zone AGV deployments from unified platforms.
| Leading Market Players |
|---|
| Daifuku |
| Dematic |
| Swisslog |
| JBT |
| Egemin Automation |
| Meidensha |
| Corecon |
| KUKA |
| Murata Machinery |
| Others |
Value Network & Pricing Analysis
Outcome-based fleet performance contracts lock in multi-year supply access for frozen warehouse operators while anchoring price visibility to pallet-move volumes rather than equipment depreciation schedules. German and Swiss third-party logistics providers now structure these arrangements to insulate against lithium iron phosphate battery cost volatility while securing priority maintenance response times.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate AGV procurement for pharmaceutical cold storage operators. Three-tier pricing structure across premium validated units, standard vision-guided systems, and economy magnetic-tape retrofits reflects certification grade and temperature-logging sophistication. Cost compression in the economy tier is intensifying because Asian manufacturers are flooding refurbished magnetic fleets into secondary markets. Food and beverage distributors exhibit highest price sensitivity, while pharmaceutical operators prioritize validated documentation over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision mechatronics production for sub-zero AGV components, while China dominates lithium iron phosphate cell fabrication. Heated battery enclosures draw from synthetic lubricant feedstocks concentrated among three European chemical suppliers, creating single-source vulnerability for thermal management systems. Distribution runs through regional system integrators who bundle hardware with WMS middleware deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet maintenance and software orchestration layers are expanding faster than hardware sales as outcome-based contracts separate ownership from operational guarantees. This service-attach dynamic rewards vendors who can embed temperature-validation documentation into recurring revenue streams.
For Market Incumbents: Compound defensive positioning by deepening backward integration into heated battery enclosure manufacturing and securing exclusive synthetic lubricant offtake agreements with European chemical suppliers. Vision-LiDAR fusion navigation threatens legacy magnetic-tape installed bases, demanding accelerated R&D spend on SLAM-based systems to preempt regional integrator encroachment. For New Entrants and Emerging Players: Anchor in India's FSSAI-mandated vaccine cold chain modernization, where validated pallet-level monitoring creates first-mover openings absent entrenched competitor relationships. Target the Hyderabad-Bengaluru pharmaceutical belt with unit load AGVs featuring embedded data-logging as the beachhead application, then expand into frozen food logistics through regional system integrator partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward navigation software specialists with proven WMS-AGV protocol translation capabilities, as middleware fragmentation creates persistent vendor lock-in premiums. The five-to-ten year viability window favors acquisition targets with established pharmaceutical validation credentials rather than hardware-only manufacturers. Watch for FDA enforcement actions on 21 CFR Part 211 temperature documentation as the inflection signal accelerating replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Navigation Technology Licensing Partnership | Vision-guided system patents enable rapid market entry without magnetic-tape infrastructure legacy. |
| Outcome-Based Fleet Performance Contract | Swiss operators now pay per pallet-move, concentrating vendor selection on uptime guarantees. |
| Refrigerant-Free Battery Thermal Management | Danish greenfield construction mandates satisfy EU F-Gas Regulation from commissioning date. |
| WMS-AGV Middleware Development | Protocol translation layers lock operators into single-vendor architectures that limit migration. |
| Pharmaceutical Validation Credential Investment | FDA 21 CFR Part 211 compliance creates immutable chain-of-custody documentation premiums. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cold storage facility directors, AGV fleet managers, pharmaceutical distribution executives, and warehouse management system integrators; and secondary validation against EU F-Gas Regulation filings, FDA 21 CFR Part 211 guidance documents, customs trade data for lithium iron phosphate cells, and SEC disclosures from material handling conglomerates. Bottom-up unit economics triangulated against top-down market sizing across navigation technology, product architecture, and end-use verticals.
Across the analysis window, the forecasting framework modeled product type segmentation by towing versus unit load configurations, technology adoption curves for vision-guided versus magnetic-guided navigation, and regional regulatory cluster impacts on procurement timing. CAGRs derived from installed base replacement cycles in Asian frozen warehouses converged with greenfield construction pipelines in Northern Europe. Industry-specific inputs included pharmaceutical serialization mandate enforcement calendars and lithium battery thermal management R&D trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EMA temperature-integrity enforcement, stable lithium carbonate pricing, and gradual magnetic-tape fleet retirement; material deviation in regulatory stringency or battery chemistry substitution would warrant model refresh. Recalibration cycles align with material shifts in cold-chain automation mandates and navigation technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
UV Curing System Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
United States Human Machine Interface Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Connected Worker Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Utility Automation Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Latin America Laboratory Automation Market