
 Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market | 2026-2036
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market Outlook
CE marking under the EU MDR is rotating the competitive landscape for Asia-Pacific manufacturers seeking export legitimacy. Medtronic PLC leverages its Galway-to-Singapore manufacturing corridor to sustain dual-hemisphere compliance. Nihon Kohden Corporation anchors its domestic position through JIS-certified production lines in Tokyo.
Cardiac arrhythmia monitoring devices are electrophysiological instruments that detect, record, and transmit irregular heart rhythms through surface electrodes or implanted sensors, typically sampling at 250–1000 Hz with noise filtering below 0.05 Hz. These systems serve to reduce stroke risk through early atrial fibrillation detection and guide anticoagulation therapy decisions. Mobile Cardiac Telemetry represents the fastest-expanding product category as reimbursement frameworks in Australia and South Korea expand ambulatory coverage. Wireless Monitoring technology commands premium positioning where hospital capital budgets prioritize cable-free telemetry wards.
PMDA in Japan, TGA in Australia, and CDSCO in India enforce divergent clinical evidence requirements that fragment product registration timelines across the region. Australia's TGA alignment with EU MDR streamlines pathway access for CE-marked devices, while India's CDSCO mandates local bridging studies that extend market entry by twelve to eighteen months. Stakeholders must calibrate regulatory sequencing to capture reimbursement windows as national health technology assessment bodies in South Korea and Thailand revise cardiac monitoring fee schedules.
Market Dynamics
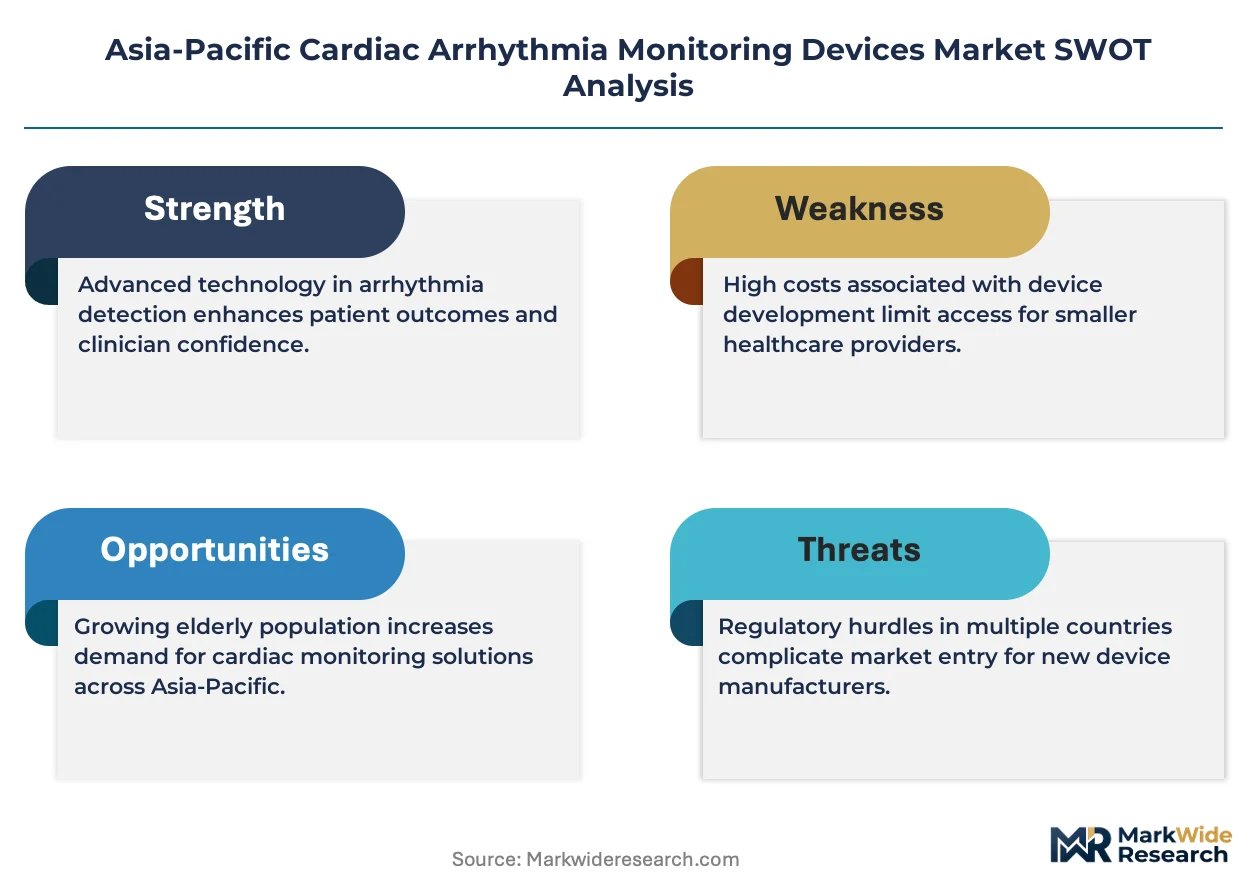
Hospital consolidation across Southeast Asia is compressing procurement timelines and favoring vendors with integrated telemetry-to-cloud platforms. Tier-1 metropolitan networks in India and Thailand now mandate single-source accountability for remote cardiac monitoring infrastructure.
Growth Catalysts
- Japan's PMDA streamlining:Digital health device approval pathways now process cardiac telemetry submissions through a dedicated review track, accelerating market entry for algorithm-enabled wearables.
- Ambulatory reimbursement expansion:Australia's TGA-aligned coverage codes for Mobile Cardiac Telemetry extend Medicare benefits to 72-hour continuous monitoring, pulling demand from inpatient telemetry wards.
- Stroke prevention protocols:South Korea's national health technology assessment body embeds atrial fibrillation screening into hypertension management programs, institutionalizing long-term monitoring subscriptions.
Market Restraints
- Bridging study mandates:India's CDSCO requires local clinical validation for algorithm-trained devices, extending registration timelines by twelve to eighteen months beyond CE-marked equivalents.
- Electrode supply concentration:Hydrogel electrode manufacturing clusters in Guangdong province create single-source dependency for disposable consumables across the region.
- Signal fidelity limitations:Motion artifact rejection below 0.05 Hz remains technically constrained during high-activity ambulatory use, limiting athletic and occupational monitoring applications.
Strategic Opportunities
- Tier-2 hospital penetration in Vietnam:Provincial cardiac centers lack capital budgets for wireless telemetry infrastructure, creating lease-model openings for refurbished cable-based systems.
- AI-ECG convergence:Deep learning classification of arrhythmia patterns trained on Asian patient cohorts enables differentiated diagnostic claims against Western-calibrated algorithms.
- Direct-to-clinic distribution:Bypassing traditional device distributors through manufacturer-owned service engineers captures margin and accelerates technical support response in Indonesia's archipelago geography.
Industry Challenges
- Electrophysiology technician scarcity:Interpretation of ambulatory ECG recordings requires specialized training that outpaces supply in Malaysia and the Philippines.
- Legacy system integration:Hospital information systems in Australia's public networks run on decade-old HL7 standards that resist seamless cloud-telemetry data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market |
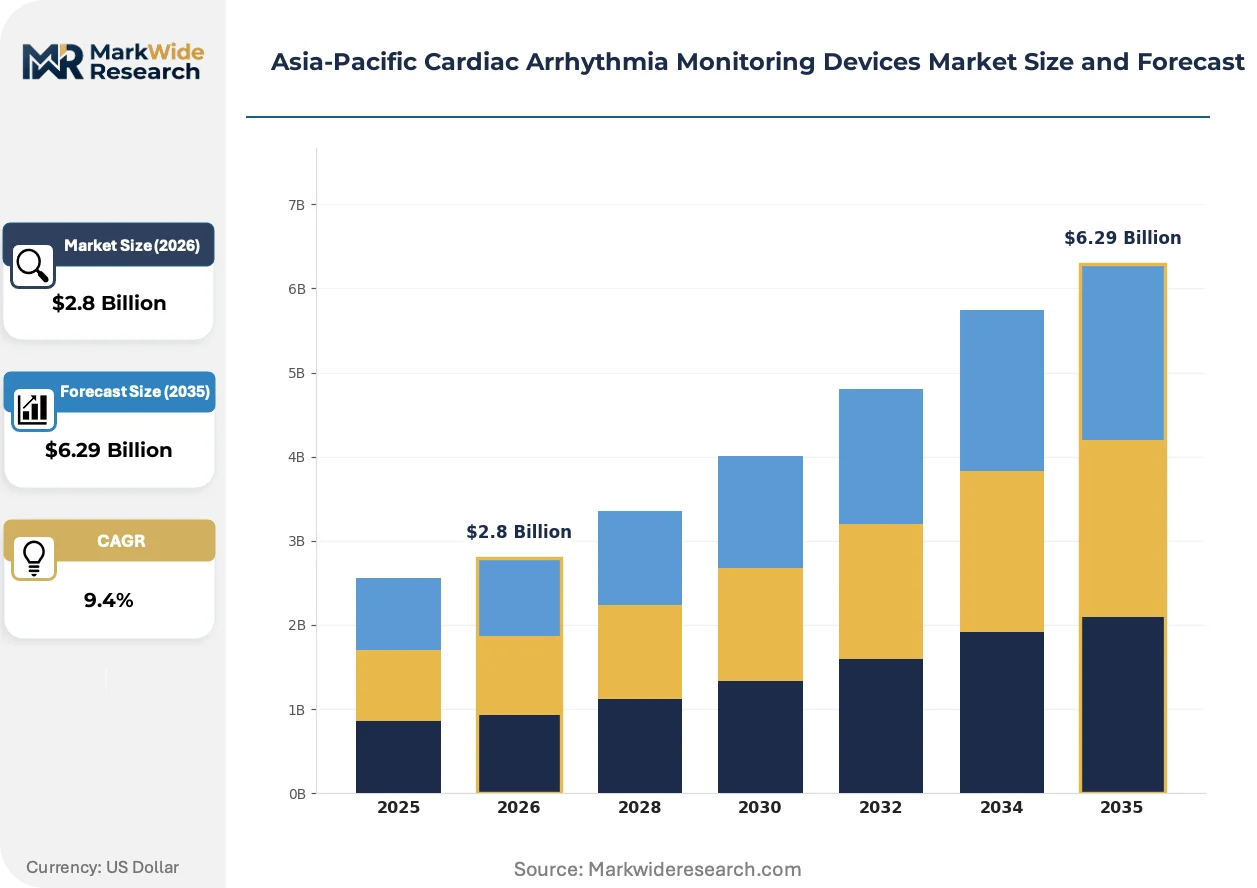
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Event Monitors, Implantable Loop Recorders, Mobile Cardiac Telemetry End User: Hospitals, Clinics, Homecare, Diagnostic Centers Technology: Electrocardiogram, Wireless Monitoring, Telehealth Solutions, Cloud-Based Systems Application: Heart Rhythm Disorders, Patient Monitoring, Emergency Response, Research & Development |
| Companies Covered | Abbott Laboratories, Biotronik, Medtronic PLC, GE Healthcare, Koninklijke Philips NV, Boston Scientific Corporation, iRhythm Technologies, Nihon Kohden Corporation, AliveCor, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market Strategic Shifts
Patch-based single-lead monitors are compressing form factors and extending wear duration, redefining patient compliance benchmarks across ambulatory cardiac monitoring. Three developments are restructuring competitive positioning.
Photoplethysmography-enhanced wearables are displacing traditional Holter monitors for initial arrhythmia screening in South Korean primary care networks. Seoul's metropolitan health screening centers now deploy ring-form factors for 14-day continuous monitoring, compressing specialist referral volumes and redirecting diagnostic workflow toward algorithm-triaged escalation.
Australia's TGA alignment with EU MDR technical documentation requirements eliminates redundant conformity assessments for CE-marked cardiac telemetry devices. Singaporean manufacturers leverage this mutual recognition to register products simultaneously across both jurisdictions, while Indian exporters face parallel CDSCO bridging studies that fragment launch sequencing.
Subscription-based monitoring services are unbundling hardware ownership from diagnostic interpretation in Japan's congestive heart failure management programs. Tokyo's cardiology clinics now lease telemetry infrastructure with per-patient-per-month analytics fees, displacing capital-intensive device purchases that dominated procurement through 2023.
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market Segmentation
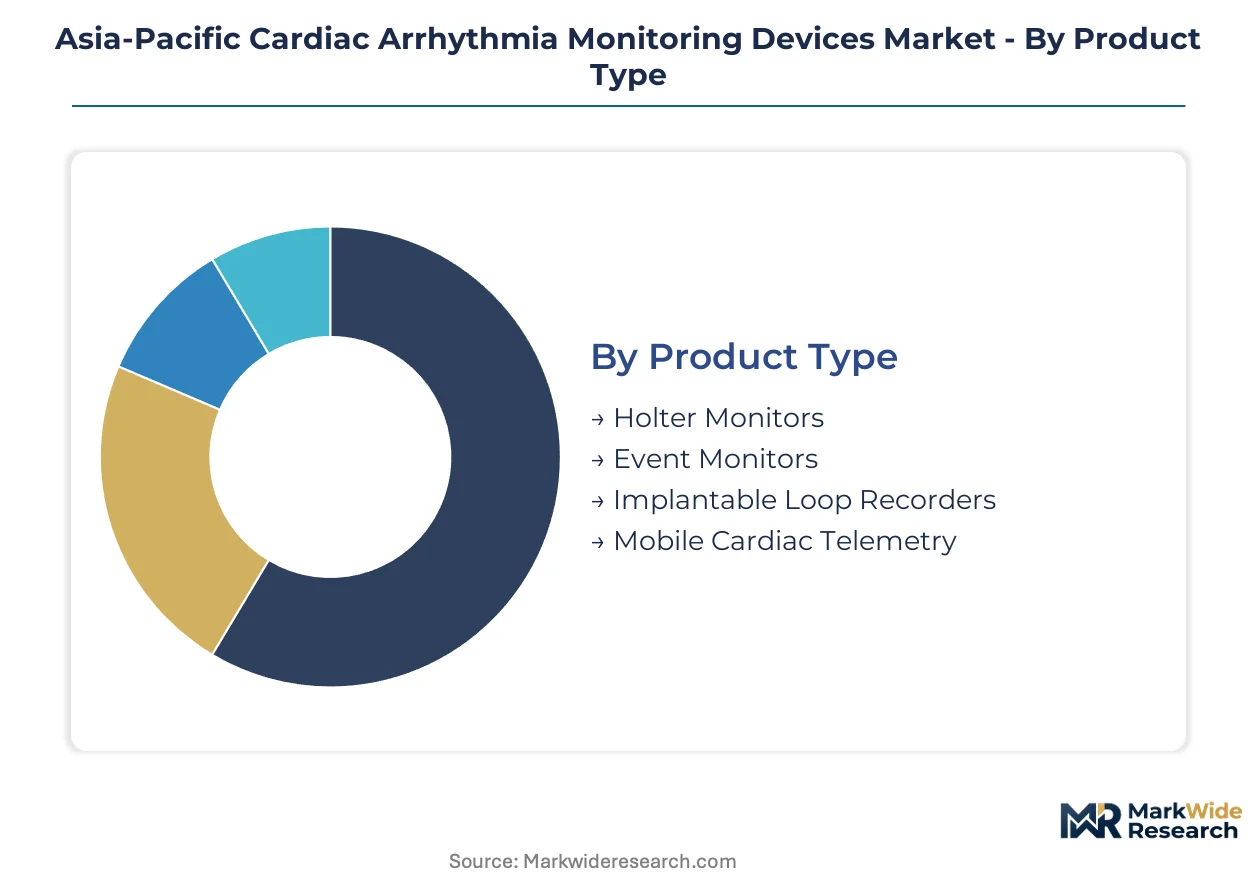
Segmentation in the Asia-Pacific cardiac arrhythmia monitoring devices market reveals divergent regulatory pathways and procurement patterns across product categories. Each dimension carries distinct geographic concentration profiles that shape vendor strategy and market entry sequencing.
Product Type:
Domestic production of Holter and event monitors clusters in Japan and South Korea for regional consumption, while mobile cardiac telemetry systems flow primarily from Singaporean and Australian exporters seeking CE-marked legitimacy in Europe.
- Holter Monitors:Multi-channel ambulatory ECG recorders sample at 250–1000 Hz with solid-state memory storage for 24–48 hour monitoring protocols. Demand concentrates in India's tier-1 metropolitan hospital networks where cardiology departments prioritize established diagnostic workflows over novel form factors.
- Mobile Cardiac Telemetry:Real-time arrhythmia detection systems transmit via cellular networks to centralized monitoring centers with algorithm-enabled event triage. Australia's TGA-aligned Medicare coverage for 72-hour continuous monitoring pulls procurement away from traditional inpatient telemetry wards in Sydney and Melbourne health systems.
- Event Monitors:Patient-activated or auto-triggered devices capture symptomatic episodes through external electrodes for intermittent monitoring needs.
- Implantable Loop Recorders:Subcutaneous devices with multi-year battery life enable long-term monitoring of cryptogenic stroke patients.
Holter monitors command the established base. The steepest expansion runs through mobile cardiac telemetry.
End User:
Procurement authority concentrates differently across customer types, with hospital networks exercising capital budget control while homecare channels respond to reimbursement rate changes.
- Hospitals:Integrated health systems across Southeast Asia mandate single-source accountability for telemetry-to-cloud infrastructure. Tier-1 metropolitan networks in Thailand and Indonesia compress vendor selection timelines through consolidated procurement committees.
- Homecare:Remote monitoring subscriptions bypass capital-intensive device purchases through per-patient-per-month analytics fees. Japan's congestive heart failure management programs in Tokyo cardiology clinics institutionalize this lease-model for telemetry infrastructure.
- Clinics:Primary care networks in South Korea deploy photoplethysmography-enhanced wearables for initial arrhythmia screening.
- Diagnostic Centers:Independent facilities in Malaysia and the Philippines face electrophysiology technician scarcity that constrains ambulatory ECG interpretation capacity.
Hospitals anchor procurement volume. Homecare channels are expanding most quickly as reimbursement frameworks mature.
Technology:
Technology selection maps to infrastructure maturity, with wireless and cloud systems requiring hospital information system upgrades that lag in Australia's public networks.
- Wireless Monitoring:Cable-free telemetry wards command premium positioning where capital budgets prioritize patient mobility and infection control. Signal fidelity limitations below 0.05 Hz during high-activity use constrain athletic and occupational monitoring applications.
- Cloud-Based Systems:Centralized data architectures enable algorithm-triaged escalation workflows in Seoul's metropolitan health screening centers. Legacy HL7 standard resistance in decade-old hospital information systems fragments seamless data ingestion in Australian public networks.
- Electrocardiogram:Surface electrode-based systems remain the diagnostic reference standard for arrhythmia classification.
- Telehealth Solutions:Remote consultation platforms integrate cardiac monitoring data for specialist access in Indonesia's archipelago geography.
Electrocardiogram technology holds the installed base. Cloud-based systems are gaining share fastest as platform consolidation accelerates.
Application:
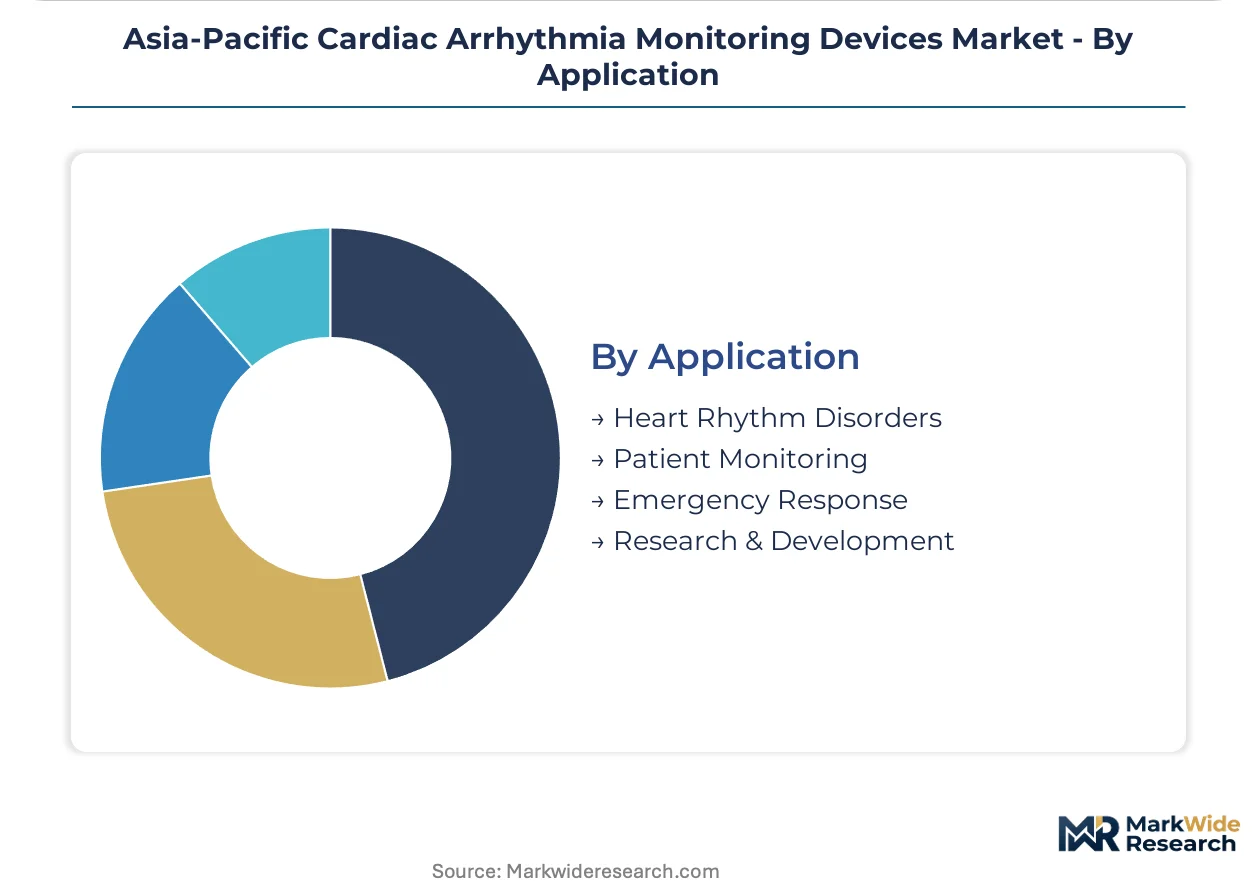
Application segmentation reflects clinical workflow integration depth, with patient monitoring and emergency response requiring distinct regulatory validation pathways across PMDA, TGA, and CDSCO jurisdictions.
- Patient Monitoring:Continuous or intermittent surveillance protocols guide anticoagulation therapy decisions through early atrial fibrillation detection. South Korea's national health technology assessment body embeds screening into hypertension management programs, institutionalizing long-term monitoring subscriptions.
- Heart Rhythm Disorders:Diagnostic workflows for atrial fibrillation, ventricular tachycardia, and bradyarrhythmia drive specialist referral volumes. AI-ECG convergence with deep learning classification trained on Asian patient cohorts enables differentiated claims against Western-calibrated algorithms.
- Emergency Response:Acute event detection systems require real-time alert infrastructure and response protocol integration.
- Research & Development:Clinical trial endpoints and algorithm training datasets support regulatory submission packages for novel device categories.
Heart rhythm disorder applications command the clinical focus. Patient monitoring shows the steepest expansion trajectory as preventive protocols institutionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA streamlining of digital health pathways accelerates regional regulatory convergence. Australia's TGA alignment with EU MDR creates dual-market access opportunities. India's CDSCO bridging study mandates fragment entry timelines for algorithm-enabled devices.
Japan
Tokyo's metropolitan cardiology clinics drive demand for subscription-based telemetry leasing models. PMDA's dedicated review track for algorithm-enabled wearables compresses approval timelines for domestic and foreign manufacturers. Osaka-based production facilities anchor JIS-certified manufacturing for regional export.
Australia
Sydney and Melbourne health systems redirect procurement from inpatient telemetry wards toward ambulatory mobile cardiac telemetry systems. TGA alignment with EU MDR technical documentation eliminates redundant conformity assessments for CE-marked devices. Queensland's regional cardiac networks lag in cloud-telemetry infrastructure adoption.
India
Maharashtra and Karnataka's tier-1 metropolitan hospital networks concentrate demand for established Holter monitor diagnostic workflows. CDSCO mandates local clinical validation for algorithm-trained devices, extending registration timelines beyond CE-marked equivalents. Delhi-NCR procurement committees consolidate vendor selection for remote monitoring infrastructure.
South Korea
Seoul's metropolitan health screening centers deploy photoplethysmography-enhanced wearables for initial arrhythmia screening protocols. The national health technology assessment body embeds atrial fibrillation screening into hypertension management programs. Busan-Ulsan medical device manufacturing clusters supply regional consumables demand.
Vietnam
Provincial cardiac centers in tier-2 cities lack capital budgets for wireless telemetry infrastructure. Lease-model openings emerge for refurbished cable-based systems in Ho Chi Minh City and Hanoi satellite facilities. Local distribution networks remain fragmented across archipelago geography.
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market Competitive Environment
Listed leaders compete with private specialists across integrated telemetry-to-cloud platforms and algorithm-enabled diagnostic workflows. The vendor base stratifies into three tiers: multinational conglomerates with dual-hemisphere compliance infrastructure, regional specialists with JIS or TGA-certified production lines, and emerging algorithm developers seeking bridging study completion. Strategic moves concentrate on M&A for AI-ECG capabilities and capacity expansion into Vietnam's tier-2 hospital networks.
Among diversified medical technology conglomerates, Medtronic PLC and Abbott Laboratories exemplify scale-driven archetypes with Galway-to-Singapore manufacturing corridors sustaining dual-hemisphere compliance. Nihon Kohden Corporation anchors the regional specialist tier through Tokyo-based JIS-certified production. These three entities occupy positions across the premium-mid-economy pricing spectrum, with algorithm-enabled wearables representing the fastest-growing capability vector.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Biotronik |
| Medtronic PLC |
| GE Healthcare |
| Koninklijke Philips NV |
| Boston Scientific Corporation |
| iRhythm Technologies |
| Nihon Kohden Corporation |
| AliveCor |
| Others |
Value Chain & Pricing Dynamics
Patch-based single-lead monitors displacing traditional Holter systems simultaneously concentrates component sourcing in Guangdong province and compresses pricing premiums for cable-based telemetry, as disposable electrode costs now dominate lifetime ownership economics across Southeast Asian procurement committees.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with PMDA-approved devices in Japan commanding substantial premiums over CDSCO-registered equivalents in India. Pricing stratifies across JIS-certified, CE-marked, and locally validated tiers, with subscription-based SaaS models for cloud telemetry displacing capital-intensive purchases in Tokyo's cardiology clinics. Cost compression in refurbished cable-based systems intensifies as tier-2 Vietnamese hospitals prioritize lease models over wireless infrastructure. Government hospital networks in Thailand exhibit highest price sensitivity, while private metropolitan chains in South Korea prioritize algorithm performance over unit cost.
Supply Chain Analysis
Guangdong province hydrogel electrode manufacturing clusters create single-source dependency for disposable consumables across the region. Component sourcing draws from Japanese sensor fabs, South Korean battery cell producers, and Taiwanese semiconductor packaging facilities. Tariff exposure on medical-grade polymers imported from the EU fragments margin structures for Australian manufacturers. Distribution runs through manufacturer-owned service engineers in Indonesia's archipelago geography, bypassing traditional device distributors to capture margin and accelerate technical response.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile cardiac telemetry represents a high-growth disruption justified by Australia's TGA-aligned Medicare expansion for 72-hour continuous ambulatory coverage, which institutionalizes algorithm-enabled wearables and redirects procurement from inpatient wards.
For Market Incumbents: Consolidate telemetry-to-cloud platform capabilities through acquisition of AI-ECG algorithm developers trained on Asian patient cohorts. Defend against photoplethysmography-enhanced wearables displacing Holter monitors in South Korean primary care by embedding deep learning classification into existing installed bases. Prioritize backward integration into hydrogel electrode production to reduce Guangdong supply dependency.
For New Entrants and Emerging Players: Australia's TGA fast-track for CE-marked devices enables simultaneous EU and Asia-Pacific registration without redundant conformity assessments. Target tier-2 provincial cardiac centers in Vietnam with refurbished cable-based lease models, exploiting capital budget constraints that exclude wireless telemetry. Deploy direct-to-clinic distribution with manufacturer-employed service engineers to circumvent fragmented Indonesian distributor networks.
For Investors and Strategic Acquirers: The market sits at a regulatory-convergence phase that favors algorithm-enabled diagnostic platforms with multi-jurisdiction approval pathways. Long-term viability centers on AI-ECG capabilities with differentiated training datasets and subscription revenue models. Watch for CDSCO bridging study completion as the inflection signal for algorithm-trained device market entry timelines in India.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Fast-Track Submission | Japan's dedicated digital health review track compresses approval timelines for algorithm-enabled wearables. |
| CE Marking Pathway | TGA alignment eliminates redundant assessments for simultaneous Australia-EU market entry. |
| Hospital System Partnership | Tier-1 metropolitan networks in Thailand mandate single-source accountability for telemetry infrastructure. |
| Software Companion Development | Algorithm-triaged escalation workflows in Seoul's screening centers require integrated analytics platforms. |
| Reimbursement Strategy | South Korea's HTA body embeds atrial fibrillation screening into hypertension management programs. |
Study Parameters
Operator-level perspectives from biomedical engineers, hospital purchasing committees, GPO contracts managers, and cardiology department heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through PMDA submission databases, TGA approval registers, CDSCO bridging study records, and Medicare coverage determinations. Bottom-up demand modeling from hospital procurement pipelines triangulated against top-down macroeconomic indicators across the Asia-Pacific region.
Sensitivity analysis tested forecast outputs against reimbursement rate volatility, regulatory timeline slippage, and electrode supply disruption scenarios. Segmentation dimensions modeled include product type, end-user channel, technology architecture, and application workflow across the projection horizon. CAGRs derived from fitted growth curves applied to disclosed hospital capital budgets and ambulatory coverage expansion schedules, with algorithm adoption curves and cloud-telemetry penetration rates serving as key forecast inputs.
Decision-makers should treat outputs as directional under stable reimbursement and regulatory convergence assumptions; material deviation in bridging study requirements or Medicare fee schedules would warrant model refresh. Practitioners should keep alternative scenarios live as PMDA-TGA-CDSCO alignment patterns and hydrogel electrode supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wireless Patient Monitoring Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
Mobile Continuous Patient Monitors Market