
 Coronary Pressure Monitors Market | 2026-2036
Coronary Pressure Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Coronary Pressure Monitors Market Analysis
Interventional cardiology fellowship training capacity is rotating toward structural heart and peripheral vascular procedures, creating a talent pipeline that limits cath lab throughput expansion. Medtronic leverages its integrated cardiovascular portfolio to sustain deep relationships with academic medical centers. Philips Healthcare anchors its position through imaging-to-hemodynamics workflow integration. GE Healthcare competes by extending its monitoring hardware into software-enabled decision support.
Coronary pressure monitors measure intracoronary blood flow dynamics using pressure transduction, typically quantifying fractional flow reserve at rest or under hyperemic stress to guide revascularization decisions. Invasive monitors with fiber optic pressure sensor technology dominate the product landscape due to superior signal fidelity during high-frequency cardiac cycles. Wireless monitors represent the fastest-growing technology segment as cath labs seek to reduce cable clutter and streamline sterile field management. Hospitals command the largest end-user share, though ambulatory surgical centers are gaining traction for same-day diagnostic catheterization.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern device commercialization, while the EU MDR has lengthened conformity assessment timelines for manufacturers seeking European market access. Clinical Research application demand fluctuates with NIH and EU Horizon funding cycles for ischemia-driven revascularization trials. Stakeholders must weigh sensor miniaturization roadmaps against evolving reimbursement policies for physiologic lesion assessment.
Market Dynamics
Fiber optic pressure transduction is displacing solid-state sensors in cath lab workflows, forcing manufacturers to recalibrate R&D roadmaps around signal fidelity metrics rather than cost reduction alone.
Growth Catalysts
- Physiologic Lesion Assessment Reimbursement:CMS coverage determinations for fractional flow reserve-guided PCI in the United States accelerate hospital capital equipment procurement cycles for hemodynamic monitoring systems.
- Ambulatory Surgical Center Expansion:Medicare's site-of-service payment differentials for same-day diagnostic catheterization pull device installations toward freestanding ASCs in suburban markets.
- NIH Revascularization Trial Funding:Renewed National Institutes of Health grant cycles for ischemia-driven outcome studies expand the installed base of research-grade coronary pressure monitors at academic medical centers.
Market Restraints
- Single-Source Sensor Supply:Japanese optical component manufacturers control the upstream supply of miniaturized fiber Bragg gratings, exposing assemblers to concentration risk.
- EU MDR Conformity Assessment:Extended notified body review timelines for Class IIa hemodynamic devices delay European market entry by 12-18 months relative to FDA 510(k) pathways.
- Non-Invasive FFR Substitutes:CT-derived fractional flow reserve algorithms from Siemens Healthineers and HeartFlow reduce the addressable volume for invasive diagnostic procedures.
Strategic Opportunities
- Wireless Catheter Integration:Bluetooth Low Energy and proprietary RF protocols eliminate cable clutter, opening same-day discharge protocols at high-throughput ASCs in Texas and Florida.
- India Cath Lab Buildout:The country's PLI scheme for medical device manufacturing incentivizes local assembly of pressure transducers for domestic consumption and regional export.
- Artificial Intelligence Workflow Embedding:Real-time pressure waveform interpretation algorithms reduce operator training burden and expand deployment at community hospitals lacking interventional cardiology fellowship programs.
Industry Challenges
- Interventional Cardiology Fellowship Pipeline:Training program slots for structural heart and peripheral vascular procedures divert talent from coronary intervention, constraining cath lab throughput expansion.
- ISO 13485 Quality System Maintenance:Annual surveillance audits and CAPA documentation requirements consume 15-20% of regulatory affairs bandwidth at mid-tier device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coronary Pressure Monitors Market |
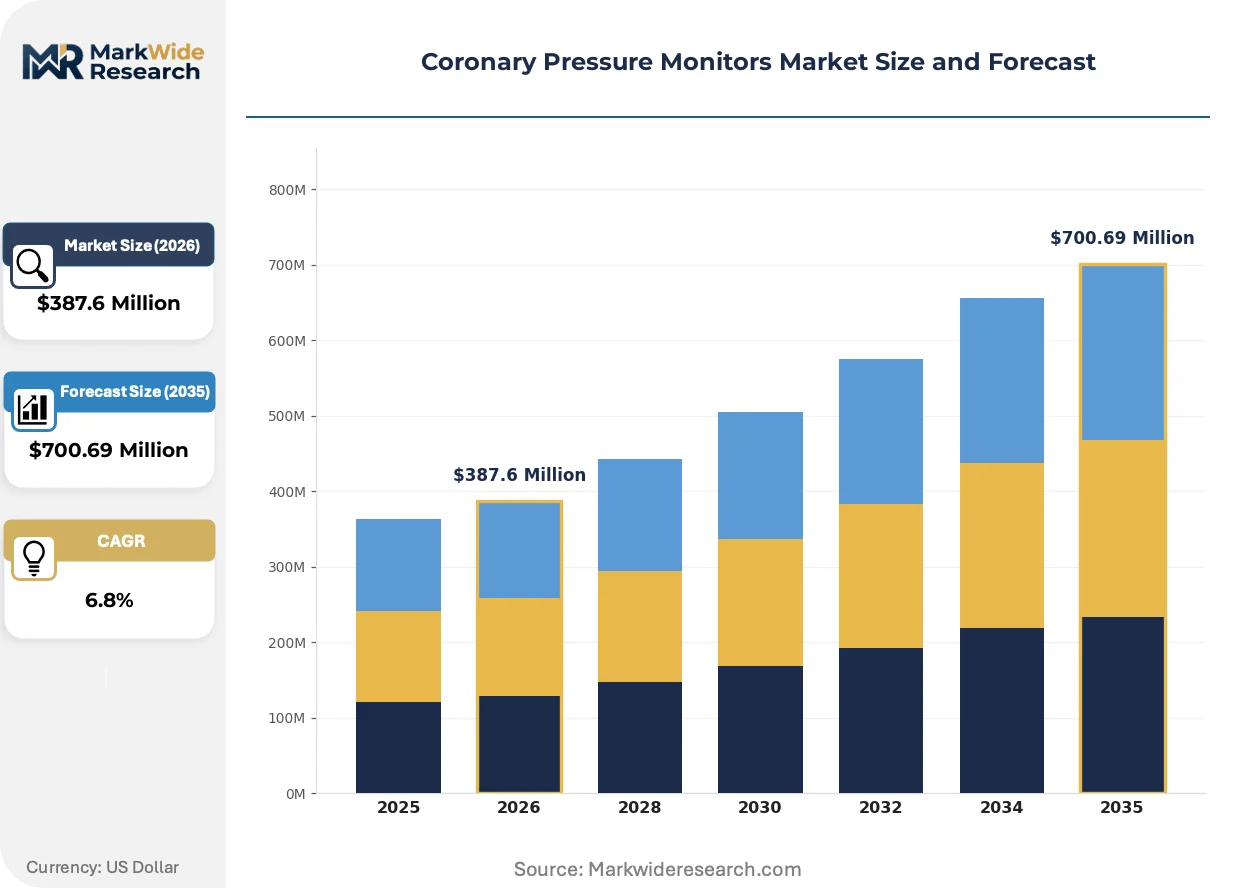
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Monitors, Non-Invasive Monitors, Wireless Monitors, Continuous Pressure Monitors End User: Cardiology Clinics, Hospitals, Ambulatory Surgical Centers, Home Healthcare Providers Technology: Optical Sensors, Electromechanical Sensors, Digital Sensors, Fiber Optic Sensors Application: Cardiac Surgery, Diagnostic Procedures, Monitoring, Clinical Research |
| Companies Covered | Omron Healthcare, SunTech Medical, Philips Healthcare, Welch Allyn, Drägerwerk, GE Healthcare, A&D Medical, American Diagnostics, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coronary Pressure Monitors Market Emerging Trajectories
Disposable pressure sensor catheters are fragmenting the reusable transducer market as sterile field protocols tighten and infection control economics reshape procurement mathematics.
Disposable fiber optic pressure wires deliver sub-millimeter spatial resolution for intracoronary pressure mapping. Academic medical centers in the United States and Germany adopt these single-use devices for complex bifurcation lesion assessment. The shift is fragmenting the aftermarket for reusable pressure transducer maintenance and recalibration services.
The EU Medical Device Regulation's post-market surveillance requirements mandate systematic collection of real-world performance data for Class IIa hemodynamic devices. Manufacturers must establish periodic safety update reports and trend analysis protocols. European notified bodies are extending review timelines for technical documentation submissions, compressing product launch windows relative to FDA-cleared competitors.
Hospital procurement committees now unbundle capital equipment acquisition from multi-year service contracts, forcing device vendors to price monitoring hardware and software maintenance as separate line items. This behavior is most pronounced at US health systems with centralized value analysis committees, where catheterization laboratory directors lose autonomy over vendor selection.
Coronary Pressure Monitors Market Segmentation
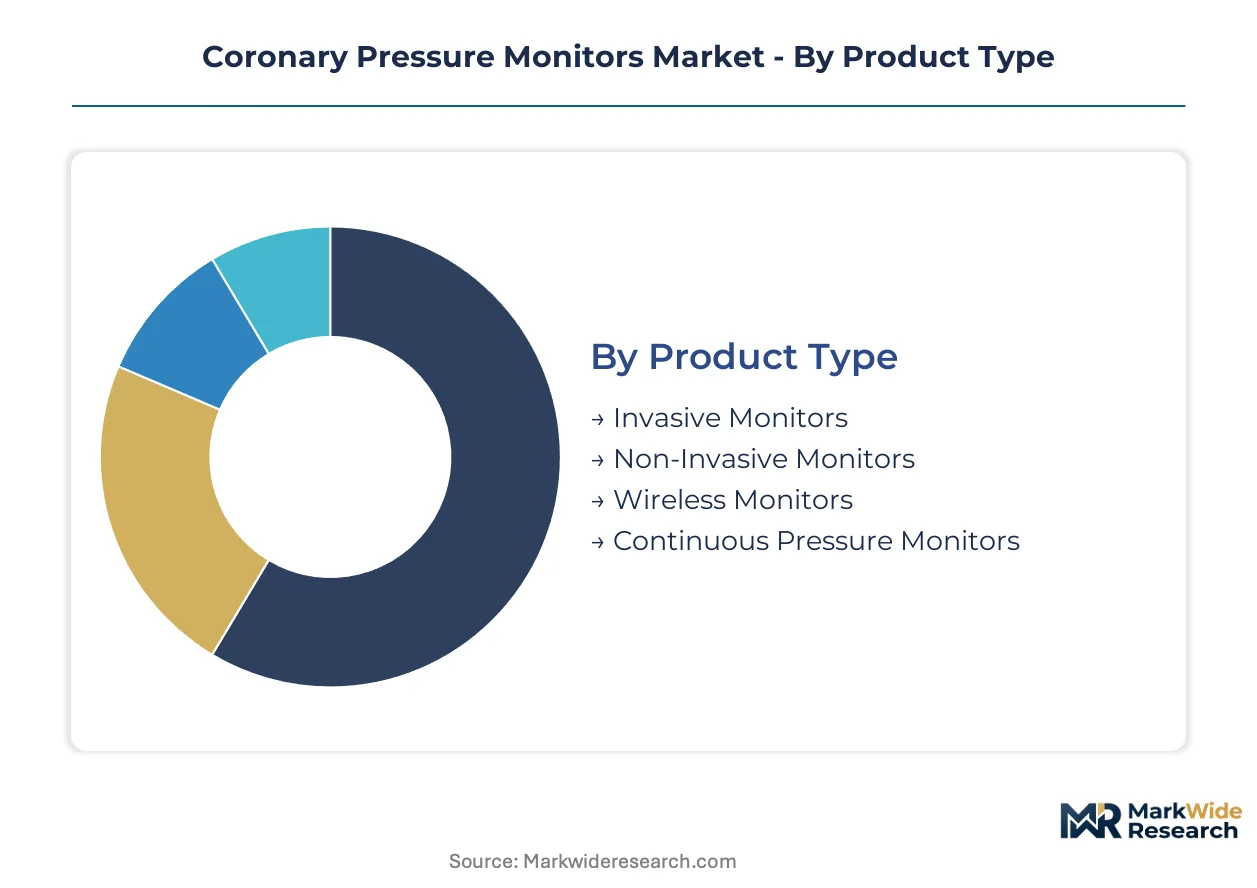
Coronary pressure monitor segmentation reveals how cath lab economics and regulatory pathways fragment procurement decisions across technology tiers. Device vendors must align sensor specifications with reimbursement codes and site-of-service requirements.
Product Type:
Wireless monitors face the most acute substitution pressure from CT-derived FFR algorithms, forcing invasive product lines to defend procedural volume through superior spatial resolution.
- Invasive Monitors:Fiber optic pressure transduction catheters deliver sub-millimeter spatial resolution for intracoronary mapping during PCI guidance. Academic medical centers in the United States and Germany concentrate demand for these devices in complex bifurcation lesion assessment, though CT-FFR growth constrains diagnostic-only procedure expansion.
- Wireless Monitors:Bluetooth Low Energy and proprietary RF protocols eliminate cable clutter from sterile fields. Ambulatory surgical centers in Texas and Florida adopt these systems for same-day discharge protocols, with Medicare site-of-service differentials accelerating installations.
- Non-Invasive Monitors:External pressure monitoring systems for post-procedure surveillance.
- Continuous Pressure Monitors:Extended-duration hemodynamic tracking for ICU settings.
Invasive monitors anchor the volume base while wireless monitors gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital installations from leaner ambulatory configurations.
- Hospitals:Integrated catheterization laboratories with multi-vendor imaging suites require hemodynamic monitoring systems that interface with angiography workstations. US health systems with centralized value analysis committees now unbundle hardware procurement from service contracts, compressing vendor margins.
- Ambulatory Surgical Centers:Freestanding facilities prioritize compact, wireless-enabled systems for same-day diagnostic catheterization. Medicare payment differentials pull device installations toward suburban ASCs in high-growth metropolitan markets.
- Cardiology Clinics:Office-based labs with limited interventional capability.
- Home Healthcare Providers:Remote monitoring configurations for post-acute surveillance.
Hospitals dominate installed base value while ambulatory surgical centers expand footprint most aggressively.
Technology:
Supply concentration in Japanese optical component manufacturing shapes competitive access to premium sensor tiers.
- Fiber Optic Sensors:Miniaturized fiber Bragg grating arrays from Japanese suppliers enable sub-millimeter catheter diameter with signal fidelity across high-frequency cardiac cycles. Device assemblers face concentration risk in upstream sourcing as optical component manufacturers control critical supply.
- Optical Sensors:LED-based transduction for standard diagnostic applications.
- Electromechanical Sensors:Solid-state pressure transduction in legacy system configurations.
- Digital Sensors:Software-enabled waveform processing with embedded decision support algorithms.
Fiber optic sensors command premium positioning while digital sensors climb fastest on AI workflow integration.
Application:
Reimbursement policy divergence separates covered diagnostic procedures from research-funded investigational use.
- Diagnostic Procedures:Fractional flow reserve measurement for ischemia-driven revascularization decisions. CMS coverage determinations for FFR-guided PCI in the United States accelerate hospital capital equipment procurement cycles for hemodynamic monitoring systems.
- Clinical Research:Research-grade monitors for NIH and EU Horizon-funded ischemia outcome trials. Academic medical centers concentrate demand as grant cycles fluctuate, creating lumpy procurement patterns distinct from clinical replacement schedules.
- Cardiac Surgery:Intraoperative hemodynamic management during bypass and valve procedures.
- Monitoring:Post-interventional surveillance for hemodynamic stability assessment.
Diagnostic procedures generate recurring revenue while clinical research applications exhibit the most volatile demand cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply across geographies, with US health systems unbundling service contracts while European institutions navigate extended regulatory timelines and Asian markets prioritize cost-efficient wireless configurations for rapid cath lab expansion.
United States
Medicare site-of-service payment differentials accelerate ambulatory surgical center installations in Texas and Florida, where same-day discharge protocols favor wireless-enabled systems. FDA 510(k) clearance pathways maintain shorter commercialization timelines than European alternatives. Academic medical centers in Boston and Cleveland anchor demand for research-grade fiber optic pressure transducers in complex bifurcation lesion assessment.
Germany
University hospitals in Munich and Heidelberg concentrate demand for high-fidelity invasive monitors in NIH and EU Horizon-funded ischemia outcome trials. EU MDR conformity assessment extends notified body review timelines by 12-18 months relative to FDA pathways. The Baden-Württemberg medical device cluster faces compressed product launch windows as post-market surveillance requirements intensify.
Japan
Domestic optical component manufacturers control upstream supply of miniaturized fiber Bragg gratings, exposing downstream assemblers to concentration risk. PMDA regulatory frameworks align with international standards while maintaining distinct quality system expectations. Tokyo and Osaka metropolitan areas concentrate cath lab infrastructure for aging-population coronary intervention volumes.
India
PLI scheme incentives for medical device manufacturing accelerate local assembly of pressure transducers for domestic consumption and regional export to Southeast Asian markets. CDSCO regulatory harmonization efforts streamline import substitution pathways. Maharashtra and Karnataka states concentrate private hospital cath lab buildout in Mumbai and Bangalore metropolitan corridors.
China
NMPA innovation fast-track pathways compress registration timelines for domestically manufactured hemodynamic monitoring systems. Provincial hospital tier-3 expansion targets drive procurement of integrated imaging-to-hemodynamics workflows. The Yangtze River Delta medical device manufacturing base in Shanghai-Suzhou corridor scales production of electromechanical sensor components for cost-sensitive installations.
Coronary Pressure Monitors Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated imaging-to-hemodynamics portfolios commanding academic medical center relationships while mid-scale sensor manufacturers defend position through optical component sourcing advantages. The competitive terrain stratifies across three archetypes: diversified cardiovascular conglomerates with integrated catheterization laboratory workflows, pure-play hemodynamic monitoring specialists with fiber optic transduction expertise, and emerging wireless technology vendors targeting ambulatory surgical center site-of-service expansion. Dominant competitive moves include strategic partnerships for Bluetooth Low Energy protocol integration and backward integration into fiber Bragg grating manufacturing to secure supply chain positioning.
Within the integrated cardiovascular portfolio tier, Medtronic and Philips Healthcare exemplify divergent strategic positioning. Medtronic anchors relationships through structural heart and coronary intervention device bundling, while Philips Healthcare occupies a position centered on imaging-to-hemodynamics workflow integration. GE Healthcare represents the scale-driven archetype, extending monitoring hardware platforms into software-enabled decision support configurations. Among these three, competitive differentiation hinges on cath lab ecosystem breadth rather than standalone sensor performance metrics.
| Leading Market Players |
|---|
| Omron Healthcare |
| SunTech Medical |
| Philips Healthcare |
| Welch Allyn |
| Drägerwerk |
| GE Healthcare |
| A&D Medical |
| American Diagnostics |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Fiber optic pressure transduction's displacement of solid-state sensors simultaneously concentrates supply geography in Japanese optical component clusters and compresses pricing economics for legacy electromechanical configurations. This substitution dynamic forces device assemblers to absorb premium input costs or surrender margin position at the standard tier.
Pricing Analysis
Long-term offtake agreements for fiber Bragg grating arrays from Japanese suppliers anchor pricing for premium invasive monitors, while spot procurement governs electromechanical sensor tiers. Price differentiation rests on FDA 510(k) certification tier and fiber optic signal fidelity grade. Cost compression in standard-tier monitors intensifies as ASC procurement committees unbundle hardware from service contracts. Community hospitals exhibit highest price sensitivity; academic medical centers least.
Supply Chain Analysis
Inventory lead times for miniaturized fiber optic sensors extend 12-18 weeks due to concentrated Japanese manufacturing. Upstream supply draws from Japan, Germany, and the United States for optical components, sensor housings, and semiconductor substrates. Single-source vulnerability in fiber Bragg grating fabrication exposes assemblers to concentration risk. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards control over fiber optic transduction capabilities, yet qualified optical engineers and PMDA-experienced regulatory specialists remain scarce relative to expansion timelines. This capability gap favors incumbents with captive supplier relationships.
For Market Incumbents: Secure backward integration into fiber Bragg grating manufacturing to neutralize Japanese supplier concentration risk. Anchor hospital system relationships through multi-year hemodynamic monitoring service contracts before ASC unbundling spreads. CT-derived FFR algorithms threaten diagnostic-only procedure volumes; defend through superior spatial resolution in complex lesion assessment. For New Entrants and Emerging Players: Lead with wireless-enabled systems for Texas and Florida ASC same-day discharge protocols, the most penetrable installation segment. India's PLI scheme for medical device manufacturing offers tariff-advantaged assembly for regional Southeast Asian export. Pursue CDSCO regulatory harmonization pathways to accelerate import substitution positioning. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier device manufacturers with ISO 13485 quality systems and established Japanese optical component supplier relationships. Long-term viability hinges on software-enabled decision support integration rather than standalone sensor hardware. Watch NIH revascularization trial funding cycles as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Bragg Grating Backward Integration | Captive supply of miniaturized optical components neutralizes Japanese manufacturer concentration risk. |
| Bluetooth Low Energy Protocol Partnership | Eliminates cable clutter for ASC same-day discharge protocols in high-growth metropolitan markets. |
| FDA 510(k) Parallel Submission Pathway | Maintains 12-18 month commercialization advantage over EU MDR conformity assessment timelines. |
| AI Workflow Embedding Development | Reduces operator training burden for community hospitals lacking interventional cardiology fellowship programs. |
| India PLI Scheme Local Assembly | Tariff-advantaged production for domestic consumption and Southeast Asian regional export. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with interventional cardiologists, cath lab directors, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up installation base modeling triangulated against top-down market sizing.
Across the projection horizon, the analytical framework modeled coronary pressure monitor demand by product type, end-user facility tier, sensor technology, and application. CAGRs derived from procedure volume elasticity to reimbursement policy shifts and cath lab infrastructure expansion patterns. Forecast inputs incorporated NIH grant cycle fluctuations and site-of-service payment differential trajectories.
The analysis sits within stated boundaries; outcomes outside sustained CMS FFR-guided PCI coverage or accelerated CT-FFR algorithm adoption would require recalibration. Forecasts reflect documented assumptions regarding interventional cardiology fellowship pipeline capacity and Japanese optical component supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Global Patient Temperature Monitoring Market